
 Brachytherapy Afterloaders Market | 2026-2036
Brachytherapy Afterloaders Market Size, Share, and Industry Trends Forecast 2026-2036
Brachytherapy Afterloaders Market Analysis
MDR compliance deadlines are recalibrating the cost-of-entry calculus for European afterloader manufacturers. Elekta AB sustains its installed base leadership through dedicated service networks and training infrastructure. Varian Medical Systems leverages its proton therapy ecosystem to cross-sell brachytherapy platforms into integrated cancer centers. Eckert & Ziegler BEBIG anchors its position in European markets through localized manufacturing and regulatory expertise.
Brachytherapy afterloaders are electromechanical devices that position radioactive sources within body cavities or interstitial catheters with submillimeter precision, typically operating iridium-192 or cobalt-60 sources at dose rates from 12 Gy/hour to over 20 Gy/minute for curative or palliative radiation oncology. High Dose Rate systems dominate current revenue pools due to shorter treatment times and outpatient compatibility, while Pulsed Dose Rate technology is gaining traction in gynecological applications where normal tissue sparing drives clinical preference. Remote Afterloading technology leads technology segment margins because it eliminates staff radiation exposure and enables complex stepping-source optimization algorithms.
FDA 510(k) pathways and MDR technical documentation requirements shape product development timelines and market access costs for afterloader manufacturers. The EPA oversees radioactive source disposal protocols, while ISO 13485 certification remains mandatory for supply chain qualification across all major markets. Stakeholders must monitor reimbursement parity between external beam and brachytherapy procedures as value-based oncology contracts reshape capital equipment purchasing authority.
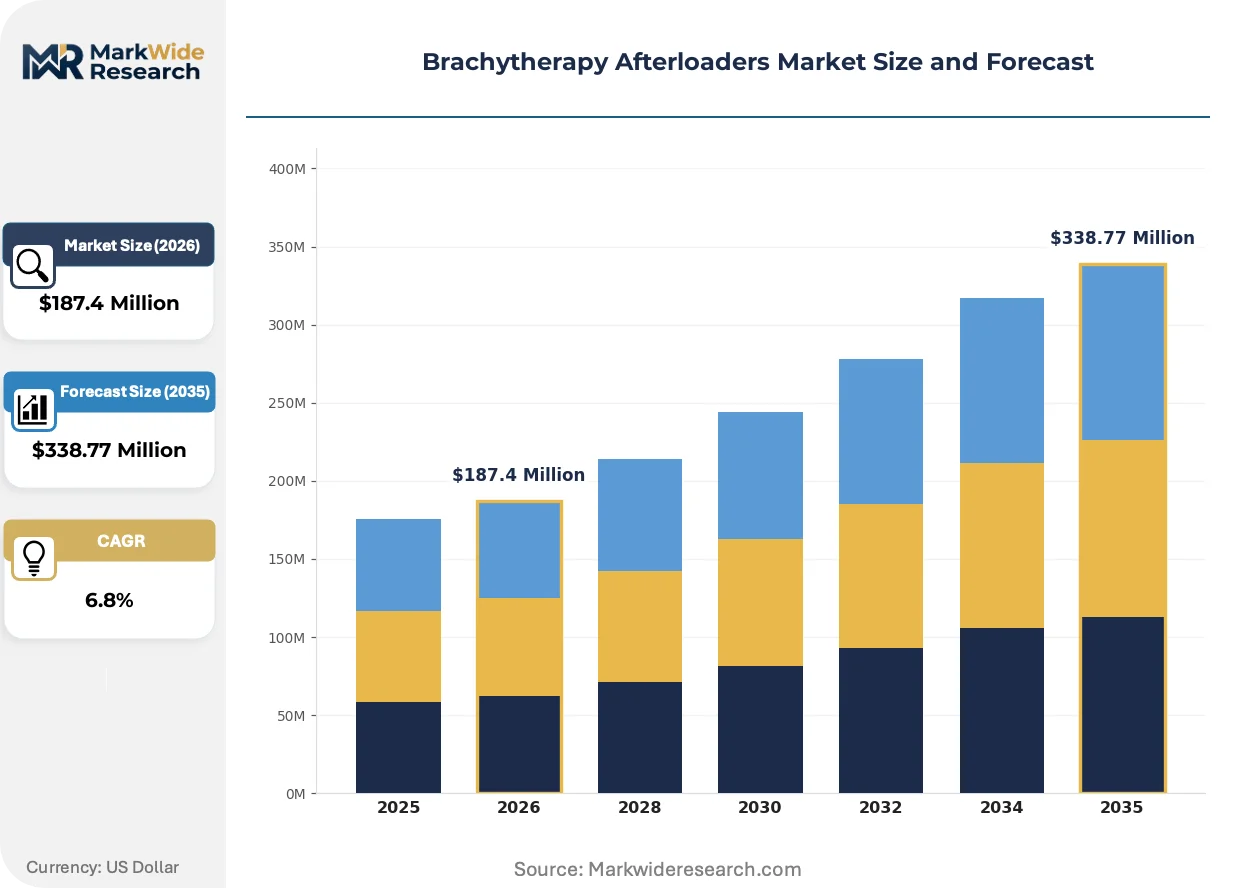
Market Dynamics
Remote afterloading technology is compressing treatment timelines while MDR compliance deadlines in Europe force manufacturers to revalidate legacy platforms, creating simultaneous pull and push forces across the installed base.
Growth Catalysts
- Outpatient migration:Cancer centers in the United States prioritize same-day discharge protocols that favor High Dose Rate systems with sub-30-minute treatment windows.
- MDR technical documentation:European manufacturers accelerating quality management system upgrades ahead of notified body recertification deadlines.
- Iridium-192 source optimization:Stepping-source algorithms enabling dose sculpting around critical structures in gynecological and prostate applications.
Market Restraints
- Source supply concentration:Cobalt-60 production depends on a handful of aging research reactors in Canada and Russia, creating isotope availability risk.
- Capital intensity:Shielded vault construction and regulatory licensing impose six-figure infrastructure costs before equipment procurement.
- External beam substitution:Stereotactic body radiation therapy platforms capture curative cases previously referred for brachytherapy boost sequences.
Strategic Opportunities
- Indian oncology network expansion:Government-funded cancer center construction under the National Cancer Grid creates first-time equipment demand in tier-2 cities.
- Pulsed Dose Rate revival:European gynecological clinics revisit PDR technology for its normal tissue sparing advantages in locally advanced cervical cases.
- AI-enabled treatment planning:Machine learning algorithms automating catheter reconstruction and dwell time optimization reduce physicist staffing burdens.
Industry Challenges
- Medical physicist scarcity:Specialized brachytherapy dosimetry expertise concentrates in academic centers, limiting community hospital program viability.
- Legacy system interoperability:Proprietary data formats from 1990s-era afterloaders resist integration with contemporary oncology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brachytherapy Afterloaders Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Dose Rate, Low Dose Rate, Pulsed Dose Rate, Afterloader Systems End User: Hospitals, Oncology Clinics, Research Institutes, Outpatient Facilities Technology: Remote Afterloading, Manual Afterloading, Digital Afterloading, Integrated Systems Application: Prostate Cancer, Breast Cancer, Gynecological Cancers, Skin Cancer |
| Companies Covered | Varian Medical Systems, Elekta AB, Eckert & Ziegler BEBIG, BEBIG Medical GmbH, Best Medical International, Eckert and Ziegler AG, Theragenics Corporation, IsoRay Medical, iCAD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brachytherapy Afterloaders Market Emerging Trajectories
Digital integration and automation are redefining how radiation oncology departments deploy precision source positioning, with software capabilities now differentiating hardware platforms more than mechanical specifications.
Magnetic resonance imaging-compatible afterloader designs are consolidating clinical preference in prostate and gynecological applications where soft-tissue visualization determines catheter placement accuracy. Academic medical centers in Germany and the Netherlands are replacing cobalt-based units with MR-conditional platforms at accelerated replacement cycles. This consolidation is compressing demand for conventional computed tomography-guided systems outside budget-constrained community settings.
Europe's Medical Device Regulation is extending technical documentation requirements to legacy afterloader platforms previously grandfathered under the Medical Device Directive. Manufacturers must generate clinical evaluation reports and post-market surveillance data for installed base units exceeding two decades of service. French and Italian cancer centers are delaying replacement decisions until notified body pathways clarify, while German university hospitals accelerate MDR-compliant procurement to secure transitional provisions.
Service unbundling is fragmenting traditional afterloader purchasing patterns as physics groups and procurement committees separate hardware acquisition from source logistics and maintenance contracts. Independent service organizations are capturing multi-vendor maintenance portfolios in the United States, displacing manufacturer-captive service agreements. This restructuring is most pronounced in California and Texas, where integrated delivery networks negotiate enterprise-wide service arrangements across heterogeneous equipment fleets.
Brachytherapy Afterloaders Market Segmentation
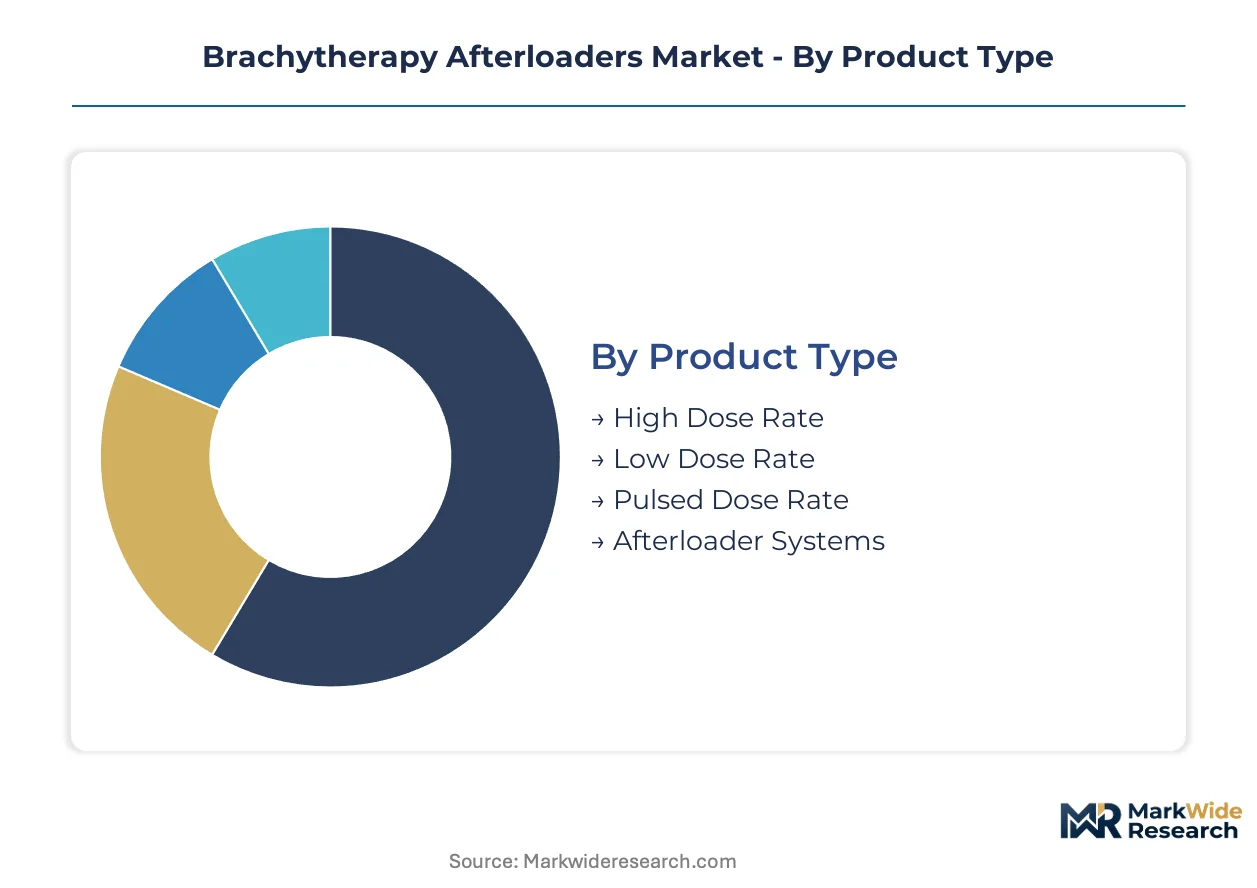
Segmentation reveals how capital deployment, clinical workflow requirements, and regulatory pathways fragment demand across distinct equipment categories. Each dimension captures different purchasing authority structures and reimbursement incentives.
Product Type:
Supply concentration in source manufacturing and shielded vault construction tilts procurement economics toward systems with shorter treatment windows and lower infrastructure burdens.
- High Dose Rate:Systems deploy iridium-192 sources at dose rates exceeding 12 Gy/hour, enabling sub-30-minute outpatient procedures. United States cancer centers prioritize HDR platforms for same-day discharge protocols and maximized linear accelerator utilization.
- Pulsed Dose Rate:Stepping-source technology delivers fractionated radiation pulses mimicking biological dose rates of Low Dose Rate while retaining remote afterloading safety. European gynecological clinics in Germany and the Netherlands favor PDR for locally advanced cervical cases where normal tissue sparing determines clinical outcomes.
- Low Dose Rate:Permanent implant seeds and temporary LDR catheters persist in prostate and breast applications requiring continuous radiation delivery over days.
- Afterloader Systems:Integrated hardware-software platforms encompassing source drives, applicator libraries, and treatment planning workstations anchor manufacturer service revenues.
High Dose Rate absorbs the bulk of installed capacity; Pulsed Dose Rate is expanding most quickly.
End User:
Capital allocation authority concentrates differently across institutional types, with procurement committees, physics groups, and integrated delivery networks exercising overlapping but distinct decision rights.
- Hospitals:Academic medical centers in the United States and university hospitals in Germany anchor replacement demand for MR-conditional platforms. Shielded vault construction and regulatory licensing impose six-figure infrastructure prerequisites that favor hospitals with established radiation oncology programs.
- Oncology Clinics:Specialized cancer centers prioritize outpatient-compatible High Dose Rate systems with compressed treatment timelines. Independent physics groups in California and Texas negotiate enterprise-wide service arrangements across heterogeneous equipment fleets.
- Research Institutes:National cancer grid institutions in India and European translational research centers drive first-time equipment demand for protocol development and clinical trials.
- Outpatient Facilities:Ambulatory surgery centers and community radiation suites favor compact afterloader configurations with simplified regulatory pathways.
Hospitals retain dominant installed base share; oncology clinics are climbing the fastest as same-day discharge protocols expand.
Technology:
Automation depth and staff radiation exposure elimination now differentiate platforms more than mechanical positioning precision.
- Remote Afterloading:Electromechanical source positioning eliminates staff radiation exposure and enables complex stepping-source optimization algorithms. FDA 510(k) pathways and MDR technical documentation requirements shape development timelines for manufacturers seeking market access.
- Digital Afterloading:Software-defined dwell time optimization and automated catheter reconstruction reduce physicist staffing burdens. Machine learning algorithms for treatment planning are consolidating preference in prostate and gynecological applications.
- Manual Afterloading:Hand-loaded source applications persist in resource-constrained settings with limited regulatory infrastructure.
- Integrated Systems:Hardware-software bundles combining afterloader platforms with oncology information systems face interoperability challenges from proprietary data formats of 1990s-era legacy units.
Remote Afterloading commands dominant revenue contribution; Digital Afterloading is gaining share fastest through AI-enabled planning modules.
Application:
Anatomical site determines applicator design, imaging compatibility requirements, and reimbursement parity with external beam alternatives.
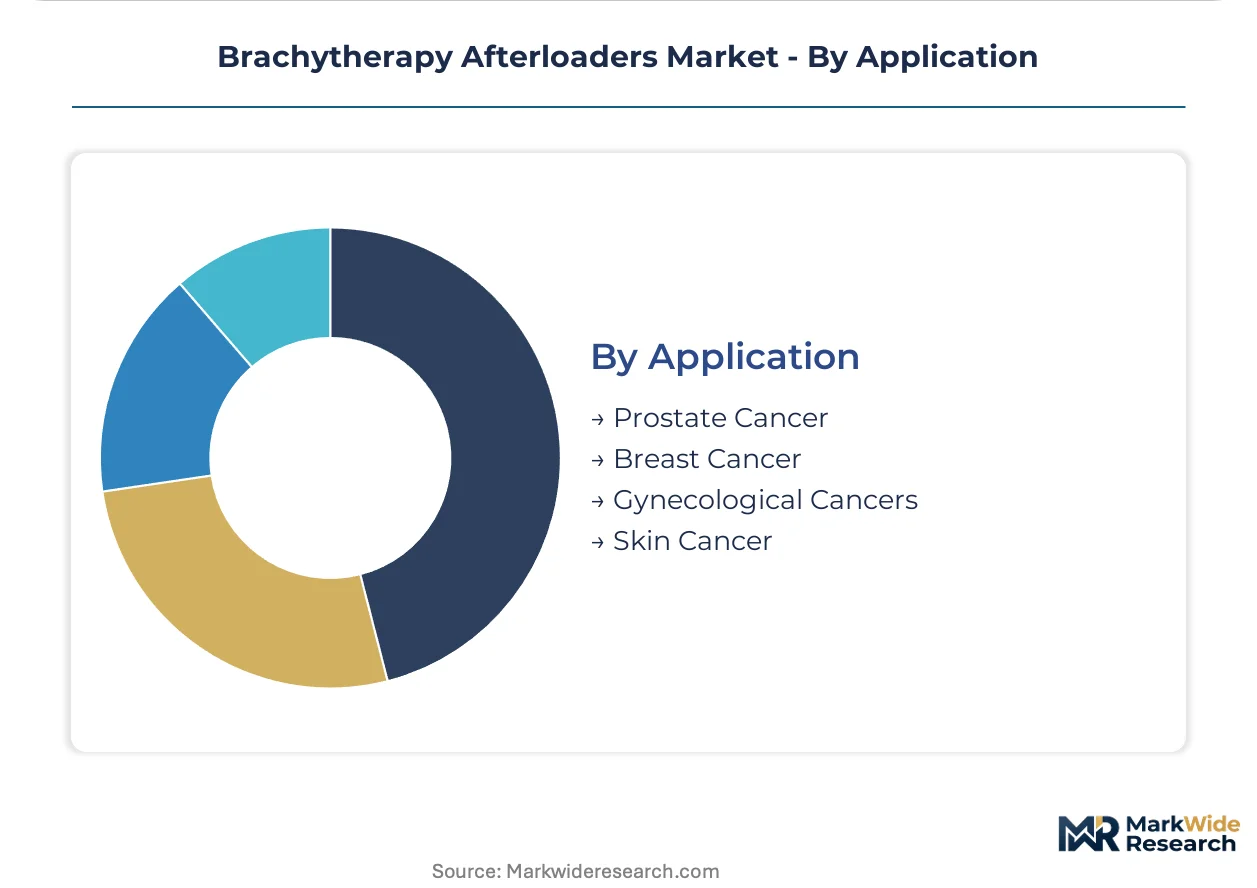
- Gynecological Cancers:Cervical and endometrial applications demand specialized tandem-and-ovoid or interstitial needle applicators with MR compatibility. European clinics revisit Pulsed Dose Rate technology for its normal tissue sparing advantages in locally advanced cases.
- Prostate Cancer:Interstitial brachytherapy with permanent seeds or High Dose Rate boost sequences competes with stereotactic body radiation therapy for curative cases. Academic centers in the United States and Germany lead adoption of MR-conditional platforms for soft-tissue visualization.
- Breast Cancer:Accelerated partial breast irradiation via interstitial or intracavitary approaches targets lumpectomy cavities with reduced treatment fractions.
- Skin Cancer:Surface applicators and custom-molded plaques address superficial lesions with limited penetration requirements.
Gynecological Cancers anchor historical procedure volume; Prostate Cancer is expanding most quickly through MR-integrated platform upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and Shanghai concentrate component sourcing for afterloader electromechanical assemblies. Tax incentives for medical device manufacturing in Penang and Singapore accelerate regional supply chain reconfiguration.
United States
Proton therapy networks in Houston and Boston drive replacement cycles for aging cobalt-based units. FDA 510(k) premarket notification requirements compress development timelines for new remote afterloading platforms. The Texas Medical Center anchors demand concentration as academic medical centers prioritize MR-conditional upgrades.
Germany
University hospitals in Heidelberg and Munich accelerate MDR-compliant procurement to secure transitional provisions. Germany's national pharmaceutical regulator enforces post-market surveillance data collection for legacy platforms exceeding two decades of service. The Rhine-Main cluster consolidates preference for Pulsed Dose Rate technology in gynecological applications.
India
Government-funded cancer center construction under the National Cancer Grid creates first-time equipment demand in tier-2 cities. CDSCO medical device registration requirements shape import pathways for European and American manufacturers. The Mumbai-Pune corridor concentrates oncology network expansion as state governments expand radiation therapy access.
Netherlands
Academic medical centers in Amsterdam and Rotterdam replace cobalt-based units with MR-conditional platforms at accelerated cycles. EMA guidance on clinical evaluation reports influences notified body interpretations for brachytherapy device recertification. The Eindhoven-Utrecht axis drives digital afterloading adoption through integrated oncology information system deployments.
Japan
PMDA quality management system inspections extend approval timelines for foreign-manufactured afterloaders. METI subsidies for advanced medical equipment procurement support hospital capital investment programs. The Kansai region around Osaka concentrates proton therapy integration projects that cross-sell brachytherapy platforms.
Brachytherapy Afterloaders Market Vendor Landscape
North American producers anchor one tier; European specialists hold differentiated positions through regulatory expertise and localized manufacturing. The vendor base concentrates around electromechanical platform providers with captive service networks and training infrastructure. Three archetypes dominate: integrated radiation oncology conglomerates with proton therapy ecosystems; dedicated brachytherapy platform specialists with applicator libraries; and component suppliers with source logistics capabilities. Strategic moves center on M&A for oncology information system integration and geographic expansion into government-funded cancer grid networks.
Among Sweden-based radiation therapy conglomerates, Elekta AB exemplifies installed base leadership through dedicated service infrastructure. Varian Medical Systems occupies a position within the integrated oncology ecosystem tier, leveraging proton therapy networks for cross-selling leverage. Eckert & Ziegler BEBIG represents the European specialist archetype, anchoring market presence through localized manufacturing and MDR regulatory expertise.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Eckert & Ziegler BEBIG |
| BEBIG Medical GmbH |
| Best Medical International |
| Eckert and Ziegler AG |
| Theragenics Corporation |
| IsoRay Medical |
| iCAD |
| Others |
Supply Flow & Price Mechanics
Specialized medical physicist concentrations in Germany and the Netherlands anchor labor-cost differentials that widen pricing-tier spreads between premium MR-conditional platforms and standard CT-guided systems.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with premium margins attaching to sub-90-day delivery commitments for MDR-compliant platforms while spot inventory of legacy cobalt-based units trades at structural discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Cost compression in the standard tier intensifies because independent service organizations are unbundling maintenance contracts from hardware sales. Community hospitals in tier-2 Indian cities exhibit highest price sensitivity; academic medical centers in the United States demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Penang and Shenzhen electromechanical assembly clusters are elongating component lead times for stepping-source drive mechanisms. Manufacturing concentrates in Germany, the United States, and China, with source logistics drawing from Canadian and Russian reactor output for cobalt-60 and iridium-192. Single-source vulnerability in isotope supply creates exposure to research reactor maintenance schedules. Distribution runs through manufacturer-captive service networks in developed markets and independent physics groups in fragmented U.S. regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market operates as a supply-constrained story where medical physicist scarcity props pricing power for service-integrated platform vendors.
For Market Incumbents: Extend service infrastructure depth into tier-2 Indian cities before National Cancer Grid procurement committees finalize vendor shortlists. Defend against external beam substitution by embedding AI-enabled treatment planning modules that reduce physicist staffing burdens per procedure. Prioritize MDR technical documentation investment to capture European replacement demand during transitional provision windows. For New Entrants and Emerging Players: Launch via independent service organization partnerships in California and Texas integrated delivery networks, bypassing manufacturer-captive channel control. Target outpatient facilities in the United States with compact afterloader configurations that compress shielded vault construction costs. White-space concentrates in AI-enabled catheter reconstruction software licensing to existing hardware fleets. For Investors and Strategic Acquirers: The window for entry favors oncology information system integrators with brachytherapy workflow modules. Long-term viability hinges on capturing physics group procurement authority as service unbundling fragments traditional purchasing patterns. Signal to monitor: FDA 510(k) clearance velocity for MR-conditional platforms as proxy for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Secures notified body recertification pathways for legacy platform revenue retention in Germany and Italy. |
| AI-Enabled Treatment Planning Development | Reduces physicist staffing burdens that constrain community hospital program viability across the United States. |
| Independent Service Organization Partnership | Captures maintenance revenue as California and Texas integrated delivery networks unbundle service contracts. |
| MR-Conditional Platform Launch | Consolidates preference in prostate and gynecological applications where Heidelberg and Munich academic centers drive replacement cycles. |
| National Cancer Grid Channel Development | Positions for first-time equipment demand in tier-2 Indian cities under government-funded oncology network expansion. |
Methodological Framework
Document review covered FDA 510(k) filings, EMA clinical evaluation reports, and hospital procurement databases, complemented by interviews with radiation oncology department heads, medical physicists, GPO contracts managers, and biomedical engineers at academic medical centers. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 certification registries, and notified body technical documentation summaries. Bottom-up installed base modeling and top-down revenue triangulation anchored market sizing.
Segmented outputs across product type, end user, technology, application, and geography dimensions were generated over the projection horizon. CAGRs were derived from regression analysis against historical replacement cycles and penetration rate assumptions. Forecast inputs incorporated MDR compliance deadline impacts on European procurement timing and National Cancer Grid construction schedules in India.
The model assumes a particular technology adoption path; alternative pathways for Pulsed Dose Rate revival in European gynecological clinics would alter the outlook. Forecasts reflect assumptions regarding isotope supply continuity and reimbursement parity with external beam alternatives. Material deviation in medical physicist training pipeline output or FDA premarket notification timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Airway Management Devices Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Thrombectomy System Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Global Monopolar Electrosurgery Market