
 Mexico Spinal Surgery Devices Market | 2026-2036
Mexico Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Spinal Surgery Devices Market Foresight
Titanium is hardening its position against traditional stainless steel in posterior spinal fixation systems, reducing implant failure rates and revision surgery burdens. Medtronic PLC leverages its integrated spine platform to dominate complex deformity correction procedures in Mexican teaching hospitals. Stryker Corporation anchors its presence through sustained investment in navigation-enabled instrumentation. Zimmer Biomet differentiates via specialized motion-preservation technologies that compete with conventional fusion approaches.
Mexico spinal surgery devices encompass implantable hardware, precision instruments, and enabling technologies designed to stabilize, decompress, or reconstruct the vertebral column, typically manufactured from biocompatible alloys with surface treatments promoting osseointegration. These systems serve to restore spinal alignment, relieve neural compression, and enable fusion or motion-preservation in patients with degenerative, traumatic, or deformity-related pathologies. Implants command the deepest margin pools due to long-term implantation requirements and premium alloy specifications, while navigation systems represent the fastest-growing technology dimension as Mexican surgeons adopt computer-assisted workflows. Degenerative disorders occupy the largest application share reflecting Mexico's aging demographic profile, though minimal invasive technology is displacing traditional open approaches in outpatient surgery centers where recovery economics favor reduced hospitalization.
COFEPRIS maintains primary oversight of medical device registration and post-market surveillance, with NOM standards governing biocompatibility and sterilization validation for imported spinal implants. The Mexican Ministry of Health's alignment with international harmonization initiatives is compressing regulatory review timelines and reshaping how manufacturers structure their Mexico market access strategies. Stakeholders must monitor evolving reimbursement frameworks within the INSABI-IMSS transition and assess whether local manufacturing partnerships or direct importation models better serve cost-positioning objectives in an increasingly price-sensitive public procurement environment.
Market Dynamics
Titanium alloy adoption in posterior fixation systems is compressing revision surgery rates while COFEPRIS regulatory streamlining accelerates import registration timelines for multinational manufacturers.
Growth Catalysts
- COFEPRIS Registration Harmonization:The Mexican medical device regulator has compressed review timelines through alignment with international standards, enabling faster market entry for spinal implant manufacturers.
- Metropolitan Hospital Infrastructure:Tertiary care centers in Mexico City, Monterrey, and Guadalajara are expanding dedicated spine surgery units with navigation-enabled operating theaters.
- Minimal Invasive Technique Diffusion:Outpatient surgery centers are adopting percutaneous pedicle screw systems that reduce hospitalization duration and shift procedures from inpatient to ambulatory settings.
Market Restraints
- Titanium Alloy Cost Structure:Premium-grade titanium raw material pricing volatility constrains margin flexibility for domestic distributors serving public procurement channels.
- Supply Concentration Risk:Navigation system hardware depends heavily on US and German precision sensor suppliers, creating exposure to transatlantic logistics disruptions.
- Technical Limitation in Rural Access:Image-guided surgery platforms require fiber-optic infrastructure absent in secondary Mexican cities, limiting technology penetration outside metropolitan zones.
Strategic Opportunities
- Central Mexico Underserved Regions:Puebla, Querétaro, and León represent surgical device penetration gaps where orthopedic clinic expansion is outpacing equipment availability.
- Motion-Preservation Convergence:Artificial disc replacement systems combined with dynamic stabilization rods offer alternatives to fusion in younger patient demographics.
- INSABI Reimbursement Modernization:The federal health system's procedural coding updates create pathways for novel implant categories to secure public coverage eligibility.
Industry Challenges
- Navigation System Integration Complexity:Mexican surgical teams face steep learning curves merging intraoperative imaging with legacy C-arm equipment in facilities with mixed-vendor installed bases.
- Biocompatibility Certification Timeline:NOM sterilization validation requirements extend product registration cycles for manufacturers lacking pre-existing ISO 13485 documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Spinal Surgery Devices Market |
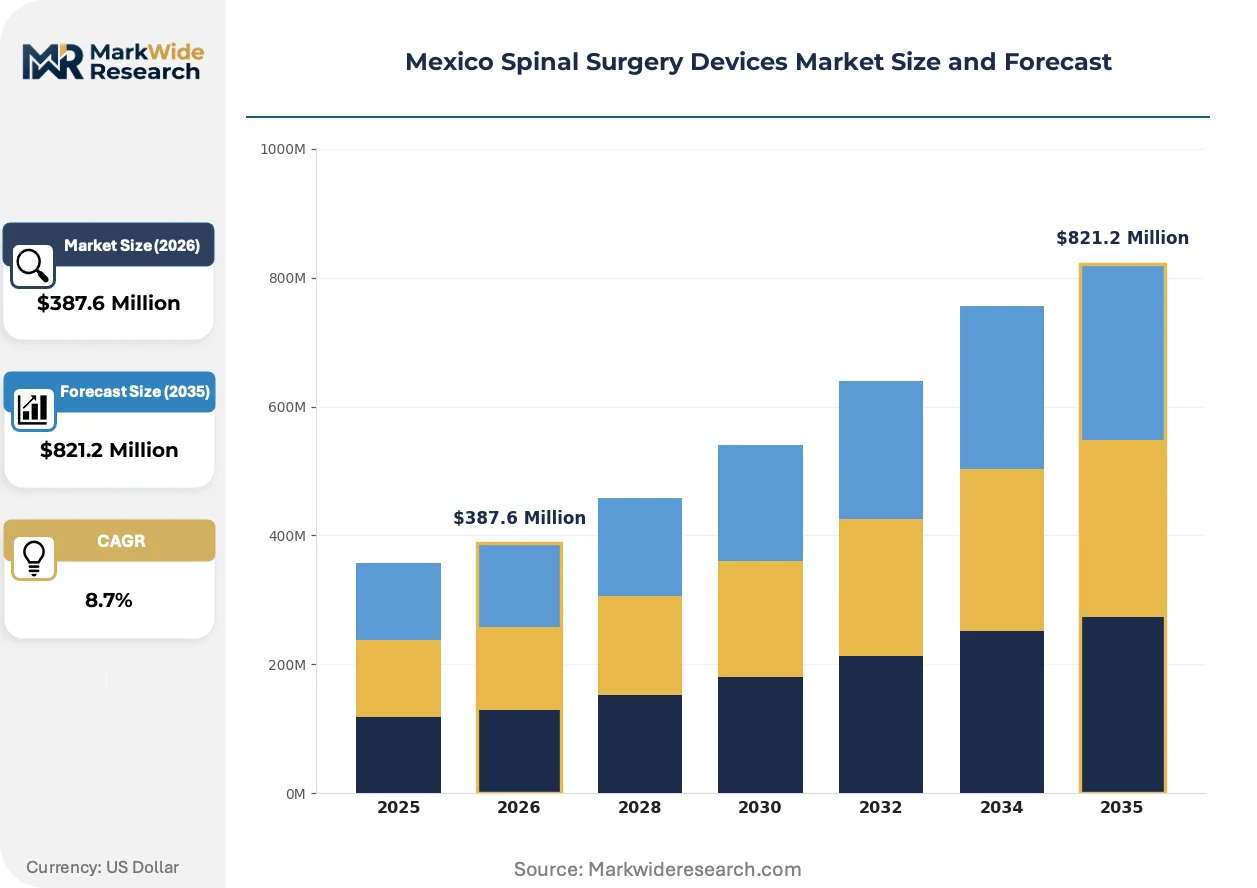
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Navigation Systems, Bone Grafts End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Outpatient Surgery Centers Technology: Minimal Invasive, Robotic Surgery, Traditional Surgery, Computer-Assisted Application: Degenerative Disorders, Trauma, Scoliotic Conditions, Tumors |
| Companies Covered | Medtronic PLC, Stryker Corporation, Zimmer Biomet, Johnson & Johnson, B. Braun Melsungen AG, Globus Medical Inc, Orthofix Holdings Inc, NuVasive, DePuy Synthes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Spinal Surgery Devices Market Shifts & Advancements
Three intersecting developments are restructuring how spinal interventions are planned, executed, and reimbursed across Mexican healthcare networks.
Robotic-assisted guidance platforms are integrating preoperative CT planning with intraoperative navigation to reduce pedicle screw malposition rates. Tertiary hospitals in Mexico City and Monterrey are piloting these systems through equipment-leasing arrangements with vendor field specialists. The technology is compressing training requirements for complex deformity corrections while expanding the addressable surgical population.
COFEPRIS has implemented expedited review pathways for devices holding prior US FDA 510(k) clearance or EU MDR certification, reducing registration timelines for established multinational portfolios. This regulatory convergence favors manufacturers with existing international approvals over domestic newcomers lacking harmonized documentation. Spinal implant categories with predicate device histories are migrating fastest through the streamlined process.
Hospital purchasing consortia are consolidating procurement decisions across state-level health systems, displacing individual facility autonomy in vendor selection. Group Purchasing Organizations serving IMSS and ISSSTE networks are extracting volume-based pricing concessions from distributors. This concentration is most visible in Mexico City where integrated delivery networks now control the majority of spinal implant purchasing decisions.
Mexico Spinal Surgery Devices Market Segmentation
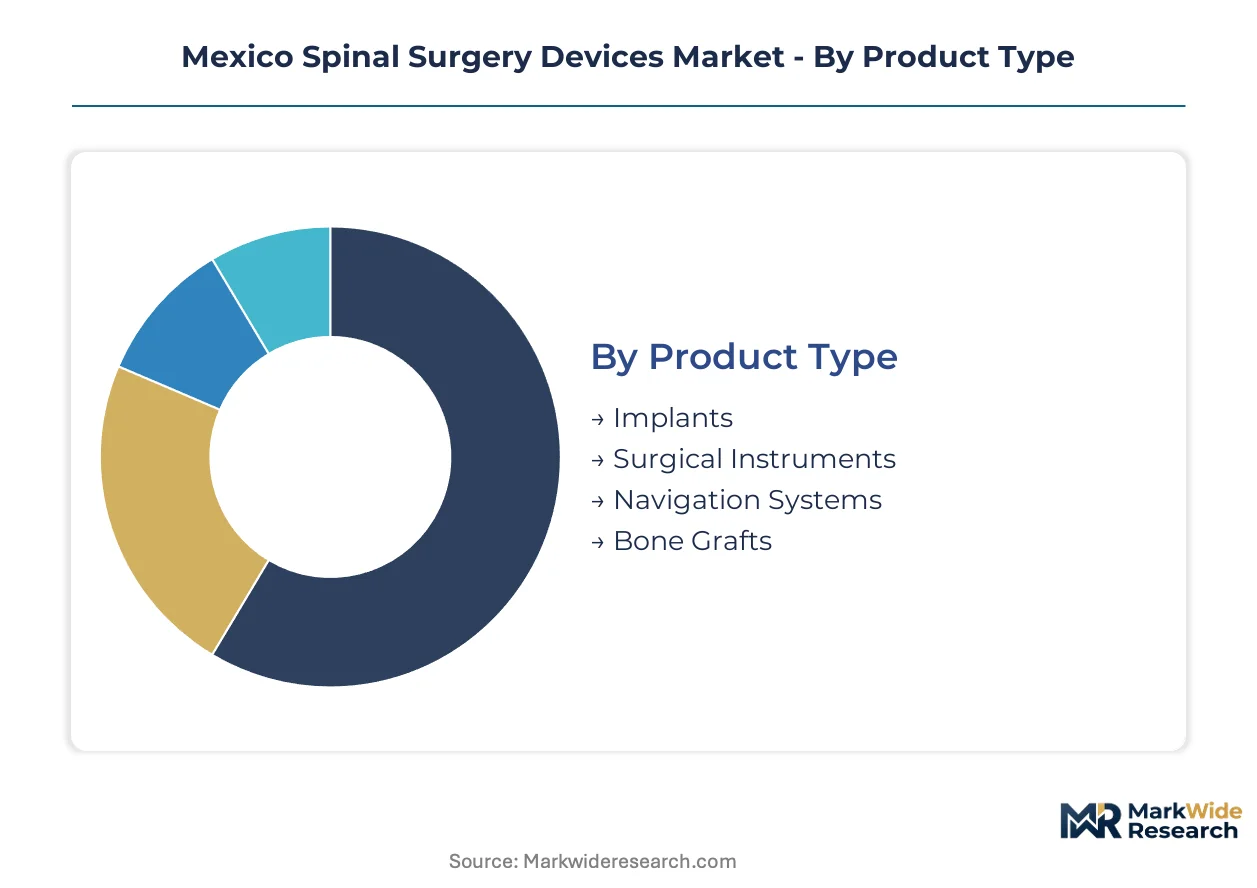
Spinal surgery devices in Mexico fragment across four critical dimensions that determine procurement pathways, clinical adoption curves, and margin architecture for manufacturers navigating the COFEPRIS registration landscape.
Product Type:
Purchasing committees weight long-term implantation requirements against capital equipment depreciation cycles when allocating budget across spinal device categories.
- Implants:Titanium alloy pedicle screws, interbody cages, and fixation rods carry premium pricing due to biocompatibility certification and osseointegration surface treatments. Demand concentrates in Mexico City tertiary hospitals performing complex deformity corrections where revision surgery costs drive preference for premium alloys.
- Navigation Systems:Intraoperative imaging platforms with optical tracking reduce screw malposition rates in minimally invasive procedures. Adoption clusters in Monterrey and Guadalajara surgical suites where hospital groups amortize capital costs across high procedural volumes.
- Surgical Instruments:Retractors, drills, and distractors manufactured from medical-grade stainless steel serve as the procedural workhorse across Mexican spine programs.
- Bone Grafts:Synthetic and allograft materials supplement autologous harvesting in fusion procedures, with synthetic alternatives gaining preference amid supply chain reliability concerns.
Volume sits with Implants; growth tilts toward Navigation Systems.
End User:
Facility reimbursement structure and surgical case complexity determine device selection authority across Mexico's delivery network.
- Hospitals:Tertiary centers in Mexico City, Monterrey, and Guadalajara maintain full-service spine programs with navigation-enabled operating theaters and fellowship-trained surgeons. IMSS and ISSSTE networks drive procurement consolidation through group purchasing organizations extracting volume-based concessions.
- Orthopedic Clinics:Specialized spine clinics in metropolitan corridors perform selective decompression and single-level fusions, favoring streamlined instrument sets over capital-intensive navigation platforms.
- Outpatient Surgery Centers:Ambulatory facilities in Puebla and Querétaro are expanding percutaneous screw capabilities that shift procedures from inpatient to same-day discharge settings.
- Rehabilitation Centers:Post-acute facilities coordinate with surgical providers for device monitoring and complication management, influencing implant selection through long-term follow-up data.
Procurement authority concentrates in Hospitals; expansion momentum favors Outpatient Surgery Centers.
Technology:
Surgeon training infrastructure and capital availability partition adoption curves across procedural approaches.
- Minimal Invasive:Percutaneous access techniques reduce tissue disruption and hospitalization duration, aligning with outpatient economics in Mexican metropolitan markets.
- Computer-Assisted:Navigation platforms merge preoperative planning with intraoperative guidance, compressing learning curves for pedicle screw placement in teaching hospitals.
- Robotic Surgery:Robotic guidance systems integrate CT planning with drill trajectory control, piloted in Mexico City through vendor leasing arrangements with field specialist support.
- Traditional Surgery:Open approaches with direct visualization retain dominance in rural facilities lacking fiber-optic infrastructure for image-guided platforms.
Traditional Surgery retains procedure volume; Minimal Invasive claims the steepest expansion trajectory.
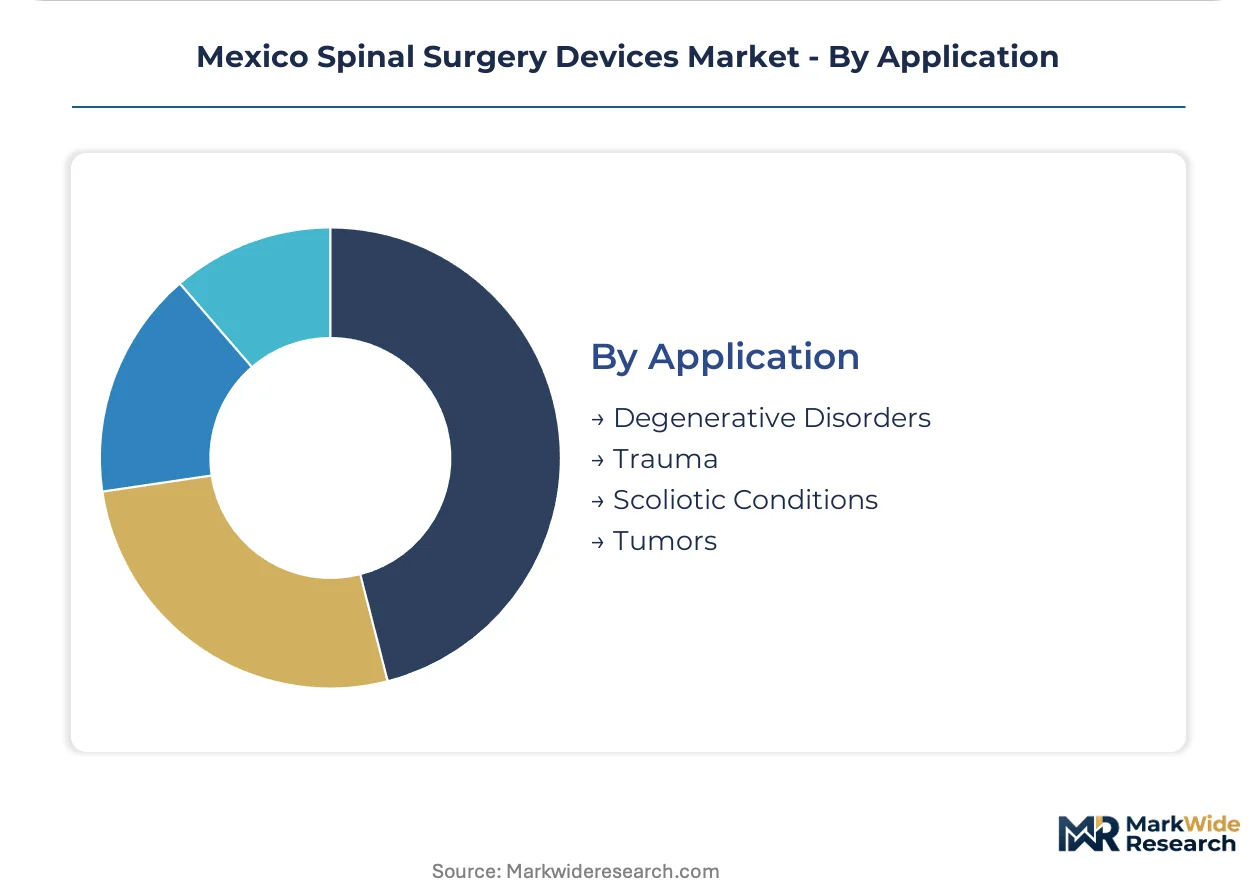
Application:
Patient demographic profile and disease prevalence shape demand concentration across spinal pathologies.
- Degenerative Disorders:Spondylolisthesis, spinal stenosis, and disc herniation drive the largest procedural volume as Mexico's aging population expands the addressable surgical population. Cases cluster in IMSS facilities serving formal sector workers with chronic occupational spine loading.
- Scoliotic Conditions:Adolescent and adult deformity corrections command premium implant configurations and extended operative times, concentrating in academic medical centers with specialized fellowship programs.
- Trauma:Fracture stabilization from vehicular and occupational injuries generates acute demand for posterior fixation systems across emergency departments in Monterrey industrial corridors.
- Tumors:Oncologic resection and reconstruction procedures require customized implant solutions with limited standardization, representing niche demand in national cancer institutes.
Case volume aggregates in Degenerative Disorders; complexity premiums concentrate in Scoliotic Conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Mexico City, Monterrey, and Guadalajara where tertiary hospital infrastructure supports complex spinal procedures. COFEPRIS regulatory harmonization with international standards accelerates device registration for manufacturers targeting these metropolitan clusters. The federal health system's procurement consolidation reshapes how suppliers structure regional distribution networks.
Mexico City Metro
IMSS and ISSSTE tertiary hospitals drive implant procurement volume through group purchasing organizations extracting volume-based concessions. COFEPRIS maintains its headquarters here, streamlining registration pathways for multinationals with existing FDA or EU MDR clearance. The city's academic medical centers pilot robotic-assisted guidance platforms through vendor leasing arrangements.
Nuevo León
Monterrey's industrial corridor generates trauma-related spinal fixation demand from occupational and vehicular injuries. State-level hospital purchasing consortia consolidate procurement decisions across public networks, displacing individual facility autonomy. Specialized spine clinics expand surgical capabilities in the metropolitan area, favoring streamlined instrument sets over capital-intensive navigation platforms.
Jalisco
Guadalajara's outpatient surgery centers adopt percutaneous pedicle screw systems that shift procedures from inpatient to same-day discharge settings. The state's fiber-optic infrastructure supports image-guided surgery platform adoption in tertiary facilities. Orthopedic clinic expansion in the metropolitan corridor outpaces equipment availability, creating penetration gaps for device suppliers.
Bajío Region
Puebla, Querétaro, and León represent underserved surgical device markets where clinic expansion exceeds equipment supply. The INSABI-IMSS transition creates reimbursement pathway uncertainty for novel implant categories in public procurement channels. Secondary cities lack fiber-optic infrastructure for navigation systems, limiting technology penetration to traditional open approaches.
Northern Border States
Cross-border healthcare referral patterns channel complex deformity corrections to US facilities, constraining premium implant demand in Tijuana and Ciudad Juárez. Maquiladora occupational health programs generate spinal screening volumes that feed diagnostic demand. Supply chain logistics exposure to transborder disruptions affects navigation system hardware availability.
Mexico Spinal Surgery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals dominating complex deformity correction while regional distributors serve price-sensitive public procurement channels. The vendor base organizes around three strategic archetypes: full-platform spine companies with navigation-enabled portfolios, motion-preservation specialists competing against fusion approaches, and regional distributors leveraging COFEPRIS registration expertise for import-dependent supply. Competitive moves center on equipment-leasing arrangements for capital-intensive robotic platforms and group purchasing organization penetration to secure volume commitments from consolidated hospital networks.
Among Ireland-registered multinationals, Medtronic PLC exemplifies the full-platform archetype through integrated spine systems targeting teaching hospital complex procedures. Stryker Corporation, a US-based entity, occupies a position anchored in navigation-enabled instrumentation investment. Zimmer Biomet represents the motion-preservation specialization vector, differentiating through artificial disc and dynamic stabilization alternatives to conventional fusion. These three entities sit within the premium-tier procurement channels where tertiary hospital purchasing committees weight long-term implantation requirements against capital equipment depreciation cycles.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Zimmer Biomet |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Globus Medical Inc |
| Orthofix Holdings Inc |
| NuVasive |
| DePuy Synthes |
| Others |
Supply & Pricing Matrix
Captive titanium alloy processing in US and German precision forges anchors supply positioning for premium spinal implants while compressing margin flexibility for Mexican distributors serving price-sensitive public procurement channels. This upstream concentration feeds directly into tiered pricing architecture across IMSS and ISSSTE networks.
Pricing Analysis
Volume aggregates in standard-grade titanium pedicle screws while margins concentrate in navigation-enabled platforms and robotic guidance systems. Three-tier pricing structure across premium navigation bundles, standard implant sets, and economy stainless steel configurations separates academic medical centers from metropolitan hospitals and rural facilities. Cost compression in the economy tier intensifies as group purchasing organizations extract volume concessions from distributors serving consolidated state-level networks. Public procurement channels exhibit highest price sensitivity; private tertiary centers in Mexico City demonstrate lowest sensitivity due to bundled service pricing and outcome-based contracting.
Supply Chain Analysis
Transatlantic freight costs and transborder logistics exposure shape inventory positioning for navigation system hardware sourced from German precision sensor suppliers and US optical tracking manufacturers. Raw material dependencies center on aerospace-grade titanium billet from US mills, medical-grade cobalt-chrome from European foundries, and precision-machined components from Swiss and Japanese contract manufacturers. Single-source vulnerability concentrates in optical tracking arrays and electromagnetic field generators, with tariff exposure running through US-Mexico-Canada trade corridors. Distribution runs through authorized distributor networks holding COFEPRIS import licenses, with tertiary hospitals maintaining direct vendor relationships for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium alloy supply constraints from aerospace-industry competition for forge capacity prop implant pricing premiums, creating a supply-constrained market structure where capacity bottlenecks defend margin pools for integrated manufacturers.
For Market Incumbents: Deploy equipment-leasing arrangements for robotic guidance platforms to lock in teaching hospital relationships before competitive entry. Deepen backward integration into titanium alloy sourcing through long-term offtake agreements with US mills, defending against aerospace-industry demand spikes. Consolidate distributor relationships in Monterrey and Guadalajara to preempt regional challengers exploiting COFEPRIS registration expertise. For New Entrants and Emerging Players: The premium-to-economy price-point gap in navigation systems creates entry opportunity for simplified optical tracking platforms targeting orthopedic clinics in Puebla and Querétaro. Target outpatient surgery centers in the Bajío region with streamlined percutaneous screw systems that bypass capital-intensive platform competition. Pursue COFEPRIS registration harmonization pathways for devices holding prior FDA clearance to compress market entry timelines against domestic newcomers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-platform spine companies seeking navigation technology tuck-ins or regional distribution capabilities. Long-term viability favors manufacturers with captive titanium supply relationships and established GPO contracts across IMSS networks. Watch INSABI reimbursement coding updates as the inflection signal for novel implant category coverage eligibility and associated valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Harmonization | Expedited pathways for FDA-cleared devices compress market entry timelines against domestic competitors. |
| Hospital System Partnership | Equipment-leasing arrangements with Mexico City teaching hospitals secure robotic platform adoption. |
| Backward Integration into Titanium Supply | Long-term offtake agreements with US aerospace-grade mills defend against raw material competition. |
| Reimbursement Strategy | INSABI procedural coding alignment secures public coverage eligibility for motion-preservation implants. |
| Software Companion Development | Preoperative CT planning modules integrate with intraoperative navigation to reduce screw malposition rates. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, COFEPRIS regulatory filings, and distributor financial disclosures underwrites the qualitative findings on procurement consolidation dynamics. Primary fieldwork engaged spine surgeons at IMSS tertiary facilities, biomedical engineers managing navigation platform integration, GPO contracts managers, and orthopedic clinic operators in Puebla and Querétaro. Secondary validation drew from COFEPRIS medical device registration databases, hospital procurement records, and trade data on titanium alloy imports. Bottom-up demand modeling across metropolitan facility expansion and top-down macroeconomic anchoring produced convergent volume estimates.
Comparable-period analysis anchored the projection window to historical procedural volume growth and capital equipment replacement cycles observed across Mexico City, Monterrey, and Guadalajara surgical suites. The analytical framework segmented by product type, end-user facility tier, technology adoption curve, and application pathology, with cross-dimensional interaction effects modeled for navigation system penetration against traditional open surgery. CAGRs derived from logistic diffusion curves for capital equipment and linear extrapolation for implant consumption, calibrated against demographic aging projections and occupational injury incidence patterns.
Inputs from hospital purchasing committees and distributor inventory records were available through the study window; gaps in real-time INSABI reimbursement transition data introduce uncertainty bands around public procurement volume assumptions. Forecasts reflect modeled assumptions about regulatory harmonization pace and metropolitan infrastructure investment commitments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Device Connectors Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Toe Fixation System Market
Medical Devices
China Contraceptive Devices Market
Medical Devices
Pharma Robots Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Bioimpedance Devices Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Medical Thermometer Market
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Lyophilized Injectable Market