
 Wearable Medical Robots Market | 2026-2036
Wearable Medical Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Medical Robots Market Analytics
Physical therapist shortages across OECD healthcare systems is rotating capital allocation toward automated gait-training platforms that reduce hands-on clinician hours. Ekso Bionics Holdings, Inc. dominates inpatient rehabilitation with FDA-cleared exoskeletons for stroke and spinal cord populations. Cyberdyne Inc. anchors the Japanese market through PMDA-approved HAL hybrid assistive limbs deployed at university hospitals. Hocoma AG specializes in sensor-driven robotic gait trainers for pediatric and adult neurorehabilitation centers.
Wearable medical robots comprise electromechanical frameworks worn on the body to restore, augment, or substitute human movement through powered actuation, force sensing, and closed-loop motor control with torque thresholds typically ranging from 10 to 80 Newton-meters at lower-limb joints. These systems serve primarily to reduce therapist burden, standardize repetitive movement dosing, and accelerate functional recovery in neurological and orthopedic patient populations. Exoskeletons command the dominant revenue share due to reimbursement codes in German and U.S. inpatient settings, while smart wearables with embedded IMU arrays and cloud-connected analytics represent the fastest-expanding technology tier as home-based prescription models gain traction. Rehabilitation robots capture concentrated margin pools through long-term service contracts and software subscription overlays that lock in provider relationships beyond initial hardware deployment.
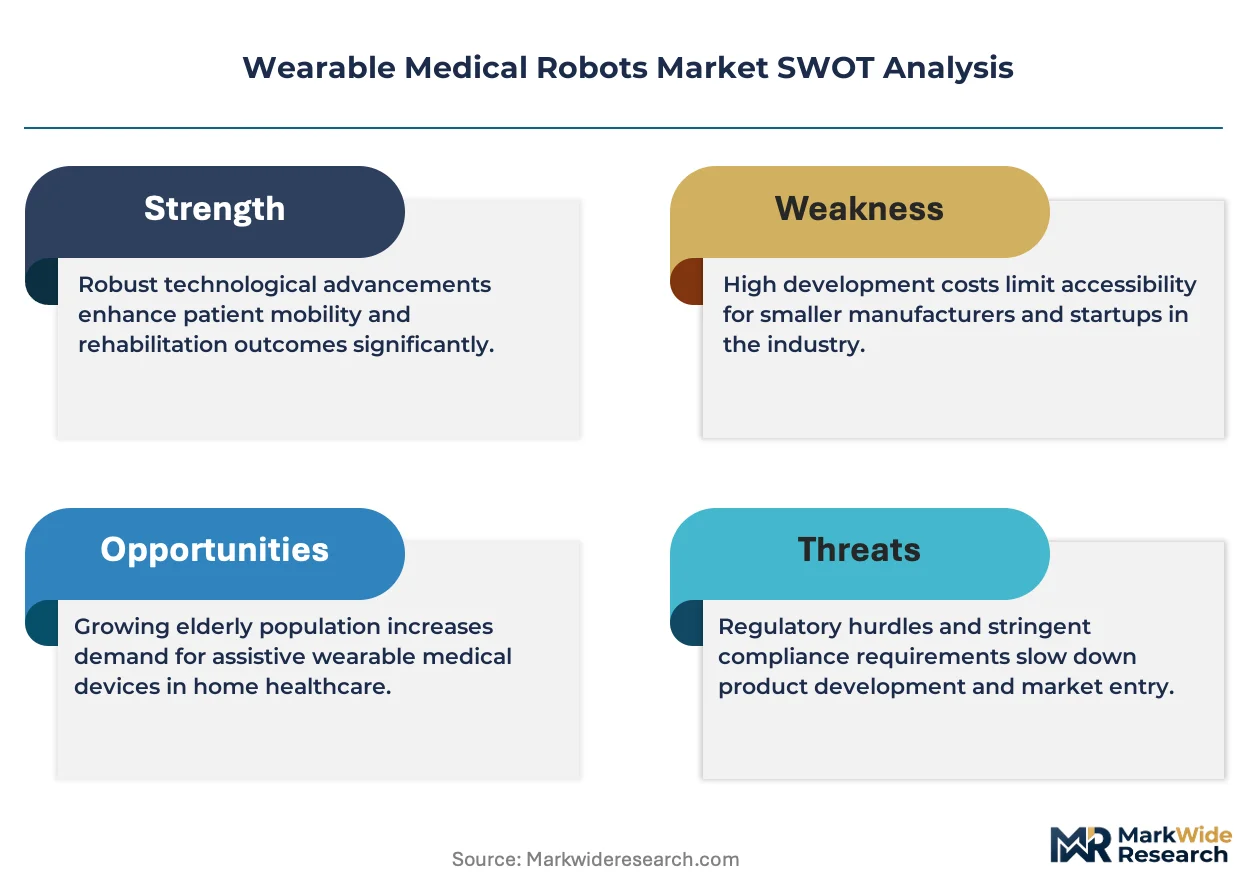
FDA 510(k) and breakthrough device pathways govern U.S. market access for wearable medical robots, while Japan's PMDA and Germany's BfArM enforce distinct clinical evidence standards that shape regional product development priorities. The EU Medical Device Regulation imposes post-market surveillance and notified body recertification burdens that favor established players with dedicated regulatory affairs teams. Stakeholders must monitor reimbursement parity between robotic and conventional therapy across national health technology assessment bodies to calibrate geographic expansion sequencing.
Market Dynamics
Reimbursement parity negotiations between robotic therapy providers and national health technology assessment bodies are compressing time-to-market for developers while forcing hardware manufacturers to demonstrate cost-effectiveness against conventional physical therapy protocols.
Growth Catalysts
- FDA Breakthrough Device Pathway:The U.S. regulator's accelerated review mechanism compresses clinical trial timelines for neurorehabilitation hardware, enabling faster commercialization of powered exoskeletons for spinal cord injury populations.
- German Inpatient Reimbursement Codes:Statutory health insurance recognition of robotic gait training in rehabilitation centers creates predictable revenue streams for hardware procurement and long-term service contracts.
- Actuator Miniaturization:Advances in brushless DC motor density and torque-to-weight ratios enable lighter exoskeleton frames that reduce patient fatigue during extended therapy sessions.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Dependence on East Asian cell manufacturers for high-discharge power packs exposes production schedules to raw material allocation constraints and shipping volatility.
- EU MDR Recertification Burden:The Medical Device Regulation's post-market surveillance requirements and notified body backlogs extend compliance timelines for Class IIa and IIb rehabilitation robots.
- Manual Therapy Substitution:Low-cost therapist-assisted gait training remains the clinical default in emerging markets with limited capital budgets for electromechanical platforms.
Strategic Opportunities
- Home-Based Prescription Models:Cloud-connected smart wearables with embedded IMU arrays enable remote monitoring of stroke recovery progress, opening reimbursement pathways outside institutional settings.
- Japan's PMDA Fast-Track Pathways:Priority review for neurorehabilitation devices accelerates market entry for hybrid assistive limb systems targeting university hospital networks.
- Pediatric Neurorehabilitation:Sensor-driven gait trainers sized for cerebral palsy patients address an underserved demographic with higher therapy intensity requirements and longer treatment horizons.
Industry Challenges
- Clinical Evidence Generation:Randomized controlled trials comparing robotic against conventional therapy demand multi-site coordination and extended follow-up periods that strain R&D budgets.
- Interoperability with EMR Systems:Integration of gait analytics platforms with hospital electronic medical record architectures requires custom API development and IT security certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Medical Robots Market |
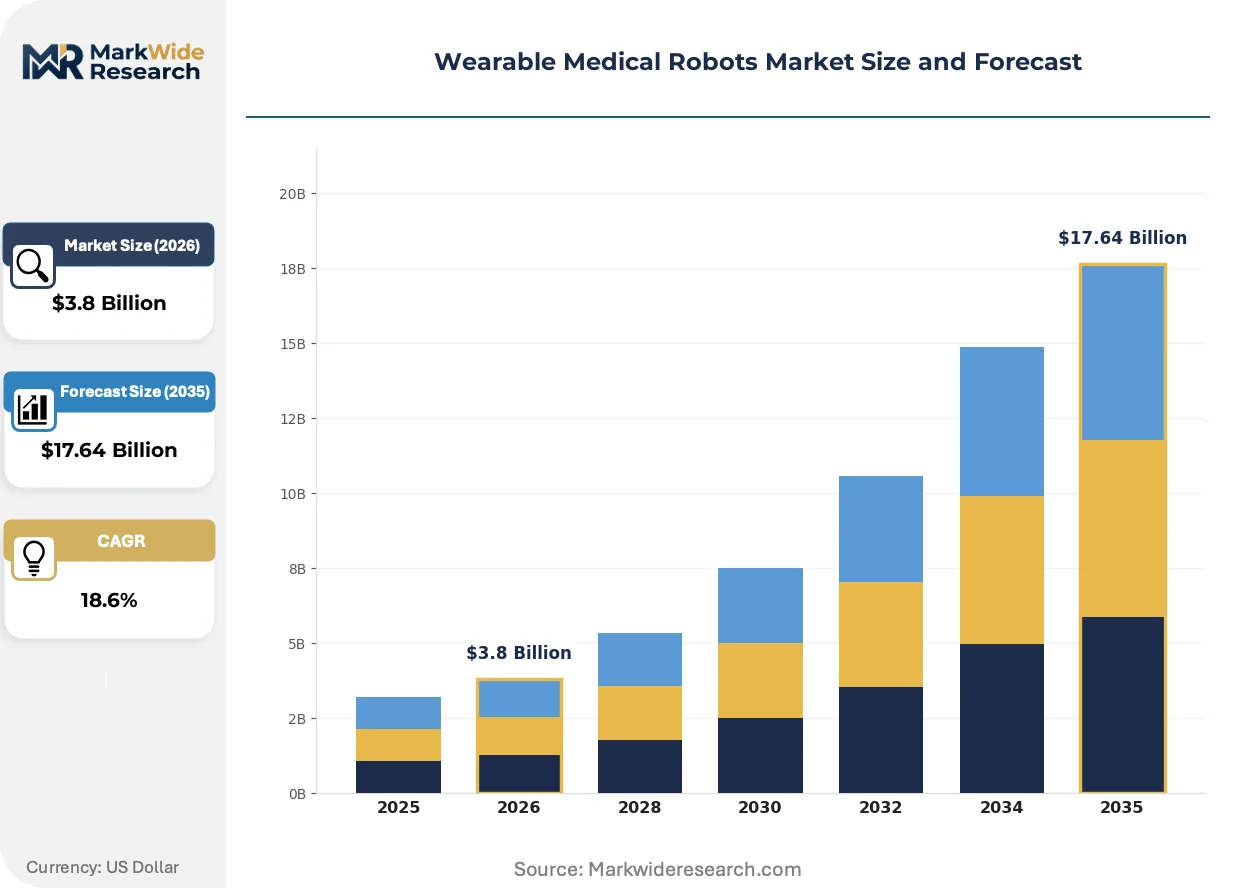
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeletons, Wearable Assistive Devices, Rehabilitation Robots, Mobility Aids Technology: Active Systems, Passive Systems, Hybrid Systems, Smart Wearables End User: Healthcare Providers, Patients, Rehabilitation Centers, Research Institutions Application: Rehabilitation, Mobility Assistance, Surgical Assistance, Physical Therapy |
| Companies Covered | Lifeward Ltd, Ekso Bionics Holdings, Inc., Fourier Intelligence Co., Ltd., Cyberdyne Inc., Wandercraft SAS, Sarcos Corporation, Myomo, Inc., Hocoma AG, ATOUN Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Medical Robots Market Evolving Landscape
Closed-loop motor control architectures are fragmenting traditional rehabilitation hardware categories as software-defined torque modulation enables single platforms to address multiple neurological indications.
Soft exosuit designs employing fabric-based actuation and tendon-driven force transmission are fragmenting the dominance of rigid-frame powered exoskeletons in outpatient settings. Veterans Affairs medical centers and ambulatory surgery clinics in the United States are piloting these lighter systems for post-stroke patients with moderate mobility impairment. The technology is fragmenting procurement decisions by separating hardware acquisition from intensive facility infrastructure requirements.
The EU Medical Device Regulation's post-market clinical follow-up mandates are forcing manufacturers to embed real-world evidence collection into hardware firmware. German notified bodies are interpreting MDR Article 83 to require continuous gait metric transmission from deployed units. Rehabilitation centers in Bavaria and North Rhine-Westphalia are negotiating data-sharing agreements that transfer liability for surveillance compliance to hospital IT departments.
Hospital procurement committees are unbundling after-sales service contracts from initial hardware purchases to benchmark robotic therapy platforms against conventional equipment leasing models. German rehabilitation center networks are leading this shift, separating preventive maintenance from software subscription overlays. The pattern is most visible in university hospital systems where clinical engineering departments retain independent service organization capabilities.
Wearable Medical Robots Market Segmentation
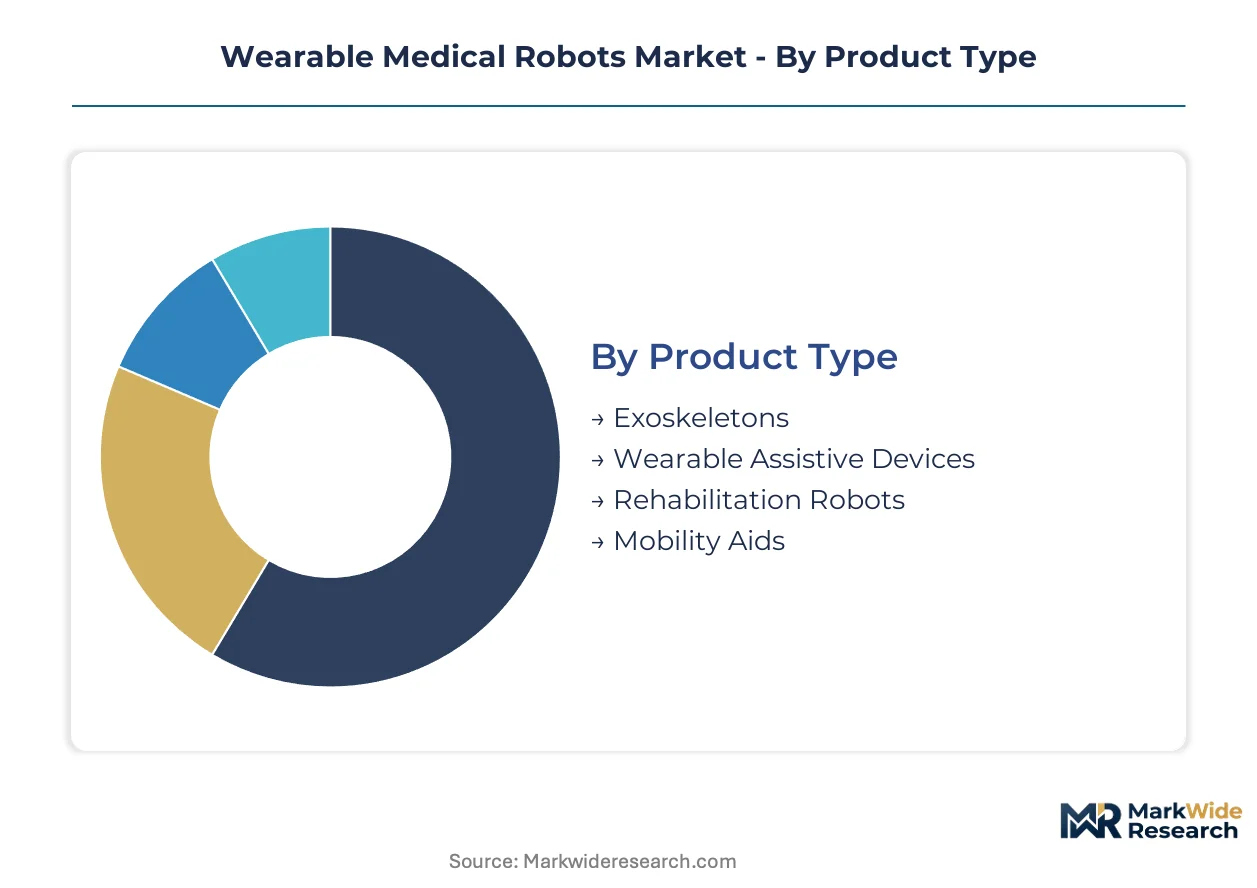
Wearable medical robots segment across four interlocking dimensions that determine procurement pathways, reimbursement eligibility, and technology substitution risk. Product architecture and actuation method define capital intensity, while end-user setting and clinical application shape regulatory clearance requirements and service contract structures.
Product Type:
Substitution pressure from low-cost manual therapy alternatives weighs heaviest on mobility aids and passive assistive devices, while powered exoskeletons defend position through demonstrated functional outcomes in spinal cord injury populations.
- Exoskeletons:Rigid-frame electromechanical systems with powered hip and knee actuation deliver torque outputs of 10-80 Newton-meters for gait restoration in stroke and spinal cord injury patients. German statutory health insurance reimbursement codes and FDA breakthrough device designations in the United States concentrate procurement demand at inpatient rehabilitation centers.
- Rehabilitation Robots:Stationary or body-worn platforms with closed-loop motor control standardize repetitive movement dosing for neurorehabilitation protocols. Sensor-driven gait trainers from Bavarian university hospitals to Japanese university medical centers capture long-term service contract revenue through software subscription overlays.
- Wearable Assistive Devices:Lightweight mechanical orthoses and unpowered support structures address osteoarthritis and joint instability with minimal capital expenditure.
- Mobility Aids:Traditional walkers, canes, and rollators remain the clinical default in emerging markets with constrained equipment budgets.
Exoskeletons anchor the volume base while rehabilitation robots gain share at the steepest rate through recurring software revenue and outcome-based contracting models.
Technology:
Cost tier stratification separates high-complexity active systems from commodity passive alternatives, with hybrid architectures capturing mid-market positioning through modular upgrade pathways.
- Active Systems:Battery-powered brushless DC motors with real-time force sensing and adaptive impedance control enable patient-initiated movement assistance. Veterans Affairs medical centers in the United States and university hospitals in Japan deploy these platforms for post-stroke gait training where therapist-to-patient ratios limit manual therapy capacity.
- Smart Wearables:Fabric-embedded IMU arrays and cloud-connected analytics platforms enable remote monitoring of rehabilitation progress outside institutional settings. Home-based prescription models in North American healthcare systems are expanding reimbursement pathways beyond traditional facility-based codes.
- Hybrid Systems:Combinations of powered actuation and passive mechanical elements reduce battery dependence while maintaining assistive torque for moderate mobility impairment.
- Passive Systems:Spring-loaded and elastic storage mechanisms provide unpowered movement assistance without electronic control systems or charging infrastructure.
Active systems dominate inpatient revenue pools while smart wearables expand most quickly into ambulatory and home-based care delivery models.
End User:
Customer type determines procurement authority, with healthcare providers controlling capital budgets and patients exercising growing influence through direct-to-consumer channels for lower-complexity devices.
- Healthcare Providers:Hospital systems and integrated delivery networks negotiate enterprise-wide robotics contracts with preventive maintenance and software update provisions. German rehabilitation center networks in Bavaria and North Rhine-Westphalia are unbundling service agreements from initial hardware purchases.
- Rehabilitation Centers:Dedicated neurorehabilitation facilities in the United States, Germany, and Japan concentrate exoskeleton utilization for spinal cord injury and stroke populations through dedicated therapy protocols.
- Patients:Direct-pay consumers access lightweight assistive devices and prescribed smart wearables through retail and specialty medical equipment channels.
- Research Institutions:University medical centers and clinical trial networks drive early adoption of investigational systems and generate evidence for regulatory submissions.
Healthcare providers commit the largest capital outlays while patients represent the emerging volume frontier as home-based prescription models mature.
Application:
Clinical indication maturity varies sharply, with rehabilitation commanding established reimbursement codes and surgical assistance requiring novel regulatory frameworks for intraoperative robotics.
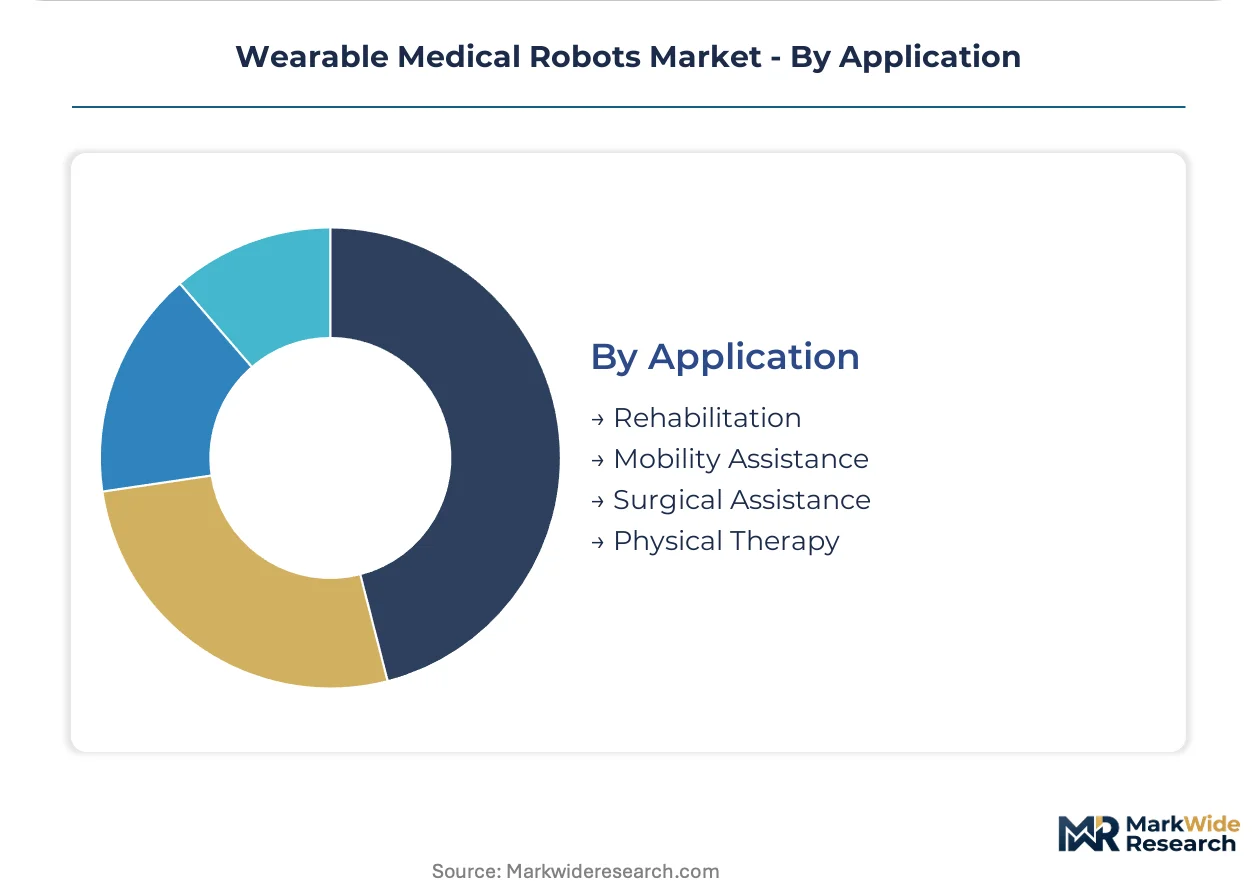
- Rehabilitation:Post-stroke and spinal cord injury gait training constitutes the dominant clinical use case with validated outcome metrics and payer recognition. FDA-cleared and PMDA-approved systems from Ekso Bionics and Cyberdyne anchor installed bases at major academic medical centers.
- Mobility Assistance:Daily living support for progressive neurological conditions addresses longer treatment horizons with lower per-session intensity requirements.
- Physical Therapy:Orthopedic recovery protocols for joint replacement and sports medicine applications compete with conventional therapist-directed exercise programs.
- Surgical Assistance:Intraoperative positioning and surgeon support functions remain exploratory with limited commercial deployment and undefined reimbursement pathways.
Rehabilitation generates the preponderance of current revenue while mobility assistance applications climb the fastest as aging demographics expand addressable patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations anchor the United States as the dominant geography, compressing clinical trial timelines for neurorehabilitation hardware developers while statutory health insurance recognition in Germany and fast-track PMDA pathways in Japan shape parallel commercialization corridors.
United States
Rehabilitation centers in California and Massachusetts scale procurement of powered exoskeletons for spinal cord injury populations. FDA 510(k) and breakthrough device pathways govern market access with accelerated review mechanisms for post-stroke gait training systems. Veterans Affairs medical centers in Palo Alto and Boston anchor installed bases for stroke and spinal cord applications.
Germany
Statutory health insurance reimbursement codes for robotic gait training create predictable revenue streams at inpatient rehabilitation facilities. BfArM enforces clinical evidence standards that favor established players with dedicated regulatory affairs teams. Bavarian and North Rhine-Westphalian rehabilitation center networks unbundle service agreements from initial hardware purchases.
Japan
University hospitals in Tokyo and Osaka deploy PMDA-approved hybrid assistive limb systems for neurorehabilitation protocols. METI coordinates priority review pathways that accelerate market entry for developers targeting spinal cord injury populations. Cyberdyne anchors the domestic market through hospital network partnerships.
United Kingdom
NHS England technology appraisal processes evaluate cost-effectiveness of robotic therapy against conventional physical therapy protocols. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR surveillance requirements. London and Manchester academic medical centers pilot soft exosuit designs for outpatient stroke rehabilitation.
China
NMPA Class II medical device registrations govern powered exoskeleton commercialization for rehabilitation applications. Provincial health commissions in Guangdong and Jiangsu pilot reimbursement schemes for robotic gait training at tertiary hospitals. Yangtze River Delta manufacturing clusters supply brushless DC motors and lithium-ion power packs to regional assemblers.
Wearable Medical Robots Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with FDA-cleared and PMDA-approved hardware manufacturers commanding premium positioning through regulatory moats. The vendor base stratifies across three archetypes: electromechanical framework developers with full-stack actuation capabilities, sensor-driven analytics platforms pursuing software subscription models, and fabric-based soft exosuit specialists targeting ambulatory settings. Competitive moves concentrate on unbundling service contracts from hardware sales and embedding real-world evidence collection into firmware to satisfy post-market surveillance mandates.
Within the integrated electromechanical tier, Ekso Bionics Holdings, Inc. and Cyberdyne Inc. occupy positions representing divergent geographic anchor points—California-based FDA clearance pathways versus Tokyo-centered PMDA fast-track positioning. Hocoma AG exemplifies the sensor-driven rehabilitation robot archetype with long-term service contract structures. Fourier Intelligence Co., Ltd. sits within the specialist tier as a China-based developer. These three named entities collectively illustrate how regulatory geography and product architecture determine competitive positioning across inpatient, outpatient, and home-based prescription models.
| Leading Market Players |
|---|
| Lifeward Ltd |
| Ekso Bionics Holdings, Inc. |
| Fourier Intelligence Co., Ltd. |
| Cyberdyne Inc. |
| Wandercraft SAS |
| Sarcos Corporation |
| Myomo, Inc. |
| Hocoma AG |
| ATOUN Inc. |
| Others |
Value Network & Pricing Analysis
Fourteen-week lead times for brushless DC motor assemblies from Yangtze River Delta suppliers concentrate procurement leverage with established manufacturers, compressing margin buffers for mid-tier exoskeleton developers while amplifying pricing power for vertically integrated incumbents with captive component sourcing.
Pricing Analysis
Price spreads between FDA-cleared and CE-marked systems span three-tier pricing structure across premium, standard, and economy levels, with FDA breakthrough device status commanding substantial brand premiums and German statutory reimbursement codes anchoring standard-tier contracts. Certification tier and after-sales service bundling drive differentiation, while cost compression in economy segments intensifies due to Chinese NMPA-registered alternatives. Rehabilitation centers exhibit highest price sensitivity; university hospital networks demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of lithium-ion power packs buffers against East Asian cell manufacturer allocation constraints, though just-in-time preferences dominate for IMU arrays and sensor modules. Component sourcing concentrates in China, South Korea, and Japan for battery cells, precision motors, and force sensors. Brushless DC actuators, high-discharge lithium cells, and cloud analytics infrastructure constitute critical dependencies. Single-source vulnerability for advanced torque-dense motors threatens production continuity. Distribution runs through hospital GPO contracts and direct rehabilitation center procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable medical robots are approaching a platform-economics inflection where software-defined torque modulation and cloud-connected gait analytics create winner-take-most dynamics, with interoperability across electronic medical record systems determining which hardware manufacturers capture recurring revenue pools.
For Market Incumbents: Consolidate regulatory affairs capabilities across FDA, PMDA, and BfArM jurisdictions to compress clearance timelines for next-generation soft exosuit platforms. Deepen backward integration into brushless DC motor production to offset East Asian supply concentration risks. Acquire sensor analytics specialists to embed real-world evidence collection directly into firmware architectures. For New Entrants and Emerging Players: Home-based prescription model gaps in North American reimbursement pathways offer immediate white-space entry, with pediatric neurorehabilitation representing the most penetrable clinical segment due to underserved therapy intensity requirements. Pursue direct-to-patient channels for lightweight smart wearables with embedded IMU arrays, leveraging remote monitoring capabilities to bypass entrenched hospital procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because software subscription overlays and outcome-based contracting models are displacing transactional hardware sales, with regulatory clearance moats determining sustainable margin capture. Target acquisition candidates with FDA breakthrough device designations or PMDA fast-track approvals already secured. Watch for inflection when CMS establishes distinct reimbursement codes for home-based robotic therapy, signaling payer acceptance of ambulatory prescription models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses clinical trial timelines for spinal cord injury hardware developers. |
| Software Companion Development | Cloud-connected gait analytics platforms enable remote monitoring and recurring subscription revenue. |
| Hospital System Partnership | Enterprise-wide contracts with German rehabilitation networks lock in long-term service relationships. |
| CE Marking Pathway | EU MDR compliance demonstrates post-market surveillance capabilities to notified bodies. |
| Reimbursement Strategy | Statutory health insurance recognition in Germany creates predictable procurement budgets. |
Research Methodology
Desk research of FDA 510(k) filings, PMDA approval databases, and German BfArM clinical evidence guidelines preceded structured interviews with rehabilitation center clinical directors, hospital biomedical engineers, GPO contracts managers, and regulatory affairs leads at exoskeleton manufacturers. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, and statutory health insurance claims records. Bottom-up unit economics triangulated against top-down healthcare expenditure models across the analysis window.
Variance decomposition separates volume drivers from price-mix effects throughout the forecast period. Segmentation dimensions span product architecture, actuation technology, end-user setting, and clinical application, with regional regulatory cluster as an additional modeled variable. CAGRs derive from installed base projections and replacement cycle assumptions, incorporating therapy session utilization rates and reimbursement code expansion trajectories as industry-specific inputs.
Underlying assumptions cover FDA breakthrough device designation velocity, PMDA fast-track pathway continuity, and lithium-ion supply chain stability, with deviation risk concentrated in EU MDR notified body backlog resolution and CMS reimbursement parity decisions. Revision becomes warranted when home-based prescription model penetration crosses institutional-setting parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pacemaker Devices Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Cervical Implants Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Artificial Retina Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Global Esophageal Catheters Market