
 Aerospace Galley Trolley Market | 2026-2036
Aerospace Galley Trolley Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Galley Trolley Market Outlook
Composite materials is broadening product economics across the aerospace galley trolley supply base. Jamco Corporation leverages its vertically integrated manufacturing footprint in Japan to control composite layup quality and reduce cycle times. Safran Cabin anchors European demand through its Toulouse engineering center, where it sustains R&D intensity on thermoplastic sandwich panels. Collins Aerospace competes on scale, operating multiple production lines that supply both narrowbody and widebody programs.
An aerospace galley trolley is a mobile storage and service cart designed for aircraft cabin operations, typically constructed from aluminum extrusions or fiber-reinforced polymer skins bonded to honeycomb cores, with dimensions governed by SAE ARP 1276 and ATLAS/ARINC 810 interface standards to ensure compatibility with galley lift mechanisms and latching systems. The product type dimension shows meal trolleys commanding the largest revenue pool due to their higher unit values and complex refrigeration integration, while composite material trolleys represent the fastest-expanding segment as airlines pursue weight reduction targets linked to fuel burn optimization. Standard full-size configurations remain the mature volume base, though compact half-size variants are gaining share on regional jet platforms where galley volume is constrained.
FAA flammability standards under 14 CFR 25.853 and EASA CS-25 certification requirements shape material selection and fire-blocking layer specifications, while ISO 7171 stability testing protocols influence wheelbase and caster designs for dynamic load conditions. The EU Green Deal's evolving cabin waste reduction targets are pressuring manufacturers to design trolleys compatible with reusable serviceware formats. Stakeholders must monitor how emerging airframe programs specify galley architecture, as trolley interface standards will determine retrofit compatibility and aftermarket revenue capture.
Market Dynamics
Composite material substitution is compressing traditional aluminum supply chains while tightening flammability certification requirements force simultaneous redesign of core structures and surface finishes.
Growth Catalysts
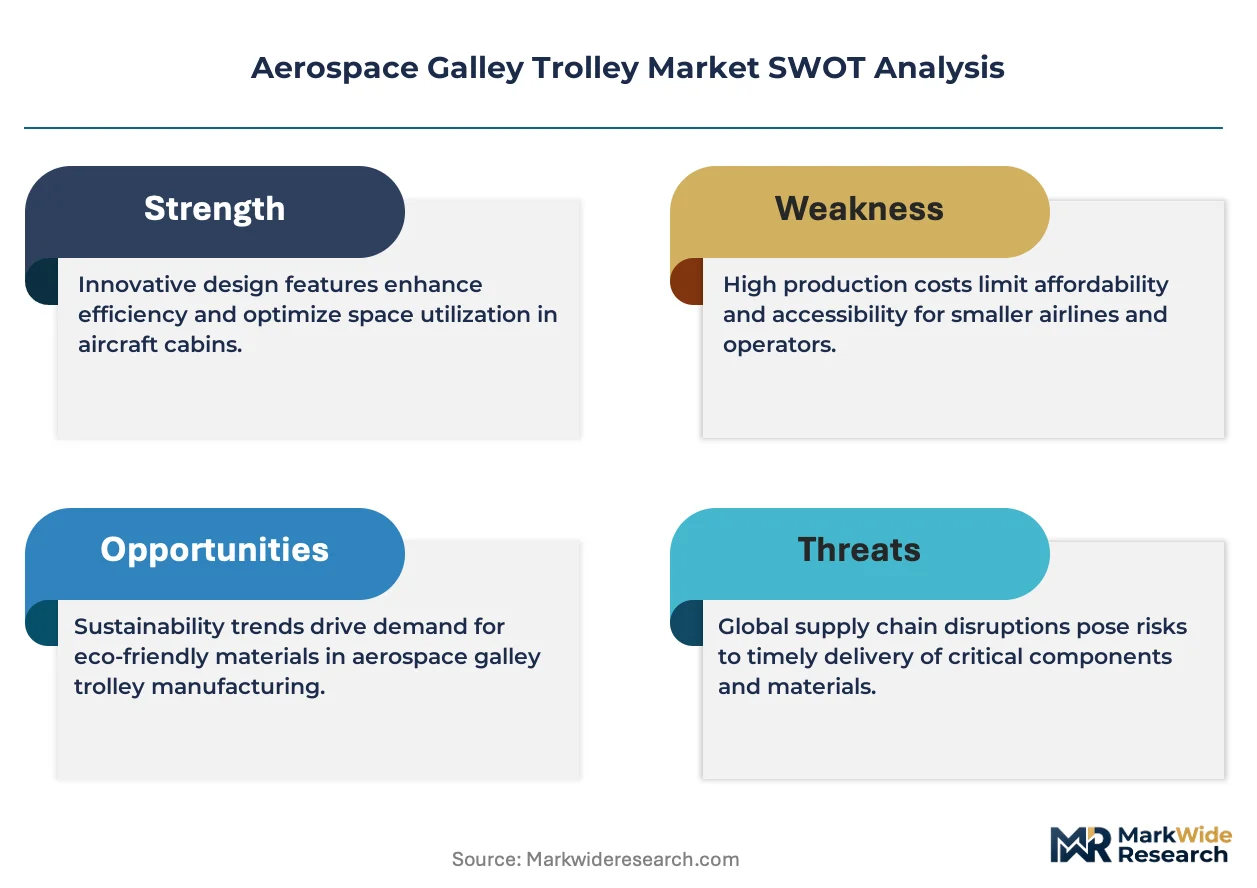
- FAA 14 CFR 25.853 evolution:Tighter flammability thresholds are accelerating R&D into fire-resistant thermoplastic cores, creating captive demand for certified suppliers.
- Asia-Pacific full-service carrier retrofit cycles:Fleet modernization programs in China and Japan are generating concentrated procurement volumes for next-generation galley systems.
- Thermoplastic sandwich panel technology:Weight reduction targets linked to fuel burn optimization are pulling composite architectures into narrowbody platforms previously served by aluminum.
Market Restraints
- Carbon fiber prepreg cost volatility:Aerospace-grade resin systems face input price instability that compresses margin structures for tier-two fabricators.
- Japanese manufacturing concentration:Vertically integrated producers in East Asia control critical composite layup capacity, creating geographic supply risk for European and North American airframers.
- SAE ARP 1276 interface lock-in:Legacy mechanical standards constrain dimensional innovation and prolong aluminum incumbent positions.
Strategic Opportunities
- China domestic airline procurement pipeline:Indigenous narrowbody programs are specifying galley architectures that favor local certification pathways.
- EU Green Deal cabin waste mandates:Reusable serviceware compatibility requirements are opening specification windows for modular trolley interior systems.
- Digital thread integration:Convergence of additive manufacturing with automated fiber placement is enabling lot-size-one customization for VIP and business jet configurations.
Industry Challenges
- Flammability testing bottleneck:EASA CS-25 certification timelines for novel core materials extend 18-24 months, delaying revenue recognition.
- Legacy ATLAS/ARINC 810 integration friction:New lightweight designs must maintain backward compatibility with installed galley lift mechanisms across mixed-generation fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Galley Trolley Market |
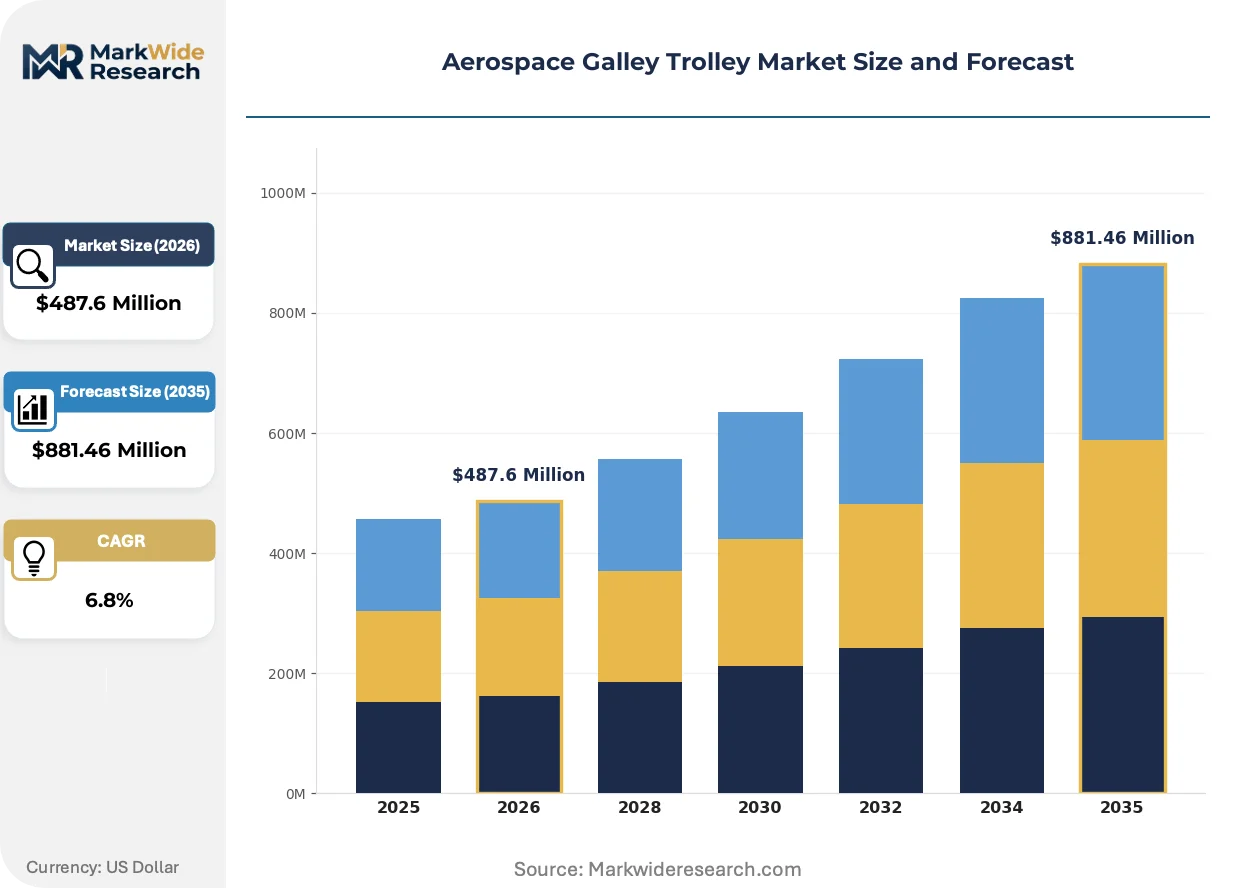
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Trolleys, Beverage Trolleys, Meal Trolleys, Service Trolleys Material: Aluminum, Stainless Steel, Plastic, Composite End User: Commercial Airlines, Cargo Airlines, Private Jet Operators, Defense Contractors Size: Full-Size, Half-Size, Custom Size, Compact |
| Companies Covered | Jamco Corporation, Geven S.p.A., Safran Cabin, Bucher Leichtbau, Collins Aerospace, Diehl Aviation, AIM Altitude, DKA Aerospace, Zodiac Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Galley Trolley Market Strategic Shifts
Thermoplastic composites are displacing thermoset architectures while regulatory pressure on cabin sustainability forces material transparency and end-of-life planning into design specifications.
Carbon fiber-reinforced PEEK sandwich panels is absorbing structural loads previously assigned to aluminum extrusions in meal trolley frames. Full-service carriers in the Middle East and Asia-Pacific are specifying these architectures for new widebody deliveries. The technology is absorbing engineering resources from legacy metal suppliers and compressing their aftermarket spare parts revenue streams.
REACH SVHC disclosure requirements are mandating material composition documentation down to the adhesive and coating level. European suppliers must now maintain substance passports for every laminate layer and fastener specification. Meal trolley refrigeration integration modules face the steepest compliance burden due to polymer content density.
Airline technical procurement teams are consolidating vendor relationships around integrated galley system providers rather than component-level sourcing. Specification authority is migrating from individual trolley attributes toward complete galley line fit and finish accountability. This pattern is most pronounced in Germany and France where flag carriers operate centralized fleet engineering centers.
Aerospace Galley Trolley Market Segmentation
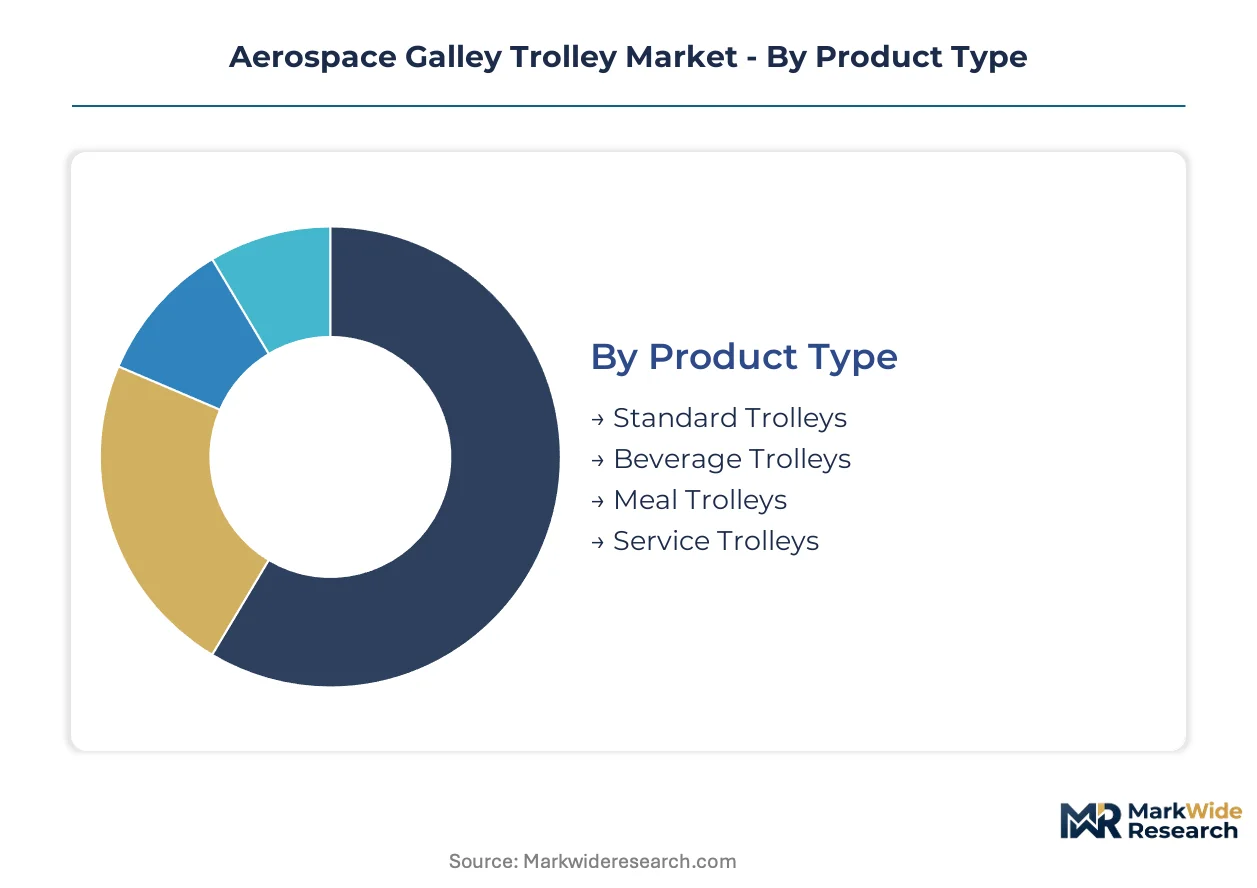
Segmentation in aerospace galley trolleys determines procurement specifications, certification pathways, and aftermarket revenue durability. Airlines configure fleet galley systems around trolley dimensions and material performance tiers, locking suppliers into long-term service contracts.
Product Type:
Technical specification drives airline procurement decisions, with refrigeration integration and payload capacity serving as primary selection criteria.
- Meal Trolleys:These units incorporate active refrigeration modules and multi-zone temperature control for hot and cold meal service. Full-service carriers in China and Japan specify these for widebody retrofit programs where catering complexity is highest.
- Beverage Trolleys:Optimized for liquid payload with reinforced casters and spill containment trays, these trolleys see concentrated demand from low-cost carriers operating high-frequency short-haul networks where turnaround speed dictates galley workflow.
- Standard Trolleys:General-purpose configurations serve mixed-fleet operators requiring interchangeability across aircraft types.
- Service Trolleys:Specialized units for amenity distribution and duty-free retail occupy premium cabin deployments on long-haul routes.
Mature deployment sits with Standard Trolleys. Newer deployment is concentrated in Meal Trolleys.
Material:
Weight reduction targets and flammability compliance are redefining material economics across the supply base.
- Composite:Carbon fiber-reinforced thermoplastic sandwich panels deliver 25-30% weight savings versus aluminum extrusions. EASA CS-25 certification pathways for these materials are accelerating adoption on next-generation narrowbody platforms.
- Aluminum:Legacy extrusion-based construction dominates installed fleet maintenance, with SAE ARP 1276 dimensional standards preserving incumbent supplier positions in aftermarket channels.
- Stainless Steel:Corrosion-resistant specifications persist in cargo airline applications where chemical exposure risk exceeds passenger cabin requirements.
- Plastic:Injection-molded polymer skins on honeycomb cores serve regional jet operators prioritizing acquisition cost over lifecycle durability.
Volume concentration remains with Aluminum. Composite architectures are climbing the fastest as fuel burn optimization tightens.
End User:
Procurement authority varies sharply across customer types, with fleet scale and specification complexity determining vendor access.
- Commercial Airlines:Full-service and low-cost carriers generate the largest procurement volumes, with technical teams consolidating around integrated galley system providers rather than component-level sourcing.
- Private Jet Operators:VIP configurations demand lot-size-one customization, with additive manufacturing enabling bespoke interior finishes and branding integration.
- Cargo Airlines:Durability specifications prioritize structural resilience over passenger-facing aesthetics, with stainless steel retention in meal service applications for flight crew.
- Defense Contractors:Military airframe programs impose electromagnetic interference shielding and crashworthiness requirements that exceed civilian certification baselines.
Procurement scale concentrates with Commercial Airlines. Specification complexity is expanding most quickly in Private Jet Operators.
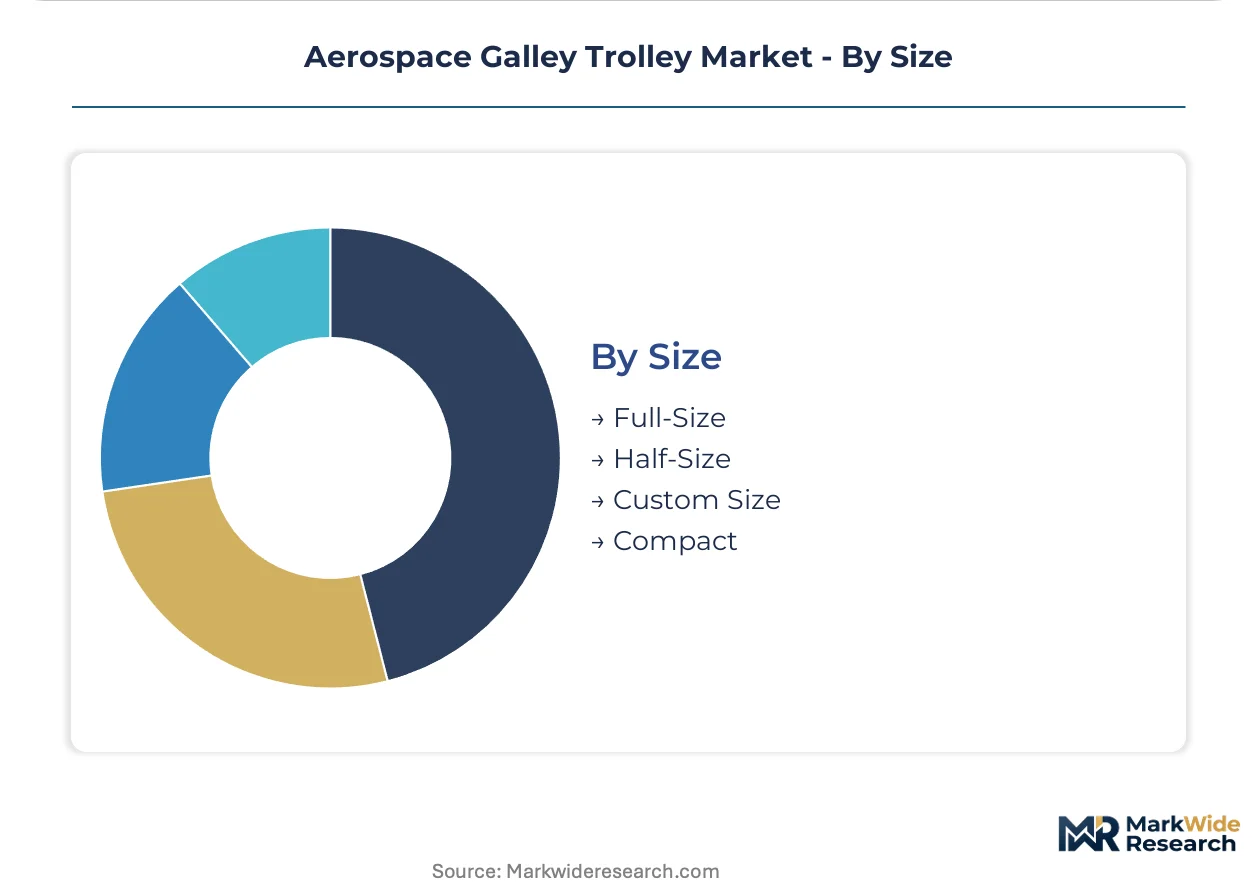
Size:
Galley volume constraints on modern airframes are fragmenting dimensional standards beyond legacy full-size dominance.
- Full-Size:ATLAS/ARINC 810 compliant dimensions remain the reference standard for widebody galleys, with backward compatibility requirements preserving specification authority for incumbent manufacturers.
- Half-Size:Regional jet platforms with constrained cabin volumes are driving adoption of compact variants, particularly on indigenous Chinese narrowbody programs where galley architecture is specified early in airframe development.
- Compact:Ultra-short-haul operators specify these for single-aisle aircraft where passenger count and service frequency compress galley storage requirements.
- Custom Size:VIP and business jet configurations bypass standardized interfaces, requiring bespoke engineering for each airframe modification.
Installed base concentration sits with Full-Size. Half-Size variants are gaining share fastest on regional platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement authority for next-generation narrowbody programs, while Japan and the United States anchor composite manufacturing capabilities. Fleet retrofit cycles in Asia-Pacific generate concentrated demand volumes. European regulatory pressure on cabin sustainability is reshaping material specification pathways.
China
Indigenous narrowbody programs at COMAC are specifying galley architectures that favor local certification pathways. MIIT and CAAC coordinate airworthiness standards for cabin interior systems. Shanghai and Tianjin host engineering centers where domestic suppliers integrate composite trolley designs into C919 and ARJ21 production lines.
United States
FAA 14 CFR 25.853 flammability thresholds are accelerating R&D into fire-resistant thermoplastic cores for meal trolley refrigeration modules. The FAA's Wichita Aircraft Certification Office processes novel material petitions alongside Seattle and Los Angeles engineering hubs. Boeing's Charleston and Everett facilities coordinate galley specification authority with tier-one integrators.
Japan
METI subsidizes lightweight composite development through the Society of Japanese Aerospace Companies. Jamco Corporation's vertically integrated manufacturing footprint in Yokohama controls composite layup quality for narrowbody retrofit programs. Osaka and Nagoya clusters concentrate precision machining capacity for ATLAS/ARINC 810 interface components.
Germany
EU Green Deal cabin waste mandates are pressuring manufacturers to design trolleys compatible with reusable serviceware formats. EASA CS-25 certification timelines for novel core materials extend through the Cologne headquarters. Hamburg and Munich engineering centers consolidate specification authority for Lufthansa Group fleet standardization.
France
REACH SVHC disclosure requirements mandate material composition documentation down to the adhesive level for laminate layers. EASA coordinates with ANSM on cabin interior substance safety assessments. Toulouse anchors European demand through Safran Cabin's engineering center, where R&D intensity focuses on thermoplastic sandwich panel architectures.
Aerospace Galley Trolley Market Competitive Environment
Capacity expansion dominates the current landscape as composite material substitution compresses traditional aluminum supply chains. The vendor base stratifies across three tiers: integrated airframe system providers, specialized trolley fabricators, and regional maintenance suppliers. Two strategic archetypes have emerged—vertically integrated composite specialists and scale-driven multi-product aerospace conglomerates. Competitive intensity concentrates on M&A activity targeting certification capabilities and geographic expansion into China's domestic airline procurement pipeline.
Among Japanese and European integrated manufacturers, Jamco Corporation, Safran Cabin, and Collins Aerospace occupy positions that exemplify the scale-driven archetype. Jamco represents vertically integrated composite control, while Safran Cabin anchors European specification authority. Collins Aerospace sits within the multi-platform supply tier, serving both narrowbody and widebody programs through distributed production capacity. These three entities illustrate how geographic manufacturing concentration and certification breadth determine competitive positioning in aftermarket and OEM channels.
| Leading Market Players |
|---|
| Jamco Corporation |
| Geven S.p.A. |
| Safran Cabin |
| Bucher Leichtbau |
| Collins Aerospace |
| Diehl Aviation |
| AIM Altitude |
| DKA Aerospace |
| Zodiac Aerospace |
| Others |
Value Chain & Pricing Dynamics
Family-owned Japanese composite specialists anchor tier-two supply capacity, concentrating pricing power among vertically integrated incumbents while forcing European and North American buyers into premium sourcing positions. This ownership pattern tightens margin structures for aluminum legacy suppliers facing carbon fiber substitution.
Pricing Analysis
Volume concentration in aluminum aftermarket spares competes against margin-rich composite OEM positions. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified thermoplastic configurations from FAA-compliant aluminum variants and uncertified plastic alternatives. Pricing pressure stems from carbon fiber prepreg cost volatility compressing tier-two fabricator margins. Low-cost carriers operating high-frequency short-haul networks exhibit highest price sensitivity, while Middle East full-service carriers prioritize weight reduction over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese vertically integrated manufacturers controlling aerospace-grade composite layup capacity. Production gravity centers on Japan, France, and the United States, with raw material dependencies spanning carbon fiber prepreg, fire-resistant thermoplastic cores, and honeycomb aluminum cores. Supply chain risk manifests as tariff exposure on aerospace-grade resin systems crossing Pacific trade lanes. Distribution runs through airframe OEM specification channels and airline fleet engineering centers rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite layup certification bottlenecks prop pricing discipline by capping qualified supplier expansion. EASA CS-25 timelines extending 18-24 months for novel core materials enforce supply scarcity.
For Market Incumbents: Extend composite capacity in East Asian manufacturing clusters to capture narrowbody retrofit cycles. Lock in multi-year offtake agreements with Chinese domestic carriers before indigenous suppliers achieve CAAC certification parity. Defend aftermarket revenue by controlling ATLAS/ARINC 810 interface component production. For New Entrants and Emerging Players: Regional jet operators specifying half-size compact variants face constrained incumbent attention. Target this underserved buyer archetype through modular trolley interior systems compatible with reusable serviceware formats. Enter via EU Green Deal compliance specialization, leveraging REACH SVHC documentation capabilities as differentiation against established aluminum suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor European aluminum legacy suppliers facing composite displacement in Germany and France. Long-term viability hinges on certification asset ownership rather than manufacturing scale. Watch EASA acceleration of thermoplastic sandwich panel approval timelines as inflection signal for composite incumbent revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Manufacturing Scale-Up | Captures fuel burn optimization mandates from Asia-Pacific full-service carriers. |
| Backward Integration into Prepreg Supply | Insulates margin structures from carbon fiber resin price volatility. |
| EASA CS-25 Certification Investment | Unlocks European narrowbody procurement blocked by 18-24 month approval timelines. |
| Joint Venture with Chinese Domestic Suppliers | Secures position in COMAC C919 and ARJ21 galley specification pipelines. |
| Modular Interior System Development | Aligns trolley designs with EU Green Deal reusable serviceware mandates. |
Study Parameters
Multi-period observation of fleet retrofit announcement flows, composite material certification filings, and airline galley procurement tenders anchored the trend analysis, supplemented by interviews with airline fleet engineering directors, aircraft interior procurement managers, EASA certification specialists, composite manufacturing engineers, and aftermarket service heads. Secondary validation drew from FAA 14 CFR 25.853 regulatory updates, EASA CS-25 certification bulletins, airline annual reports, and customs trade data on aerospace-grade carbon fiber imports. Bottom-up segment sizing triangulated against top-down fleet expansion projections from airframe OEM delivery schedules.
Segment-weighting across product type, material architecture, end-user category, and dimensional configuration drove the analytical framework. CAGRs were derived from installed base replacement cycles, new aircraft delivery pipelines, and material substitution elasticity models. Forecast inputs incorporated flammability standard evolution timelines and indigenous narrowbody program production ramps.
Revisions become necessary when EASA accelerates thermoplastic core certification timelines, when COMAC achieves CAAC-EASA reciprocal recognition, or when carbon fiber prepreg supply disruptions exceed six-month duration. Forecasts reflect documented assumptions on fleet renewal rates and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market