
 NATO Defense Market | 2026-2036
NATO Defense Market Size, Share, and Industry Trends Forecast 2026-2036
NATO Defense Market Foresight
Market Context with Strategic Players
Buyer concentration among NATO military forces is expanding as member states consolidate procurement through joint acquisition frameworks and pooled defense initiatives. Lockheed Martin Corporation leverages its integrated air and missile defense portfolio to anchor major transatlantic programs. BAE Systems sustains its position through deep specialization in naval systems and electronic warfare. Rheinmetall competes aggressively in land systems and ammunition, extending its manufacturing footprint across multiple member countries.
Technical Definition and Structural Segments
NATO Defense encompasses the collective military capabilities, equipment, and services procured by the North Atlantic Treaty Organization's thirty-two member states to fulfill Article 5 mutual defense obligations, spanning kinetic systems, cyber infrastructure, and integrated command networks operating across classified and coalition interoperability standards. Surveillance Systems and Communication Equipment represent mature, high-margin segments where long-term service contracts sustain vendor profitability. Cybersecurity and AI Systems constitute the fastest-expanding technology categories, driven by NATO's recognition of cognitive domains as operational theaters alongside traditional physical domains. Ammunition and Vehicles retain substantial volume importance, though pricing pressures and supply chain constraints compress margins relative to software-defined capabilities.
Regulatory Framework and Forward Outlook
NATO Standardization Office protocols, EU defense procurement directives, and member-specific export control regimes such as the U.S. International Traffic in Arms Regulations collectively shape product specifications and market access conditions for defense contractors. The EU AI Act introduces mandatory risk classification for autonomous military systems, forcing vendors to redesign development pipelines for algorithmic accountability. Stakeholders must monitor how NATO's forthcoming capability targets for collective defense spending thresholds reshape national procurement priorities and vendor eligibility across the alliance.
Market Dynamics
Defense procurement across NATO member states is consolidating through joint acquisition frameworks, compressing vendor margins while elevating interoperability requirements as the dominant purchasing criterion.
Growth Catalysts
- EU AI Act Risk Classification:Mandatory algorithmic accountability standards for autonomous military systems are accelerating procurement of certified AI-enabled surveillance platforms across frontline member states.
- Poland Accelerated Modernization:Frontline positioning against eastern flank threats is driving sustained capital allocation toward integrated air defense and armored vehicle replacement programs.
- Interoperability Mandates:NATO Standardization Office protocols for secure communication networks are obligating member states to upgrade legacy command infrastructure to coalition-compatible standards.
Market Restraints
- Tungsten Supply Concentration:Ammunition manufacturing faces structural input cost volatility as China controls approximately eighty percent of global tungsten refining capacity.
- ITAR Export Friction:U.S. International Traffic in Arms Regulations create licensing delays and technology transfer restrictions that fragment transatlantic supply chains for sensitive components.
- Skilled Workforce Scarcity:Semiconductor packaging and advanced composite fabrication require specialized technicians that European defense industrial bases cannot currently source at scale.
Strategic Opportunities
- Polish Industrial Partnerships:Warsaw's localization requirements for foreign military sales create captive manufacturing opportunities for land systems and ammunition production within the country.
- Quantum-Resistant Cryptography:Convergence of post-quantum algorithms with existing tactical radio networks offers first-mover advantage for vendors achieving NATO certification.
- Joint Acquisition Frameworks:NATO Support and Procurement Agency pooled initiatives reduce customer acquisition costs and extend contract visibility for qualified suppliers.
Industry Challenges
- Security Clearance Bottlenecks:Personnel vetting timelines for classified program access stretch eighteen to thirty-six months in Germany and the United States, constraining engineering deployment.
- Legacy System Integration:Coalition interoperability mandates force vendors to bridge thirty-year-old command architectures with modern IP-based networks, multiplying integration complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NATO Defense Market |
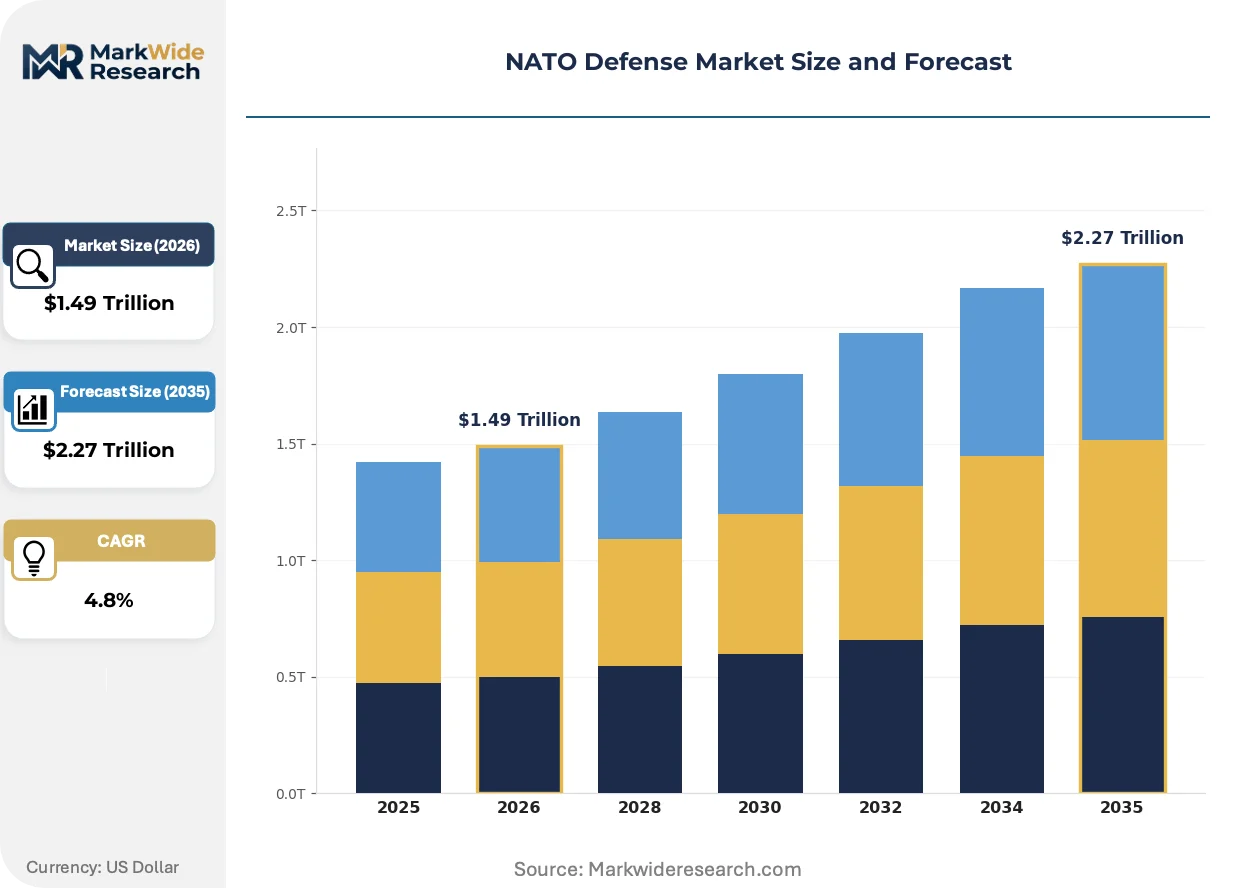
| Market Size in 2026 | $1.49 Trillion |
| Market Size in 2035 | $2.27 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ammunition, Vehicles, Surveillance Systems, Communication Equipment Technology: Cybersecurity, AI Systems, Robotics, Sensor Technology End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions Deployment: Onshore, Offshore, Joint Operations, Tactical Missions |
| Companies Covered | BAE Systems, Leonardo, Lockheed Martin Corporation, Thales, Airbus, Northrop Grumman Corporation, Rheinmetall, Saab, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NATO Defense Market Shifts & Advancements
Software-defined capabilities are displacing hardware-centric procurement models across NATO defense programs, compressing development cycles and elevating cybersecurity to a primary design specification rather than aftermarket consideration.
Autonomous surveillance platforms is expanding into contested electromagnetic environments where manned reconnaissance faces unacceptable attrition risk. Baltic member states and Poland are fielding uncrewed aerial systems at brigade level and below, creating demand for edge-processed intelligence and reduced-bandwidth datalinks. This capability shift is compressing procurement timelines for traditional manned surveillance aircraft and redirecting capital toward modular, rapidly upgradeable sensor payloads.
The EU AI Act's mandatory risk classification for military autonomous systems is forcing vendors to restructure development pipelines around documented algorithmic traceability and human oversight protocols. High-risk system categories now require conformity assessments before member state procurement authorization. German and French defense ministries are responding by embedding ethics review boards within acquisition offices, adding six to twelve months to program initiation.
Consolidated through-life support contracts are displacing transactional spare parts purchasing across major NATO procurement programs. Denmark, Norway, and the Netherlands now structure fighter and maritime platform acquisitions around availability-based payment models rather than capital equipment transfers. This pattern is most visible in Nordic defense cooperation frameworks, where pooled fleet management reduces per-unit sustainment costs through scale economics and shared technical labor pools.
NATO Defense Market Segmentation
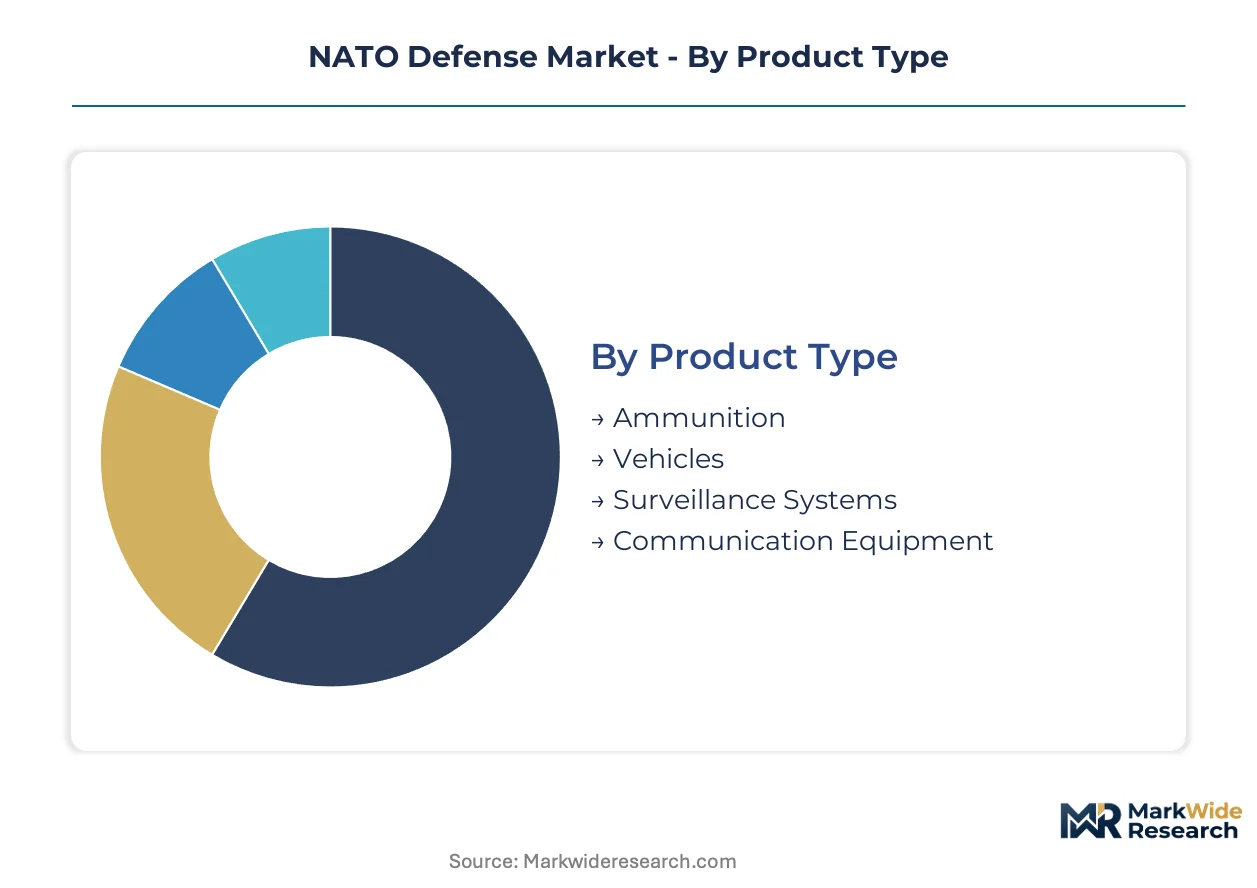
NATO defense procurement operates through distinct capability categories where upgrade cycles and interoperability mandates reshape vendor priorities. Understanding how spending distributes across product types, technologies, end users, and deployment modes reveals where procurement consolidation and capability gaps intersect.
Product Type:
Replacement timelines for legacy systems vary dramatically by platform category, with ammunition and vehicles cycling faster than integrated surveillance networks.
- Surveillance Systems:Integrated sensor platforms combining electro-optical, radar, and signals intelligence capabilities operate across classified datalink architectures. Polish and Baltic military forces are procuring uncrewed aerial systems at brigade level to fill gaps left by manned reconnaissance attrition risk.
- Communication Equipment:Secure tactical radios and satellite terminals engineered to NATO Standardization Office interoperability protocols bridge legacy analog infrastructure with modern IP-based command networks. German and French procurement offices now require post-quantum cryptographic certification for new radio acquisitions.
- Ammunition:Precision-guided munitions and artillery shells face tungsten supply constraints from concentrated Chinese refining capacity.
- Vehicles:Armored platforms and logistics trucks are modernizing across frontline states with embedded electronic warfare protection.
Volume placements concentrate in Ammunition and Vehicles; the faster expansion belongs to Surveillance Systems.
Technology:
Capability investments stratify sharply between proven defensive technologies and emerging autonomous systems where regulatory certification remains unsettled.
- AI Systems:Machine learning algorithms for target recognition, predictive maintenance, and logistics optimization must now document algorithmic traceability under EU AI Act high-risk system classifications. German defense ministry ethics review boards are adding six to twelve months to program initiation for autonomous targeting systems.
- Cybersecurity:Network defense tools, endpoint protection, and secure cloud architectures for classified coalition data sharing represent the procurement category with most urgent member state demand acceleration.
- Robotics:Ground-based uncrewed platforms for explosive ordnance disposal and logistics transport are fielding in Poland and Romania.
- Sensor Technology:Multi-spectral detection arrays and electronic support measures are integrating into next-generation fighter and maritime platforms.
Procurement volume clusters in Cybersecurity; AI Systems are climbing the fastest as regulatory frameworks mature.
End User:
Buyer concentration patterns diverge between direct military operators and the contractor ecosystem that designs, integrates, and sustains complex platforms.
- Military Forces:National armies, navies, and air forces across NATO's thirty-two member states consolidate procurement through joint acquisition frameworks like the NATO Support and Procurement Agency. Polish military modernization programs are driving sustained capital allocation toward integrated air defense and armored vehicle replacement.
- Defense Contractors:Prime systems integrators and subsystem suppliers compete for position in transatlantic supply chains fragmented by U.S. ITAR export licensing delays.
- Government Agencies:National defense ministries and intelligence services procure specialized capabilities outside standard military acquisition channels.
- Research Institutions:University-affiliated laboratories and government research centers develop prototype systems under NATO Science and Technology Organization funding.
Contract flow concentrates through Military Forces; Defense Contractors are gaining share fastest as through-life support contracts displace transactional purchasing.
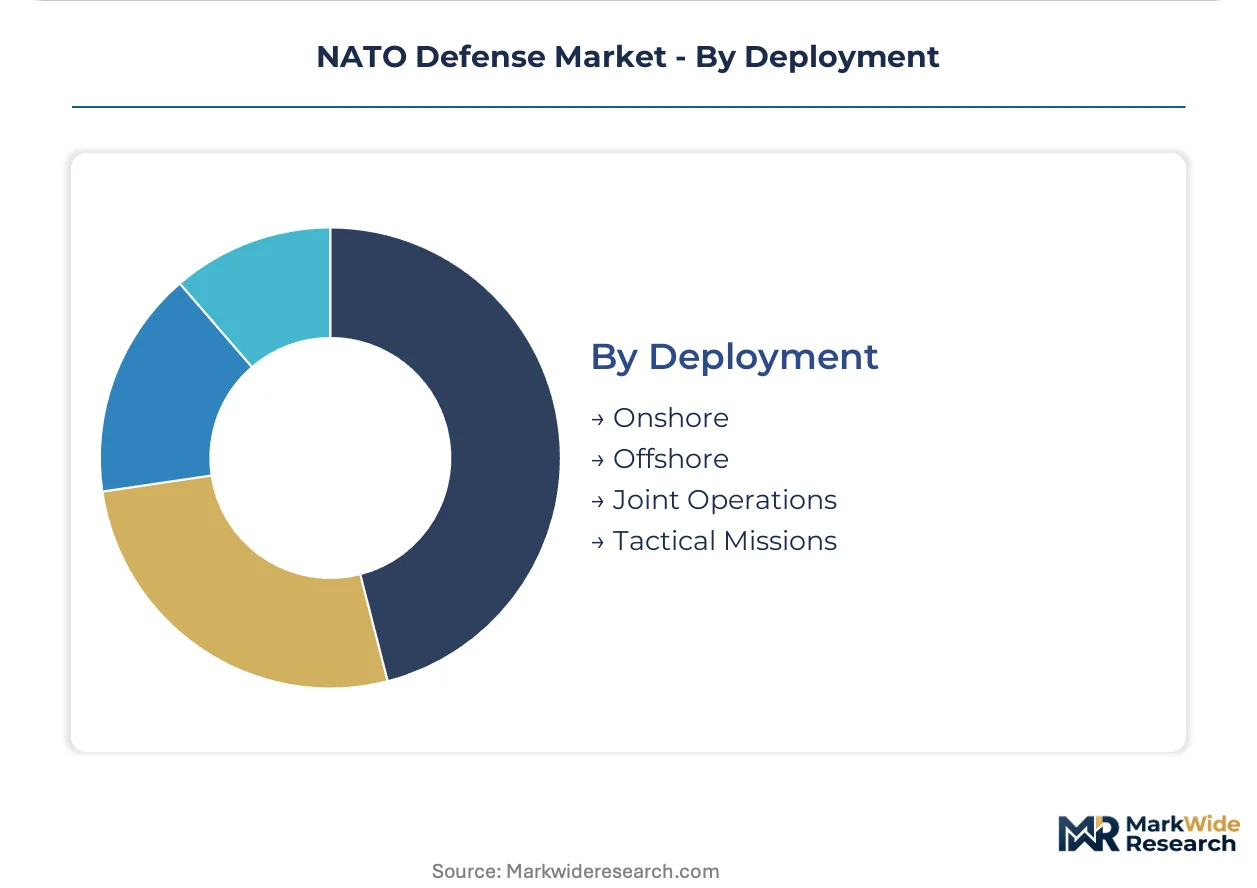
Deployment:
Operational context shapes capability specifications, with frontline positioning against eastern flank threats driving distinct procurement priorities from rear-area support missions.
- Tactical Missions:Short-range, rapidly deployable systems for battalion-level operations in contested electromagnetic environments prioritize reduced-bandwidth datalinks and edge-processed intelligence. Baltic member states field these capabilities for territorial defense scenarios.
- Joint Operations:Coalition-compatible command networks and interoperable logistics systems enable combined NATO task force deployments. Denmark, Norway, and the Netherlands structure fighter and maritime acquisitions around pooled fleet management and availability-based payment models.
- Onshore:Fixed-site infrastructure including air defense batteries and cyber operations centers concentrates in Germany and Poland.
- Offshore:Maritime patrol and submarine capabilities sustain NATO's northern and Mediterranean flanks.
Capability investment concentrates in Joint Operations; Tactical Missions are expanding most quickly as frontline states accelerate brigade-level modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten refining capacity concentrates in China, creating supply vulnerability for NATO ammunition manufacturers dependent on penetrator materials. Member state procurement patterns diverge sharply between frontline eastern flank investments and western European sustainment priorities.
United States
Integrated air and missile defense programs absorb the largest capital allocation, driven by Indo-Pacific rebalancing and European reassurance missions. ITAR licensing requirements under State Department jurisdiction fragment technology transfer to allied contractors. The Pentagon's Virginia-class submarine production in Connecticut and F-35 final assembly in Texas anchor transatlantic supply chains.
Germany
Zeitenwende fiscal commitments are redirecting procurement toward heavy ground combat systems and ammunition stockpiles depleted by Ukrainian support. KBA vehicle certification standards and Bundestag defense committee oversight extend program timelines. Rheinmetall's expanded manufacturing in Lower Saxony and Thuringia is capturing localization requirements for armored vehicle replacement.
Poland
Brigade-level modernization against eastern flank threats is driving sustained orders for integrated air defense and main battle tanks. National procurement law mandates minimum domestic content thresholds for foreign military sales. The Radom and Poznań industrial clusters are absorbing technology transfer agreements for licensed production of South Korean and American platforms.
United Kingdom
AUKUS submarine commitments are diverting naval procurement resources from NATO European theater priorities. Ministry of Defence export licensing under the Strategic Export Controls regime maintains transatlantic interoperability standards. BAE Systems' Barrow-in-Furness shipyard and Warton aerospace facilities sustain nuclear and combat air industrial capabilities.
France
Autonomous systems development prioritizes algorithmic sovereignty under EU AI Act high-risk classification frameworks. DGA procurement directives emphasize European defense industrial base consolidation over transatlantic sourcing. Thales and Safran concentration in Île-de-France and Occitanie anchors sensor and electronic warfare supply chains.
NATO Defense Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue quantum-resistant cryptography and AI-enabled surveillance niches. The vendor base stratifies between transatlantic primes with NATO Standardization Office certification and mid-tier specialists in ammunition and vehicle subsystems. Three archetypes dominate: integrated platform integrators, component specialists with manufacturing depth across multiple member states, and software-defined capability providers. Competitive moves center on Polish industrial partnerships for captive manufacturing and joint acquisition framework positioning through the NATO Support and Procurement Agency.
Within the integrated platform tier, Lockheed Martin Corporation and BAE Systems exemplify transatlantic primes anchoring major air and maritime programs. Rheinmetall occupies a position bridging land systems specialization with ammunition manufacturing scale across German and Polish facilities. These three entities represent distinct geographic and capability anchoring strategies within alliance procurement consolidation.
| Leading Market Players |
|---|
| BAE Systems |
| Leonardo |
| Lockheed Martin Corporation |
| Thales |
| Airbus |
| Northrop Grumman Corporation |
| Rheinmetall |
| Saab |
| General Dynamics Corporation |
| Others |
Supply & Pricing Matrix
Tungsten penetrator materials flow from Chinese refining capacity through ammunition pricing tiers, with raw material concentration compressing margins at the economy end while certified alloy grades sustain premium positioning for precision-guided munitions.
Pricing Analysis
Warranty bundling separates availability-based payment models from transactional spare parts purchasing, with Nordic pooled fleet management and Polish localization requirements driving divergent structures. Three-tier pricing stratifies across NATO Standardization Office certified systems, member-state qualified alternatives, and non-certified economy options. Price differentiation hinges on interoperability certification level and through-life service bundling. Cost compression in ammunition manufacturing is intensifying because tungsten supply volatility feeds directly into bill-of-materials exposure. Tier 2 member states with joint acquisition framework access exhibit lowest price sensitivity; standalone national procurement offices face highest budget constraint pressure.
Supply Chain Analysis
Dual-sourcing mandates for semiconductor packaging and advanced composite fabrication force prime contractors to qualify redundant suppliers across German and Polish industrial clusters. Upstream concentration centers on Chinese tungsten refining, South Korean memory components, and Taiwanese advanced packaging. Raw material dependencies span tungsten ore, gallium nitride substrates, and carbon fiber prepregs. Single-source vulnerability in Chinese rare earth processing creates tariff-agnostic supply risk. Distribution runs through NATO Support and Procurement Agency pooled frameworks and bilateral foreign military sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NATO defense market sits in a software-defined capability transition, with AI-enabled surveillance platforms displacing hardware-centric procurement models and compressing traditional platform upgrade cycles.
For Market Incumbents:Acquire quantum-resistant cryptography certification assets to anchor post-quantum radio network positioning before NATO Standardization Office protocols finalize. Backward integration into Polish manufacturing clusters captures localization requirements for South Korean and American platform licenses. Certification investment in EU AI Act high-risk system conformity assessments defends against emerging software-defined entrants. Channel control through NATO Support and Procurement Agency framework pre-qualification sustains contract visibility against mid-tier specialists.
For New Entrants and Emerging Players:Baltic brigade-level uncrewed aerial system operators represent the most penetrable buyer archetype, with reduced-bandwidth datalink and edge-processing intelligence gaps unaddressed by transatlantic primes. Polish industrial partnerships for ammunition component manufacturing offer captive production entry without prime contractor status. Quantum-resistant cryptography modules for legacy radio retrofit present white-space opportunity ahead of NATO certification deadlines. Go-to-market through national defense ministry ethics review board pre-engagement accelerates program initiation timelines.
For Investors and Strategic Acquirers:Distressed-cycle entries favor mid-tier ammunition specialists with German KBA certification and Polish manufacturing footprint, as tungsten cost compression forces consolidation among non-integrated producers. Long-term viability over the coming decade rests on software-defined capability pivots and joint acquisition framework positioning. Watch NATO collective defense spending threshold announcements as inflection signal for national procurement acceleration. Deviation in Chinese export license policy for tungsten compounds would shift ammunition manufacturing economics materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Polish Manufacturing Localization | Captures Warsaw's domestic content thresholds for South Korean tank and artillery licenses. |
| Post-Quantum Cryptography Certification | Locks in first-mover advantage for NATO tactical radio network upgrade cycles. |
| EU AI Act Conformity Assessment | Accelerates German and French defense ministry procurement authorization for autonomous systems. |
| NATO Support and Procurement Agency Pre-Qualification | Reduces customer acquisition costs and extends contract visibility across pooled initiatives. |
| Through-Life Support Contract Transition | Mirrors Nordic availability-based payment models and displaces transactional spare parts purchasing. |
Research Methodology
Document review covered NATO Standardization Office protocol filings, EU defense procurement directives, and member state budget appropriations, complemented by interviews with defense procurement officers, prime contractor program managers, subsystem engineering leads, and national ethics review board administrators. Secondary validation drew from U.S. Defense Department budget justification materials, German Bundestag defense committee records, Polish Ministry of National Defence acquisition announcements, and customs trade data for tungsten and ammunition components. Bottom-up project pipeline analysis and top-down member state spending allocation triangulation anchored market sizing.
Cross-referencing historical procurement cycle patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology maturity tier, end user procurement channel, and deployment operational context. CAGRs were derived from weighted member state spending trajectories and capability target convergence. Industry-specific forecast inputs encompassed Polish brigade modernization timelines and EU AI Act implementation phase transitions.
Revisions become necessary when NATO collective defense spending thresholds shift, Chinese tungsten export controls materialize, or EU AI Act high-risk system classifications expand. Forecasts reflect documented assumptions about interoperability mandate adoption rates and joint acquisition framework participation. Deviation in German Zeitenwende fiscal commitment sustainability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Tent and Shelter Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market