
 Military Aircraft Modernization and Retrofit Market | 2026-2036
Military Aircraft Modernization and Retrofit Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aircraft Modernization and Retrofit Market Intelligence
Software-defined mission systems is expanding as the primary service layer in military aircraft modernization, shifting revenue from hardware replacement to recurring capability upgrades. Lockheed Martin Corporation leverages its digital thread infrastructure across F-16 and F-22 sustainment programs. BAE Systems plc anchors European fighter upgrade activity through its electronic warfare and flight control retrofit portfolio. Elbit Systems Ltd. specializes in helmet-mounted cueing systems and large-area displays that compete on integration speed with legacy analog architectures.
Military aircraft modernization and retrofit encompasses the engineering, fabrication, and installation of upgraded subsystems into in-service airframes to extend operational relevance against evolving threat environments. The process typically involves airframe structural life extension, wiring harness replacement, and power and cooling capacity increases to support higher-draw digital avionics. Avionics refresh programs generate the deepest margin pools among technology segments because software reprogrammability creates recurring upgrade revenue. Combat applications attract the most concentrated investment among end-use categories, while modular enhancements represent the fastest-growing deployment mode as militaries seek to minimize aircraft downtime.
The US FAA and DoD open systems architecture mandates shape product standards by requiring interoperable, non-proprietary interfaces in new upgrade programs. EASA's military certification liaison and NATO's airworthiness standards further define market access conditions for European retrofit providers. Stakeholders must monitor how software supply chain security regulations reshape vendor qualification requirements for mission-critical avionics.
Market Dynamics
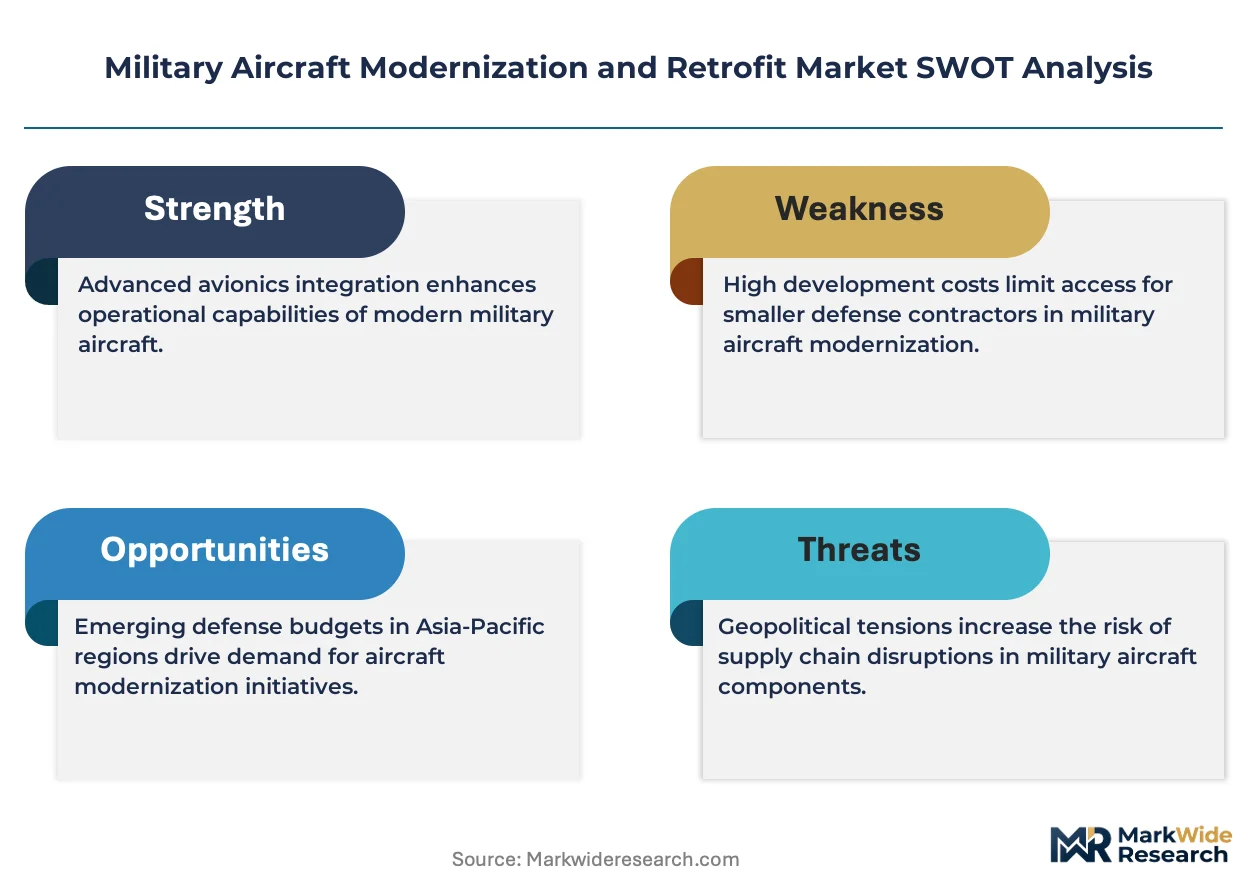
Open systems architecture mandates from the US Department of Defense are compressing proprietary avionics upgrade cycles into modular, competitive-bid pathways. This structural shift dismantles decades of vendor lock-in across fourth-generation fighter fleets.
Growth Catalysts
- FAA and DoD Open Systems Standards:Interoperability mandates force non-proprietary interfaces into new retrofit programs, expanding qualified supplier pools and accelerating upgrade timelines for aging tactical aircraft.
- Electronic Warfare Threat Evolution:Near-peer adversary radar and missile capabilities drive demand for software-definable countermeasure suites that integrate with existing airframes without structural redesign.
- Helmet-Mounted Cueing Systems:Pilot interface modernization replaces analog head-up displays with integrated visor-projected targeting, reducing cockpit modification complexity and downtime during depot maintenance.
Market Restraints
- Specialized Aerospace-Grade Wiring Harnesses:Supply concentration among qualified mil-spec cable producers creates input bottlenecks during large-scale fleet rewiring programs.
- Airframe Fatigue Life Certification:Structural life extension requires extensive non-destructive testing protocols that extend program timelines and compress contractor margins.
- Skilled Technician Scarcity:Depots face persistent shortages of airframe mechanics certified for both legacy analog systems and digital mission computer integration.
Strategic Opportunities
- Unmanned Teaming Interface Modules:Retrofit kits enabling fourth-generation fighters to command loyal wingman drones open new upgrade revenue streams without full platform replacement.
- Large-Area Display Retrofits:Multi-function touchscreen panels replace mechanical instruments, creating aftermarket content delivery platforms for recurring software updates.
- NATO Airworthiness Standard Harmonization:Cross-border certification reciprocity reduces duplicate testing costs for upgrade providers serving multiple allied air forces.
Industry Challenges
- Digital-Analog Architecture Bridging:Integration of software-defined systems with 1970s-era analog flight controls demands custom signal conditioning hardware that defies economies of scale.
- Software Supply Chain Security Verification:Mission-critical avionics now require component-level provenance documentation that extends vendor qualification timelines by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aircraft Modernization and Retrofit Market |
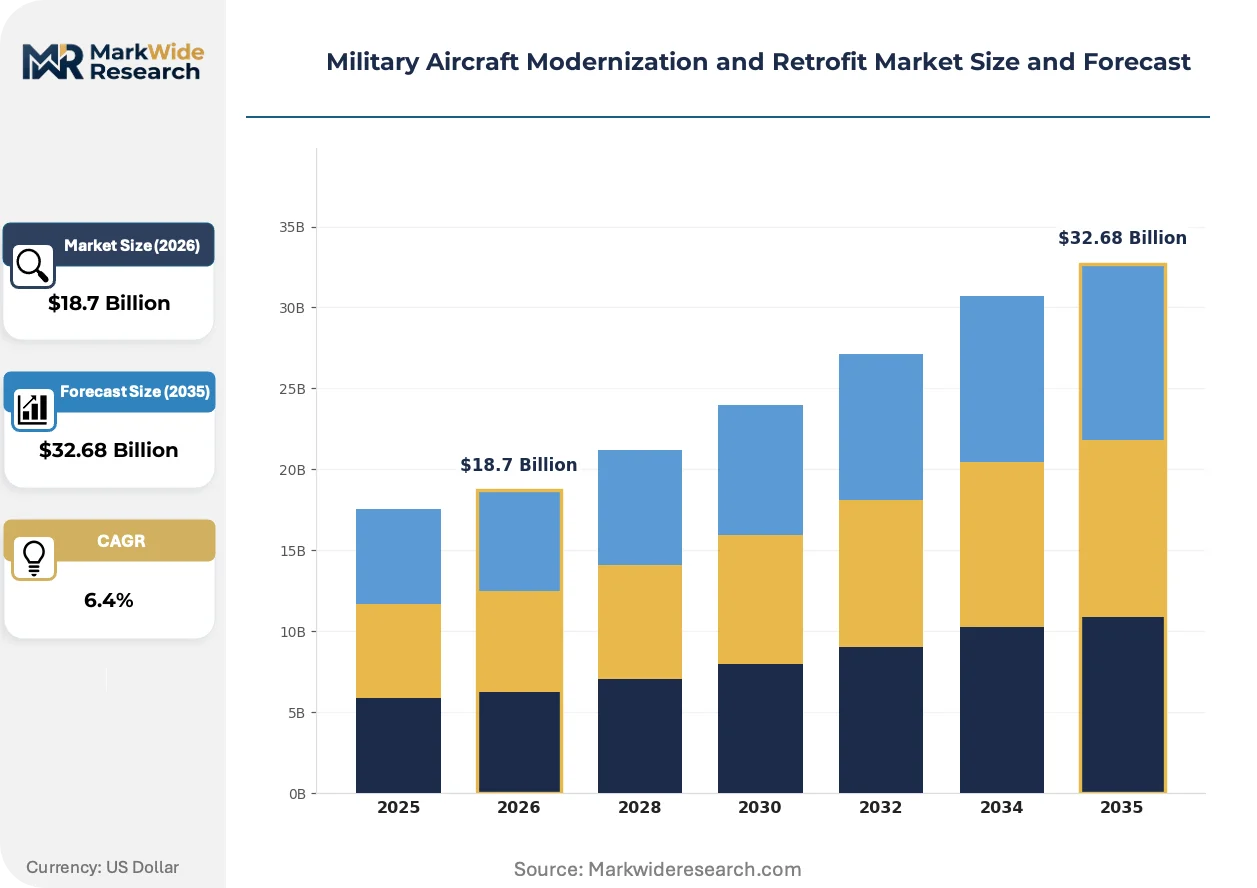
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Avionics, Propulsion Systems, Structural Upgrades, Weaponry Integration End User: Government, Defense Contractors, OEMs, Military Operators Application: Surveillance, Combat, Transport, Training Deployment: On-site Upgrades, Factory Refits, Modular Enhancements, Mobile Solutions |
| Companies Covered | The Boeing Company, L3Harris Technologies Inc., Lockheed Martin Corporation, Honeywell International Inc., Elbit Systems Ltd., Northrop Grumman Corporation, RTX Corporation, Israel Aerospace Industries Ltd., BAE Systems plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aircraft Modernization and Retrofit Market Strategic Shifts & Innovations
Software-defined architectures are collapsing the hardware refresh cycle into continuous capability delivery. This transformation shifts contractor revenue from discrete platform upgrades to persistent engineering services tied to operational flight program iterations.
Modular mission computers with standardized 1553 and Ethernet backbones are unifying previously fragmented avionics subsystems into single software-configurable platforms. NATO air forces are adopting these architectures fastest where mixed-nationality coalition operations demand rapid interoperability reconfiguration. This unifying hardware approach compresses upgrade cycle times from years to months and enables competitive subsystem sourcing that breaks prime contractor monopolies.
The US Department of Defense's modular open systems approach mandate requires all new avionics programs to publish technical standards and interfaces. This regulatory pressure fragments previously consolidated upgrade markets by lowering barriers for specialized subsystem vendors. Fighter sustainment programs now face explicit source-selection criteria favoring designs with demonstrated third-party integration capacity.
Air force procurement offices are unbundling long-term sustainment contracts into separately competed engineering services, hardware provision, and software maintenance components. This disaggregation disrupts traditional prime contractor turnkey models and elevates specialized avionics integrators with rapid software deployment capabilities. The United States Air Force's fighter sustainment enterprise exhibits this pattern most prominently, with depot maintenance increasingly separated from capability insertion contracts.
Military Aircraft Modernization and Retrofit Market Segmentation
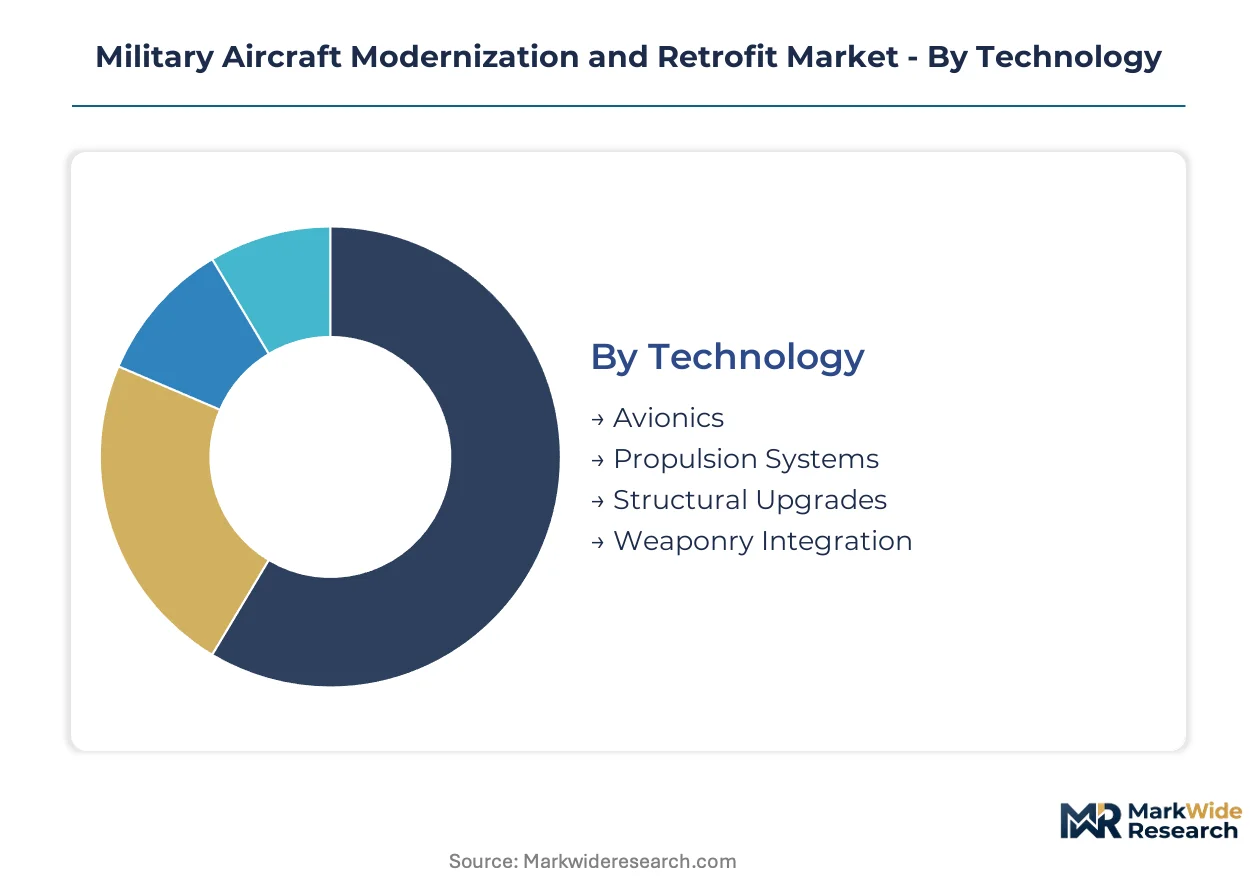
Segmentation in military aircraft modernization reveals how technology investment, procurement authority, and operational tempo reshape upgrade pathways. Each dimension exposes distinct margin structures, vendor qualification barriers, and contract vehicle preferences across defense aviation.
Technology:
Avionics commands premium pricing through software reprogrammability, while structural upgrades anchor volume deployment across aging tactical fleets.
- Avionics:Digital mission computers, large-area displays, and helmet-mounted cueing systems integrate via open systems architectures. Demand concentrates in US Air Force F-16 and F-22 sustainment programs driven by DoD modular open systems approach mandates.
- Propulsion Systems:Engine life extension programs and fuel control upgrades extend airframe operational envelopes without full powerplant replacement. NATO member states prioritize these upgrades for fourth-generation fighters facing range-payload tradeoffs against near-peer threats.
- Structural Upgrades:Center wing box replacements, corrosion repair, and fatigue life extension through non-destructive testing protocols.
- Weaponry Integration:Hardpoint modifications, stores management computer updates, and carriage-release system upgrades for new munitions families.
Mature deployment sits with structural upgrades. Newer deployment is concentrated in avionics.
End User:
Procurement authority fragmentation splits upgrade contracts between government program offices and prime contractor sustainment enterprises.
- Government:Air force materiel commands and defense acquisition agencies directly contract for depot-level capability insertion. The US Air Force Life Cycle Management Center dominates this channel through competitively awarded engineering services contracts.
- Defense Contractors:Prime integrators and tier-1 suppliers perform organic fleet modifications under performance-based logistics agreements. European defense contractors anchor this segment through multi-national NATO upgrade consortia.
- OEMs:Original equipment manufacturers execute design authority modifications and configuration control for type-certified airframes.
- Military Operators:Squadron-level maintenance organizations execute limited scope upgrades during scheduled maintenance windows.
Contract value concentrates with government program offices. Execution speed advantages sit with defense contractors.
Application:
Threat environment intensity drives investment hierarchy across mission categories, with electronic warfare refresh rates varying by operational exposure.
- Combat:Fighter and attack aircraft receive prioritized funding for sensor fusion, electronic countermeasures, and weapons integration. The US Department of Defense concentrates investment here through its fighter sustainment enterprise managing the largest aging tactical inventory.
- Surveillance:Intelligence, surveillance, and reconnaissance platforms require signals intelligence payload upgrades and datalink modernization. NATO allied air forces drive demand for interoperable coalition network architectures.
- Transport:Cargo and tanker fleets focus on communications navigation surveillance/air traffic management compliance and defensive systems.
- Training:Jet trainer upgrades emphasize cockpit commonality with frontline fighters and synthetic training system integration.
Capability insertion budgets concentrate in combat applications. Steepest expansion trajectory appears in surveillance platform modernization.
Deployment:
Maintenance availability constraints and airframe condition determine whether upgrades execute at organic depots, contractor facilities, or operational bases.
- Modular Enhancements:Line-replaceable unit swaps and software loads minimize aircraft downtime through rapid reconfiguration. US Air Force agile combat employment concepts accelerate adoption of this deployment mode for distributed operations.
- Factory Refits:Comprehensive structural and avionics integration at contractor or government depot facilities enables complex modifications requiring jig assembly.
- On-site Upgrades:Field maintenance teams execute limited scope modifications at operational locations without aircraft movement.
- Mobile Solutions:Deployable upgrade kits and forward support equipment enable capability insertion in austere locations.
Program complexity concentrates in factory refits. Operational responsiveness demands are reshaping investment toward modular enhancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retrofit execution concentrates in defense industrial bases with organic depot infrastructure, while demand spreads across NATO allied air forces extending fourth-generation fighter service lives. The United States absorbs the largest share of engineering services contracts through its Air Force Life Cycle Management Center. European nations coordinate through multi-national upgrade consortia to amortize non-recurring engineering costs.
United States
The US Air Force's fighter sustainment enterprise manages the largest inventory of aging F-16 and F-22 airframes requiring capability insertion. FAA and DoD open systems architecture mandates force non-proprietary interfaces into new retrofit programs, expanding qualified supplier pools. Lockheed Martin's digital thread infrastructure in Fort Worth, Texas anchors domestic avionics refresh activity.
United Kingdom
Royal Air Force Typhoon and F-35 fleets drive demand for electronic warfare and flight control retrofit services. BAE Systems plc leverages its design authority position to execute configuration-controlled modifications under UK Ministry of Defence contracts. The company's electronic systems division in Lancashire concentrates European fighter upgrade engineering.
Israel
Israel Defense Forces operate one of the most extensively modified F-16 fleets globally, generating specialized demand for helmet-mounted cueing systems and large-area displays. Israel Aerospace Industries Ltd. and Elbit Systems Ltd. compete on integration speed with legacy analog architectures. Tel Aviv-area defense clusters specialize in rapid software deployment for operational flight program iterations.
Germany
Luftwaffe Tornado replacement delays extend structural life certification programs for aging strike aircraft. EASA's military certification liaison and NATO airworthiness standards define market access conditions for European retrofit providers. Bavaria-based maintenance, repair and overhaul facilities coordinate with Airbus Defence and Space for multi-national upgrade consortia.
Japan
Japan Air Self-Defense Force F-15J fleets undergo extensive radar and electronic countermeasure modernization to address near-peer threats in the Indo-Pacific. METI industrial policy supports domestic integration partnerships with US prime contractors. Nagoya-area aerospace manufacturing clusters host joint engineering teams for indigenous upgrade capability development.
Military Aircraft Modernization and Retrofit Market Key Industry Players
Top-tier vendors anchor prime integrator positions on major fighter sustainment programs, while specialized subsystem providers capture modular upgrade niches through rapid software deployment capabilities. The vendor base stratifies across three tiers: full-service primes with design authority, mission system specialists with open architecture integration expertise, and component suppliers qualified for military airworthiness standards. Two dominant competitive moves are reshaping positioning: unbundling of long-term sustainment contracts into separately competed engineering services and hardware provision, and vertical integration into software-defined mission systems to capture recurring upgrade revenue.
Among US-based defense primes, Lockheed Martin Corporation, Northrop Grumman Corporation and RTX Corporation occupy positions across the full-service tier, representing archetypes of digital thread infrastructure deployment, electronic warfare system integration, and propulsion control modernization respectively. Lockheed Martin exemplifies the prime contractor leveraging sustainment program scale to enforce open systems standards. Northrop Grumman sits within the mission systems specialist vector where software reprogrammability generates recurring revenue. RTX anchors the propulsion and power systems upgrade pathway through engine life extension programs.
| Leading Market Players |
|---|
| The Boeing Company |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| Honeywell International Inc. |
| Elbit Systems Ltd. |
| Northrop Grumman Corporation |
| RTX Corporation |
| Israel Aerospace Industries Ltd. |
| BAE Systems plc |
| Others |
Cost & Logistics Intelligence
US Air Force Life Cycle Management Center procurement concentration anchors cost-plus contracting as the dominant pricing model across fighter sustainment programs, with fixed-price competition emerging only where open systems architecture mandates fragment prime integrator control. This buyer structure compresses margins on structural life extension while preserving premium pricing for software-reprogrammable avionics refresh.
Pricing Analysis
Margin tightening in depot-level engineering services reflects unbundling of long-term sustainment contracts into separately competed hardware and software components. Cost-plus incentive fee structures dominate government program office awards, while competitive bidding on modular line-replaceable units forces price transparency. Price differentiation rests on MIL-STD-810 environmental certification tier and demonstrated third-party integration capacity. NATO allied air forces exhibit highest price sensitivity due to multi-national cost-sharing constraints; US domestic programs show lowest sensitivity where national security overrides procurement cost thresholds.
Supply Chain Analysis
Skilled airframe mechanic shortages in Texas, Arizona, and Georgia constrain depot throughput for digital-analog integration programs. Aerospace-grade wiring harness production concentrates in the United States, United Kingdom, and Israel, drawing from specialized mil-spec cable producers qualified to SAE AS50881 standards. Single-source vulnerability pervades mission-critical semiconductor components for legacy 1553 bus architectures. Distribution runs through prime contractor logistics chains to government depot facilities, with emergent direct sourcing by program offices for open architecture subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward control over software-defined mission systems determines recurring revenue capture. Players are pursuing downstream leverage through persistent engineering services tied to operational flight program iterations.
For Market Incumbents: Hedge against prime contractor disaggregation by capturing modular upgrade niches through rapid software deployment capabilities. Lockheed Martin's digital thread infrastructure exemplifies defensive positioning against unbundling of sustainment contracts. Invest in FAA and DoD open systems certification to preserve integration role as third-party vendors proliferate. For New Entrants and Emerging Players: Launch via direct contracting with US Air Force Life Cycle Management Center for agile combat employment upgrade kits. NATO multi-national upgrade consortia present the most penetrable channel for European market entry. Target helmet-mounted cueing system and large-area display retrofits where integration speed with legacy analog architectures commands premium positioning. For Investors and Strategic Acquirers: The window for entry favors specialized avionics integrators with demonstrated open architecture deployment records. Long-term viability hinges on software reprogrammability revenue streams rather than discrete hardware refresh cycles. Watch for DoD modular open systems approach mandate expansion as the inflection signal for prime contractor valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Open Systems Architecture Certification | FAA and DoD mandates expand qualified supplier pools beyond traditional prime integrators. |
| Software-Defined Mission System Development | Recurring upgrade revenue displaces discrete hardware refresh profitability. |
| Depot Infrastructure Partnership | Organic fleet modification capacity secures performance-based logistics contract flow. |
| Multi-National Upgrade Consortium Formation | NATO airworthiness standard harmonization amortizes non-recurring engineering across allied budgets. |
| Unmanned Teaming Interface Module Launch | Retrofit kits enabling loyal wingman command open new revenue without platform replacement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with US Air Force program executives, defense contractor engineering directors, depot maintenance officers, and NATO standardization office leads. FAA airworthiness directives, DoD modular open systems approach documentation, EASA military certification liaison records, and SAE technical standards provided segmentation benchmarks. Bottom-up fleet inventory analysis triangulated against top-down defense budget appropriation data.
Production volume and contract value outputs reconciled shipment data from prime contractor disclosures with government procurement database records across the projection horizon. Segmentation dimensions modeled include technology type, end-user procurement authority, combat versus surveillance application, and modular versus factory deployment mode. CAGRs derived from fleet age demographics, threat environment evolution timelines, and regulatory mandate implementation schedules. Software reprogrammability penetration rates and open architecture adoption curves served as industry-specific forecast inputs.
Defense budget reallocation, near-peer threat capability surprise, and software supply chain security regulation expansion are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding NATO alliance cohesion and US congressional appropriation continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Land Digital Battlefield Market