
 Global Soldier Modernization Market | 2026-2036
Global Soldier Modernization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soldier Modernization Market Outlook
Multi-source procurement of soldier system subcomponents is shifting toward vertically integrated platform contracts as defense ministries seek interoperability guarantees. BAE Systems leverages its British manufacturing base to dominate core personal protective equipment supply. Elbit Systems anchors Israeli export programs through battlefield-proven networking solutions. Rheinmetall competes on German Army modernization frameworks with modular weapon-integrated soldier kits.
Soldier modernization encompasses the integration of protective, communicative, sensory, and lethality-enhancing equipment worn or carried by dismounted warfighters, typically involving ballistic helmets rated to NIJ Level IIIA, encrypted tactical radios operating in 30-512 MHz bands, and load-bearing exoskeleton frames reducing musculoskeletal strain during extended patrols. Personal Protective Equipment commands the largest procurement share as ceramic-composite plate demand tracks infantry force expansion across multiple NATO commitments. Communication Systems represent the fastest-growing technology segment as software-defined radio architectures displace legacy hardware across allied force structures.
The US Department of Defense, the UK Ministry of Defence, and NATO Standardization Office collectively shape market access through STANAG interoperability mandates and country-specific export control classifications under ITAR and EU dual-use regulations. France's ANSM-equivalent defense procurement agency DGA imposes additional electromagnetic compatibility standards that filter non-European suppliers from certain subsystem competitions. Stakeholders must monitor evolving classification thresholds for night vision and thermal imaging components as these determine both addressable market scope and partnership requirements for technology transfer agreements.
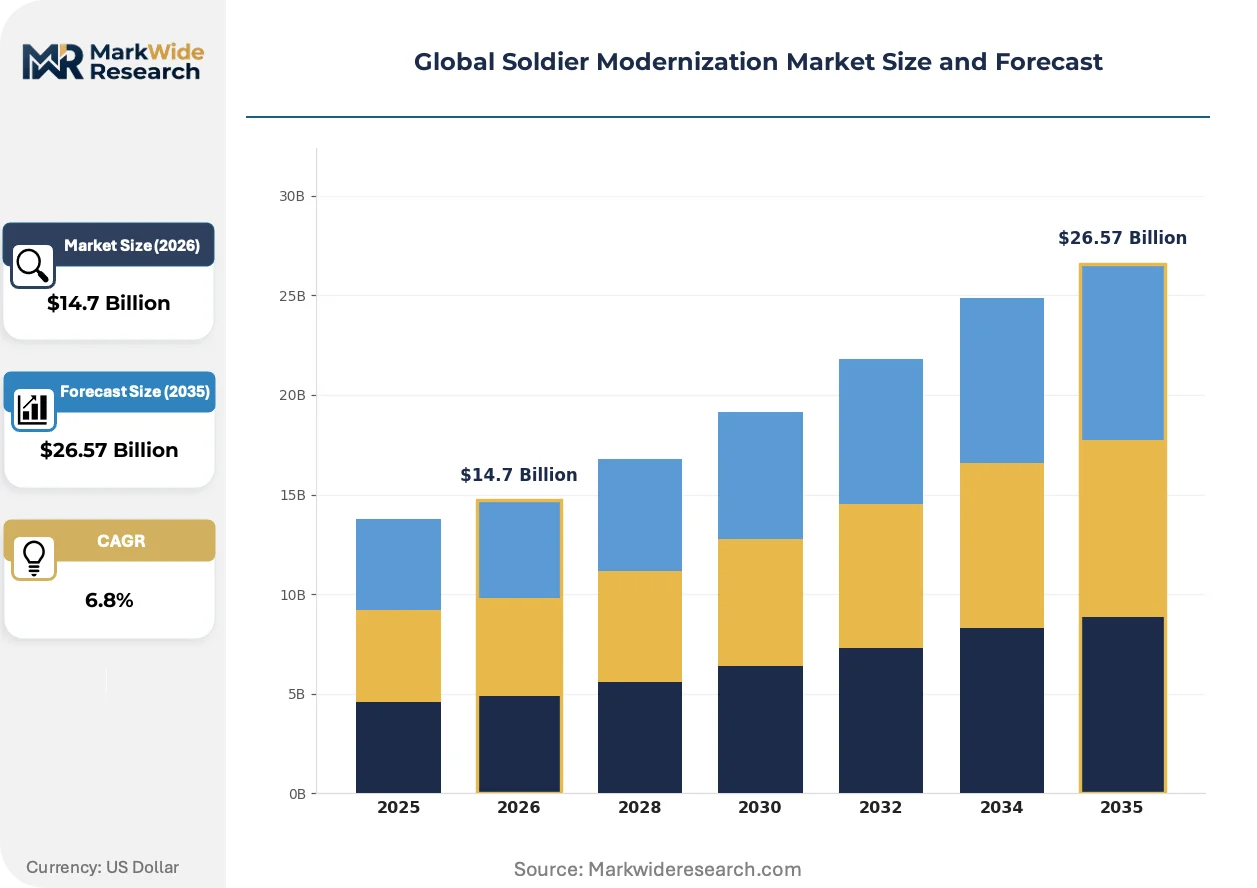
Market Dynamics
Software-defined radio architectures are compressing hardware refresh cycles across NATO allied forces, forcing subsystem vendors to abandon standalone radio production in favor of integrated platform partnerships with prime contractors.
Growth Catalysts
- IVAS Program Mandate:The US Department of Defense's Integrated Visual Augmentation System is driving unified procurement standards that bundle heads-up displays, thermal imaging, and networked communications into single-source contracts.
- NATO STANAG 4695:This interoperability framework for soldier systems is compelling European defense ministries to consolidate fragmented equipment purchases around certified integrated platforms.
- Ceramic-Composite Plates:Advances in silicon carbide and boron carbide manufacturing are reducing plate weight while maintaining NIJ Level IV protection, enabling wider infantry force equipping without mobility penalties.
Market Restraints
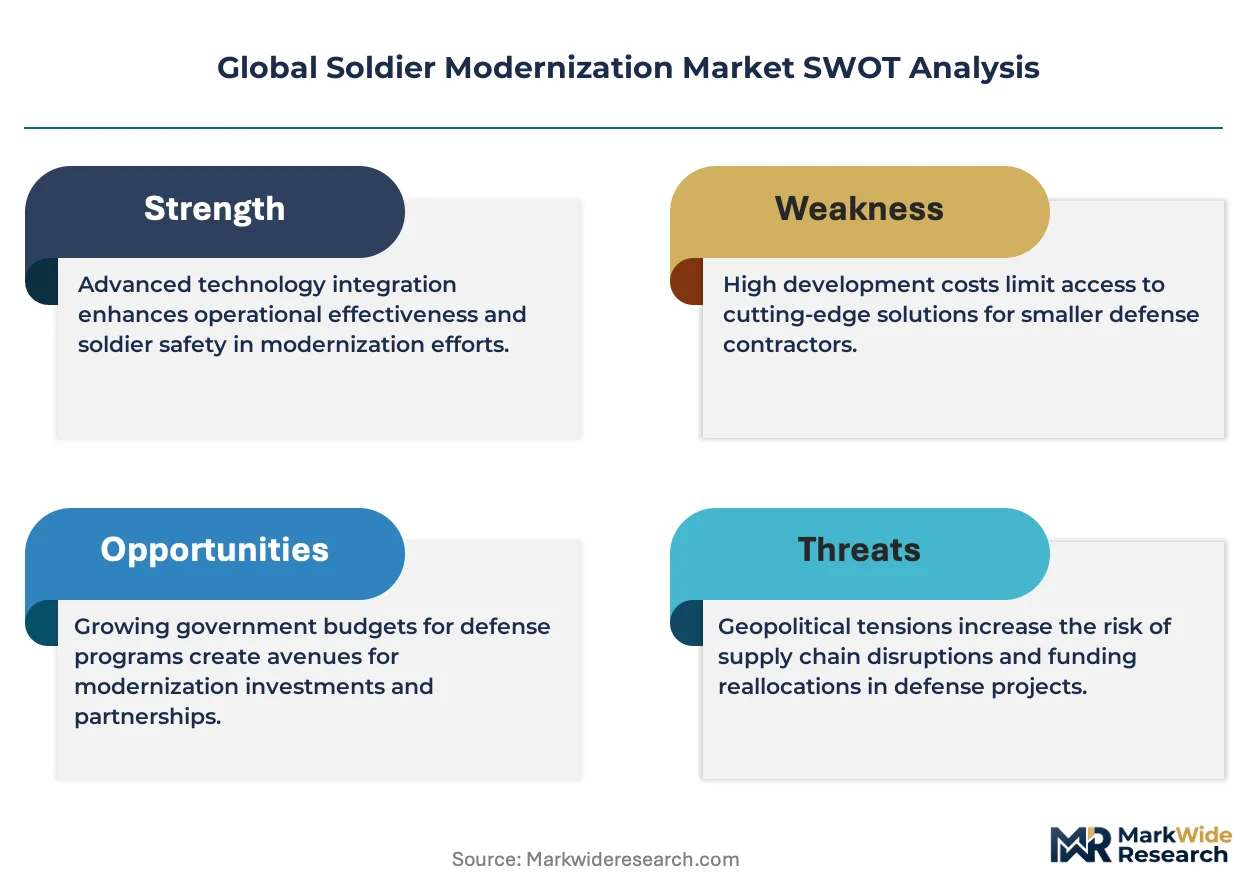
- ITAR Classification Thresholds:US State Department export controls on night vision intensifier tubes and thermal cores restrict technology transfer to non-NATO partners, fragmenting addressable markets.
- Rare Earth Magnet Dependence:Chinese dominance in neodymium and dysprosium processing creates supply vulnerability for exoskeleton actuator motors and precision weapon stabilization systems.
- Electromagnetic Spectrum Congestion:Civilian 5G expansion into previously military-reserved bands below 6 GHz is forcing tactical radio redesigns and reducing transmission reliability in urban environments.
Strategic Opportunities
- Polish Armed Forces Modernization:Warsaw's accelerated NATO interoperability investments are creating demand for integrated soldier kits that bypass legacy Soviet-era equipment dependencies.
- AI-Enabled Threat Detection:Convergence of edge computing hardware with acoustic and seismic sensor networks enables real-time hostile fire localization without centralized command node dependency.
- Australian Army Land 125:This phased equipment replacement program offers entry points for non-traditional suppliers meeting TGA-equivalent defense materiel certification standards.
Industry Challenges
- Systems Integration Engineering Gap:Prime contractors face acute shortages of engineers capable of harmonizing power management, thermal loads, and data protocols across multi-vendor subsystems.
- STANAG Certification Timelines:NATO standardization testing for electromagnetic compatibility and ballistic protection extends product validation cycles, delaying revenue recognition and freezing design iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soldier Modernization Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Protective Equipment, Communication Systems, Weapon Systems, Surveillance Equipment Technology: Wearable Technology, Augmented Reality, Biometrics, Networking Solutions End User: Army, Navy, Air Force, Defense Contractors Application: Tactical Operations, Training Simulations, Reconnaissance, C4ISR |
| Companies Covered | BAE Systems plc, Thales Group, Elbit Systems Ltd., Rheinmetall AG, L3Harris Technologies Inc., Leonardo S.p.A., General Dynamics Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soldier Modernization Market Strategic Shifts
Convergence of augmented reality interfaces with biometric monitoring is redefining how dismounted warfighters process battlefield information and how command structures measure individual combatant readiness in real time.
Software-defined radio is overtaking legacy hardware-defined architectures in tactical communications. Special operations units across allied forces are fielding multi-band units that reconfigure waveforms through firmware rather than hardware swaps. This compression of upgrade cycles is collapsing the traditional 10-year radio replacement timeline and forcing manufacturers toward subscription-based software maintenance models.
EU AI Act risk classification requirements are extending to military autonomous subsystems through dual-use export control interpretations. French DGA electromagnetic compatibility standards now incorporate algorithmic decision transparency mandates for target recognition modules. German KBA-equivalent defense procurement offices are demanding compliance documentation that traces training data provenance for machine learning-enabled threat detection systems.
Bundled platform contracting is displacing component-level procurement across NATO member defense ministries. British Army FIST program requirements now specify integrated helmet-weapon-power-data systems rather than separable subsystems. This behavioral shift concentrates vendor selection authority with prime integrators and marginalizes specialized subsystem suppliers lacking platform partnership credentials.
Global Soldier Modernization Market Segmentation
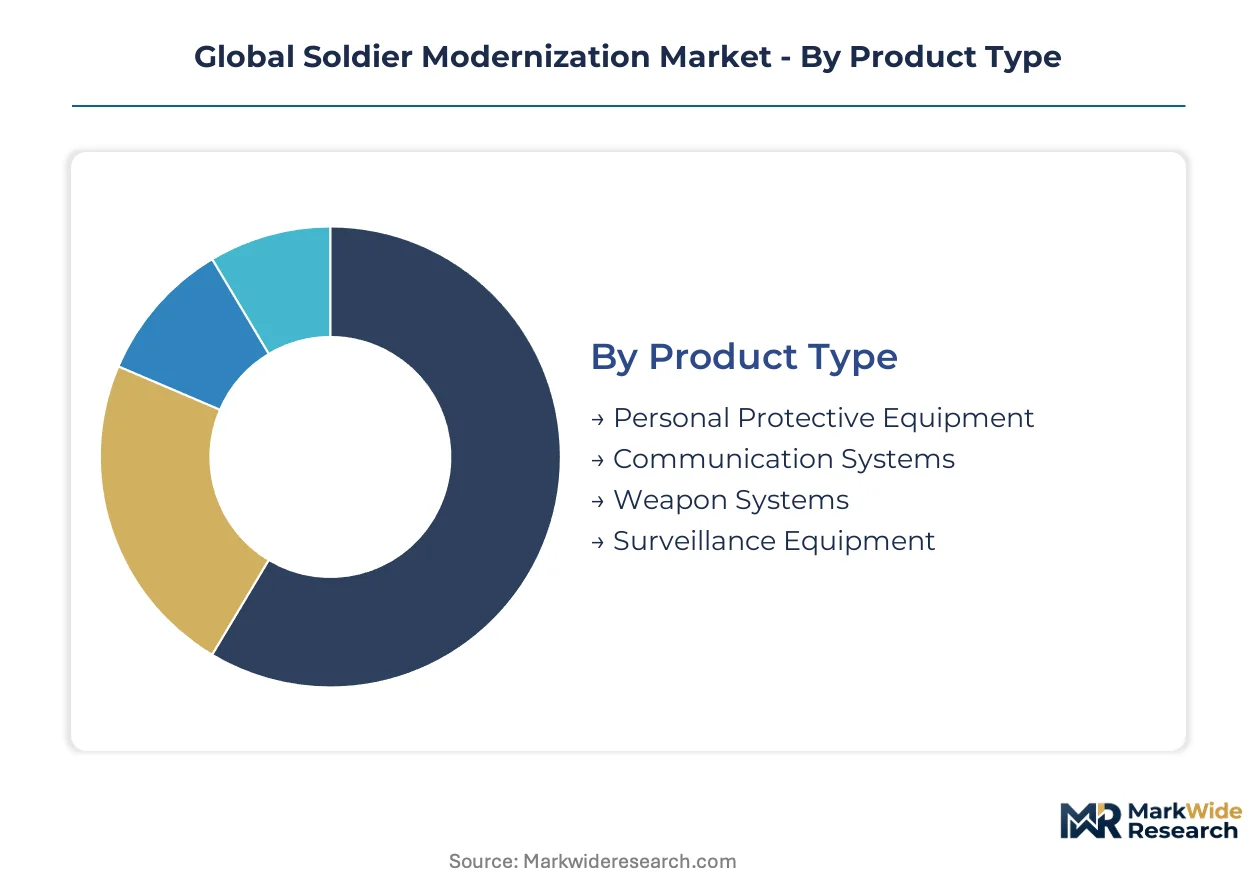
Defense procurement offices evaluate soldier modernization investments through four distinct lenses: equipment category, underlying technology, service branch, and operational mission. Each segmentation axis reveals different vendor selection criteria, certification requirements, and budget allocation patterns across NATO allied forces.
Product Type:
Procurement volume tracks force protection mandates and casualty reduction targets set by national defense ministries.
- Personal Protective Equipment:Ceramic-composite ballistic plates, NIJ Level IIIA helmets, and modular load-bearing vests constitute the largest procurement category. United States Army equipping programs drive demand for lightweight silicon carbide inserts that maintain Level IV protection without mobility penalties. STANAG 2920 fragmentation testing requirements filter suppliers capable of delivering certified platforms at scale.
- Communication Systems:Software-defined radios operating across 30-512 MHz bands with encrypted waveforms represent the technology segment climbing fastest. United Kingdom Ministry of Defence Bowman replacement programs and French DGA SCORPION radio modernizations concentrate demand for multi-band units that reconfigure through firmware updates rather than hardware swaps.
- Weapon Systems:Modular small arms with integrated fire control and target acquisition modules.
- Surveillance Equipment:Night vision intensifiers, thermal weapon sights, and handheld reconnaissance sensors.
Volume sits with Personal Protective Equipment; growth tilts toward Communication Systems.
Technology:
Technology selection hinges on power budget constraints and electromagnetic compatibility certification timelines.
- Wearable Technology:Load-bearing exoskeleton frames, biometric monitoring patches, and power distribution textiles reduce musculoskeletal strain during extended patrols. German Army IdZ-ES program specifications prioritize systems that operate within 50W soldier-borne power budgets while maintaining NATO STANAG 4695 interoperability.
- Networking Solutions:Mesh radio architectures, edge computing nodes, and self-healing tactical data networks enable dismounted command posts without vehicle dependency. Australian Army Land 125 Phase 3C requirements and Polish Territorial Defence Force modernization frameworks concentrate demand for MANET protocols that function in GPS-denied environments.
- Augmented Reality:Helmet-mounted displays integrating thermal overlay and navigation waypoints.
- Biometrics:Real-time physiological monitoring for heat injury prevention and combat readiness assessment.
Procurement maturity favors Wearable Technology; capability investment flows toward Networking Solutions.
End User:
Service branch procurement authority determines platform integration depth and subsystem certification pathways.
- Army:Dismounted infantry, mechanized units, and special operations forces constitute the dominant end-user category. United States Army PEO Soldier manages IVAS program integration while British Army FIST program offices specify helmet-weapon-power-data system bundles rather than separable components.
- Navy:Maritime interdiction teams and amphibious assault units require corrosion-resistant communications and flotation-integrated load carriage.
- Air Force:Combat search and rescue personnel and forward air controllers prioritize lightweight kits for rapid deployment.
- Defense Contractors:Private military companies and security services operating under government contract purchase commercial equivalents with reduced encryption tiers.
Platform complexity concentrates with Army; procurement flexibility expands with Defense Contractors.
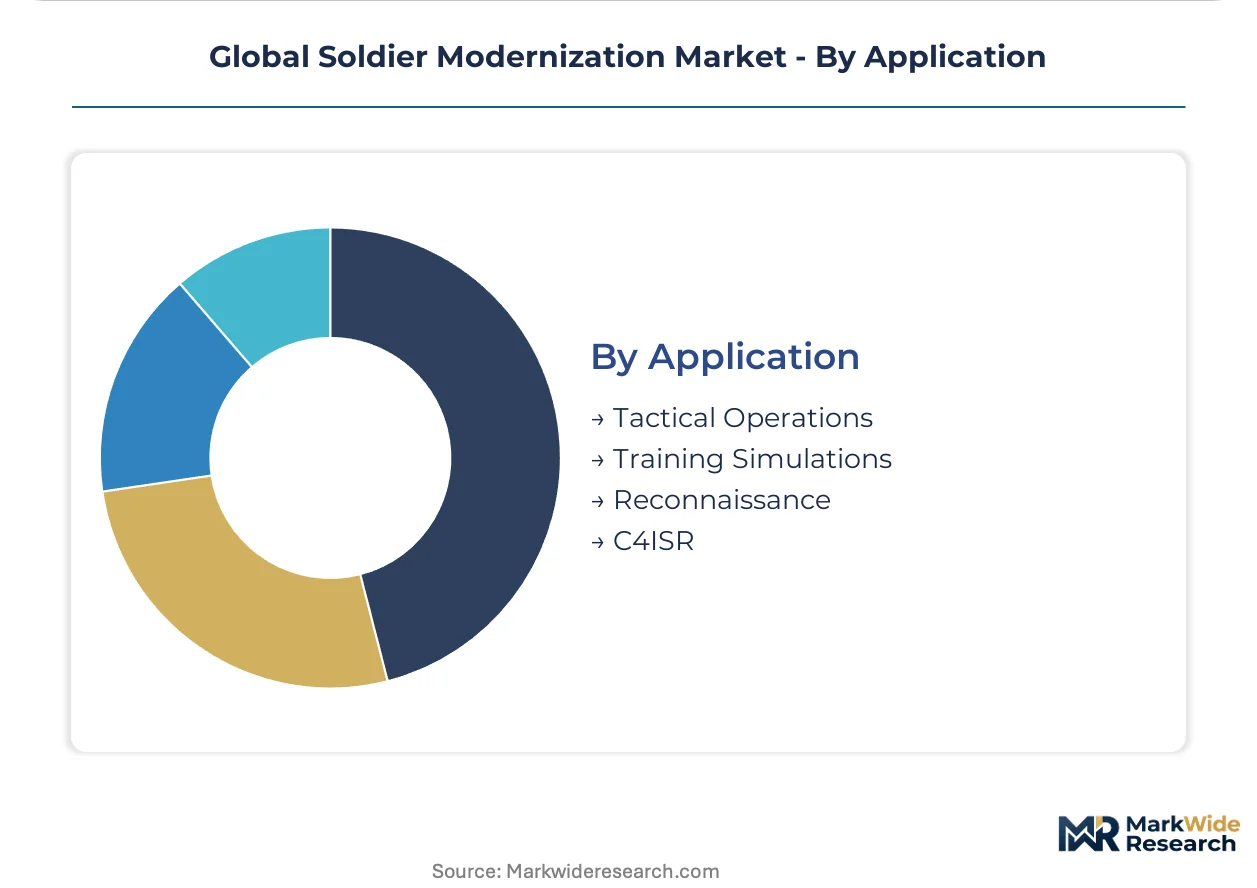
Application:
Mission profile dictates sensor fusion requirements and data throughput specifications.
- Tactical Operations:Direct action missions requiring real-time situational awareness, hostile fire detection, and networked targeting. French Special Operations Command and United States Army 75th Ranger Regiment fielding programs drive demand for integrated kits that compress sensor-to-shooter timelines below ten seconds.
- C4ISR:Command, control, communications, computers, intelligence, surveillance, and reconnaissance integration at dismounted echelons. NATO Allied Command Transformation experimentation cells evaluate AI-enabled threat detection algorithms that process acoustic and seismic signatures without centralized node dependency.
- Training Simulations:Force-on-force exercises with after-action review data capture.
- Reconnaissance:Long-range patrols emphasizing signature reduction and extended battery life.
Operational tempo anchors Tactical Operations; capability experimentation centers on C4ISR.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement for soldier modernization concentrates in NATO member states with active force modernization mandates. The United States, United Kingdom, Germany, France, and Australia anchor equipment demand through structured acquisition programs. National regulatory frameworks and interoperability standards filter market access across these jurisdictions.
United States
The US Army's IVAS program and PEO Soldier office drive integrated platform procurement bundling displays, sensors, and communications. ITAR regulations administered by the State Department restrict thermal core and night vision exports to non-NATO partners. Industrial activity clusters around Arlington, Virginia, where defense primes maintain proximity to Pentagon acquisition commands.
United Kingdom
British Army FIST program requirements specify helmet-weapon-power-data system integration rather than separable subsystems. Ministry of Defence procurement offices enforce STANAG 4695 interoperability certification for all submitted platforms. Manufacturing and integration work concentrates in Hampshire and the West Midlands, where BAE Systems operates core production facilities.
Germany
The IdZ-ES program prioritizes soldier-borne power budgets under 50W while maintaining NATO interoperability standards. Federal Office of Bundeswehr Equipment mandates electromagnetic compatibility testing that extends product validation timelines. Defense industrial activity centers in North Rhine-Westphalia and Bavaria, where Rheinmetall anchors modular weapon-integrated kit development.
France
DGA procurement specifications incorporate algorithmic transparency mandates for AI-enabled target recognition modules under EU AI Act dual-use interpretations. SCORPION radio modernization programs concentrate demand for multi-band software-defined units. Industrial capability clusters in the Île-de-France region around Paris-Saclay, where Thales Group coordinates subsystem integration.
Australia
Army Land 125 phased equipment replacement creates entry points for suppliers meeting TGA-equivalent defense materiel certification. Department of Defence requirements emphasize MANET protocols functioning in GPS-denied environments for regional expeditionary missions. Capability development concentrates in Victoria and New South Wales, where local integration facilities support Indo-Pacific force posture requirements.
Global Soldier Modernization Market Competitive Environment
Platform-level contracting dominates the current landscape as defense ministries abandon component-level procurement. The vendor structure organizes around prime integrators with NATO certification credentials and specialized subsystem suppliers seeking platform partnership status. Three archetypes prevail: vertically integrated defense conglomerates with in-house manufacturing across all subsystems; networking specialists leveraging software-defined radio expertise; and protection-focused suppliers anchored in ceramic-composite and ballistic materials. Competitive moves concentrate on strategic partnerships for STANAG certification access and backward integration into critical component supply.
Among British-based prime contractors, BAE Systems plc exemplifies the integrated platform archetype through its FIST program positioning. Israeli networking specialists include Elbit Systems Ltd., which occupies a position exemplifying battlefield-proven communications integration. German industrial conglomerate Rheinmetall AG anchors the modular weapon-system archetype within European Army modernization frameworks. These three entities represent distinct competitive positioning vectors without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| BAE Systems plc |
| Thales Group |
| Elbit Systems Ltd. |
| Rheinmetall AG |
| L3Harris Technologies Inc. |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed defense conglomerates and private-equity-rolled-up subsystem specialists anchor supply ownership patterns, concentrating pricing power with prime integrators while fragmenting margins among component vendors competing for platform partnership status.
Pricing Analysis
Volume concentrates in ceramic-composite ballistic plates and NIJ-certified helmets, while margins pool with software-defined radio architectures and AI-enabled threat detection modules. Three-tier pricing structure across platform-integrated, STANAG-certified, and commercial-equivalent levels separates NATO prime contractors from regional system integrators and defense contractors purchasing reduced-encryption tiers. Cost compression in communication subsystems is intensifying because firmware-upgrade cycles collapse hardware replacement timelines. National armed forces exhibit lowest price sensitivity due to interoperability mandates; private military companies show highest sensitivity, driving commercial-equivalent procurement.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing for neodymium and dysprosium, which feeds exoskeleton actuator motors and precision weapon stabilization systems. Manufacturing concentrates in the United States, Germany, and Israel for integrated soldier platforms; ceramic-composite plate fabrication clusters in the United States and United Kingdom. Raw material dependencies span silicon carbide substrates, gallium nitride semiconductors, and ITAR-classified night vision intensifier tubes. Tariff exposure on Chinese-processed rare earth elements threatens cost structures for wearable power systems. Distribution runs through defense ministry procurement offices and NATO standardization certification pathways rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over STANAG certification access and captive supply of ITAR-restricted components determines platform award probability.
For Market Incumbents: To counter software-defined radio margin compression, BAE Systems and Rheinmetall should deepen backward integration into gallium nitride semiconductor fabrication and ceramic-composite armor manufacturing, securing supply autonomy while accelerating electromagnetic compatibility certification timelines through captive testing facilities. For New Entrants and Emerging Players: Capture Australian Army Land 125 Phase 3C requirements and Polish Territorial Defence Force modernization frameworks by positioning as MANET protocol specialists for GPS-denied environments, leveraging TGA-equivalent certification pathways to bypass entrenched NATO prime contractor relationships. For Investors and Strategic Acquirers: IVAS program milestone completions are the leading indicator that integrated platform contracting is displacing component-level procurement, signaling long-term viability for software-defined radio and augmented reality subsystem vendors with proven NATO interoperability credentials; target acquisition archetypes are Israeli networking specialists and British protection-equipment manufacturers lacking platform partnership scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gallium Nitride Fabrication | Captive semiconductor supply reduces dependence on US-based foundries subject to ITAR export controls. |
| STANAG 4695 Certification Acceleration | Pre-qualified platform status enables sole-source contracting with British Army FIST and German IdZ-ES programs. |
| AI-Enabled Threat Detection Module Development | French DGA algorithmic transparency mandates filter suppliers capable of training data provenance documentation. |
| Rare Earth Magnet Supply Diversification | Australian and Canadian mining partnerships mitigate Chinese processing concentration for exoskeleton actuator motors. |
| Software-Defined Radio Platform Integration | Subscription-based firmware maintenance models collapse traditional hardware replacement revenue cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with program executive officers at PEO Soldier and British Army FIST directorates, defense procurement managers at DGA and BAAINBw, subsystem engineering leads at Elbit Systems and Thales, and electromagnetic compatibility testing laboratory directors. Secondary sources included NATO STANAG documentation, US State Department ITAR classification registers, EU dual-use export control determinations, and defense ministry budget appropriation records. Bottom-up equipment procurement forecasts triangulated against top-down NATO force structure modernization commitments.
Data-stream reconciliation across shipment volumes, contract award announcements, and certification timeline disclosures informed the analytical framework across the analysis window. Segmentation dimensions modeled encompassed product type, underlying technology, service branch, and operational mission profile, with additional granularity on software-defined versus hardware-defined radio architectures. CAGRs derived from equipment replacement cycle compression rates and force expansion mandates. Industry-specific forecast inputs included IVAS program integration milestones and Polish Armed Forces NATO interoperability investment schedules.
The model holds under sustained NATO defense spending commitments and stable ITAR classification thresholds; deviation in rare earth supply disruptions or electromagnetic spectrum reallocation would shift equipment availability timelines and procurement prioritization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global CBRN Defense Market