
 Rocket Solid Propulsion Market | 2026-2036
Rocket Solid Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Rocket Solid Propulsion Market Analytics
Domestic propellant grain casting facilities in the United States are pivoting toward automated filament winding and continuous processing to shorten lead times for strategic missile programs. Northrop Grumman leverages its Utah-based solid rocket infrastructure to sustain Minuteman III replacement motor production at scale. China Aerospace Science and Technology Corporation dominates domestic launch capacity with in-house ammonium perchlorate synthesis and large-diameter grain casting. Nammo AS specializes in tactical rocket motors for European defense customers, competing across shoulder-fired and precision-strike segments.
Rocket solid propulsion refers to thrust generation through controlled combustion of a pre-cast solid fuel-oxidizer matrix, typically comprising ammonium perchlorate crystals bound in hydroxyl-terminated polybutadiene with aluminum powder additives, achieving chamber pressures of 5-15 MPa and specific impulse values of 250-280 seconds. The technology serves as the primary propulsion architecture for ballistic missiles, launch vehicle strap-on boosters, and upper-stage kick motors where simplicity and storability outweigh liquid engine complexity. Composite propellant formulations command the deepest margin pools due to tailored burn-rate modifiers and customized grain geometries for mission-specific thrust profiles. Satellite launch applications represent the fastest-expanding demand channel as constellation deployment schedules compress and commercial providers seek reliable, storable propulsion for responsive access to orbit.
FAA launch licensing requirements, DoD MIL-STD-2105 safety criteria, and EPA perchlorate monitoring under the Safe Drinking Water Act collectively shape product qualification timelines, facility siting constraints, and oxidizer handling protocols across the United States supply base. ESA member-state procurement regulations and REACH chemical restrictions impose parallel compliance burdens on European manufacturers seeking cross-border defense contracts. Stakeholders must monitor chlorine-free propellant chemistry maturation, as regulatory pressure on perchlorate environmental persistence threatens to disrupt established formulation supply chains before alternative oxidizers achieve comparable performance and cost parity.
Market Dynamics
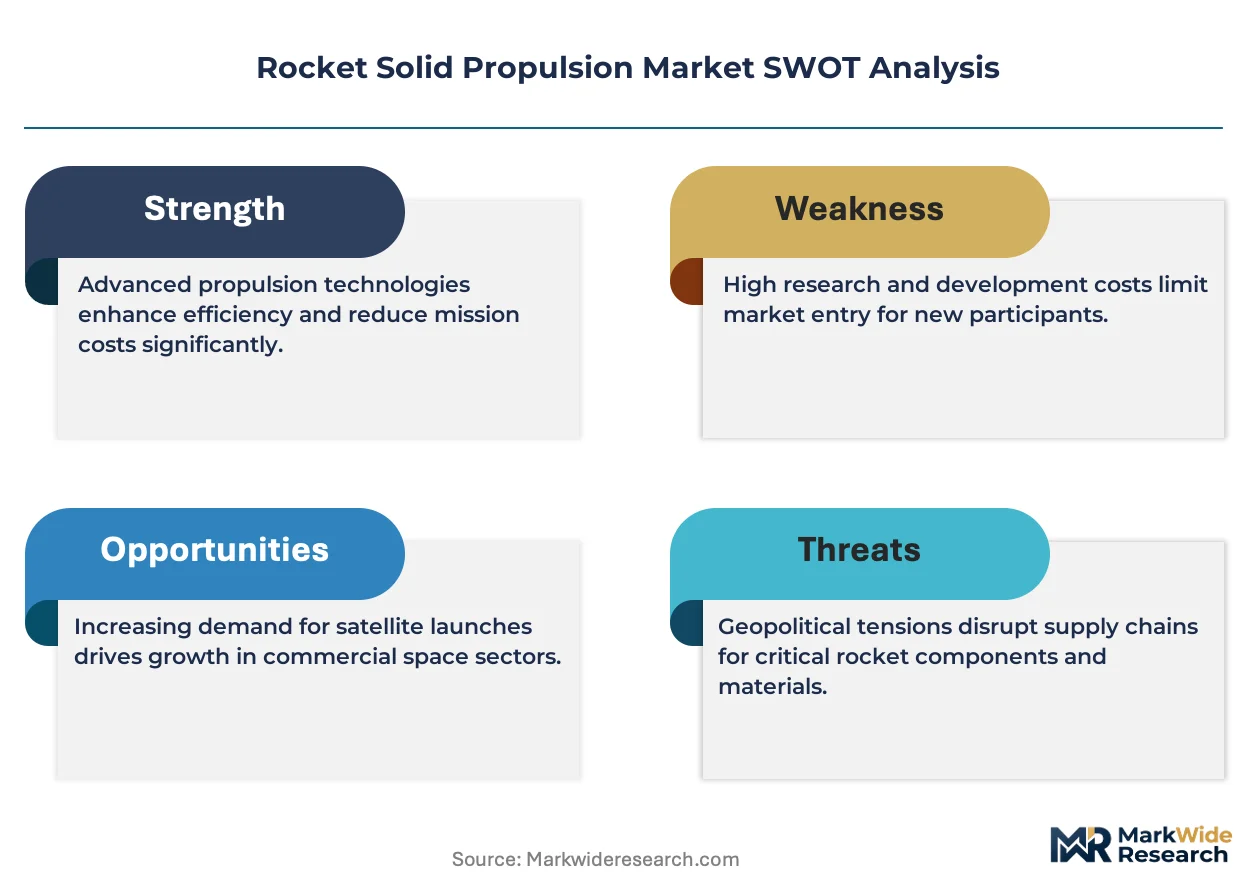
Perchlorate contamination liability is restructuring solid propellant supply chains as EPA enforcement under the Safe Drinking Water Act forces facilities toward chlorine-free oxidizer research before alternative chemistries achieve cost parity.
Growth Catalysts
- Tactical Missile Procurement:NATO defense ministries are expanding solid rocket motor inventories for precision-strike systems, sustaining multi-year production commitments.
- REACH Chemical Restrictions:European manufacturers are accelerating composite propellant R&D to maintain cross-border defense contract eligibility under evolving ECHA substance controls.
- Responsive Space Access:Commercial constellation operators are compressing launch schedules, creating pull demand for storable, rapid-response solid upper-stage kick motors.
Market Restraints
- Ammonium Perchlorate Supply Concentration:Domestic synthesis capacity clusters in Utah and Texas, creating single-point vulnerability for US strategic missile programs.
- Facility Siting Friction:EPA perchlorate monitoring protocols extend environmental review timelines for new grain casting plants by 18-24 months.
- Liquid Engine Substitution:Reusable launch vehicle developers favor liquid oxygen-kerosene architectures for cost-per-kilogram advantages in heavy-lift segments.
Strategic Opportunities
- Chlorine-Free Oxidizer Maturation:Ammonium dinitramide and hydroxylammonium nitrate formulations offer regulatory-compliant pathways for next-generation tactical motors.
- Automated Filament Winding:Continuous processing technologies reduce strategic missile lead times while improving grain geometry consistency.
- Small Satellite Kick Motors:Orbital transfer vehicle demand from commercial constellation deployers creates volume opportunities for standardized solid propulsion units.
Industry Challenges
- Propellant Chemist Talent Pipeline:Universities are graduating fewer specialists in energetic materials synthesis, constraining R&D velocity for novel oxidizer programs.
- MIL-STD-2105 Qualification Burden:Safety criteria testing for insensitive munitions compliance adds 12-18 months to new motor certification cycles.
- Legacy Equipment Retrofit Costs:Casting facilities must reconfigure automated winding systems without interrupting active Minuteman replacement production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rocket Solid Propulsion Market |
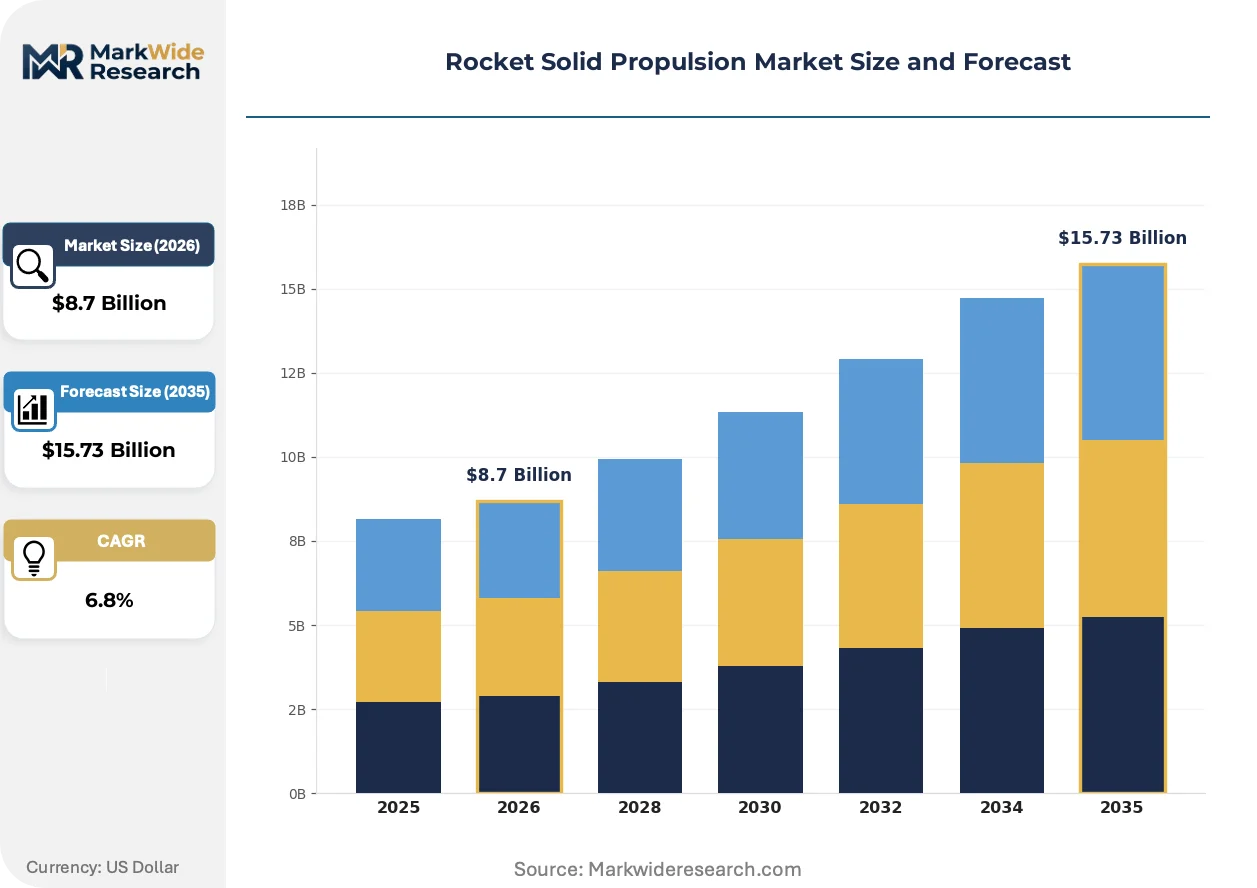
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propellant Type: Hydroxyl-terminated Polybutadiene, Ammonium Perchlorate, Composite Propellant, Metal Additives Application: Military, Space Exploration, Satellite Launch, Research End User: Government, Aerospace Companies, Defense Contractors, Research Institutions Capacity: Small Scale, Medium Scale, Large Scale, Custom Solutions |
| Companies Covered | China Aerospace Science and Technology Corporation, IHI Corporation, Northrop Grumman, Anduril Industries, Kratos Defense & Security Solutions, L3Harris Technologies, Rafael Advanced Defense Systems, ROKETSAN, Nammo AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rocket Solid Propulsion Market Evolving Landscape
Digital grain design tools and alternative oxidizer chemistry are converging to compress development cycles while environmental compliance pressures reshape formulation priorities.
Additive manufacturing of complex grain geometries is consolidating competitive positioning among propulsion houses with in-house simulation capabilities. Space Force launch providers are adopting topology-optimized star and wagon-wheel configurations to tailor thrust profiles for specific orbital insertion requirements. This capability is consolidating procurement decisions around suppliers with integrated computational fluid dynamics and rapid prototyping infrastructure.
EPA perchlorate maximum contaminant level deliberations are forcing formulation changes across the US supply base. The Safe Drinking Water Act regulatory pressure is accelerating ammonium dinitramide pilot programs despite higher raw material costs. Tactical motor manufacturers in the United States are responding by qualifying hybrid oxidizer blends that reduce chlorine content while maintaining ballistic performance.
Fixed-price milestone contracts are displacing cost-plus arrangements for strategic missile propulsion procurement. Defense agencies are transferring technical risk to prime contractors while demanding guaranteed delivery schedules for replacement motor production. This shift concentrates contract awards on vertically integrated suppliers with captive ammonium perchlorate synthesis and automated casting capabilities.
Rocket Solid Propulsion Market Segmentation
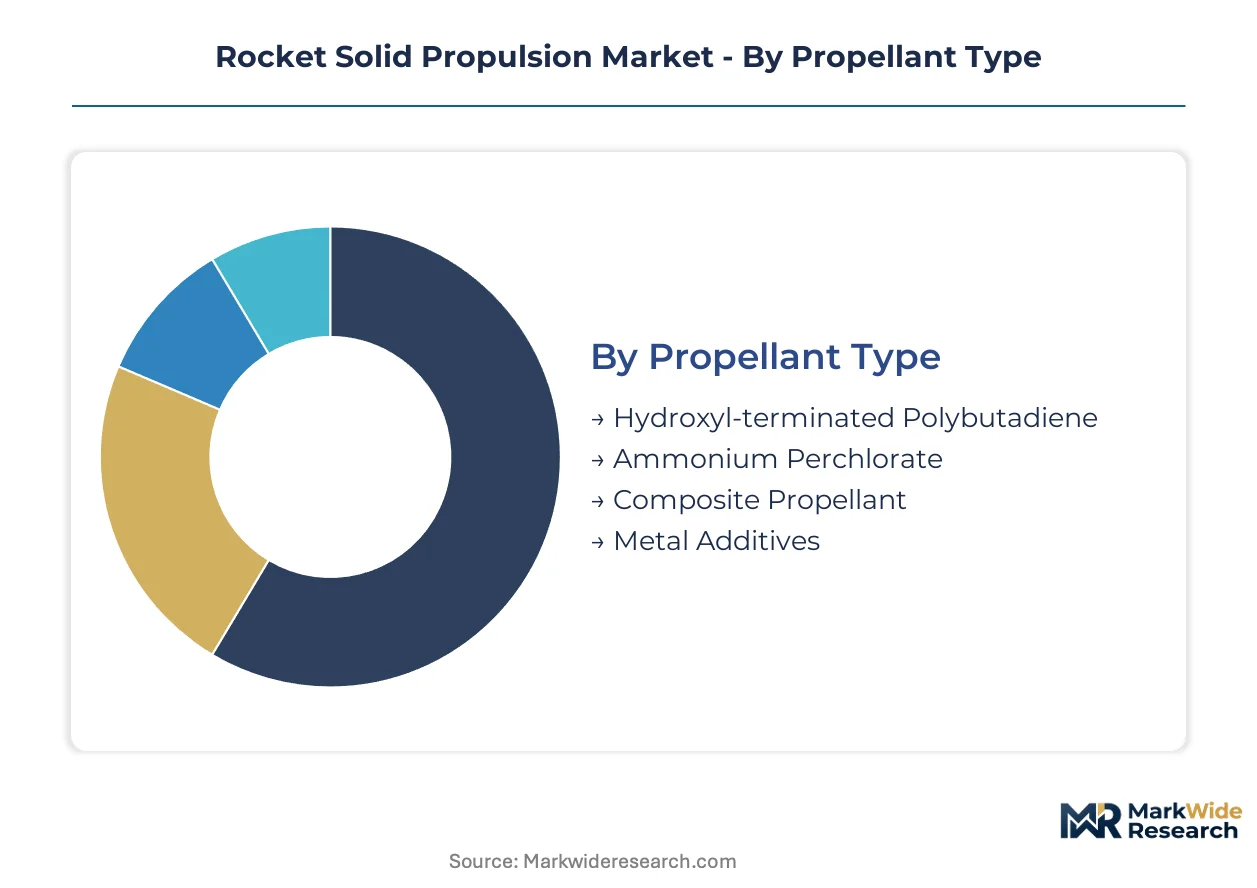
Solid propulsion procurement decisions pivot on chemical composition, mission profile, and scale economics. Segment boundaries blur as defense agencies demand dual-use motors serving both ballistic missile and responsive launch applications.
Propellant Type:
Composite formulations command premium margins while commodity oxidizers anchor volume production for legacy programs.
- Hydroxyl-terminated Polybutadiene:The dominant binder chemistry cross-links with isocyanate curatives to form elastomeric fuel matrices. United States strategic missile programs specify HTPB for its mechanical resilience across temperature extremes and predictable burn-rate characteristics. Utah casting facilities process thousands of tons annually for Minuteman replacement motors.
- Ammonium Perchlorate:Crystalline oxidizer supplying 34% oxygen by weight remains the workhorse for tactical and strategic applications despite environmental liability exposure. Domestic synthesis concentrates in Texas and Utah, creating supply vulnerability for NATO missile inventories. EPA perchlorate enforcement is accelerating substitution research before alternatives achieve cost parity.
- Composite Propellant:Tailored formulations combining crystalline oxidizers, metallic fuels, and polymeric binders enable mission-specific thrust profiles. European defense contractors favor composites for precision-strike motors under REACH substance restrictions.
- Metal Additives:Aluminum powder boosts specific impulse and combustion stability in upper-stage applications. Space Force launch providers specify 16-18% aluminum loading for kick motor performance.
Today's leader: Ammonium Perchlorate. Tomorrow's challenger: Composite Propellant.
Application:
Mission requirements dictate motor architecture, with storability and simplicity favoring solid systems over liquid alternatives.
- Military:Ballistic missiles, tactical rockets, and air-to-surface weapons constitute the foundational demand base. NATO procurement programs sustain multi-year production commitments for precision-strike inventories.
- Space Exploration:Crewed mission abort systems and planetary probe kick motors leverage solid reliability where failure tolerance is zero. NASA Artemis solid rocket boosters represent the largest-diameter grain casting in production.
- Satellite Launch:Commercial constellation deployment schedules compress, creating pull demand for storable upper-stage motors. Orbital transfer vehicles represent the steepest expansion trajectory among application segments.
- Research:Suborbital sounding rockets and university launch programs consume standardized small-diameter motors with rapid procurement cycles.
Defense procurement anchors current revenue. Commercial space access drives capacity expansion planning.
End User:
Contracting mechanisms diverge sharply between fixed-price commercial awards and cost-plus development programs.
- Government:Space Force, Missile Defense Agency, and NASA sustain multi-year propulsion modernization budgets with stringent MIL-STD-2105 qualification requirements.
- Aerospace Companies:Commercial launch providers seek standardized kick motors for constellation deployment, favoring suppliers with rapid-response production schedules.
- Defense Contractors:Prime systems integrators specify custom grain geometries for weapon platform integration, consolidating procurement around vertically integrated propulsion houses.
- Research Institutions:Universities and national laboratories pilot alternative oxidizer formulations with limited production runs and accelerated testing protocols.
Prime contractors capture integration value. Pure-play propulsion specialists defend component margins.
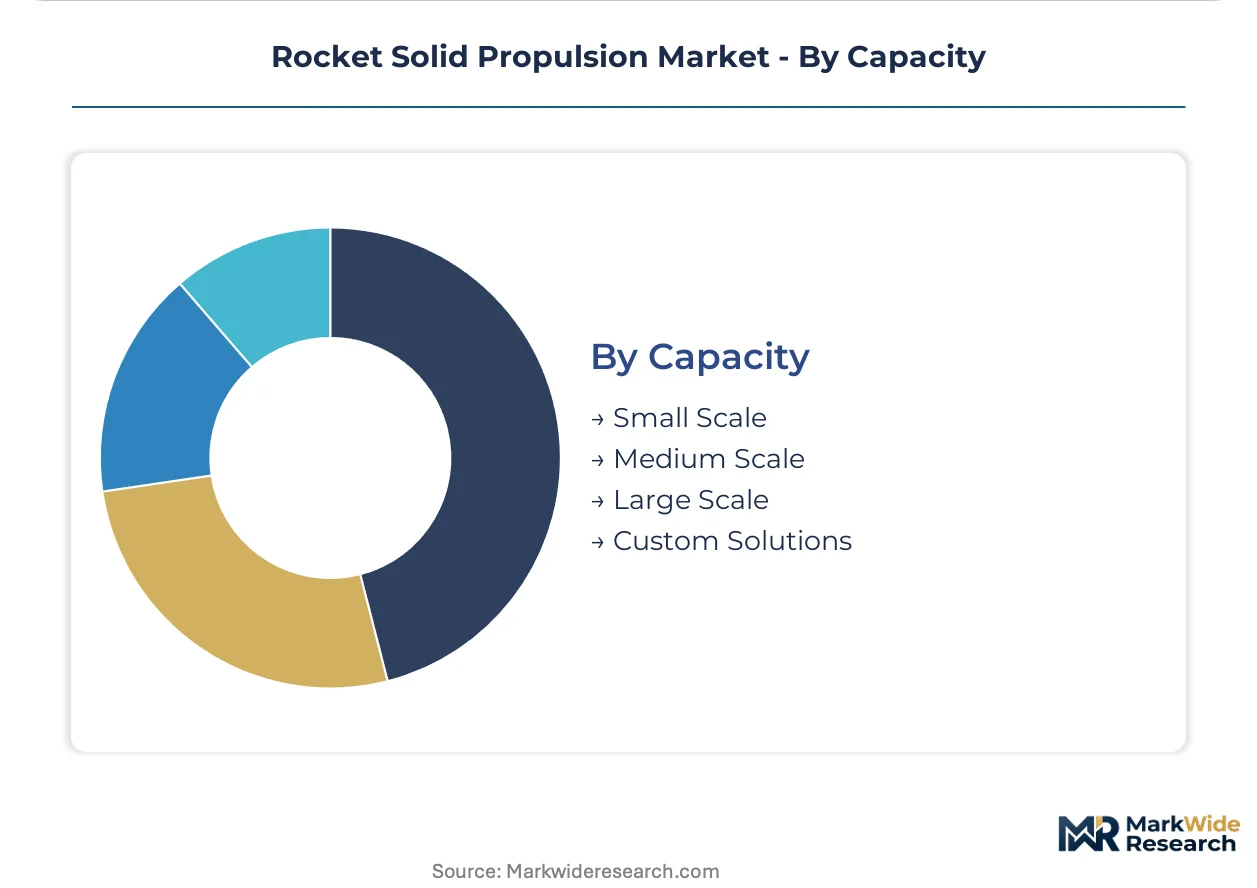
Capacity:
Scale economics favor large-diameter casting facilities, while small-batch flexibility serves responsive launch niches.
- Small Scale:Suborbital research motors and tactical training rounds utilize standardized 6-16 inch diameter grains with minimal customization.
- Medium Scale:Theater ballistic missiles and air-launched weapons occupy the mid-range, balancing performance tailoring with production efficiency.
- Large Scale:Strategic missile first stages and heavy-lift boosters require 60+ inch diameter casting and automated filament winding infrastructure concentrated in Utah.
- Custom Solutions:Mission-specific grain geometries and hybrid oxidizer blends serve experimental programs and rapid prototyping contracts.
Large-scale infrastructure locks in strategic programs. Custom solutions capture R&D premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as EPA perchlorate enforcement in the United States accelerates facility investments in jurisdictions with lighter environmental compliance burdens. Manufacturers are diversifying casting capacity across multiple regulatory zones to hedge against enforcement variance and qualification timeline extension.
United States
Space Force launch providers and Missile Defense Agency procurement sustain demand for large-diameter strategic motors. EPA Safe Drinking Water Act monitoring extends environmental review timelines for new grain casting facilities by 18-24 months. Utah hosts concentrated automated filament winding infrastructure serving Minuteman replacement programs.
China
Domestic launch capacity expansion and military modernization programs absorb in-house ammonium perchlorate synthesis output. MIIT standards and dual carbon goals shape facility emissions protocols without matching US perchlorate liability exposure. Xian and Beijing clusters integrate large-diameter grain casting with satellite constellation deployment schedules.
France
ArianeGroup solid booster production and independent tactical missile programs sustain composite propellant demand. REACH substance restrictions under ECHA jurisdiction accelerate chlorine-free oxidizer research among European defense contractors. The Bordeaux-Toulouse aerospace corridor concentrates grain design and testing infrastructure.
Israel
Precision-strike missile exports and domestic defense procurement maintain steady tactical motor consumption. National security-driven procurement regulations prioritize supply chain independence over cost minimization. Rafael Advanced Defense Systems anchors vertically integrated propulsion manufacturing in the central coastal region.
Japan
Space exploration missions and ballistic missile defense interceptors generate specialized solid motor requirements. METI industrial policy supports domestic propellant chemistry capabilities amid regional security tensions. Tanegashima and Uchinoura launch complexes drive demand for reliable upper-stage kick motors.
Rocket Solid Propulsion Market Competitive Landscape
United States producers anchor one tier; European and Israeli specialists hold differentiated positions in tactical segments. The vendor base clusters around vertically integrated defense primes with captive oxidizer synthesis and automated casting infrastructure. Three archetypes dominate: strategic missile houses with government-captive production lines, commercial launch providers seeking standardized kick motors, and regional defense contractors serving national procurement programs. Competitive moves concentrate on backward integration into ammonium perchlorate supply and automated filament winding capacity expansion.
Within the defense-prime tier, Northrop Grumman and China Aerospace Science and Technology Corporation exemplify vertically integrated architectures spanning oxidizer synthesis through final motor assembly. Nammo AS occupies a specialist position in European tactical propulsion. These three anchors represent divergent geographic and regulatory exposure profiles that shape their respective competitive positioning.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation |
| IHI Corporation |
| Northrop Grumman |
| Anduril Industries |
| Kratos Defense & Security Solutions |
| L3Harris Technologies |
| Rafael Advanced Defense Systems |
| ROKETSAN |
| Nammo AS |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense primes with captive oxidizer synthesis anchor pricing discipline across strategic motor programs, while their integrated casting infrastructure insulates procurement costs from ammonium perchlorate spot volatility. This ownership pattern concentrates bargaining power among Utah and Texas facilities serving Space Force multi-year commitments, compressing margins for non-integrated tactical motor specialists competing on fixed-price awards.
Pricing Analysis
Direct-to-government contracting eliminates distributor markups, concentrating margin capture at the prime contractor level. Three-tier pricing structure across strategic, tactical, and research-grade motors separates mission-critical ballistic programs from commoditized training rounds. Cost compression in tactical segments intensifies as fixed-price milestone contracts displace cost-plus arrangements. Research institutions exhibit highest price sensitivity, while strategic missile programs prioritize delivery certainty over unit cost.
Supply Chain Analysis
Ammonium perchlorate supply rests on domestic synthesis clusters in Utah and Texas, with European REACH-regulated producers and Chinese state-owned chemical complexes serving regional demand. Critical inputs span crystalline oxidizer feedstock, hydroxyl-terminated polybutadiene binder, and aluminum powder metallic fuel. Single-source vulnerability concentrates in domestic perchlorate synthesis capacity, where EPA enforcement threatens operational continuity. Distribution runs through defense-prime captive facilities and qualified subcontractor networks under MIL-STD-2105 protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where EPA Safe Drinking Water Act perchlorate enforcement is restructuring formulation economics and accelerating chlorine-free oxidizer procurement.
For Market Incumbents: Anchor strategic positioning through backward integration into ammonium perchlorate synthesis and automated filament winding capacity expansion in Utah. Defend against liquid engine substitution in heavy-lift segments by emphasizing storability advantages for responsive launch architectures. Prioritize MIL-STD-2105 qualification pipeline investment to compress certification cycles for next-generation motors. For New Entrants and Emerging Players: Begin with small satellite kick motor standardization for commercial constellation deployers, where rapid-response production schedules favor agile specialists over defense-prime bureaucracy. Target orbital transfer vehicle demand from SpaceX and Amazon Kuiper procurement teams. Pursue ESA member-state defense contracts under REACH-compliant composite propellant qualifications. For Investors and Strategic Acquirers: Defense primes with propulsion gaps are the most active acquirer in this space, seeking vertical completion through tactical motor specialists. Long-term viability hinges on regulatory arbitrage positioning as EPA enforcement intensifies. Watch chlorine-free oxidizer pilot program scale-up at European and Israeli defense contractors as inflection indicator for formulation transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Chlorine-Free Oxidizer Scale-Up | Ammonium dinitramide pilot programs at Nammo AS and Rafael Advanced Defense Systems demonstrate regulatory-compliant pathway viability. |
| Automated Filament Winding Expansion | Northrop Grumman's Utah infrastructure investments reduce Minuteman replacement motor lead times while improving grain consistency. |
| Small Satellite Kick Motor Standardization | Commercial constellation deployers create volume pull for storable, rapid-response solid upper-stage units. |
| REACH-Compliant Composite R&D | European defense contractors accelerate formulation work to maintain cross-border contract eligibility under ECHA substance controls. |
| Fixed-Price Contract Capability Build | Defense agencies transfer technical risk to primes, concentrating awards on vertically integrated suppliers with captive oxidizer synthesis. |
Research Methodology
Coverage spans the United States, China, France, Israel, and Japan, with primary inputs from each propulsion manufacturing cluster. The analysis combines structured interviews with solid rocket motor program managers, propellant chemists at national laboratories, defense procurement officers, and commercial launch provider engineering directors with secondary validation from FAA launch licensing databases, EPA Safe Drinking Water Act enforcement records, ECHA REACH substance restriction updates, and DoD budget justification materials. Bottom-up segment sizing triangulates against top-down defense expenditure allocation models.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include propellant chemistry type, application mission profile, end-user contracting mechanism, and casting facility scale tier. CAGRs derive from production run-rate analysis and procurement commitment visibility. Industry-specific forecast inputs incorporate Space Force launch manifest density and Missile Defense Agency interceptor inventory targets.
Several conditions sit outside the modeled scope, including classified strategic missile production rates and perchlorate remediation liability quantification. Forecasts reflect documented assumptions about regulatory enforcement timing and alternative oxidizer cost parity achievement. A small set of named triggers warrants ongoing watch: EPA maximum contaminant level finalization, ammonium dinitramide pilot program scale-up, and European defense procurement consolidation under NATO capability targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Global Landing String Equipment Market