
 Middle-East and Africa Battery Cell Market | 2026-2036
Middle-East and Africa Battery Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Battery Cell Market Foresight
Market Context
The capital-intensity divergence between integrated cell manufacturers and pack assemblers is redrawing competitive boundaries across the Middle-East and Africa. BYD Co Ltd leverages captive mining-to-cell verticality to undercut regional pricing floors on lithium-iron-phosphate systems. Contemporary Amperex Technology Co Limited anchors its position through binding offtake agreements with Saudi and Emirati utility developers. LG Energy Solution Ltd competes by licensing high-nickel cathode formulations to local joint ventures seeking technology transfer.
Technical and Segment Structure
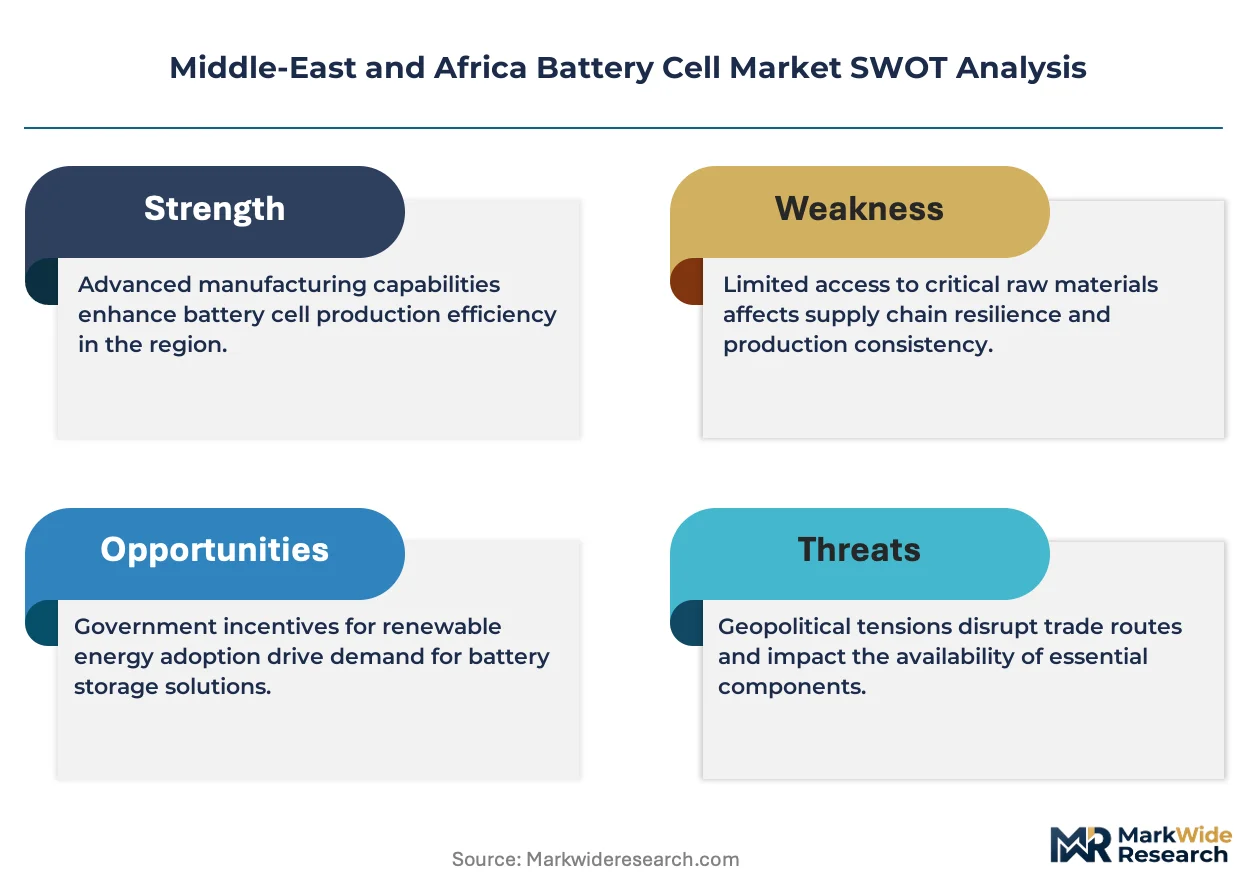
A battery cell is an electrochemical device comprising anode, cathode, separator, and electrolyte engineered to deliver reversible energy storage through controlled ion transfer, with nominal voltages ranging from 3.2 V for lithium-iron-phosphate to 4.2 V for nickel-cobalt-manganese variants. Its primary purpose is to serve as the foundational energy unit within modules and packs for mobility, grid stabilization, and portable power systems. Lithium-ion chemistry dominates installed capacity given superior gravimetric density, though lead-acid retains share in telecom backup applications where capex sensitivity outweighs cycle-life requirements. Solid-state technology draws disproportionate R&D allocation from automotive OEMs seeking thermal runaway elimination, while flow batteries occupy niche utility-scale duration segments above four hours.
Regulatory Environment and Outlook
Saudi Arabia's Saudi Standards, Metrology and Quality Organization and South Africa's National Regulator for Compulsory Specifications enforce cell safety and transport protocols that determine market access for imported products. The UAE's Emirates Authority for Standardization and Metrology mandates product registration and local testing for grid-connected storage systems, creating compliance moats for established suppliers. Stakeholders must monitor evolving domestic content requirements and carbon border adjustments that will determine whether local cell assembly or continued importation of finished packs delivers superior landed cost positions.
Market Dynamics
Capital concentration in Saudi and Emirati gigafactory zones is compressing procurement timelines for utility-scale storage, forcing pack assemblers to choose between captive cell supply and stranded capacity risk.
Growth Catalysts
- Solar-plus-storage mandates:UAE regulatory requirements for renewable pairing are pulling lithium-iron-phosphate volumes into grid stabilization contracts. Developers must procure cells meeting Emirates Authority for Standardization and Metrology protocols.
- Carbon pricing mechanisms:South Africa's escalating carbon tax is accelerating battery energy storage system deployments at mining and industrial facilities seeking load-shifting arbitrage.
- Public transit electrification:Fleet procurement specifications across Dubai and Riyadh are specifying high-cycle-life cells for electric bus rapid transit corridors operating in extreme thermal conditions.
Market Restraints
- Lithium carbonate volatility:Raw material price swings transmitted from Chilean and Australian concentrate markets are compressing margin visibility for regional pack integrators lacking long-term offtake hedges.
- Cell import dependency:Absence of localized cathode active material production concentrates supply risk on Asian manufacturing hubs subject to shipping lane disruptions through the Red Sea corridor.
- Lead-acid substitution lock-in:Telecom tower operators in Nigeria and Kenya continue specifying flooded lead-acid for backup power given capex constraints and established maintenance infrastructure.
Strategic Opportunities
- Second-life automotive cells:Retired electric vehicle battery packs from European fleets are entering refurbishment channels for stationary storage applications in Moroccan and Egyptian industrial zones.
- Flow battery duration segments:Vanadium redox systems are capturing four-to-eight-hour utility contracts in South Africa's renewable energy procurement program where lithium-ion economics degrade.
- Local assembly incentives:Saudi Industrial Development Fund financing is enabling joint ventures to establish module and pack assembly lines serving Gulf Cooperation Council markets with reduced import duty exposure.
Industry Challenges
- Thermal management engineering scarcity:Cell system designers capable of optimizing passive and active cooling architectures for 50°C ambient operation are concentrated in East Asian and European labor markets.
- Multi-standard certification timelines:Products must sequentially satisfy Saudi Standards, Metrology and Quality Organization safety protocols, UAE product registration requirements, and South African National Regulator for Compulsory Specifications transport rules before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Battery Cell Market |
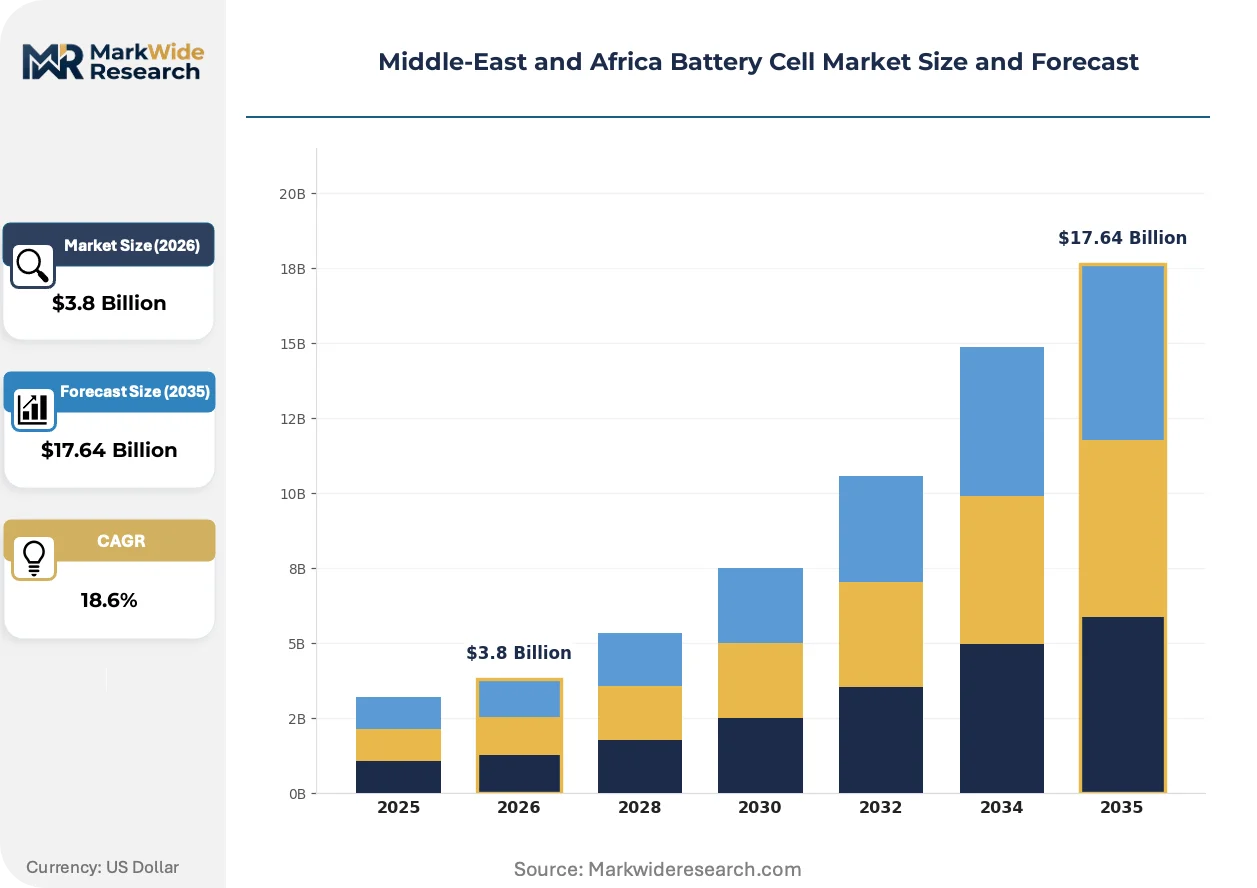
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Flow Batteries Application: Electric Vehicles, Consumer Electronics, Industrial Machinery, Renewable Energy Storage End User: Automotive OEMs, Telecom Providers, Power Utilities, Electronics Manufacturers Technology: Solid-State, Carbon-Based, Advanced Lead-Carbon, Hybrid Systems |
| Companies Covered | BYD Co Ltd, Contemporary Amperex Technology Co Limited, LG Energy Solution Ltd, Panasonic Corporation, EnerSys, Clarios, Saft Groupe S A, GS Yuasa Corporation, Samsung SDI Co., Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Battery Cell Market Shifts & Advancements
Electrochemical system architectures and procurement frameworks are undergoing simultaneous transformation as thermal constraints and financing structures reshape technical specifications.
Sodium-ion chemistry is miniaturizing from grid-scale prototypes into commercial formats for stationary storage applications where energy density requirements are relaxed. Saudi utility developers are piloting sodium-ion cells for solar-plus-storage installations where lithium cost volatility threatens project returns. This chemistry is miniaturizing the cost premium between imported lithium-ion packs and locally assembled alternatives, compressing payback periods for domestic manufacturing investments.
Saudi Standards, Metrology and Quality Organization is enforcing updated cell safety and transport protocols that mandate UN 38.3 testing documentation for all imported lithium-ion products. Industrial developers must now submit comprehensive thermal runaway propagation test data before receiving grid interconnection approvals. Large-scale storage projects in Riyadh and Jeddah industrial corridors are experiencing extended commissioning timelines as engineering teams adapt documentation packages to these requirements.
Energy-as-a-service contracting is displacing traditional equipment purchase models for commercial and industrial battery installations across South African mining operations. Engineering procurement construction firms are retaining asset ownership and selling guaranteed demand charge reductions to offtakers. This structure concentrates performance risk on technology providers while accelerating deployment velocity at platinum and gold extraction facilities seeking power cost stability.
Middle-East and Africa Battery Cell Market Segmentation
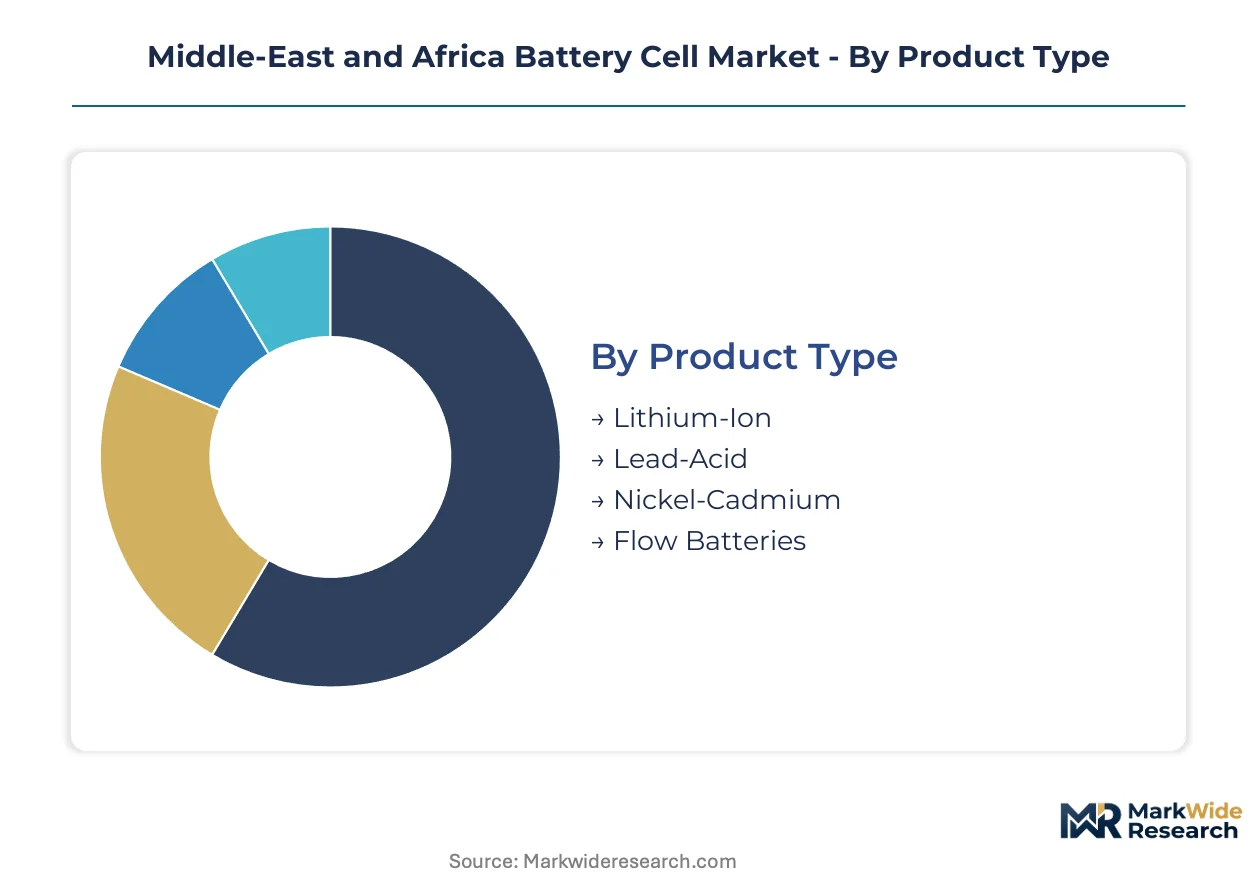
Segmentation in the Middle-East and Africa battery cell market exposes how procurement specifications diverge across climates, financing structures, and regulatory jurisdictions. Understanding these fault lines enables suppliers to align product portfolios with where capital is actually deploying.
Product Type:
Lithium-ion chemistry commands the widest margin pools given its dominance in utility-scale and mobility contracts, while lead-acid retains defensive profitability in price-sensitive backup applications.
- Lithium-Ion:Electrochemical systems utilizing lithium iron phosphate or nickel-cobalt-manganese cathodes deliver 3.2-4.2 V nominal outputs with superior cycle life. Demand concentrates in UAE solar-plus-storage mandates where Emirates Authority for Standardization and Metrology certification requirements filter out uncertified suppliers.
- Lead-Acid:Flooded and valve-regulated designs using lead dioxide and sponge lead electrodes provide 2 V nominal cells with established recycling infrastructure. Procurement persists across Nigerian and Kenyan telecom towers where capex constraints override total cost-of-ownership calculations.
- Nickel-Cadmium:Alkaline storage systems with nickel oxide hydroxide cathodes and cadmium anodes tolerate extreme temperature swings. Aviation and rail signaling applications in Saudi Arabia specify these cells for reliability in 50°C ambient conditions.
- Flow Batteries:Vanadium redox and zinc-bromine architectures decouple power and energy ratings through external electrolyte tanks. South Africa's renewable energy procurement program awards four-to-eight-hour duration contracts where lithium-ion economics degrade.
The dominant share belongs to Lithium-Ion, while Flow Batteries is closing the gap fastest in utility-scale duration segments.
Application:
Application-based margin distribution tracks electrification policy intensity, with electric vehicles and renewable storage capturing premium pricing versus commoditized consumer electronics.
- Electric Vehicles:High-discharge-rate cells engineered for 800V architectures and thermal management in extreme climates. Fleet procurement specifications across Dubai and Riyadh bus rapid transit corridors are specifying high-cycle-life chemistries for desert operation.
- Renewable Energy Storage:Grid-stabilization systems with four-hour to multi-day discharge capabilities co-located with solar assets. Saudi gigafactory zones are compressing procurement timelines for utility-scale developers seeking captive cell supply.
- Consumer Electronics:Cylindrical and pouch formats optimized for energy density in portable devices. Distribution runs through electronics retail channels in South Africa and UAE where import duty structures favor assembled packs over bare cells.
- Industrial Machinery:Heavy-duty traction and starter batteries for mining equipment and material handling. South African platinum and gold extraction facilities are deploying energy-as-a-service contracts to hedge power cost volatility.
Renewable Energy Storage holds the dominant position, with Electric Vehicles expanding most quickly as transit electrification mandates proliferate across Gulf Cooperation Council capitals.
End User:
End user segmentation reveals how procurement authority concentrates in entities with balance sheet capacity to underwrite long-duration storage assets.
- Power Utilities:State-owned and independent power producers procuring cells for grid-scale storage and ancillary services. Saudi and Emirati utilities are binding offtake agreements that lock in supply through 2030 commissioning windows.
- Automotive OEMs:Vehicle manufacturers integrating cells into electric bus, truck, and passenger vehicle platforms. Local assembly incentives from Saudi Industrial Development Fund are enabling joint ventures to serve GCC markets with reduced import exposure.
- Telecom Providers:Mobile network operators specifying backup power for base stations and data centers. MTN and Airtel operations in Nigeria continue specifying flooded lead-acid given established maintenance infrastructure.
- Electronics Manufacturers:Device assemblers sourcing cells for laptops, power tools, and medical equipment. These buyers prioritize UN 38.3 documentation and Saudi Standards, Metrology and Quality Organization transport compliance for cross-border supply chains.
Power Utilities command the dominant share, while Automotive OEMs is gaining share fastest as domestic manufacturing incentives reshape procurement geography.
Technology:
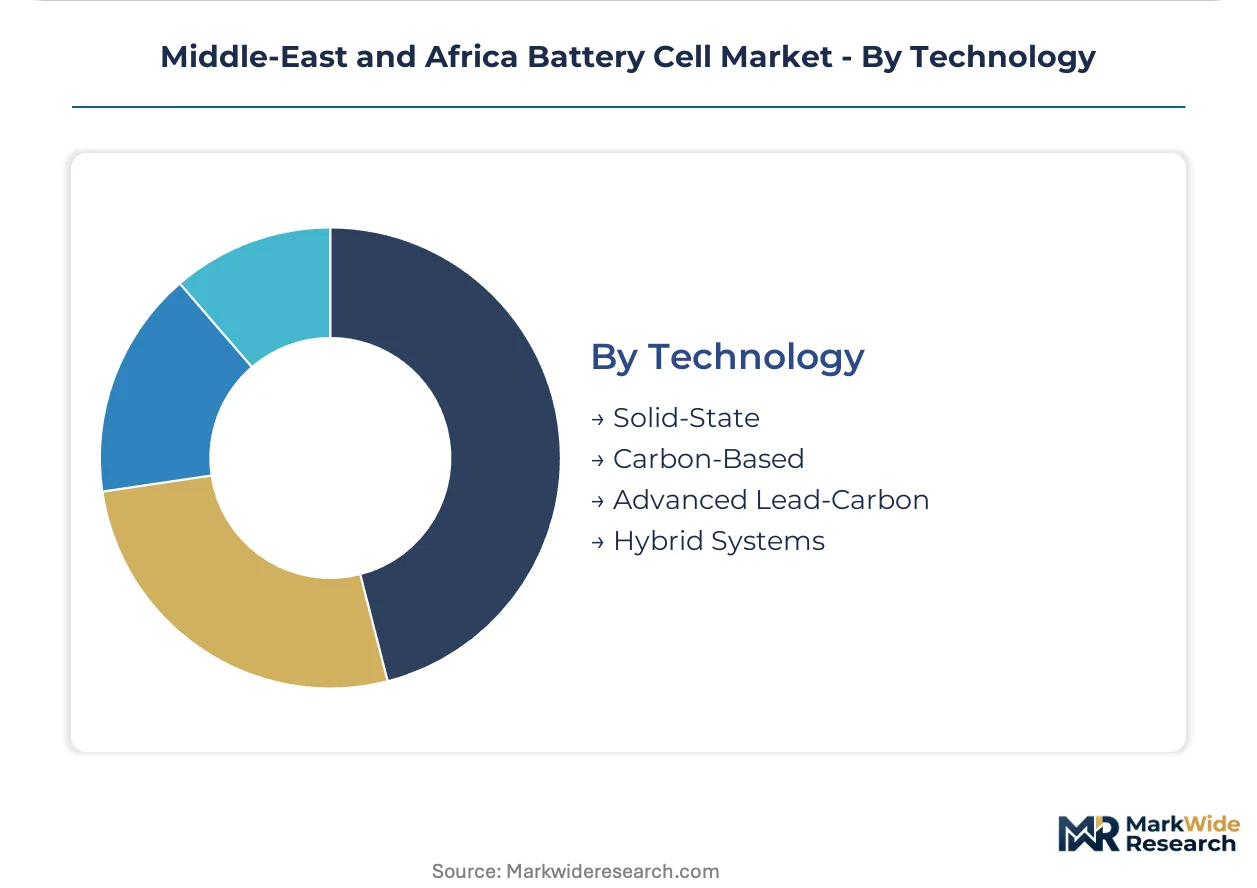
Technology-based segmentation tracks R&D allocation intensity, with solid-state and hybrid systems capturing development capital while carbon-based approaches defend incumbent positions.
- Solid-State:Cells replacing liquid electrolytes with ceramic or polymer ionic conductors to eliminate thermal runaway risk. Automotive OEMs are directing disproportionate R&D allocation toward these architectures for next-generation electric bus fleets.
- Hybrid Systems:Architectures combining lithium-ion with ultracapacitors or fuel cells to optimize power-energy ratios. Saudi utility developers are piloting these configurations for solar-plus-storage installations seeking enhanced ramp-rate response.
- Carbon-Based:Lithium-ion anodes utilizing synthetic or natural graphite intercalation compounds. These electrodes dominate current production volumes given established supply chains from Asian manufacturing hubs.
- Advanced Lead-Carbon:Enhanced lead-acid designs incorporating carbon additives to improve partial state-of-charge cycling. Telecom backup applications in Kenya are evaluating these as a bridge technology between flooded lead-acid and lithium-ion economics.
Carbon-Based technology retains the dominant installed base, though Solid-State is climbing the fastest as thermal safety requirements tighten across Saudi and UAE regulatory frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle-East and Africa battery cell market operates through a pronounced import dependency, with finished cell volumes flowing predominantly from Asian manufacturing hubs while regional assembly capacity concentrates in Saudi and Emirati industrial zones. This trade configuration shapes procurement timelines, compliance architectures, and domestic content negotiations across the analysis window.
United Arab Emirates
Solar-plus-storage mandates from the Emirates Authority for Standardization and Metrology are pulling lithium-iron-phosphate volumes into grid stabilization contracts at scale. Dubai's gigafactory investments are compressing procurement timelines for utility developers seeking captive cell supply. The Jebel Ali industrial corridor hosts module and pack assembly lines serving Gulf Cooperation Council markets with reduced import duty exposure.
Saudi Arabia
Carbon pricing mechanisms and renewable energy procurement regulations are accelerating utility-scale storage deployments across mining and industrial facilities. The Saudi Standards, Metrology and Quality Organization enforces updated cell safety protocols mandating UN 38.3 testing documentation for all imported lithium-ion products. Riyadh and Jeddah industrial corridors are experiencing extended commissioning timelines as engineering teams adapt thermal runaway propagation test data to these requirements.
South Africa
Escalating carbon tax structures are accelerating battery energy storage system deployments at platinum and gold extraction facilities seeking load-shifting arbitrage. The National Regulator for Compulsory Specifications enforces transport protocols that determine market access for imported products. Energy-as-a-service contracting is displacing traditional equipment purchase models across mining operations in the Bushveld Complex.
Egypt
Second-life automotive cells from European electric vehicle fleets are entering refurbishment channels for stationary storage applications in industrial zones. The country's national standards body is developing product registration frameworks for grid-connected storage systems. The Suez Canal Economic Zone is attracting pack assembly investments seeking re-export positioning to African markets.
Nigeria
Telecom tower operators continue specifying flooded lead-acid for backup power given capex constraints and established maintenance infrastructure. The national communications commission is evaluating backup power standards for base station resilience. Lagos and Abuja logistics corridors are consolidating distribution channels for imported battery packs serving West African markets.
Middle-East and Africa Battery Cell Market Competitive Landscape
Concentration sits with integrated cell manufacturers possessing captive mining-to-cell verticality, while pack assemblers compete on procurement velocity and local certification navigation. The vendor base fragments across three strategic archetypes: Asian conglomerates with full vertical integration, European specialists in high-nickel chemistries, and regional joint ventures seeking technology transfer through licensing arrangements. Competitive positioning hardens through binding offtake agreements with utility developers and strategic partnerships with industrial facility operators seeking power cost stability.
Within the integrated manufacturer tier, BYD Co Ltd and Contemporary Amperex Technology Co Limited exemplify archetypes of backward integration into raw material supply chains. LG Energy Solution Ltd occupies a position among technology licensors seeking joint venture structures for regional market access. These three entities represent distinct strategic postures: captive supply chain control, scale-driven manufacturing economics, and partnership-based technology transfer.
| Leading Market Players |
|---|
| BYD Co Ltd |
| Contemporary Amperex Technology Co Limited |
| LG Energy Solution Ltd |
| Panasonic Corporation |
| EnerSys |
| Clarios |
| Saft Groupe S A |
| GS Yuasa Corporation |
| Samsung SDI Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ninety-day cathode active material lead times from Asian manufacturing hubs compress margin visibility for regional pack integrators and concentrate pricing power with vertically integrated cell producers possessing captive lithium carbonate positions. This inventory dynamic shapes how procurement teams balance spot market exposure against long-term offtake commitments across Middle-East and African deployment corridors.
Pricing Analysis
The customization-premium spread between configured-to-order lithium-iron-phosphate systems and standard nickel-cobalt-manganese packs runs wide across utility-scale tenders, with project-based contract structures dominating procurement frameworks. Price differentiation stems from Emirates Authority for Standardization and Metrology certification tiers and volume scale commitments exceeding hundred-megawatt-hour thresholds. Pricing pressure stems from lithium carbonate volatility transmitted from Chilean and Australian concentrate markets, compressing margins for pack assemblers lacking upstream hedging instruments. State-owned utilities in Saudi Arabia and the United Arab Emirates exhibit lowest price sensitivity given sovereign balance sheet capacity, while Nigerian telecom tower operators demonstrate acute capex constraints favoring flooded lead-acid alternatives.
Supply Chain Analysis
Ninety-day cathode active material inventories concentrate supply risk on Chinese, South Korean, and Japanese manufacturing hubs subject to Red Sea shipping lane disruptions. Cell production draws from lithium carbonate, cobalt hydroxide, and synthetic graphite feedstocks anchored in Australian mining operations and Indonesian processing facilities. Supply chain risk centers on single-source vulnerability for high-nickel cathode formulations licensed through limited technology transfer agreements. Distribution runs through Jebel Ali and Riyadh industrial corridor assembly lines serving Gulf Cooperation Council markets with reduced import duty exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs deep across this market as solar-plus-storage mandates and transit electrification specifications proliferate, creating specialized niches for chemistry-specific suppliers and thermal management engineering capabilities.
For Market Incumbents: Compound defensive positioning through binding offtake agreements with Saudi and Emirati utility developers seeking supply security through commissioning windows. Deepen backward integration into lithium carbonate positions to undercut regional pricing floors threatened by BYD's captive mining-to-cell verticality. Prioritize certification investment in Saudi Standards, Metrology and Quality Organization protocols to extend compliance moats against emerging Asian competitors. For New Entrants and Emerging Players: Emirates Authority for Standardization and Metrology certification fast-tracks unlock grid-connected storage procurement channels currently filtering out uncertified suppliers. Target South African mining energy-as-a-service contracts where performance risk concentration favors technology providers with thermal management engineering capabilities. Penetrate Moroccan and Egyptian second-life automotive cell refurbishment channels as the most accessible white-space entry point. Deploy modular pack assembly partnerships with Saudi Industrial Development Fund financing to reduce import duty exposure across Gulf Cooperation Council markets. For Investors and Strategic Acquirers: Long-term, this sits as a utility-scale infrastructure play because sovereign renewable mandates and carbon pricing mechanisms institutionalize demand visibility across the analysis window. Acquisition target archetype: regional joint ventures with established module assembly lines and active technology licensing negotiations with Korean or Japanese cell producers. Watch sodium-ion chemistry pilot outcomes at Saudi solar-plus-storage installations as the inflection signal for domestic manufacturing investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Joint ventures with LG Energy Solution unlock high-nickel cathode formulations for Saudi gigafactory zones. |
| Backward Integration into Cathode Materials | Captive lithium-iron-phosphate powder production compresses landed cost positions against Chinese imports. |
| Energy-as-a-Service Platform Launch | Asset ownership models concentrate performance risk while accelerating deployment at South African mining facilities. |
| Second-Life Cell Refurbishment Network | European electric vehicle pack refurbishment channels address stationary storage demand in Moroccan industrial zones. |
| UN 38.3 Certification Program | Comprehensive thermal runaway documentation satisfies Saudi Standards, Metrology and Quality Organization grid interconnection requirements. |
Research Methodology
A standing panel of utility procurement officers, battery energy storage system EPC contractors, cathode material procurement leads, and thermal management engineering directors provided ongoing calibration across primary interview rounds. Secondary validation drew from Saudi Standards, Metrology and Quality Organization filing databases, Emirates Authority for Standardization and Metrology product registration records, South African National Regulator for Compulsory Specifications transport protocols, customs trade data tracking cell import volumes, and utility tender documentation from renewable energy procurement programs. Bottom-up cell deployment estimates triangulated against top-down market sizing derived from gigafactory capacity announcements and binding offtake disclosure.
Consistency checks validated volume and value outputs against external benchmarks including IEA battery demand projections, BNEF utility-scale storage deployment trackers, and regional carbon pricing mechanism impact assessments. The analytical framework modeled chemistry type, application segment, end-user category, and technology architecture dimensions across the projection horizon. CAGRs were derived from logistic diffusion curves fitted to procurement timeline compression observed in Saudi and Emirati gigafactory zones. Industry-specific forecast inputs incorporated solar-plus-storage mandate implementation schedules and mining sector energy-as-a-service contract velocity.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate price stability, Red Sea shipping lane continuity, and sovereign renewable procurement commitment would require recalibration. Forecasts reflect documented assumptions regarding technology transfer licensing velocity and domestic content requirement evolution. Raw material price volatility, regulatory documentation timeline extensions, and thermal management engineering labor scarcity constitute specific risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Stretchable Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Modular Battery Market
Batteries
North America NMC Battery Pack Market
Batteries
South America Battery Cell Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Battery Plate Market
Batteries
North America Industrial Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Residential Battery Market
Batteries
Battery Materials Market
Batteries
Battery Cell Market
Batteries
Power Battery Cells Market