
 Middle East Flooring and Carpet Market | 2026-2036
Middle East Flooring and Carpet Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Flooring and Carpet Market Foresight
The gap between hand-knotted Persian carpets and machine-made broadloom rolls is realigning procurement patterns across the Middle East. Oriental Weavers leverages Egyptian manufacturing scale to dominate machine-made exports. Abdullatif Carpets anchors Saudi Arabia's domestic supply chain through captive dyeing and tufting operations. Al Sorayai Group differentiates via vertical integration into wool sourcing and custom hospitality installations.
Middle East flooring and carpet encompasses woven, tufted, and resilient surface products engineered for thermal insulation, acoustic dampening, and interior aesthetics in commercial and residential built environments. Broadloom carpets deliver seamless wall-to-wall coverage through heat-set nylon or polypropylene fiber systems, while carpet tiles permit modular replacement and reduced installation waste. Vinyl flooring leads commercial retrofit activity due to moisture resistance and low maintenance profiles, whereas wool-based products command premium residential specification. Hospitality end-user demand concentrates in luxury hotel developments across the Gulf, driving thicker pile weights and custom patterning.
Saudi Standards, Metrology and Quality Organization (SASO) mandates fire-resistance testing and formaldehyde emission limits for interior finishes, filtering import eligibility and local production compliance. The Emirates Authority for Standardization and Metrology (ESMA) enforces UAE-specific labeling and performance benchmarks that shape distributor sourcing decisions. Stakeholders must monitor evolving green building rating adoption across Gulf municipalities, as LEED and Estidama compliance increasingly dictates material specification in premium developments.
Market Dynamics
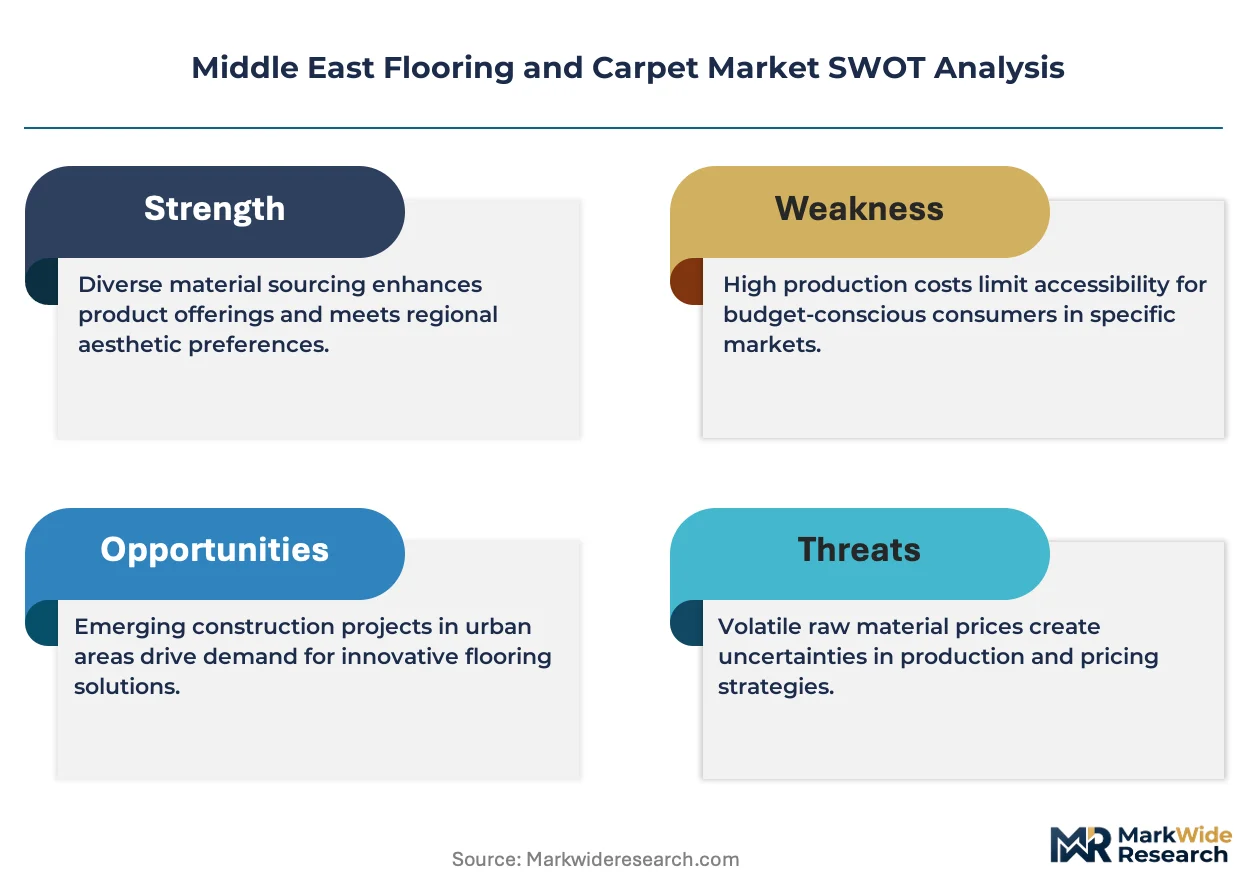
SASO fire-resistance mandates and formaldehyde emission limits are compressing import eligibility windows while forcing domestic manufacturers toward captive testing infrastructure, fundamentally restructuring competitive access in Gulf flooring supply.
Growth Catalysts
- Hospitality Construction Pipeline:Luxury hotel developments across Dubai, Riyadh, and Doha are specifying thicker pile weights and custom patterning, pulling volume toward broadloom and Axminster systems.
- ESMA Labeling Convergence:The Emirates Authority for Standardization and Metrology is harmonizing UAE-specific performance benchmarks with SASO technical requirements, reducing dual-certification burdens for regional distributors.
- Modular Installation Preference:Carpet tile specification is accelerating in commercial retrofit segments due to reduced waste profiles and zone-specific replacement economics.
Market Restraints
- Wool Input Volatility:New Zealand and Australian wool auction prices fluctuate with climate-driven yield variations, compressing margin stability for premium residential manufacturers.
- Import Concentration Risk:Chinese polypropylene fiber supply dominates machine-made carpet backing, exposing regional converters to shipping rate spikes and customs clearance delays.
- Technical Substitution Pressure:Luxury vinyl tile and rigid core SPC flooring are capturing specification share in moisture-prone commercial applications previously reserved for broadloom.
Strategic Opportunities
- Kuwait Residential Underpenetration:Post-pandemic housing stock expansion in Kuwait City and Jahra is outpacing local carpet distribution infrastructure, creating whitespace for direct-to-developer supply contracts.
- Estidama Material Credits:Abu Dhabi's green building rating system awards points for low-VOC finishes and recycled content, incentivizing specification of cradle-to-cradle certified carpet tile.
- Digital Specification Platforms:BIM-integrated product libraries are compressing architect decision cycles, enabling manufacturers to embed performance data directly into design-phase material schedules.
Industry Challenges
- Fire-Testing Bottlenecks:SASO-accredited laboratory capacity in Riyadh and Jeddah is constrained, extending product approval timelines from weeks to months for imported broadloom.
- Installation Skill Scarcity:Seamless wall-to-wall fitting and pattern-matching for hand-tufted hospitality products requires specialized craft labor that training pipelines across the GCC have failed to replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Flooring and Carpet Market |
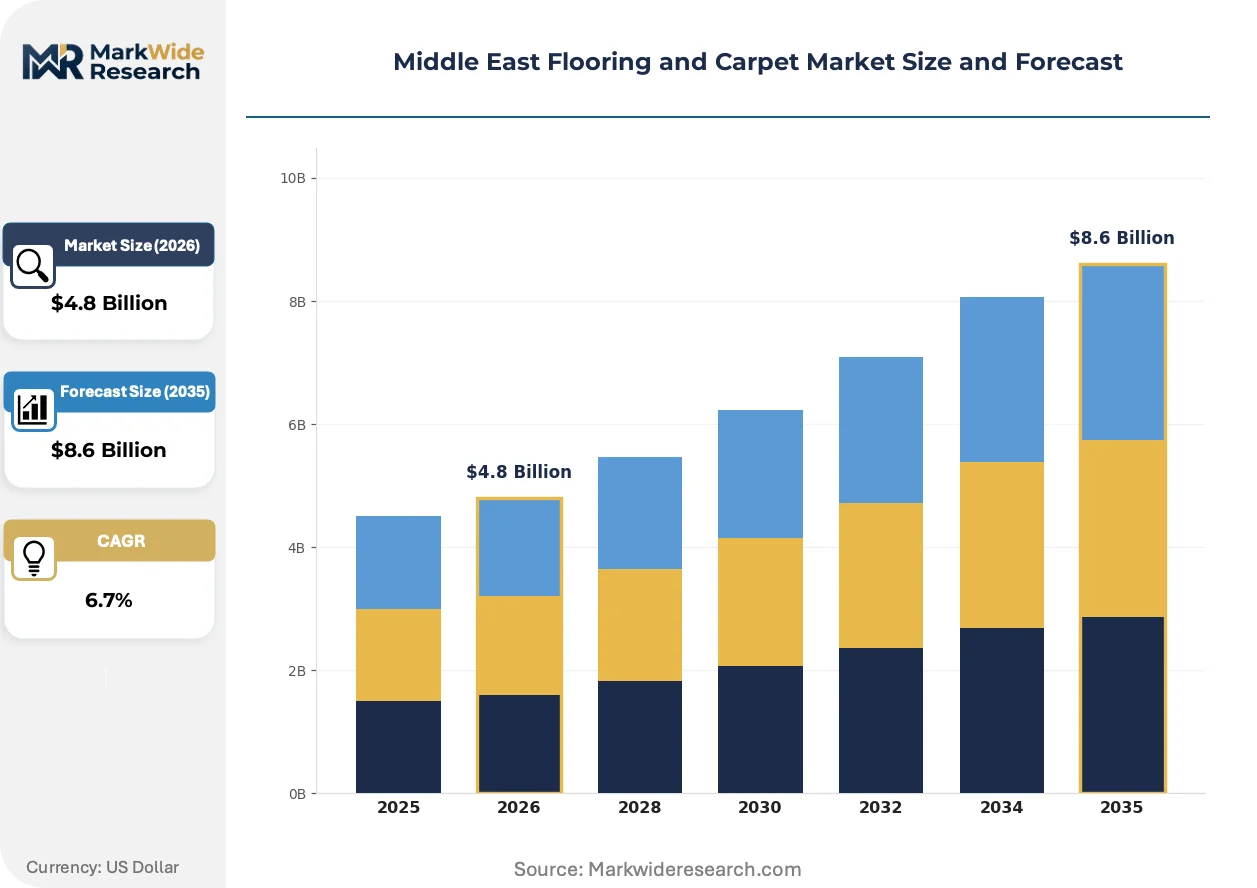
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet Tiles, Broadloom Carpets, Vinyl Flooring, Laminate Flooring Material: Nylon, Polyester, Wool, Polypropylene End User: Residential, Commercial, Hospitality, Industrial Installation Method: Glue-Down, Loose Lay, Click-Lock, Stretch-In |
| Companies Covered | Iran Carpet Company, Kaleen Carpets, Al Sorayai Group, Mohawk Industries, Tarkett Middle East, Oriental Weavers, Abdullatif Carpets, Interface Middle East, Abu Dhabi National Carpet Factory, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Flooring and Carpet Market Shifts & Advancements
Digital design-to-manufacture workflows and polymer chemistry advances are compressing development cycles while enabling mass-customization economics previously restricted to artisan production.
Solution-dyed nylon fiber technology is consolidating specification share in high-traffic commercial segments by eliminating post-dyeing water consumption and enabling precise color matching across production lots. Airport terminals and convention centers in Dubai and Doha are specifying these systems for 15-year replacement cycles. The technology is consolidating manufacturer investment away from conventional beck-dyeing infrastructure toward continuous filament extrusion lines.
SASO's 2024 technical regulation update for interior finishes tightens smoke density thresholds and mandates third-party conformity assessment for all imported broadloom and carpet tile. Saudi customs authorities are rejecting shipments lacking SASO Quality Mark certificates, forcing distributors to pre-position inventory in bonded warehouses pending approval. Domestic manufacturers with in-house testing laboratories are capturing specification share from import-dependent competitors.
Developer-led procurement consolidation is compressing distributor margins and favoring direct manufacturer relationships for large hospitality and mixed-use projects. Emaar, Aldar, and Red Sea Global are centralizing flooring specification across their development portfolios, bypassing traditional specification agent networks. This concentration is most visible in Dubai and Riyadh, where single-source supply agreements now cover multiple tower and resort phases.
Middle East Flooring and Carpet Market Segmentation
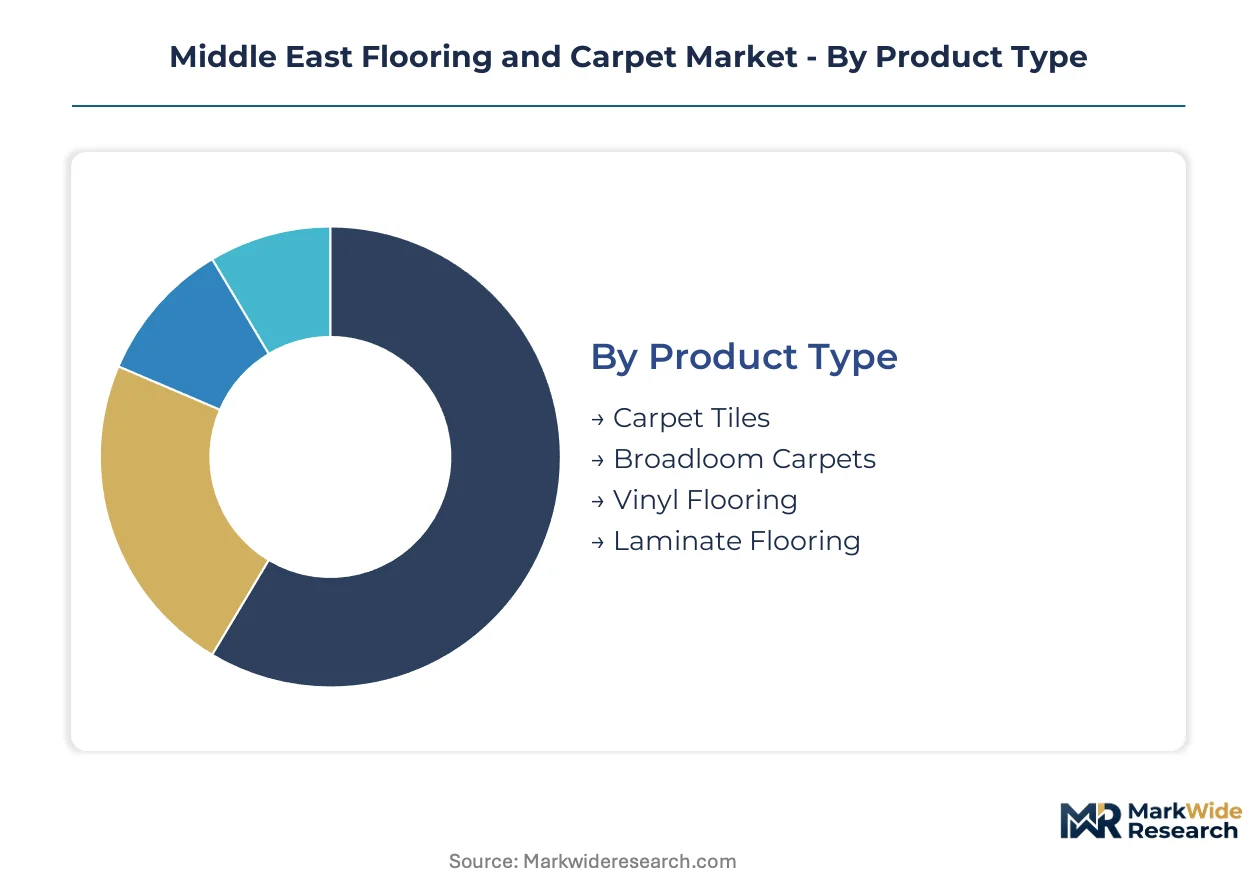
Procurement patterns across the Middle East flooring and carpet market diverge sharply by product format, material composition, and end-use application. Specification cycles in hospitality and commercial retrofit segments are compressing replacement timelines and reshaping volume allocation across segment boundaries.
Product Type:
Upgrade cycles in Dubai and Riyadh commercial real estate are pulling specification toward formats that balance first-cost against lifecycle replacement economics.
- Carpet Tiles:Modular nylon or polypropylene squares with integral backing enable zone-specific replacement and reduced installation waste. Demand concentrates in Doha office retrofits and Dubai co-working expansions where churn rates demand flexible flooring systems.
- Broadloom Carpets:Seamless wall-to-wall rolls deliver acoustic dampening and luxury aesthetics through heat-set fiber systems. Hospitality developments across the Red Sea coast and Riyadh financial district specify thicker pile weights for guest room and ballroom applications.
- Vinyl Flooring:Resilient PVC or SPC core products dominate moisture-prone commercial kitchens and healthcare corridors.
- Laminate Flooring:HDF-core decorative surfaces capture residential cost-sensitive segments in Kuwait and Bahrain.
Volume placements concentrate in broadloom systems; the faster expansion belongs to carpet tile formats.
Material:
Raw material selection tracks end-use performance requirements and import duty exposure across GCC customs regimes.
- Nylon:Solution-dyed fiber technology delivers colorfastness and stain resistance for 15-year commercial replacement cycles. Airport terminals in Dubai and convention centers in Doha specify nylon broadloom for high-traffic circulation zones.
- Wool:Natural fiber systems command premium residential specification in Jeddah and Riyadh luxury villa developments. New Zealand auction price volatility compresses margin stability for manufacturers dependent on imported fleece.
- Polyester:Recycled PET fiber systems are gaining Estidama material credit eligibility in Abu Dhabi green building projects.
- Polypropylene:Olefin fiber dominates machine-made carpet backing and budget hospitality applications.
Polypropylene captures the largest shipment volumes; polyester is climbing the fastest on sustainability specification.
End User:
Customer-type segmentation reveals divergent procurement authority structures and decision-cycle lengths.
- Hospitality:Luxury hotel developers including Emaar and Red Sea Global centralize flooring specification across portfolio phases. Custom patterning and Axminster weaving systems dominate five-star guest room and public area applications.
- Commercial:Office landlords and facility managers in Dubai International Financial Centre prioritize carpet tile for lease-cycle flexibility and reduced tenant improvement costs.
- Residential:Villa and apartment owner-occupiers in Riyadh and Kuwait City specify wool broadloom for living spaces and vinyl plank for utility areas.
- Industrial:Manufacturing facilities and logistics warehouses specify heavy-gauge vinyl or polished concrete overlays.
Commercial placements dominate current volumes; hospitality is gaining share fastest on pipeline expansion.
Installation Method:
Application technique selection determines labor cost exposure and substrate preparation requirements.
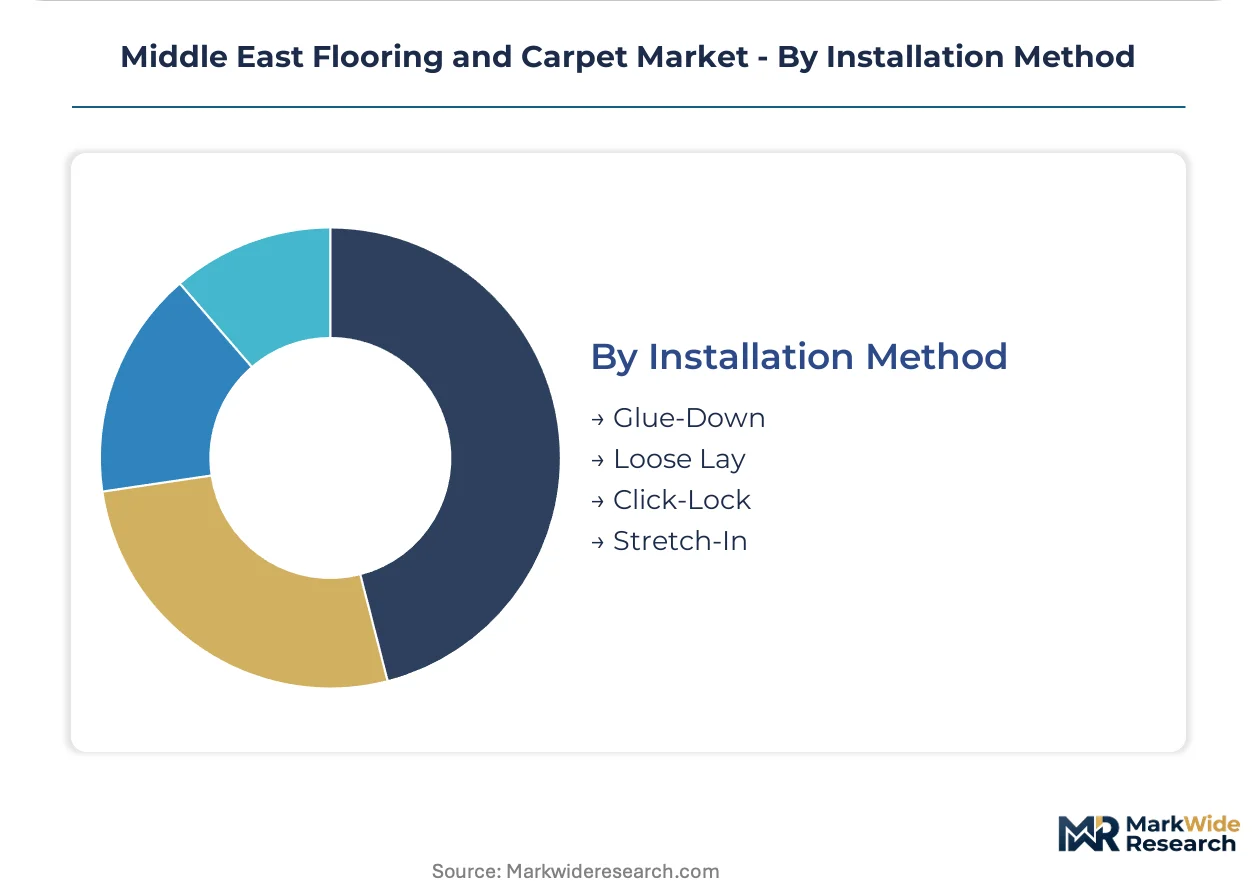
- Glue-Down:Full-spread adhesive application secures broadloom and vinyl sheet in permanent commercial installations. Dubai mall and airport projects specify this method for dimensional stability under rolling loads.
- Stretch-In:Tackless strip installation enables future salvage and reuse of wool broadloom in Riyadh residential developments.
- Click-Lock:Rigid-core SPC and laminate systems permit floating installation over imperfect subfloors.
- Loose Lay:Friction-fit vinyl tiles with weighted backing accelerate retrofit timelines in occupied commercial spaces.
Glue-down methods retain the largest installed base; click-lock systems are expanding most quickly on speed-to-occupancy demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's commercial real estate pipeline commands the largest flooring procurement volumes across the Gulf Cooperation Council zone, with hospitality and mixed-use developments driving specification upgrades for premium broadloom and modular carpet systems.
United Arab Emirates
Dubai International Financial Centre and Business Bay office retrofits are specifying carpet tiles for lease-cycle flexibility. The Emirates Authority for Standardization and Metrology enforces UAE-specific labeling and performance benchmarks that shape distributor sourcing decisions. Abu Dhabi's Estidama green building rating system awards material credits for low-VOC finishes, incentivizing specification in premium developments across the capital.
Saudi Arabia
NEOM and Red Sea Global resort developments are pulling custom-patterned Axminster systems for luxury hospitality applications. The Saudi Standards, Metrology and Quality Organization mandates fire-resistance testing and formaldehyde emission limits that filter import eligibility and local production compliance. Riyadh's financial district and Jeddah's residential villa clusters are driving wool broadloom specification for premium living spaces.
Qatar
Doha's convention center and airport expansion projects specify solution-dyed nylon broadloom for 15-year replacement cycles in high-traffic circulation zones. The country's national standardization body aligns technical requirements with Gulf Cooperation Council harmonization frameworks. Lusail City development corridors are concentrating commercial flooring procurement for co-working and retail fit-outs.
Kuwait
Kuwait City and Jahra residential housing stock expansion is outpacing local carpet distribution infrastructure, creating whitespace for direct-to-developer supply contracts. The Public Authority for Industry administers import conformity requirements for interior finishes. Salmiya and Hawally retail corridors are emerging as specification nodes for vinyl plank and laminate residential applications.
Egypt
Cairo and Alexandria manufacturing zones leverage Egyptian cotton and synthetic fiber access to supply machine-made carpet exports across North Africa and the Levant. The Egyptian Organization for Standardization and Quality regulates textile product safety and labeling for domestic market access. Tenth of Ramadan Industrial City hosts concentrated tufting and backing operations serving regional export demand.
Middle East Flooring and Carpet Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification infrastructure and hospitality customization capabilities, with domestic manufacturers capturing specification share from import-dependent competitors through captive testing laboratories. The vendor base organizes around three strategic archetypes: Egyptian and Saudi manufacturers with scale-driven machine-made production, Gulf-based specialists in custom hospitality installations, and international brands with modular commercial tile portfolios. Dominant competitive moves include developer-led procurement consolidation bypassing traditional specification agent networks, and backward integration into wool sourcing and dyeing operations to compress input cost volatility.
Within the vertically integrated tier, Al Sorayai Group and Abdullatif Carpets exemplify domestic supply chain control through captive dyeing and tufting operations. Oriental Weavers anchors Egyptian manufacturing scale for machine-made export supply. Among international modular specialists, Interface Middle East and Tarkett Middle East occupy positions in commercial carpet tile specification for retrofit and flexible workspace applications.
| Leading Market Players |
|---|
| Iran Carpet Company |
| Kaleen Carpets |
| Al Sorayai Group |
| Mohawk Industries |
| Tarkett Middle East |
| Oriental Weavers |
| Abdullatif Carpets |
| Interface Middle East |
| Abu Dhabi National Carpet Factory |
| Others |
Supply & Pricing Matrix
Captive dyeing and tufting operations in Saudi Arabia and Egypt anchor supply positions while compressing input cost volatility and supporting premium pricing power for SASO-certified domestic manufacturers against import-dependent competitors.
Pricing Analysis
Outcome-based pricing tied to Estidama material credit eligibility and LEED compliance anchors premium tiers for low-VOC carpet tile in Abu Dhabi and Dubai developments. Pricing stratifies across certification grade, with SASO Quality Mark holders commanding 15-20% premiums over uncertified imports. Cost compression in machine-made broadloom intensifies as Egyptian scale producers compete on volume. Residential villa buyers in Riyadh and Jeddah exhibit lowest price sensitivity for wool-based custom patterning, while Kuwait apartment developers drive hardest bargain on laminate and vinyl plank.
Supply Chain Analysis
New Zealand and Australian wool auction supply rests on climate-driven yield variations, exposing premium residential manufacturers to margin instability. Chinese polypropylene fiber and Belgian dye chemical inputs dominate machine-made carpet backing and coloration systems. Single-source vulnerability concentrates in Red Sea shipping lanes and Jeddah customs clearance bottlenecks. Distribution runs through Dubai Jebel Ali free zone warehousing for re-export across GCC markets, with bonded pre-positioning now mandatory pending SASO approval timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constrained SASO-accredited laboratory capacity in Riyadh and Jeddah props pricing for domestic manufacturers with in-house testing infrastructure, creating supply-constrained conditions favoring certified incumbents.
For Market Incumbents: Anchor specification share by expanding captive fire-testing laboratories to bypass SASO approval bottlenecks extending import timelines. Defend against luxury vinyl tile substitution by embedding performance data into BIM-integrated product libraries for architect decision cycles. Prioritize direct supply agreements with Emaar, Aldar, and Red Sea Global as developer-led procurement consolidation bypasses traditional specification agents. For New Entrants and Emerging Players: Digital specification platforms and BIM-integrated product libraries offer lowest-friction entry vectors for architect-facing market access. Target Kuwait City and Jahra residential housing expansion where distribution infrastructure lags demand growth. Pursue direct-to-developer supply contracts for post-pandemic housing stock expansion, bypassing established distributor networks with speed-to-occupancy value propositions. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by Egyptian and Saudi scale manufacturers seeking Gulf distribution footprint. Long-term viability favors vertically integrated domestic producers with captive dyeing, testing, and hospitality customization capabilities. Watch SASO technical regulation evolution as inflection indicator for import eligibility compression and domestic manufacturing preference.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Laboratory Expansion | SASO-accredited in-house facilities compress approval timelines from months to weeks for broadloom imports. |
| Backward Integration into Wool Sourcing | Direct New Zealand and Australian fleece procurement insulates margin stability from auction price volatility. |
| BIM-Integrated Product Library Development | Embedded performance data in architect design-phase material schedules compresses specification decision cycles. |
| Direct Developer Supply Agreements | Single-source contracts with Emaar and Red Sea Global bypass traditional specification agent networks. |
| Estidama Certification Investment | Low-VOC and recycled content credentials unlock Abu Dhabi green building material credits. |
Research Methodology
Multi-period observation of hospitality construction pipeline announcements, SASO technical regulation updates, and wool auction price movements anchored the trend analysis, supplemented by interviews with flooring procurement managers at Dubai and Riyadh developers, carpet manufacturing operations heads in Tenth of Ramadan Industrial City, and specification architects at Gulf commercial design firms. Secondary validation drew from Emirates Authority for Standardization and Metrology labeling directives, Saudi Standards, Metrology and Quality Organization conformity assessment protocols, customs trade data for polypropylene fiber imports, and hospitality project development databases. Bottom-up volume modeling across product format and material composition triangulated against top-down GDP-linked construction spend projections.
Segment-weighting across product type, material composition, end-user application, and installation method dimensions structured the analytical framework across the projection horizon. CAGRs derived from regression against construction pipeline data and replacement cycle assumptions. Industry-specific forecast inputs included solution-dyed nylon technology adoption curves in airport and convention center specifications, and carpet tile penetration rates in Dubai co-working and Doha office retrofit segments.
The model holds under stable GCC construction pipeline execution and SASO regulatory implementation timelines; deviation in Chinese polypropylene supply disruptions or New Zealand drought-driven wool yield collapses would shift volume and value trajectories. A small set of named triggers—SASO laboratory capacity expansion, Red Sea Global project acceleration, and Estidama credit rule evolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market