
 Flooring Wood Panels Market | 2026-2036
Flooring Wood Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Flooring Wood Panels Market Foresight
Cross-laminated timber is pivoting from structural framing into finished flooring substrates, compressing installed costs versus traditional hardwood. Mohawk Industries leverages captive resin production to stabilize engineered wood panel margins amid volatile adhesive feedstock markets. Kährs Group anchors its position through vertical control over Baltic birch veneer supply chains. EGGER Group competes on scale, operating particleboard and laminate flooring plants that share fiber procurement networks across Central Europe.
Flooring wood panels are composite or solid wood products manufactured to specified thickness, density, and wear-layer parameters for interior walking surfaces, typically bonded with urea-formaldehyde, phenol-formaldehyde, or isocyanate resins under heat and pressure. Engineered wood dominates value generation due to dimensional stability across humidity zones and compatibility with radiant heating systems. Laminate occupies the high-volume, price-sensitive tier where property developers prioritize cost per square meter over refinishing potential. Residential flooring remains the largest application segment, though commercial flooring commands thicker wear layers and stricter slip-resistance certification.
EPA TSCA Title VI, CARB Phase 2, and the EU Timber Regulation collectively govern formaldehyde emissions, chain-of-custody documentation, and deforestation-linked import prohibitions in the largest demand centers. Compliance costs are filtering out smaller mills lacking in-house testing laboratories or certified procurement systems. Stakeholders must monitor evolving bio-based adhesive standards and mass timber building codes that could expand structural-flooring convergence opportunities.
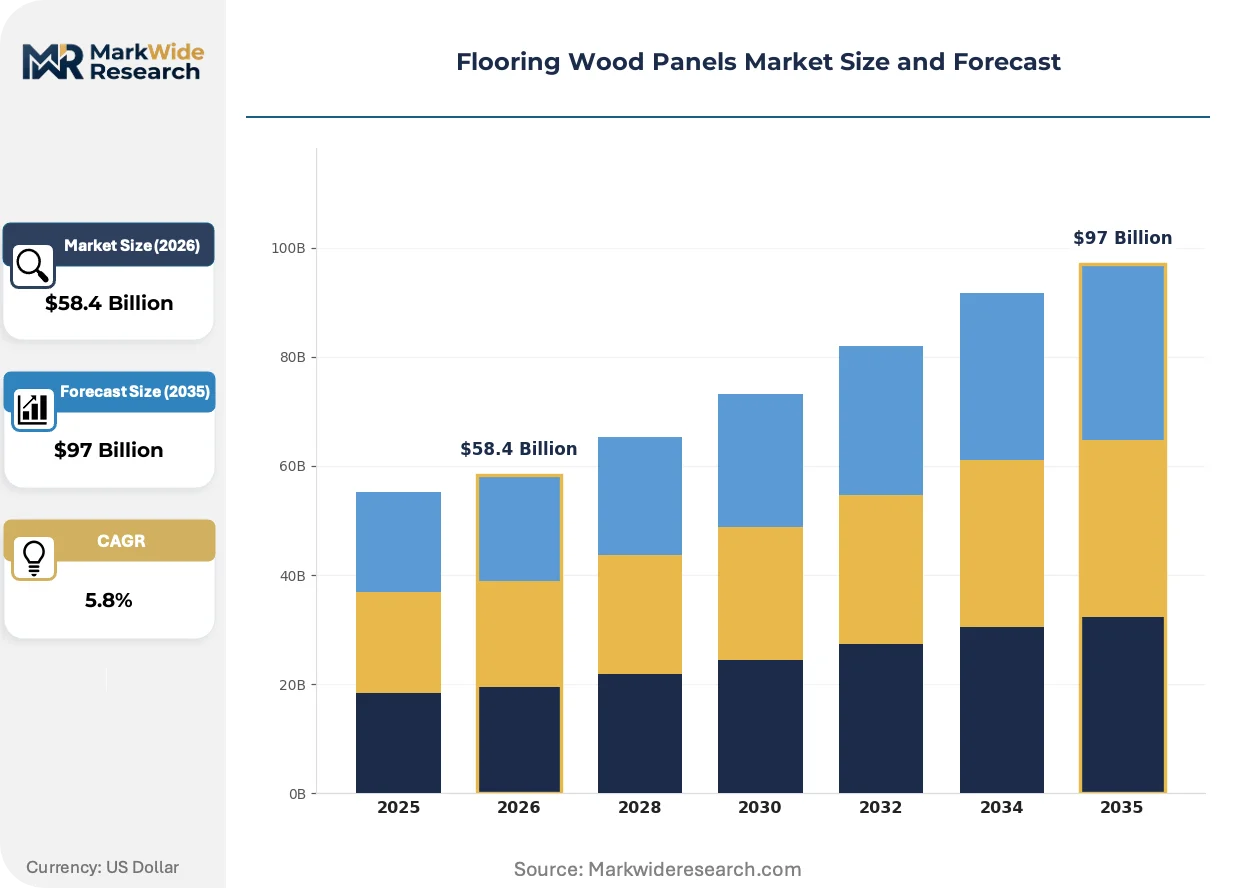
Market Dynamics
Cross-laminated timber is compressing installed costs for multi-family developers by eliminating separate structural and finish flooring trades, while California's CARB Phase 2 and the EU Timber Regulation are filtering out mills lacking certified procurement systems and in-house testing laboratories.
Growth Catalysts
- CARB Phase 2 formaldehyde standards:California's emission limits are accelerating consolidation toward compliant engineered wood producers with captive resin production and certified fiber sourcing.
- Radiant heating compatibility:Engineered wood's dimensional stability across humidity zones is pulling specification from solid hardwood in residential renovation and new multi-family construction.
- Germany's renovation density:Elevated green building certification adoption and housing stock refurbishment are concentrating demand for laminate and engineered flooring substrates in Central Europe.
Market Restraints
- Urea-formaldehyde price volatility:Adhesive feedstock costs fluctuate with methanol and natural gas markets, squeezing margins for producers without backward integration into resin manufacturing.
- Baltic birch veneer concentration:Supply chains for high-grade face veneers cluster in specific Eastern European regions, exposing buyers to geopolitical and logistics disruptions.
- Laminate refinishing limitation:Property developers prioritizing cost per square meter accept non-renewable wear layers that reduce long-term asset value compared to sandable solid or engineered hardwood.
Strategic Opportunities
- Mass timber building codes:Structural-flooring convergence in multi-story residential projects creates specification pathways for CLT-based finished substrates in jurisdictions adopting tall wood construction standards.
- Bio-based adhesive standards:Emerging certification frameworks for soy and lignin binders offer differentiation for producers investing in phenol-formaldehyde and isocyanate alternatives.
- Direct contractor channels:Flooring installers and renovation contractors are bypassing traditional distribution to source engineered panels directly from mills with digital specification tools.
Industry Challenges
- Chain-of-custody documentation:EU Timber Regulation and EPA TSCA Title VI require mill-level traceability systems that smaller producers struggle to implement without third-party certification costs.
- Slip-resistance certification timelines:Commercial flooring specifications demand extended testing protocols for thicker wear layers, delaying project approvals and inventory turns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flooring Wood Panels Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Wood, Engineered Wood, Laminate, Bamboo, Cork Application: Residential Flooring, Commercial Flooring, Institutional Flooring, Recreational Facilities Installation Method: Floating, Glue-Down, Nail-Down, Click-Lock, Staple-Down End User: Homeowners, Property Developers, Interior Designers, Facility Managers |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Armstrong Flooring, Inc., Tarkett, Mannington Mills, Inc., Kährs Group, Barlinek Group, Pergo, EGGER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flooring Wood Panels Market Shifts & Advancements
Digital manufacturing and regulatory stringency are restructuring how flooring wood panels are specified, produced, and procured, with automation and compliance systems becoming primary competitive differentiators.
Digital printing technology is automating decorative layer replication for laminate flooring, enabling grain and texture matching that narrows the visual gap with natural hardwood at substantially lower input costs. Residential developers in price-sensitive multi-family segments are adopting these digitally finished panels for specification speed. The technology is automating design-to-production workflows that previously required physical sampling and extended approval cycles.
EPA TSCA Title VI formaldehyde emission rules are extending California's CARB Phase 2 standards nationwide, requiring third-party certification and quarterly testing for all composite wood products sold in the United States. Mills without existing laboratory infrastructure face capital outlays or outsourcing costs that favor larger producers with established compliance departments. Engineered wood flooring imports from Asia-Pacific manufacturing centers are restructuring supply chains to secure EPA-recognized third-party certifiers.
Certification-driven procurement is elevating FSC and PEFC chain-of-custody documentation from premium niche to baseline requirement in commercial and institutional flooring specifications. Architects and corporate facility managers are rejecting uncertified products regardless of price positioning. Germany and Scandinavia exhibit the strictest enforcement, with public procurement mandates and green building rating systems penalizing non-compliant materials.
Flooring Wood Panels Market Segmentation
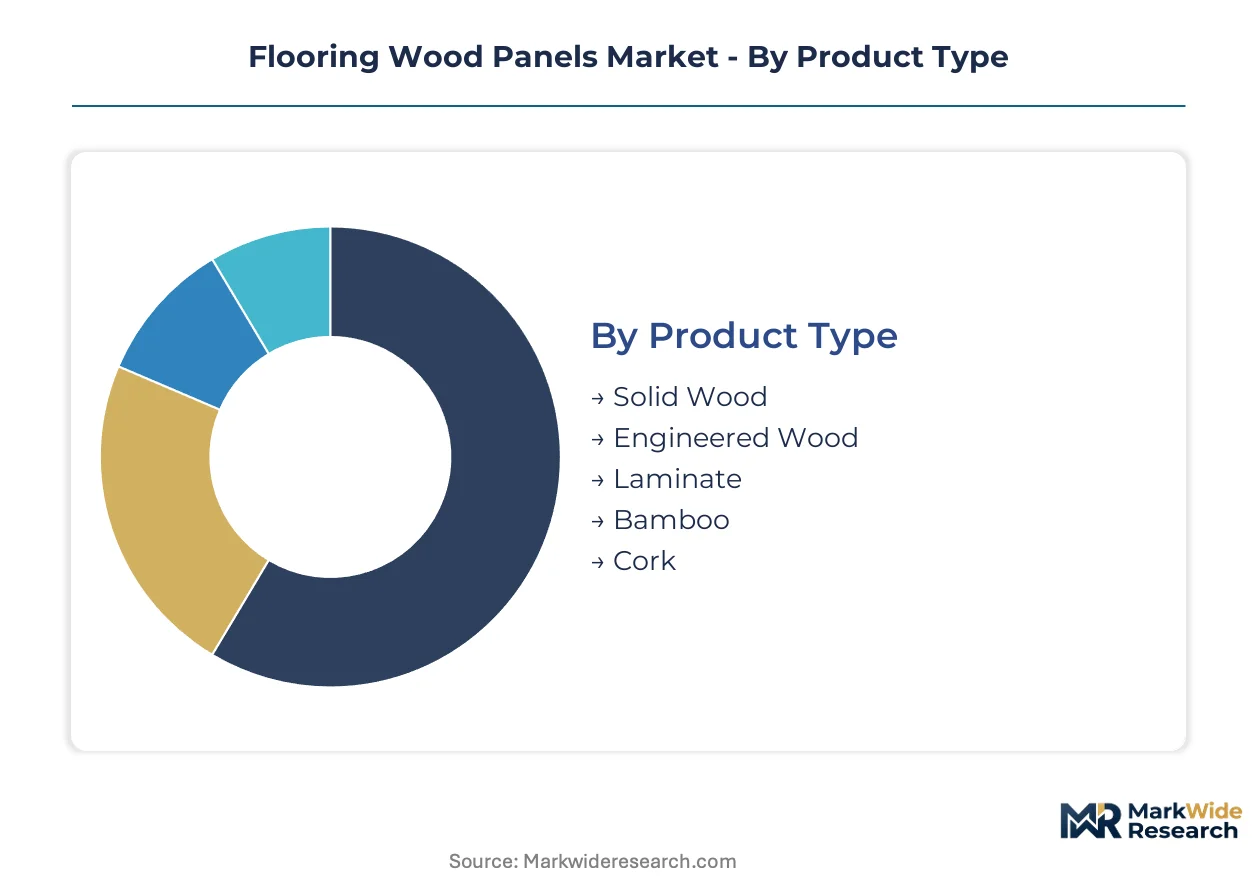
Segmentation in flooring wood panels reveals how specification requirements diverge across construction types and user sophistication. Technical performance standards, installation constraints, and procurement authority patterns create distinct addressable markets within each dimension.
Product Type:
Technical specifications around dimensional stability, wear-layer thickness, and substrate composition define competitive positioning across material categories.
- Engineered Wood:Multi-layer construction with a hardwood veneer bonded to plywood or high-density fiberboard cores delivers superior dimensional stability across humidity zones. Demand concentrates in Germany and California multi-family housing where radiant heating compatibility and CARB Phase 2 compliance filter specification toward producers with captive resin production and certified fiber sourcing.
- Laminate:High-density fiberboard cores carry decorative paper layers impregnated with melamine resins, creating wear-resistant surfaces at substantially lower installed cost. Property developers in price-sensitive residential segments prioritize cost per square meter over refinishing potential, accepting non-renewable wear layers that reduce long-term asset value.
- Solid Wood:Single-species planks milled to specified thickness retain sandable surfaces across multiple refinishing cycles. Premium residential renovation projects in heritage districts specify these for authenticity despite moisture sensitivity constraints.
- Bamboo:Grass-based material processed into strand-woven or horizontal-vertical constructions offers rapid-renewable positioning with hardness exceeding traditional oak. Green building certification adopters in Scandinavia specify these for LEED and BREEAM point accumulation.
- Cork:Bark-harvested material provides acoustic dampening and thermal insulation properties valued in multi-story residential applications. Commercial office fit-outs in Portugal and Spain leverage domestic supply chains for sustainability narrative alignment.
Engineered wood leads on scale; bamboo leads on momentum.
Application:
Performance requirements escalate from residential comfort standards through institutional durability mandates, with wear-layer thickness and slip-resistance certification serving as primary differentiators.
- Residential Flooring:Thinner wear layers balance initial cost against lifecycle refinishing potential in owner-occupied and rental housing. Germany's renovation density concentrates demand for laminate and engineered substrates compatible with underfloor heating retrofits.
- Commercial Flooring:Extended testing protocols for thicker wear layers and slip-resistance certification delay project approvals. Office and retail specifications demand mill-level chain-of-custody documentation under EU Timber Regulation enforcement.
- Institutional Flooring:Healthcare and education facilities require antimicrobial treatments and enhanced fire ratings that narrow qualified supplier pools. Public procurement mandates in Germany and France reject uncertified products regardless of price positioning.
- Recreational Facilities:Sports halls and fitness centers prioritize shock absorption and point-load resistance over aesthetic grain matching. Specialized polyurethane subfloor systems integrate with engineered wood surfaces for compliance with DIN standards.
Residential flooring leads on volume; commercial flooring leads on margin expansion.
Installation Method:
Labor cost structures and subfloor conditions determine method selection, with speed-to-completion and skill-level requirements influencing contractor preferences across project types.
- Click-Lock:Tongue-and-groove profiles with mechanical locking mechanisms enable floating installations without adhesives or fasteners. Renovation contractors bypass traditional distribution to source these engineered panels directly from mills with digital specification tools.
- Glue-Down:Direct adhesive bonding to concrete or plywood subfloors delivers superior acoustic performance and eliminates hollow-sound complaints. Commercial specifications in high-traffic zones mandate this method despite extended cure times and VOC exposure protocols.
- Floating:Interlocking panels rest on underlayment without mechanical attachment to subfloor, enabling rapid installation and future removal. Multi-family developers favor this for lease-turn efficiency and damage replacement accessibility.
- Nail-Down:Traditional fastening to wood subfloors requires skilled carpentry and limits application to above-grade installations with adequate joist access. Solid hardwood specifications in North American single-family construction retain this method for structural authenticity.
- Staple-Down:Pneumatic fastening with narrower crown staples reduces surface penetration visibility versus nail-down methods. Engineered wood applications with thinner wear layers specify staple spacing patterns to prevent telegraphing through face veneers.
Click-lock leads on installation velocity; glue-down leads on performance specification.
End User:
Procurement authority and technical sophistication create distinct sales channel requirements, with specification influence varying across project phases and decision-making structures.
- Property Developers:Volume purchasers prioritize cost per square meter and specification speed over material provenance. Multi-family housing projects in California and Germany consolidate procurement around compliant engineered wood producers with digital sampling workflows.
- Interior Designers:Aesthetic coordination authority drives premium material selection and custom finish specifications. Commercial and hospitality projects leverage these influencers to justify FSC-certified products at price premiums.
- Homeowners:Direct purchasers in renovation markets research durability ratings and installation compatibility through manufacturer digital tools. Big-box retail and direct-to-consumer channels capture this fragmented demand with sample-to-door logistics.
- Facility Managers:Lifecycle cost accountability drives maintenance-accessible specifications and extended warranty requirements. Corporate and institutional accounts negotiate national purchasing agreements with mill-direct service commitments.
Property developers lead on volume concentration; interior designers lead on value extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr and Stuttgart manufacturing corridors anchor European engineered wood panel production, with renovation density and green building certification adoption concentrating demand for laminate and engineered substrates across Central Europe.
Germany
Multi-family housing refurbishment and Energieeffizienzhaus (energy-efficient house) standards drive specification of radiant-heating-compatible engineered wood. The Bundesimmissionsschutzgesetz (BImSchG) enforces formaldehyde emission limits that filter procurement toward mills with captive resin production. Production clusters in Bavaria and North Rhine-Westphalia supply cross-border demand from France and the Netherlands.
United States
California's multi-family developers specify CARB Phase 2 compliant engineered panels for cost compression in high-density housing. EPA TSCA Title VI extends these emission standards nationwide, requiring third-party certification that favors established producers with laboratory infrastructure. Manufacturing concentrates in the Southeast and Pacific Northwest near timber supply basins.
China
Urban residential construction and commercial office fit-outs absorb high volumes of laminate flooring for cost-sensitive developers. The Ministry of Ecology and Environment (MEE) enforces GB standards for indoor air quality that reshape adhesive formulations. Production gravity centers on Guangdong and Zhejiang provinces with integrated fiberboard and decorative paper supply chains.
Sweden
Green building certification adopters specify FSC-certified engineered wood and bamboo for LEED and BREEAM point accumulation. The Swedish Environmental Protection Agency (Naturvårdsverket) enforces chain-of-custody documentation under EU Timber Regulation alignment. Västra Götaland and Småland regions host vertically integrated producers controlling Baltic birch veneer sourcing.
Canada
Mass timber building code adoption in British Columbia and Ontario creates specification pathways for CLT-based finished substrates in multi-story residential projects. Health Canada and the Canadian Wood Council promote tall wood construction standards that compress installed costs versus traditional hardwood. Quebec and British Columbia concentrate production near certified fiber procurement zones.
Flooring Wood Panels Market Competitive Landscape
Global majors compete with regional champions across resin integration and certified fiber sourcing, producing a tiered structure where scale-driven conglomerates, specialty engineered wood producers, and laminate-focused manufacturers occupy distinct competitive positions. Consolidation favors enterprises with backward integration into adhesive production and in-house laboratory infrastructure for emission testing. Two strategic archetypes dominate: vertically integrated resin producers stabilizing margins against feedstock volatility, and design-forward specialists commanding premium positioning through controlled veneer supply chains. Dominant competitive moves include capacity expansion in Southeast Asia for Asia-Pacific market access and strategic partnerships with certification bodies for chain-of-custody documentation.
Among North American conglomerates, Mohawk Industries, Inc. and Shaw Industries Group, Inc. occupy positions representing scale-driven diversification across flooring categories, with captive manufacturing infrastructure spanning multiple substrate technologies. Kährs Group anchors the European specialist tier, exemplifying controlled supply chain positioning through geographic naming conventions suggesting Nordic origin and hardwood flooring heritage. These three entities collectively illustrate the competitive spectrum from diversified volume production to focused premium positioning in engineered wood substrates.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Armstrong Flooring, Inc. |
| Tarkett |
| Mannington Mills, Inc. |
| Kährs Group |
| Barlinek Group |
| Pergo |
| EGGER Group |
| Others |
Supply & Pricing Matrix
Methanol price indices cascade through urea-formaldehyde resin markets into engineered wood panel pricing tiers, compressing margins for non-integrated mills while rewarding producers with captive adhesive production in Germany and the US Southeast.
Pricing Analysis
Input-cost pass-through from volatile methanol and natural gas markets separates pricing power between integrated and non-integrated producers. Three-tier pricing structure across premium certified, standard compliant, and economy laminate levels reflects FSC chain-of-custody documentation and CARB Phase 2 testing investments. Pricing pressure stems from Asian laminate imports competing on square-meter cost in multi-family residential segments. Property developers exhibit highest price sensitivity, while institutional facility managers prioritize lifecycle durability over initial cost.
Supply Chain Analysis
Certification gating through EPA TSCA Title VI and EU Timber Regulation documentation requirements filters supplier资格 toward mills with in-house testing laboratories and third-party certifier relationships. Production clusters concentrate in Germany, China, and the US Southeast, drawing from Baltic birch veneer supply chains, Guangdong fiberboard networks, and Appalachian timber basins. Single-source vulnerability runs through Eastern European face veneer regions exposed to logistics disruptions. Distribution runs through direct contractor channels bypassing traditional wholesale layers for engineered wood specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flooring wood panels market functions as a stable compounder, with renovation density in Germany and California multi-family housing delivering predictable specification volume across economic cycles.
For Market Incumbents: Extend backward integration into resin manufacturing to stabilize margins against methanol price volatility threatening non-integrated competitors. Add in-house EPA-recognized laboratory capacity to defend against smaller mills losing certification access. Consolidate around Baltic birch veneer sourcing relationships before geopolitical disruption escalates procurement risk.
For New Entrants and Emerging Players: Renovation contractors represent the most accessible channel partner type for bypassing established distribution. Target Germany's Energieeffizienzhaus retrofit segment where radiant heating compatibility drives engineered wood specification away from incumbents. Pursue digital sampling workflows that compress specification cycles for multi-family developers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap engineered wood specialists controlling certified fiber procurement in Scandinavia and the Baltic states. Five-to-ten-year viability hinges on mass timber building code expansion converting structural CLT into finished flooring substrates. Monitor tall wood construction standard adoption in British Columbia and Ontario as the primary inflection signal for CLT-based flooring convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Mohawk Industries stabilizes engineered wood margins against methanol price swings through captive urea-formaldehyde production. |
| Certification Body Partnership | FSC and PEFC chain-of-custody documentation shifts from premium niche to baseline procurement requirement in German public tenders. |
| Digital Specification Platform Launch | Direct contractor channels bypass traditional distribution layers with sample-to-door logistics for renovation markets. |
| CLT Substrate Capacity Expansion | Mass timber building codes in Canada and select US jurisdictions create structural-flooring convergence opportunities. |
| Bio-based Adhesive R&D Investment | Soy and lignin binder alternatives differentiate producers ahead of emerging certification frameworks for phenol-formaldehyde substitutes. |
Research Methodology
Bottom-up residential and commercial flooring modeling reconciled against top-down engineered wood and laminate production tracking forms the analytical core of this study. Primary interviews with multi-family developers, renovation contractors, flooring installers, and mill procurement directors combined with secondary validation from EPA TSCA Title VI certification databases, EU Timber Regulation enforcement records, and trade flow customs data. Triangulation across specification surveys and production volume disclosures ensures segment-level accuracy.
Historical trendline analysis across product type, application, installation method, and end-user dimensions establishes baseline growth patterns over the projection horizon. CAGRs derive from regression analysis against renovation spending indices, housing starts data, and green building certification adoption rates. Forecast inputs include radiant heating penetration rates in German multi-family housing and mass timber building code adoption timelines in North American jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to adhesive feedstock price volatility and geopolitical disruption in Baltic birch veneer supply chains. A model refresh is warranted upon material change in EPA enforcement posture or EU Timber Regulation documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market