
 Europe Vinyl Flooring Market | 2026-2036
Europe Vinyl Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vinyl Flooring Market Intelligence
Digital templating and specification software sold as a subscription layer is recalibrating how architects and contractors procure vinyl flooring across Europe. Tarkett leverages its captive recycling infrastructure in Sweden to secure specification wins on circular-economy tenders. Gerflor anchors its position through deep distribution relationships with French hospital networks. Mohawk Industries competes by extending its rigid-core manufacturing scale from North American lines into European click-lock production.
Europe vinyl flooring comprises multi-layer polymer systems—typically PVC wear layers, printed decorative films, and stabilized core substrates—engineered for dimensional stability under foot traffic and moisture exposure. The material serves primarily as a cost-efficient, hygienic surface solution for high-traffic commercial interiors and moisture-prone residential zones. Luxury Vinyl Tiles occupy the dominant margin pool as specification-grade products command premium positioning in hospitality and healthcare retrofits. Vinyl Sheets sustain volume leadership in institutional settings where seamless hygiene protocols outweigh aesthetic customization. Click Lock installation is displacing glue-down methods in residential renovation as floating-floor systems reduce skilled-labor dependency and accelerate project timelines.
REACH restrictions on phthalate plasticizers and the EU Green Deal's building-performance standards are forcing reformulation toward bio-based plasticizers and recycled-content cores across the supply base. ECHA's candidate list updates for SVHC substances directly shape product-development roadmaps and factory certification requirements for exporters into the European Economic Area. France's RE2020 environmental regulation and Germany's Building Energy Act create divergent compliance calendars that manufacturers must navigate simultaneously. Stakeholders should monitor how embodied-carbon disclosure mandates under the CSRD reshape procurement criteria for public-sector flooring contracts.
Market Dynamics
REACH restrictions on phthalate plasticizers and the EU Green Deal's embodied-carbon thresholds are forcing wholesale reformulation of vinyl flooring chemistries across European manufacturing bases.
Growth Catalysts
- Healthcare Renovation Wave:German hospital networks are accelerating material procurement for hygiene-critical retrofits, creating specification-grade demand for seamless vinyl sheet systems.
- RE2020 Compliance Deadlines:France's environmental regulation is compressing procurement calendars for low-carbon interior finishes in urban residential construction.
- Click-Lock Floating Systems:Rigid-core polymer engineering is displacing glue-down methods in residential renovation by reducing skilled-labor dependency and shortening project timelines.
Market Restraints
- Petrochemical Feedstock Volatility:PVC resin and plasticizer input costs fluctuate with crude-oil derivatives, compressing margin predictability for mid-tier producers.
- Recycling Infrastructure Gaps:Post-consumer vinyl collection networks remain concentrated in Nordic clusters, limiting circular-economy scale-up across Southern and Eastern Europe.
- Linoleum Resurgence:Bio-based linoleum flooring is capturing specification share in premium educational and municipal projects where natural-material narratives outweigh polymer performance.
Strategic Opportunities
- Polish Residential Retrofit:Warsaw and Kraków urban renewal programs remain underpenetrated by specification-grade LVT, offering first-mover positioning for digital-templating-enabled distributors.
- CSRD-Driven Public Procurement:Corporate Sustainability Reporting Directive mandates are reshaping tender criteria for healthcare and education flooring contracts toward embodied-carbon disclosure.
- Digital Specification Platforms:Subscription-based templating software is converging with Building Information Modeling workflows, creating new recurring-revenue layers for material suppliers.
Industry Challenges
- SVHC Compliance Timelines:ECHA candidate-list updates for substances of very high concern compress product-development roadmaps and factory-certification windows for exporters into the European Economic Area.
- Multi-Jurisdiction Labeling:Simultaneous navigation of France's RE2020, Germany's Building Energy Act, and divergent national fire-safety codes fragments quality-assurance protocols.
- Skilled Installer Scarcity:Glue-down specialty trades are aging out faster than click-lock competency spreads, creating execution risk for seamless-sheet projects in institutional settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vinyl Flooring Market |
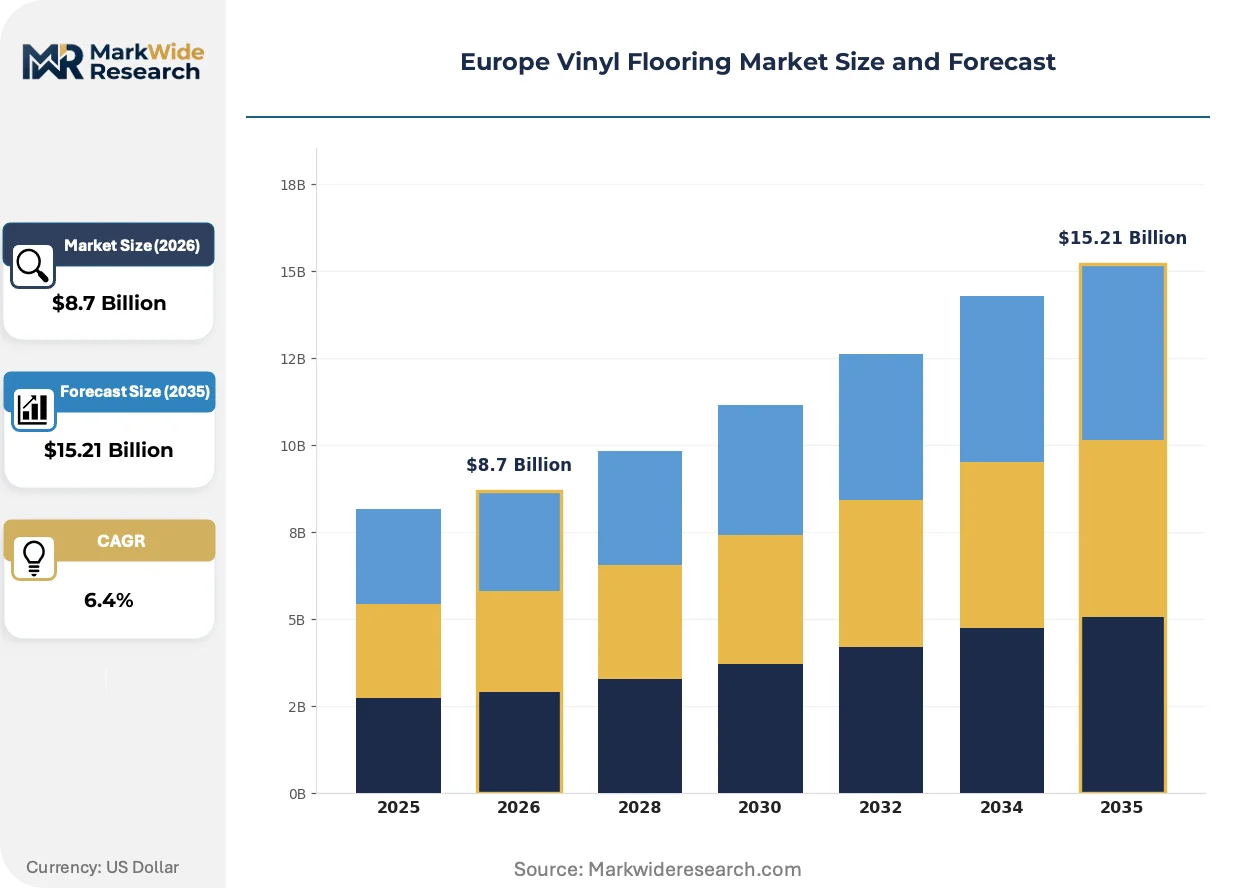
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tiles, Vinyl Sheets, Vinyl Planks, Hybrid Vinyl Installation Method: Glue Down, Loose Lay, Click Lock, Embossed End User: Residential, Commercial, Industrial, Institutional Thickness: Light, Medium, Heavy, Extra Heavy |
| Companies Covered | Polyflor, Parador, Tarkett, IVC Group, Mohawk Industries, Forbo Flooring, Interface, Amtico, Gerflor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vinyl Flooring Market Strategic Shifts & Innovations
Digital tools and regulatory disclosure mandates are compressing traditional specification cycles while reformulation pressures accelerate material-science investment across European vinyl flooring supply chains.
Rigid-core polymer substrates with mineral-loaded stabilized layers are consolidating technical performance standards for moisture-prone residential and light-commercial applications. German and French contractors are specifying these systems for basement and bathroom retrofits where dimensional stability under hydrostatic pressure previously required ceramic or engineered wood. The technology is consolidating installation-method preferences toward floating-floor systems that eliminate adhesive curing times and substrate-prep labor.
REACH Annex XVII restrictions on phthalate plasticizers are compelling migration toward bio-based alternatives and recycled-content core formulations. Industrial consequence includes factory recertification costs and reformulation R&D cycles that favor larger producers with captive polymer research capacity. Healthcare and childcare segments are most affected, with procurement officers now requiring SVHC-free documentation chains for all interior finish specifications.
Subscription-based digital templating platforms are replacing traditional physical-sample distribution for architect and contractor specification decisions. French hospital network procurement teams are adopting these tools for accelerated visualization and embodied-carbon comparison across finish alternatives. The shift is most visible in Paris and Lyon metropolitan renovation markets where project timelines have compressed by 30-40 percent through pre-construction digital sign-off workflows.
Europe Vinyl Flooring Market Segmentation

European vinyl flooring procurement channels diverge sharply across product formats, installation competencies, and end-use compliance requirements. Specification-grade segments command premium positioning through embodied-carbon documentation and hygiene certification, while residential retrofit volumes concentrate in contractor-friendly installation systems.
Product Type:
Manufacturing capacity clusters around multi-layer polymer systems with differentiated wear-layer specifications and core stabilization chemistries.
- Luxury Vinyl Tiles:Rectangular polymer composite tiles with high-definition printed decorative films and transparent PVC wear layers. French hospital networks and German hospitality retrofits specify these for design flexibility combined with seamless maintenance protocols.
- Vinyl Sheets:Continuous roll goods with homogeneous or heterogeneous layer construction, welded at seams for impermeable surfaces. German healthcare procurement teams prioritize these for operating theaters and isolation wards where bacterial ingress control overrides aesthetic considerations.
- Vinyl Planks:Elongated rectangular formats mimicking timber dimensions, typically 4-8mm total thickness with rigid mineral cores. Polish residential distributors stock these heavily for Warsaw apartment renovations.
- Hybrid Vinyl:Composite substrates combining vinyl wear layers with alternative core materials such as stone-polymer or wood-polymer composites. These address moisture-prone basement applications across Benelux markets.
Vinyl Sheets absorb the bulk of installed capacity; Luxury Vinyl Tiles are expanding most quickly.
Installation Method:
Contractor labor availability and project timeline compression are shifting specification preferences toward reduced-skill installation systems.
- Glue Down:Full-spread or perimeter-bonded adhesive application requiring substrate moisture testing and surface preparation. Aging installer populations in France and Germany constrain volume growth despite superior performance in high-traffic commercial settings.
- Click Lock:Interlocking edge profiles enabling floating-floor installation without adhesive curing periods. Residential renovation contractors across Spain and Italy specify these for accelerated project completion and reduced skilled-labor dependency.
- Loose Lay:Friction-fit systems relying on dimensional stability and perimeter retention without adhesive or mechanical fastening. Temporary commercial installations and tenant improvement projects favor these for future removal flexibility.
- Embossed:Surface-textured products with registered embossing aligned to printed grain patterns, installed via multiple methods. Premium residential specifications in Scandinavian markets value these for tactile authenticity.
Click Lock systems capture the steepest expansion trajectory as installer scarcity reshapes contractor procurement criteria.
End User:
Compliance documentation requirements and embodied-carbon disclosure mandates fragment procurement protocols across customer categories.
- Residential:Homeowner-driven renovation and new construction specifying through retail channels and contractor networks. Urban retrofit programs in France concentrate volume in Paris and Lyon metropolitan zones.
- Commercial:Office, retail, and hospitality interiors balancing durability specifications with design flexibility. German hotel renovation cycles sustain consistent demand for specification-grade LVT.
- Institutional:Healthcare, education, and government facilities with mandatory hygiene protocols and public procurement regulations. ECHA SVHC documentation requirements shape tender specifications.
- Industrial:Manufacturing and logistics facilities prioritizing chemical resistance and load-bearing capacity over aesthetic considerations. Eastern European automotive supplier plants generate periodic volume.
Institutional contracts absorb the bulk of specification-grade capacity; Residential renovation is climbing the fastest.
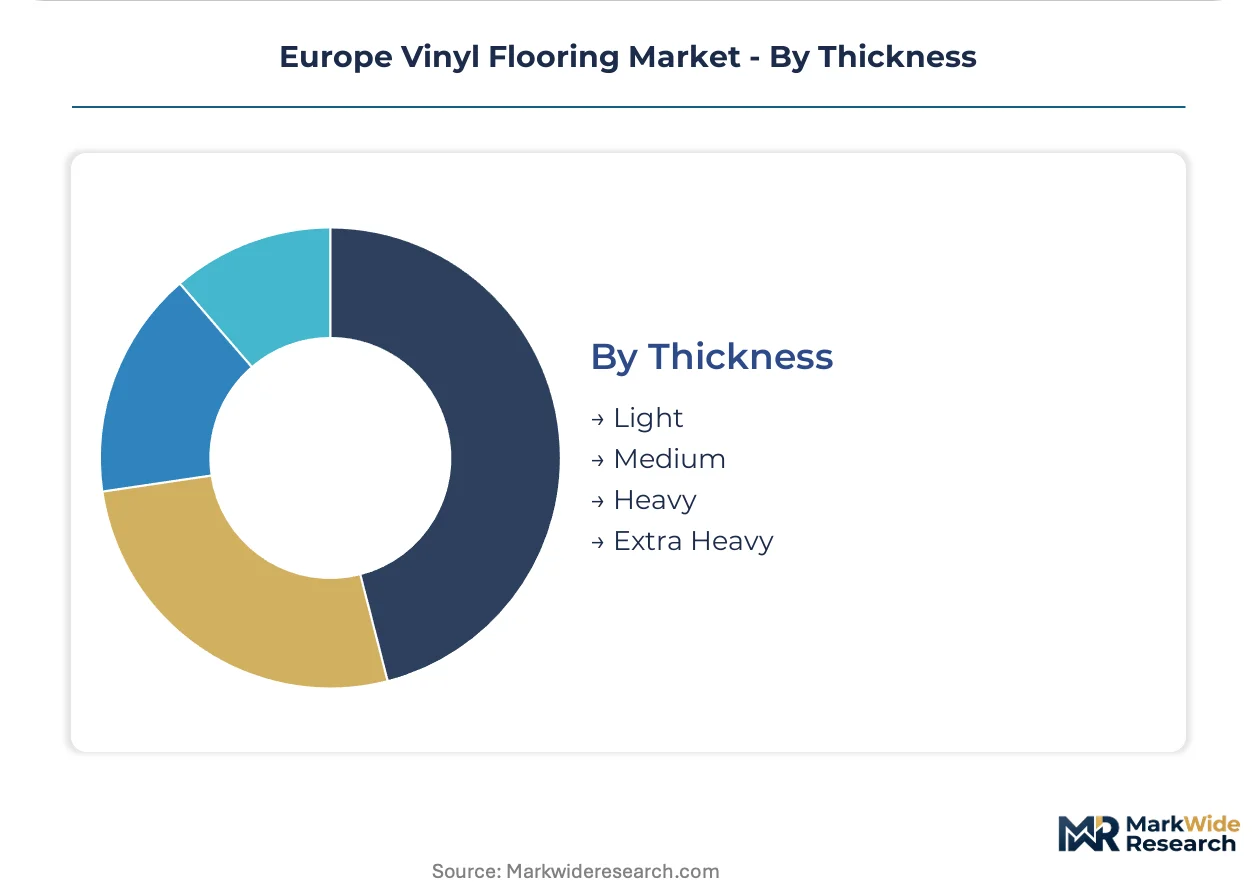
Thickness:
Wear-layer depth and total plank dimension determine application suitability and price positioning across end-use segments.
- Heavy:Total construction exceeding 4.0mm with substantial wear layers for commercial traffic loads. German transport hubs and French school corridors specify these for replacement-cycle extension.
- Medium:2.5-4.0mm construction balancing residential durability with cost efficiency. Volume concentrates in Spanish and Portuguese residential new-build specifications.
- Light:Sub-2.5mm products for budget residential and light commercial applications. Temporary installations and rental property renovations drive demand.
- Extra Heavy:Premium construction exceeding 5.0mm with enhanced acoustic properties and indentation resistance. Nordic healthcare and education specifications require these for warranty compliance.
Medium thickness dominates unit volumes; Heavy construction is gaining share fastest in commercial retrofit specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European vinyl flooring production concentrates in Belgium and Germany, while consumption spreads across renovation-heavy Western European markets. This geographic split shapes logistics costs and specification relationships between manufacturers and national distributors.
Germany
Hospital renovation networks in North Rhine-Westphalia and Bavaria drive specification-grade demand for seamless vinyl sheet systems. The Building Energy Act tightens embodied-carbon thresholds for public procurement, compressing supplier compliance windows. Cologne and Düsseldorf distribution clusters serve as specification gateways into Central European contractor networks.
France
Urban residential retrofits in Paris and Lyon concentrate demand for click-lock rigid-core systems. RE2020 environmental regulation mandates low-carbon interior finishes in new construction, shifting procurement toward documented recycled-content products. Marseille hospitality renovation cycles sustain premium LVT specification volumes.
United Kingdom
Healthcare estate modernization across NHS trusts generates institutional demand for welded-seam vinyl sheet. Building Safety Act compliance requirements extend material documentation chains for fire-performance certification. Manchester and Birmingham distribution hubs coordinate specification support for regional contractor networks.
Poland
Warsaw and Kraków urban renewal programs remain underpenetrated by specification-grade LVT distributors. EU cohesion fund infrastructure investments expand commercial flooring procurement budgets. Wrocław manufacturing clusters supply cost-optimized products into Eastern European retail channels.
Sweden
Nordic circular-economy tenders prioritize suppliers with captive post-consumer recycling infrastructure. Miljöbyggnad certification requirements shape green procurement criteria for public-sector flooring contracts. Stockholm specification teams influence sustainability standards across Scandinavian markets.
Europe Vinyl Flooring Market Key Industry Players
Top-tier vendors anchor specification-grade healthcare and hospitality contracts, while mid-tier fabricators compete on residential renovation volumes through distributor relationships. The vendor base organizes around three strategic archetypes: integrated polymer producers with captive recycling infrastructure, specification specialists with deep architect relationships, and scale-oriented manufacturers optimizing rigid-core production lines. M&A activity targets recycling technology assets and digital templating platforms.
Within the integrated producer tier, Tarkett and Mohawk Industries exemplify divergent geographic strategies. Tarkett leverages its Swedish recycling infrastructure to secure circular-economy tender wins. Mohawk Industries extends North American rigid-core manufacturing scale into European click-lock production. Gerflor occupies a position anchored through French hospital network distribution relationships. These three represent distinct competitive vectors: circular certification, manufacturing scale, and channel depth.
| Leading Market Players |
|---|
| Polyflor |
| Parador |
| Tarkett |
| IVC Group |
| Mohawk Industries |
| Forbo Flooring |
| Interface |
| Amtico |
| Gerflor |
| Others |
Cost & Logistics Intelligence
Click-lock rigid-core manufacturing scale-up across Belgium and Germany simultaneously compresses per-unit production economics and concentrates polymer compounding capacity among integrated producers with captive mineral-core supply. This dual effect reshapes margin distribution between specification-grade sheet producers and residential-focused click-lock fabricators.
Pricing Analysis
Margin tightening in mid-tier rigid-core segments reflects PVC resin and plasticizer feedstock volatility tethered to crude-oil derivatives. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade healthcare products with SVHC-free documentation from commodity residential click-lock. Cost-down pressure on economy-tier products accelerates because Polish and Spanish distributors prioritize volume throughput over margin retention. Institutional buyers in German hospital networks exhibit lowest price sensitivity due to compliance-driven procurement protocols.
Supply Chain Analysis
Post-consumer vinyl collection and mechanical recycling flows concentrate in Swedish and Belgian processing clusters, limiting circular-economy scale-up across Southern and Eastern Europe. Manufacturing draws from petrochemical feedstocks anchored in German and Dutch polymer production, with decorative film printing concentrated in Italian and French converter networks. Single-source vulnerability in phthalate-free plasticizer supply creates reformulation risk as REACH Annex XVII restrictions tighten. Distribution runs through Cologne, Düsseldorf, and Paris specification hubs serving national contractor networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European vinyl flooring is consolidating around producers with captive recycling infrastructure and REACH-compliant formulation capabilities, forcing mid-tier fabricators without backward polymer integration toward exit or acquisition.
For Market Incumbents: Deploy specification-grade certification investment to defend healthcare and hospitality tender positions against bio-based linoleum substitution. Deepen architect relationships through digital templating platform subscriptions that embed products into pre-construction workflows. Counter Mohawk Industries' rigid-core scale expansion by accelerating Swedish recycling infrastructure utilization for circular-economy public procurement wins. For New Entrants and Emerging Players: Polish residential retrofit contractors in Warsaw and Kraków represent the most penetrable buyer archetype currently underserved by specification-grade LVT distributors. Capture share through click-lock rigid-core products with accelerated delivery timelines and contractor-friendly installation training. Prioritize digital-native specification tools that compress traditional sample-based procurement cycles for renovation project managers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier fabricators possessing regional distribution depth but lacking REACH-compliant formulation capacity, given CSRD-driven disclosure mandates reshaping tender eligibility. Long-term viability favors targets with backward integration into polymer compounding or captive post-consumer recycling streams. Monitor ECHA SVHC candidate-list updates as inflection indicators for factory recertification cost spikes that accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Circular-Economy Certification Program | Swedish post-consumer recycling infrastructure secures public-sector tender eligibility under EU Green Deal procurement criteria. |
| Backward Integration into Polymer Compounding | In-house plasticizer formulation capacity insulates margin from REACH-driven supply disruptions and feedstock volatility. |
| Digital Specification Platform Launch | Subscription templating software embeds products into French hospital network procurement workflows ahead of physical sampling. |
| Geographic Manufacturing Footprint Expansion | Polish production proximity to Warsaw and Kraków retrofit markets reduces logistics cost and delivery lead times. |
| Long-term Supply Agreement | Fixed-price PVC resin contracts with Belgian petrochemical producers stabilize input costs for rigid-core volume production. |
Research Approach
Independent corroboration across specification-grade product managers, healthcare procurement officers, and residential distribution channel heads underwrites the qualitative findings. Primary fieldwork encompassed polymer R&D directors, French hospital network material planners, German contractor association representatives, and sustainability certification auditors. Secondary validation drew from ECHA SVHC candidate-list updates, EU Green Deal building-performance disclosures, REACH Annex XVII restriction timelines, and national trade data for PVC resin and plasticizer imports. Bottom-up channel checks across Belgian, German, and French manufacturing clusters triangulate against top-down market sizing.
Historical reference periods anchored volume and value trajectories to pre-pandemic renovation cycles and post-RE2020 regulatory implementation phases across the analysis window. Segmentation modeling incorporated product format, installation method complexity, end-use compliance tier, and regional regulatory cluster dimensions. CAGRs derive from polynomial trend fitting across disclosed production capacities and channel inventory turns. Industry-specific inputs include embodied-carbon disclosure mandate adoption curves and skilled installer demographic projections.
Revisions become necessary when ECHA accelerates SVHC substance restrictions, EU Green Deal procurement thresholds tighten ahead of schedule, or petrochemical feedstock disruptions exceed historical volatility bands. Practitioners should monitor circular-economy tender award patterns and digital specification platform adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market