
 Rugs Market | 2026-2036
Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Rugs Market Outlook
Artisan weaving expertise is rotating toward digital design and automated tufting, narrowing the pipeline of master craftspeople capable of hand-knotting fine wool pieces. Mohawk Industries leverages captive nylon fiber production to control raw material flows across its residential carpet and rug divisions. Oriental Weavers Group anchors its competitiveness on Egyptian manufacturing scale and direct distribution into North American big-box retail. Shaw Industries Group differentiates through Cradle to Cradle certification and closed-loop recycling infrastructure for commercial-grade products.
Rugs are textile floor coverings constructed from woven, tufted, or needle-punched fibers with pile heights typically ranging from 3mm to 25mm, designed for thermal insulation, acoustic dampening, and interior spatial definition. Wool and silk segments command premium positioning in traditional and bohemian styles where hand-knotting density above 100 knots per square inch signals quality. Synthetic materials, particularly solution-dyed polyester and nylon, dominate the modern and contemporary style categories where stain resistance and lower price points drive residential volume. The hospitality end user segment generates outsized margin pools through custom sizing and fire-retardant specifications for hotel and cruise ship installations.
EPA regulations on indoor air quality and VOC emissions influence synthetic rug formulations sold in the United States, while REACH compliance in Europe restricts chemical inputs across dyeing and finishing stages. India's BIS certification for textile durability and flammability shapes export readiness for manufacturers in Bhadohi and Mirzapur. Stakeholders must monitor how carbon border adjustments and extended producer responsibility frameworks in the European Union and United States reshape sourcing economics for wool imports and synthetic recycling infrastructure.
Market Dynamics
REACH restrictions on azo dyes and formaldehyde emissions are compressing dye chemistry options for European manufacturers and accelerating migration toward certified natural dyes and recycled PET backings across the supply base.
Growth Catalysts
- Hospitality procurement expansion:Luxury property developers in Dubai and Riyadh are expanding floor-covering budgets for premium installations, driving demand for custom-sized, fire-retardant specifications.
- Regulatory compliance premiums:REACH mandates in Europe reward manufacturers with certified natural dye processes, creating margin differentiation for compliant producers in Germany and France.
- Artisan cluster concentration:Hand-knotted wool production in Jaipur and Bhadohi supplies premium buyers in the United States and Germany with density-grade products above 100 knots per square inch.
Market Restraints
- Wool input cost volatility:New Zealand and Australian wool auction prices fluctuate with climate conditions and herd sizes, compressing margin predictability for hand-knotted segment producers.
- Master craftsperson scarcity:Automated tufting adoption is narrowing the pipeline of weavers capable of fine hand-knotting, constraining output growth for traditional luxury segments.
- Carbon border adjustment exposure:European Union carbon border mechanisms threaten to impose cost penalties on wool imports from India and synthetic fiber shipments from Egypt.
Strategic Opportunities
- Cruise ship outfitting contracts:Fire-retardant custom specifications for maritime hospitality create high-margin, long-duration order books for specialized manufacturers.
- Closed-loop recycling infrastructure:Cradle to Cradle certification pathways enable premium positioning for commercial-grade products in United States corporate fit-outs.
- Digital design-to-loom integration:Convergence of automated CAD systems with high-speed tufting machinery compresses sample-to-production timelines for residential volume buyers.
Industry Challenges
- Hand-knotting skill attrition:Generational transition away from artisan apprenticeships in Bhadohi and Mirzapur threatens quality consistency for premium wool segments.
- Dual certification timelines:Simultaneous pursuit of EPA indoor air quality compliance and BIS durability certification extends product launch cycles for India-based exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugs Market |
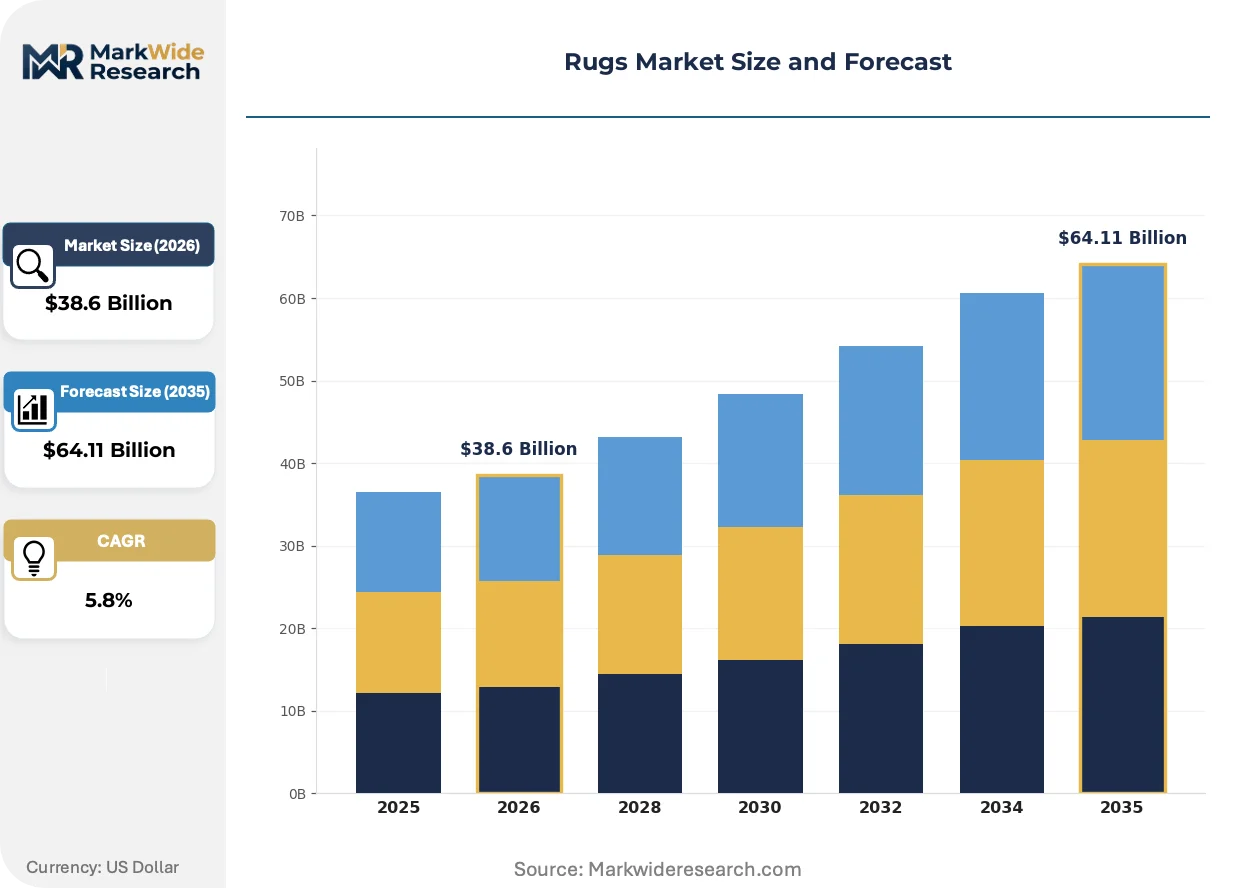
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wool, Cotton, Silk, Synthetic Style: Traditional, Modern, Bohemian, Contemporary Size: Small, Medium, Large, Runner End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Nourison Industries, Milliken & Company, Mohawk Industries Inc., Tarkett S.A., The Dixie Group Inc., Shaw Industries Group Inc., Interface Inc., Beaulieu International Group, Oriental Weavers Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugs Market Strategic Shifts
Production technology, chemical compliance frameworks, and procurement centralization are converging to reshape how rugs are specified, manufactured, and distributed across residential and commercial channels.
Solution-dyed polyester fiber technology is miniaturizing color batch variability and enabling precision-matched hospitality installations. Hotel procurement teams in Dubai specify this material for stain-resistant corridor and ballroom applications. The technology is compressing lead times for custom color runs from weeks to days.
EPA indoor air quality standards for VOC emissions are tightening formulations for synthetic rug backings sold in the United States. Manufacturers serving the residential segment are reformulating adhesives and latex coatings to meet stricter thresholds. California and New York building codes are driving early compliance adoption ahead of federal mandates.
Direct specification relationships between hospitality procurement teams and manufacturing clusters are disintermediating traditional distributor networks. Hotel development groups in Riyadh now contract directly with Egyptian and Indian producers for custom sizing. This pattern concentrates volume with vertically integrated suppliers capable of design-to-delivery coordination.
Rugs Market Segmentation
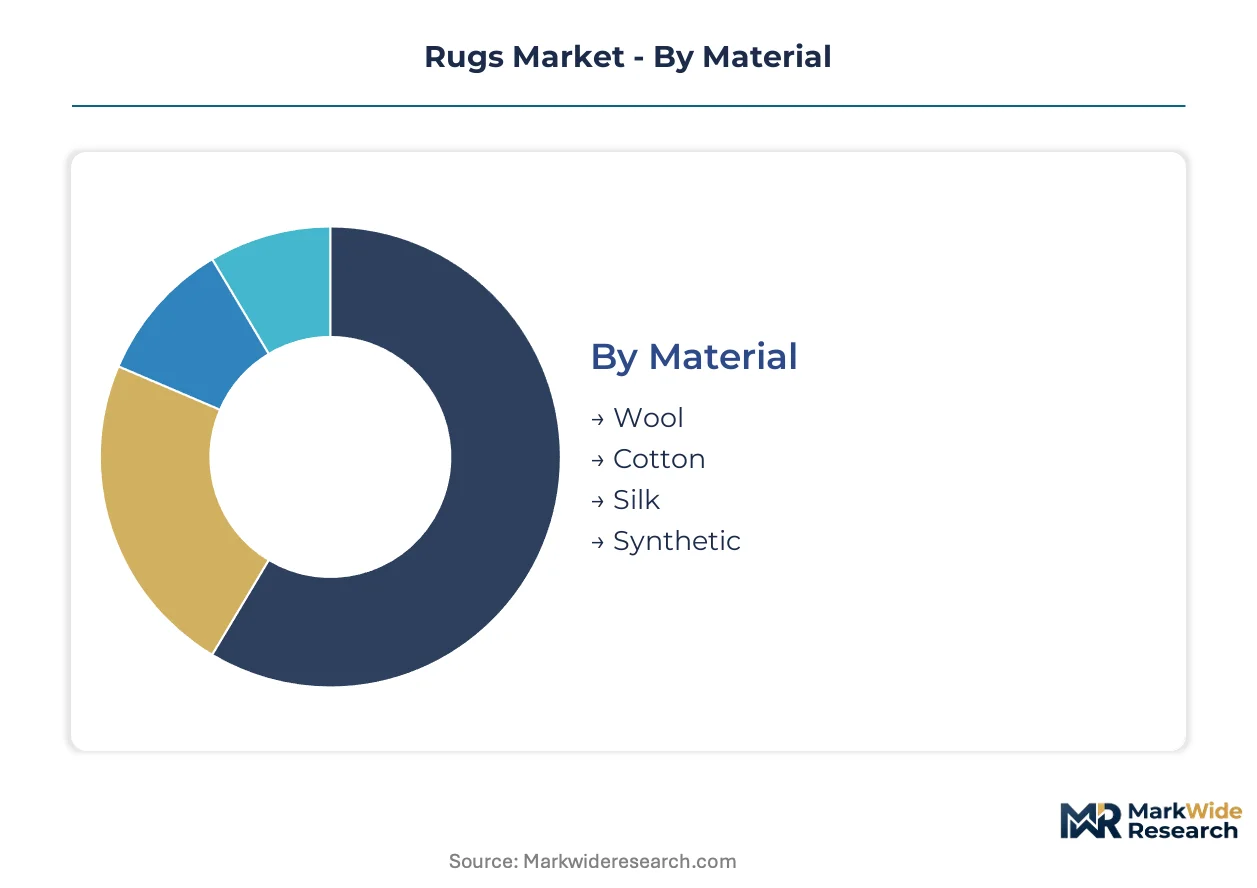
Material composition and end-use application create divergent margin profiles across the rugs market. Procurement specifications from Dubai hotel developers and REACH-compliant European buyers fragment demand into distinct technical tiers.
Material:
Wool and synthetic volumes split between export-led premium channels and domestic mass-market consumption, with silk and cotton occupying intermediate positions.
- Wool:Hand-knotted construction above 100 knots per square inch defines quality grading for German and United States premium buyers. Jaipur and Bhadohi clusters supply density-grade pieces where auction volatility in New Zealand and Australian wool markets compresses margin predictability.
- Synthetic:Solution-dyed polyester and nylon formulations dominate stain-resistant hospitality specifications in Dubai corridor and ballroom installations. Fire-retardant backings meet maritime procurement standards for cruise ship outfitters seeking long-duration order books.
- Cotton:Flat-weave dhurries and kilims serve price-sensitive residential segments with shorter replacement cycles.
- Silk:High-knot-density accent pieces command ceremonial and luxury residential placement in Middle Eastern markets.
Wool commands the established base. The steepest expansion runs through synthetic fiber systems.
Style:
Cost tier differentiation separates artisan hand-knotting premiums from machine-tufted volume production, with design complexity driving specification decisions.
- Traditional:Persian and Oriental patterns require master craftsperson density execution for United States and German collectors. Generational transition away from Bhadohi apprenticeships threatens quality consistency for fine wool segments.
- Modern:Geometric minimalism aligns with corporate fit-out procurement in United States commercial real estate. Cradle to Cradle certification pathways enable premium positioning for closed-loop recycling compliance.
- Bohemian:Distressed vintage aesthetics target residential volume through digital design-to-loom integration.
- Contemporary:Abstract forms accommodate custom color matching through solution-dyed fiber technology with compressed lead times.
Traditional styling retains the premium price tier. Contemporary segments are climbing the fastest on specification flexibility.
Size:
Application-driven dimension requirements fragment manufacturing batch economics between standardized residential SKUs and custom hospitality dimensions.
- Large:Custom dimensioning for hotel lobbies and ballroom installations in Riyadh generates outsized margin pools through fire-retardant specification premiums.
- Runner:Corridor applications dominate cruise ship and hospitality procurement with repetitive linear patterns enabling production efficiency.
- Medium:Standard living room dimensions serve residential replacement cycles through big-box retail distribution.
- Small:Accent and bath mat specifications compete with hard surface alternatives in price-sensitive channels.
Large format captures hospitality margins. Runner specifications are gaining share fastest on maritime contract concentration.
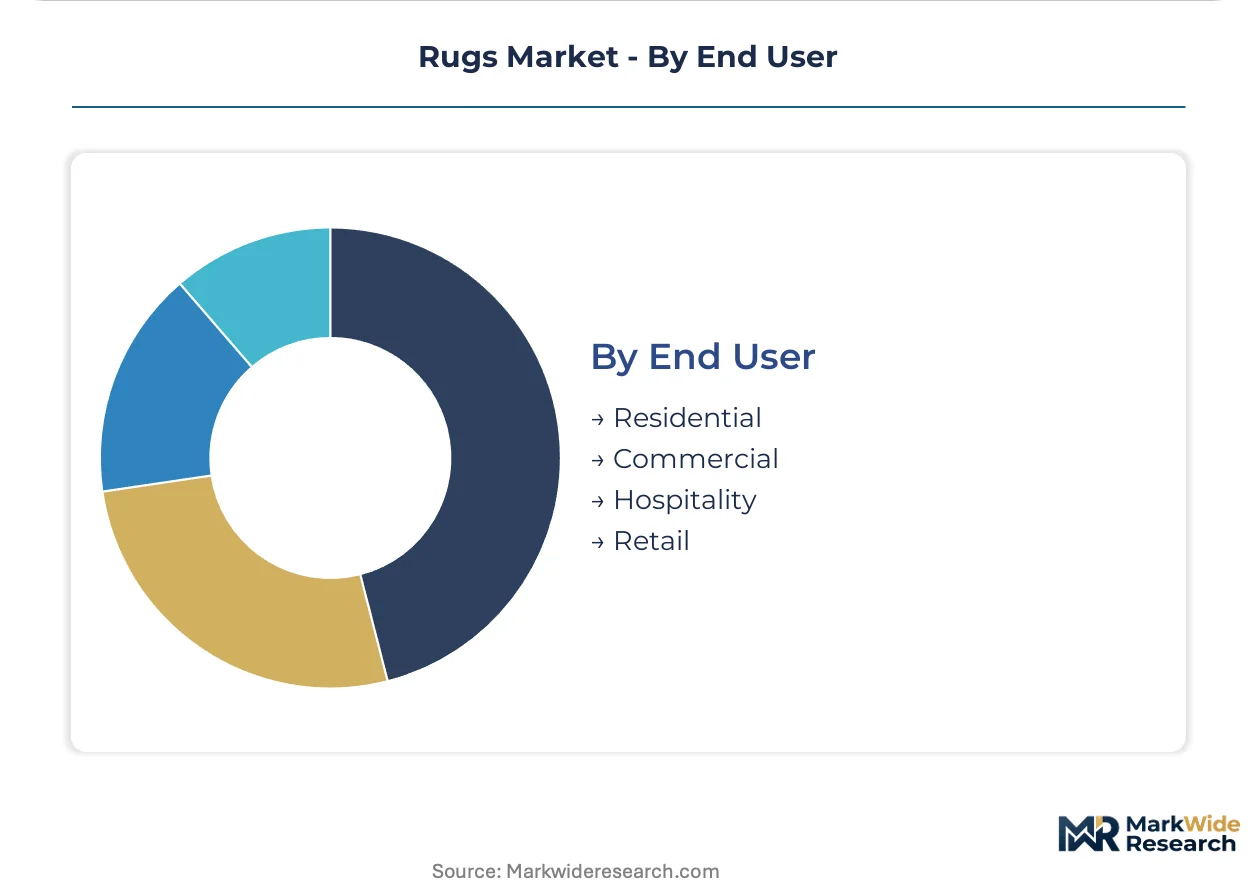
End User:
Customer type determines certification burden and procurement centralization, with hospitality buyers disintermediating traditional distributor networks.
- Hospitality:Direct specification relationships between Dubai and Riyadh development groups and Egyptian or Indian manufacturing clusters compress distributor margins. Custom sizing and fire-retardant standards create multi-year order visibility.
- Residential:Volume buyers prioritize stain resistance and price accessibility through solution-dyed synthetic fiber adoption.
- Commercial:Corporate fit-outs in United States markets reward Cradle to Cradle certification with specification premiums.
- Retail:Inventory risk concentrates with distributors serving fragmented residential demand through seasonal pattern rotation.
Residential volume commands the unit base. Hospitality procurement is expanding most quickly on direct manufacturer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement by ECHA anchors European compliance costs and redirects dye chemistry investments toward certified natural alternatives. Procurement centralization in Middle Eastern hospitality and artisan cluster concentration in South Asia define regional competitive positioning.
United States
Corporate fit-out demand for Cradle to Cradle certified commercial rugs drives specification premiums in New York and California markets. EPA indoor air quality standards for VOC emissions tighten adhesive and latex backing formulations ahead of federal mandates. Dalton, Georgia hosts concentrated tufting and carpet manufacturing infrastructure serving residential volume channels.
Germany
REACH-compliant natural dye processes reward margin differentiation for manufacturers serving premium residential collectors. BSI certification requirements for textile durability shape export readiness protocols for hand-knotted wool imports. Frankfurt and Hamburg procurement offices centralize European hospitality specification decisions for fire-retardant custom installations.
India
BIS certification for textile durability and flammability determines export market access for Bhadohi and Mirzapur manufacturers. PLI scheme incentives for textile manufacturing upgrade automation in Jaipur artisan clusters. Hand-knotted wool production above 100 knots per square inch supplies density-grade pieces to United States and German premium buyers.
United Arab Emirates
Dubai hotel development groups expand floor-covering budgets for luxury property installations with custom sizing requirements. MOHAP product safety standards align with maritime fire-retardant specifications for cruise ship outfitting contracts. Direct procurement relationships with Egyptian and Indian manufacturers disintermediate traditional distributor networks.
Egypt
Oriental Weavers Group anchors manufacturing scale for synthetic fiber rug exports into North American big-box retail. Egyptian production infrastructure supports solution-dyed polyester volume for stain-resistant hospitality specifications. Cairo and Alexandria industrial zones concentrate tufting machinery and direct distribution capabilities.
Rugs Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive fiber production and closed-loop recycling infrastructure defining the upper layer. Mid-scale manufacturers compete on design-to-delivery speed through automated CAD-to-loom integration. Three archetypes dominate: vertically integrated fiber-to-finish operators, artisan-cluster coordinators, and hospitality-focused custom specification houses. Competitive moves concentrate on direct procurement relationships with Dubai and Riyadh developers, plus certification stacking for EPA and BIS compliance.
Within the integrated fiber production tier, Mohawk Industries and Shaw Industries Group exemplify captive nylon supply chain control. Oriental Weavers Group occupies a position representing Egyptian manufacturing scale and North American retail distribution density. Among specialty hospitality suppliers, Nourison Industries and Interface Inc. anchor the custom specification segment for fire-retardant maritime and corporate fit-out applications.
| Leading Market Players |
|---|
| Nourison Industries |
| Milliken & Company |
| Mohawk Industries Inc. |
| Tarkett S.A. |
| The Dixie Group Inc. |
| Shaw Industries Group Inc. |
| Interface Inc. |
| Beaulieu International Group |
| Oriental Weavers Group |
| Others |
Value Chain & Pricing Dynamics
Egyptian manufacturing scale at Oriental Weavers Group compresses unit economics for synthetic fiber rugs while simultaneously anchoring price floors for hand-knotted wool segments where Jaipur and Bhadohi artisan clusters face capacity constraints. This divergence between automated volume production and craft-limited premium supply concentrates pricing power with vertically integrated operators capable of spanning both tiers.
Pricing Analysis
Price spreads between Egyptian synthetic exports and Indian hand-knotted wool pieces exceed threefold across German and United States import channels. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified natural dye products from conventional synthetic formulations and basic flat-weave cotton alternatives. Pricing pressure stems from New Zealand wool auction volatility compressing margins for density-grade producers above 100 knots per square inch. Hospitality procurement teams in Dubai demonstrate lowest price sensitivity due to fire-retardant specification premiums, while residential volume buyers through North American big-box retail concentrate price-driven sourcing decisions.
Supply Chain Analysis
Inventory cycles for custom hospitality specifications stretch longer than standardized residential SKUs due to fire-retardant certification sequencing and maritime logistics coordination. Supply concentrates in Egypt for synthetic fiber tufting, India for hand-knotted wool craftsmanship, and United States for commercial-grade Cradle to Cradle certified production. Raw material dependencies center on New Zealand and Australian wool auctions, solution-dyed polyester fiber systems, and recycled PET backing substrates. Single-source vulnerability runs through Bhadohi and Mirzapur artisan clusters where generational skill attrition threatens output consistency. Distribution runs through direct procurement relationships between Dubai and Riyadh hotel developers and manufacturing clusters, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality procurement consolidation in Dubai and Riyadh shifts buyer power toward direct manufacturer relationships, fragmenting traditional distributor margins and rewarding vertically integrated suppliers with design-to-delivery capabilities.
For Market Incumbents: Shield margin pools in premium hand-knotted wool segments by securing long-term apprenticeship pipelines in Bhadohi and Mirzapur before generational skill attrition accelerates. Anchor synthetic fiber competitiveness through captive nylon production or backward integration into solution-dyed polyester fiber systems to offset Egyptian manufacturing scale advantages. Certification stacking for EPA indoor air quality and BIS textile durability compliance creates switching costs against mid-scale competitors lacking compliance infrastructure. For New Entrants and Emerging Players: Lead with digital design-to-loom integration targeting bohemian and contemporary residential segments where compressed sample-to-production timelines differentiate against established artisan networks. White-space concentration sits in cruise ship outfitting contracts for fire-retardant custom specifications, a segment where maritime procurement standards and long-duration order books reward specialized entrants. Direct specification relationships with Middle Eastern hospitality developers offer faster penetration than contested North American big-box retail channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with captive fiber production and closed-loop recycling infrastructure over pure-play design houses lacking manufacturing control. Long-term viability through the next technology cycle hinges on carbon border adjustment preparedness and extended producer responsibility framework compliance in European Union and United States markets. Acquisition target archetypes include hospitality-focused custom specification houses with established Dubai and Riyadh relationships and artisan-cluster coordinators with secured master craftsperson pipelines. Monitor carbon border adjustment implementation timelines as the critical inflection signal for wool import cost structures and synthetic fiber competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive nylon or solution-dyed polyester supply secures margin control against Egyptian manufacturing scale advantages. |
| Cradle to Cradle Certification Investment | Closed-loop recycling infrastructure unlocks specification premiums in United States corporate fit-out procurement. |
| Artisan Apprenticeship Pipeline Securement | Long-term craftsperson development in Bhadohi and Mirzapur defends quality consistency for premium wool segments. |
| Direct Hospitality Procurement Relationships | Bypassing distributor networks with Dubai and Riyadh hotel developers concentrates volume and margin capture. |
| Fire-Retardant Specification Capability Buildout | Maritime compliance certification opens cruise ship outfitting contracts with multi-year order visibility. |
Study Parameters
Cross-validation between primary fieldwork with hospitality procurement directors, textile manufacturing executives, and artisan cluster coordinators and secondary analysis of BIS certification records, EPA regulatory filings, and REACH compliance databases anchors the qualitative findings. Bottom-up triangulation incorporates production capacity assessments from Bhadohi, Jaipur, and Egyptian manufacturing zones alongside top-down demand modeling from United States and German import statistics. Trade flow analysis from customs records and hospitality development pipeline tracking from Dubai and Riyadh construction permits provide secondary validation layers.
Sensitivity analysis across wool auction price scenarios, carbon border adjustment cost assumptions, and artisan skill attrition rates stress-tests projection stability throughout the forecast period. Segmentation dimensions span material composition, construction technique, style category, size format, and end-user application with geographic regulatory cluster differentiation. CAGRs derive from weighted average growth trajectories across these segments calibrated to historical volume and value correlations. Industry-specific forecast inputs incorporate REACH enforcement timelines by ECHA and PLI scheme incentive disbursement patterns in Indian textile manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained hospitality development momentum in Dubai and Riyadh or accelerated carbon border adjustment implementation would require recalibration. Forecasts reflect documented assumptions regarding wool price volatility ranges and master craftsperson pipeline sustainability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market