
 Sheet Flooring Market | 2026-2036
Sheet Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Flooring Market Analysis
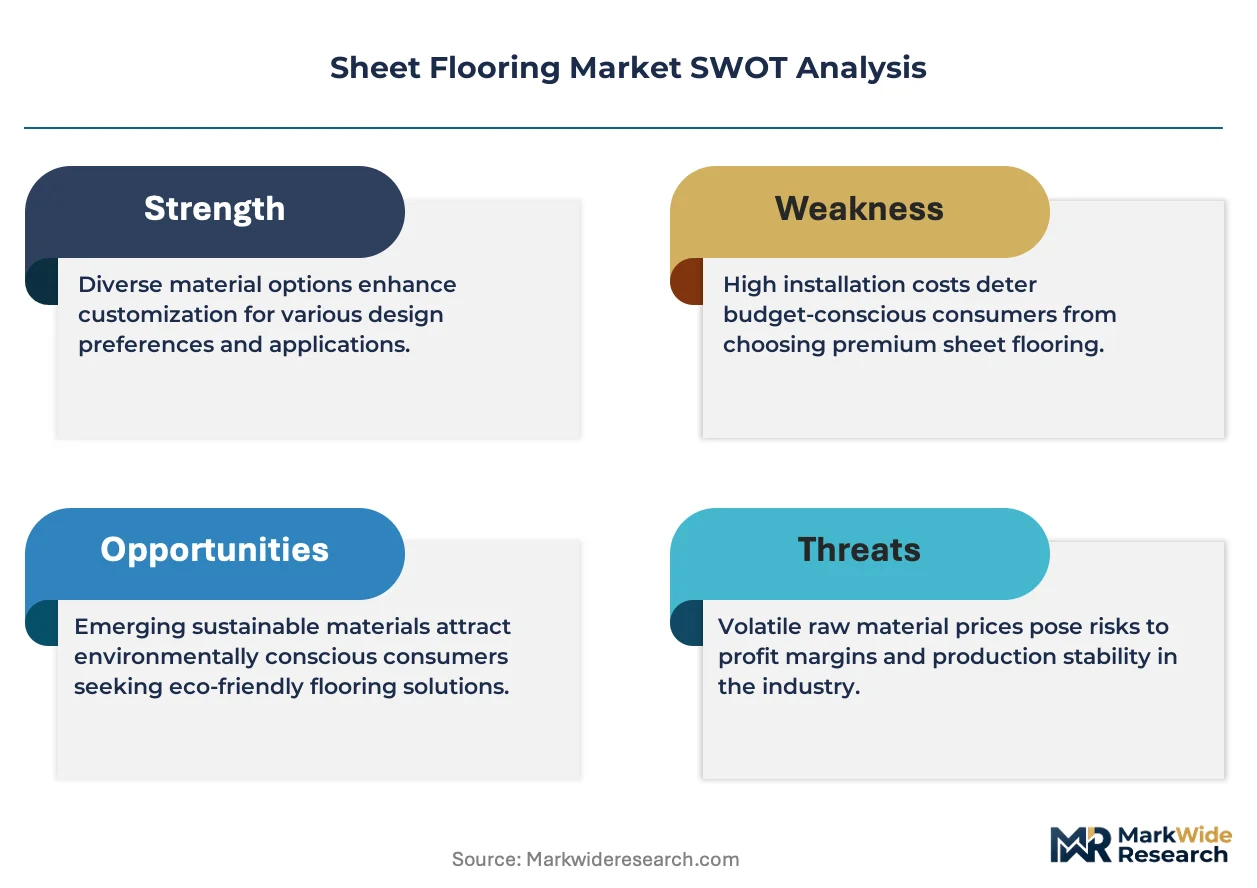
FloorScore certification is collapsing as a baseline qualifier for commercial project eligibility, compressing the vendor pool to manufacturers with verified low-VOC supply chains. Mohawk Industries leverages captive resin production to sustain margin stability across vinyl roll goods. Tarkett anchors European healthcare specification through Cradle to Cradle-certified linoleum lines. Shaw Industries Group differentiates via PET recycled-content backing systems that meet LEED v4.1 compliance thresholds.
Sheet flooring comprises continuous rolled material manufactured through calendering or extrusion of polymer compounds, typically supplied in widths of 6 to 12 feet for seamless installation across large surface areas. The product category serves primarily to deliver durable, moisture-resistant walking surfaces with reduced seam vulnerability versus tile or plank alternatives. Vinyl roll goods dominate volume shipments owing to cost-positioning in multi-family residential replacement cycles, while linoleum retains specification loyalty in European education and healthcare sectors where solvent-free composition carries procurement weight. Rubber sheet concentrates in industrial and transportation end uses where static-dissipative and heavy-load performance justify premium positioning.
EPA regulations on formaldehyde emissions from composite wood products extend testing burdens to flooring substrates, while FloorScore and GREENGUARD Gold certifications now gate access to K-12 and institutional bidding in the United States. The EU's REACH Annex XVII restrictions on short-chain chlorinated paraffins and pending ECHA evaluations on PVC additives are reshaping compound formulation strategies for exporters serving European project specifications. Stakeholders must monitor accelerating state-level extended producer responsibility laws in California and New York that will impose end-of-life collection obligations on vinyl flooring suppliers.
Market Dynamics
EU REACH Annex XVII restrictions on phthalate plasticizers and short-chain chlorinated paraffins are forcing compound reformulation across vinyl roll goods, compressing supplier margins while accelerating bio-based polymer development timelines for exporters serving European healthcare and education specifications.
Growth Catalysts
- Healthcare infection control mandates:Hospital construction codes in Germany and France now specify seamless sheet flooring for operating theaters and patient rooms, driving specification volume for low-porosity vinyl and linoleum systems.
- REACH regulatory acceleration:ECHA evaluations on PVC additives are compelling manufacturers to validate alternative plasticizers ahead of 2025 restriction timelines, creating first-mover advantage for compliant formulation portfolios.
- Calendering efficiency gains:Multi-roll extrusion lines with real-time thickness control are reducing material waste in continuous vinyl production, improving yield rates for commercial-grade roll goods.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer costs fluctuate with ethylene and propylene feedstock pricing, compressing margin stability for non-integrated manufacturers lacking captive chlor-alkali capacity.
- Substitution pressure from LVT:Luxury vinyl tile with rigid core construction is capturing multi-family residential replacement demand previously served by sheet vinyl, particularly in North American rental housing.
- End-of-life collection obligations:California's pending extended producer responsibility legislation will impose take-back infrastructure costs on vinyl flooring suppliers without established recycling networks.
Strategic Opportunities
- Underpenetrated Indian healthcare infrastructure:Hospital accreditation standards under the country's national health mission are beginning to specify anti-microbial flooring, creating specification entry points for compliant sheet vinyl.
- Convergence of bio-based binders and digital printing:Linoleum formulations using linseed oil and wood flour are combining with high-definition rotogravure decoration to challenge vinyl's aesthetic dominance in European institutional segments.
- Green building certification tailwinds:LEED v4.1 and BREEAM credits for low-VOC materials are elevating FloorScore and GREENGUARD Gold certifications from preference to bidding prerequisite in K-12 and university construction.
Industry Challenges
- Certification timeline compression:Third-party emissions testing for FloorScore and Cradle to Cradle now requires 90-120 day validation cycles, delaying product launches and freezing specification windows.
- Compound formulation complexity:Replacing legacy phthalate plasticizers with bio-based alternatives while maintaining stain resistance and dimensional stability demands extended R&D cycles and capital-intensive pilot line testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Flooring Market |
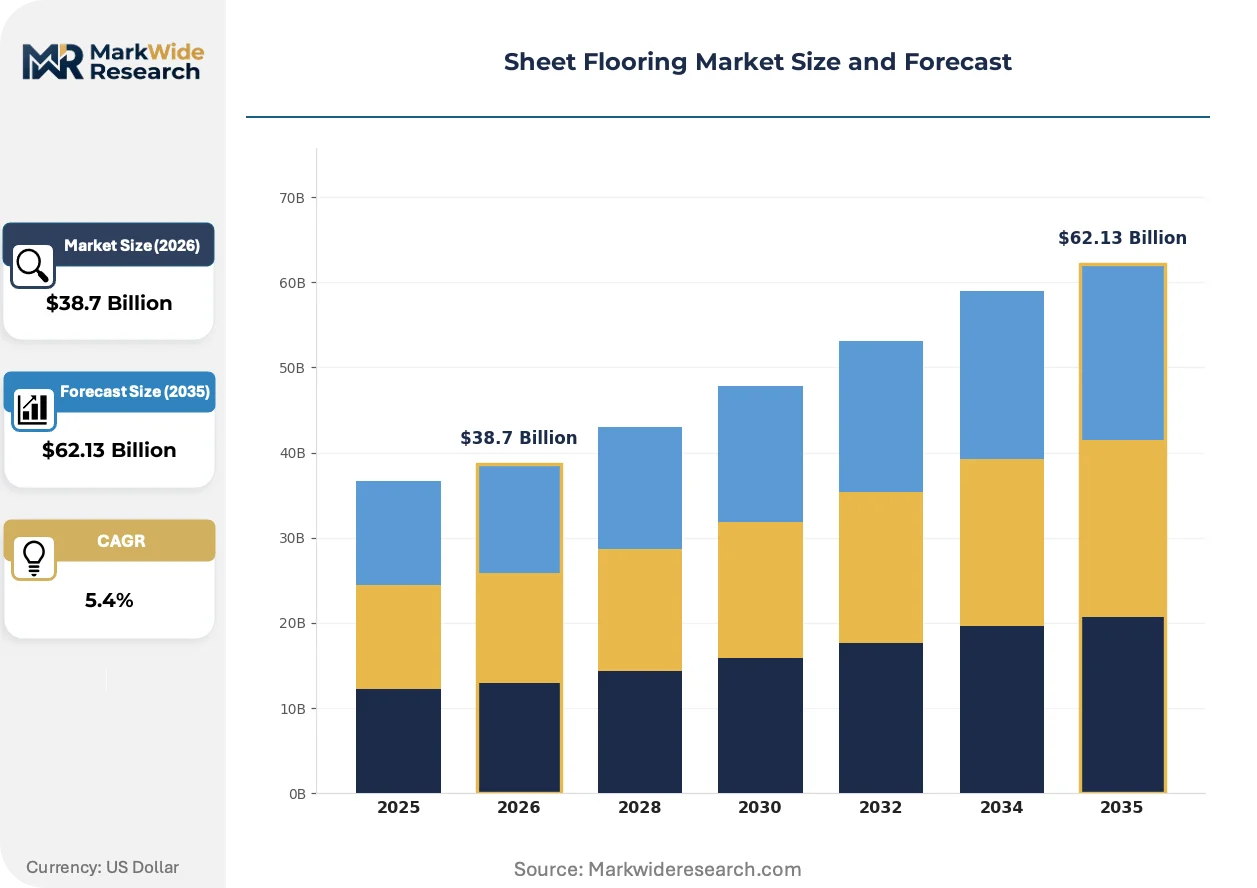
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Linoleum, Rubber, Cork Installation Method: Glue-Down, Loose Lay, Interlocking, Floating End User: Residential, Commercial, Industrial, Hospitality Thickness: 2mm, 3mm, 5mm, 8mm |
| Companies Covered | Mohawk Industries, Tarkett, Shaw Industries Group, Gerflor, Forbo, Interface, Armstrong Flooring, Beaulieu International Group, Milliken & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Flooring Market Emerging Trajectories
Digital decoration technologies and regulatory chemistry constraints are converging to redefine material specification hierarchies across commercial construction, with seamless installation performance now competing against modular aesthetics for project-level decisions.
High-definition rotogravure printing systems with 600+ dpi resolution are enabling photorealistic stone and wood replication on vinyl sheet substrates. Healthcare and hospitality specifiers in Germany and the Netherlands are adopting these systems for branded environment consistency. The technology is miniaturizing the aesthetic gap between sheet goods and premium LVT, forcing manufacturers to compete on installation speed rather than visual differentiation alone.
ECHA's pending restriction proposals on medium-chain chlorinated paraffins under REACH Annex XVII are extending compliance burdens beyond short-chain variants already banned. Compounders serving European export markets must reformulate stabilizer packages and validate flame-retardant performance with alternative chemistries. Rubber sheet manufacturers for transportation applications face the steepest retesting obligations given fire safety certification dependencies.
Specification decisions are migrating from general contractors to facilities management departments with total-cost-of-ownership mandates. Healthcare systems in France and the United Kingdom are consolidating flooring procurement through framework agreements that bundle installation, maintenance, and replacement cycles. This concentration is displacing fragmented project-by-project bidding and rewarding manufacturers with national service networks and certified installer training programs.
Sheet Flooring Market Segmentation
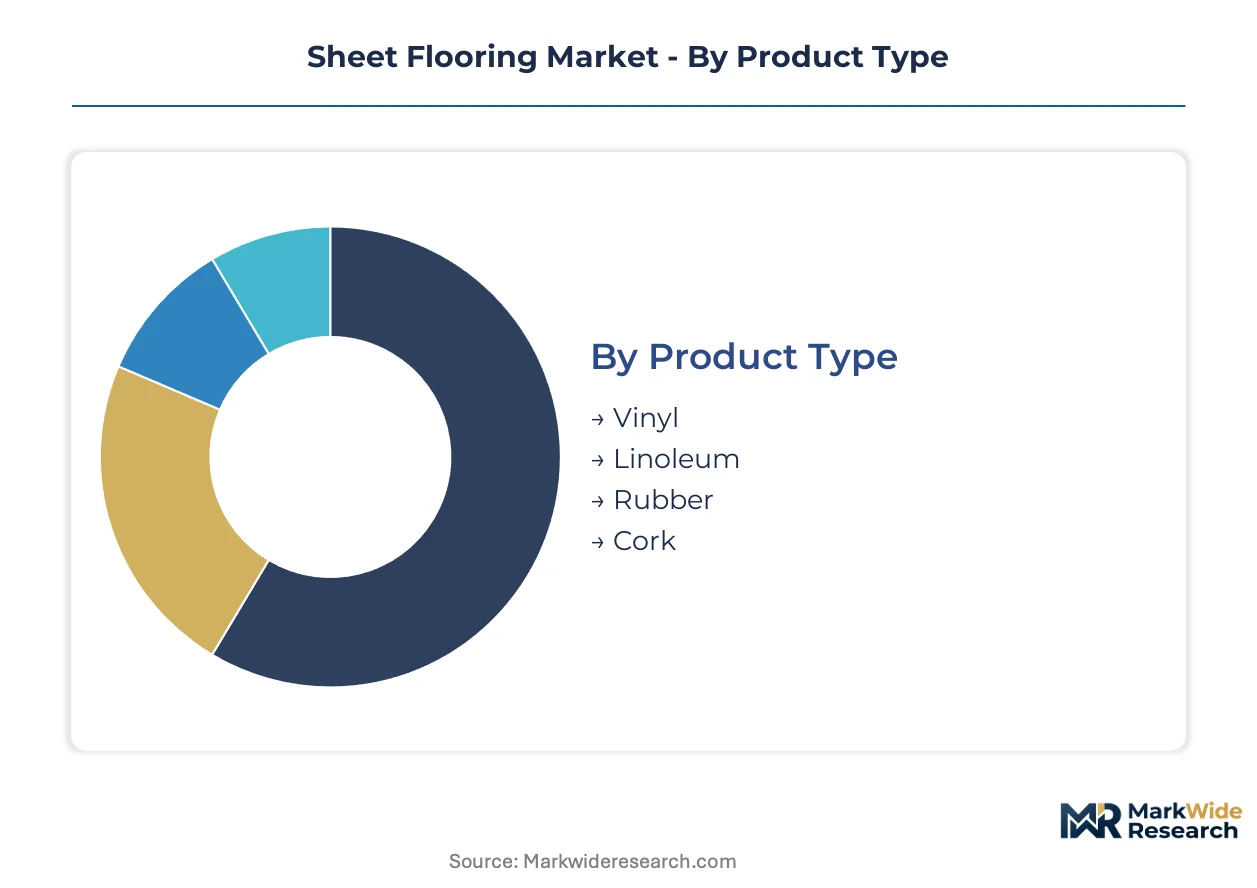
Segmentation in sheet flooring reveals distinct margin architectures across material chemistry, installation labor intensity, and specification grade. Procurement patterns diverge sharply between residential replacement cycles and institutional framework agreements, demanding tailored formulation and certification strategies.
Product Type:
Premium margin pools concentrate in bio-based formulations serving European healthcare specifications, while commodity vinyl roll goods compete on calendering efficiency and captive resin economics.
- Vinyl:Polyvinyl chloride compounds calendered into continuous rolls dominate volume shipments through cost positioning in multi-family residential replacement. Hospital construction codes in Germany and France now specify low-porosity vinyl systems for operating theaters, tightening compliance requirements around plasticizer chemistry.
- Linoleum:Linseed oil and wood flour binders deliver solvent-free composition that retains procurement loyalty in European education and healthcare sectors. Cradle to Cradle certification anchors specification against vinyl alternatives in Dutch and French institutional bidding.
- Rubber:Static-dissipative and heavy-load performance justifies premium positioning in industrial and transportation end uses.
- Cork:Natural acoustic properties serve niche commercial applications demanding renewable content credentials.
The dominant share belongs to vinyl, while linoleum is closing the gap fastest through regulatory chemistry constraints.
Installation Method:
Volume concentration tracks labor cost arbitrage between skilled adhesive application and rapid deployment systems for renovation timelines.
- Glue-Down:Full-spread adhesive systems deliver permanent bond strength for heavy commercial traffic loads in healthcare and hospitality corridors. German facilities management frameworks increasingly bundle glue-down installation with maintenance contracts, locking in specification continuity.
- Loose Lay:Friction-backed sheet goods enable rapid renovation without adhesive curing delays, capturing multi-family residential turnover demand in North American rental housing.
- Interlocking:Precision-edged systems reduce seam vulnerability in modular commercial layouts.
- Floating:Underlayment-integrated installation accommodates subfloor irregularity in renovation applications.
Glue-down retains the largest installed base, though loose lay is expanding most quickly through speed-to-occupancy mandates.
End User:
Specification authority migrates toward facilities management departments with total-cost-of-ownership mandates, compressing project-by-project bidding fragmentation.
- Commercial:Healthcare systems in France and the United Kingdom consolidate procurement through framework agreements bundling installation, maintenance, and replacement cycles. FloorScore and GREENGUARD Gold certifications gate K-12 and university construction access in the United States.
- Residential:Multi-family replacement cycles drive vinyl roll goods volume through cost positioning against LVT substitution pressure.
- Industrial:Heavy-load and chemical resistance requirements concentrate demand in rubber sheet systems.
- Hospitality:Branded environment consistency demands high-definition rotogravure decoration matching premium LVT aesthetics.
Commercial commands the deepest specification value, with hospitality climbing fastest through digital decoration convergence.
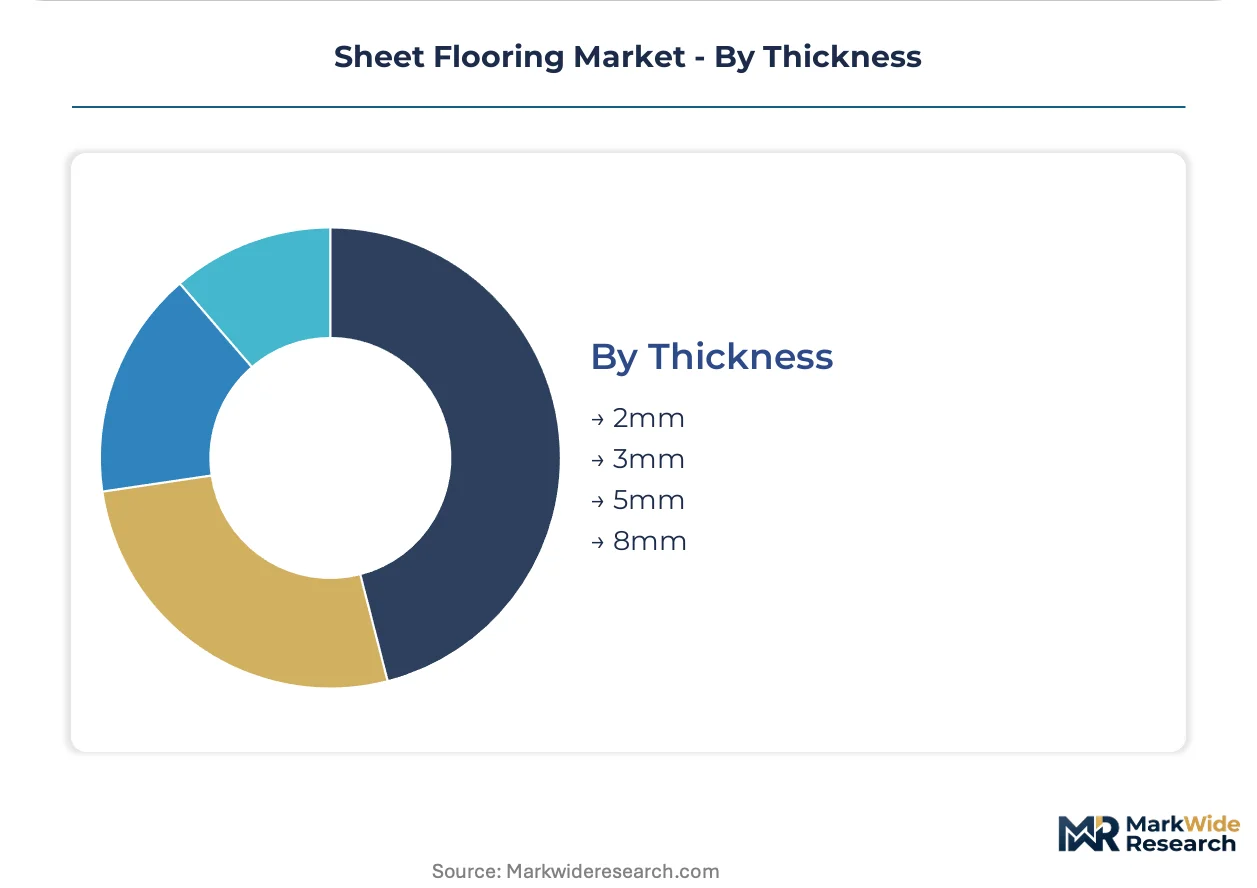
Thickness:
Material yield rates and freight economics favor thinner gauges for volume residential, while acoustic and indentation performance drive thicker specifications in healthcare and education.
- 2mm:Thin-gauge vinyl maximizes roll length per freight unit for cost-sensitive residential replacement in multi-family housing.
- 3mm:Mid-range gauge balances durability and material efficiency across light commercial applications.
- 5mm:Enhanced acoustic dampening serves healthcare patient rooms and education facilities where footfall noise reduction carries specification weight.
- 8mm:Maximum indentation resistance targets heavy commercial corridors and industrial applications with rolling load requirements.
2mm holds the volume lead, yet 5mm is gaining share fastest through healthcare acoustic mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Annex XVII restrictions on phthalate plasticizers are redirecting procurement flows across major construction markets. Healthcare infection control mandates and green building certification requirements are reshaping specification patterns in Germany, the United States, China, India, and France.
Germany
Hospital construction codes in Bavaria and North Rhine-Westphalia now mandate seamless sheet flooring for operating theaters. The country's national health mission aligns procurement with ECHA evaluations on PVC additives. The Frankfurt-Rhine-Main corridor concentrates specification authority among facilities management frameworks bundling installation and maintenance contracts.
United States
K-12 construction in Texas and California drives FloorScore-certified volume through LEED v4.1 compliance thresholds. EPA regulations on formaldehyde emissions extend testing burdens to flooring substrates. The Southeast corridor from Florida to Georgia captures multi-family residential replacement cycles through loose-lay installation speed.
China
Hospital accreditation standards under the national health mission are beginning to specify anti-microbial flooring in tertiary care facilities. The country's GB standards for indoor air quality increasingly reference low-VOC material specifications. The Yangtze River Delta manufacturing cluster supplies calendered vinyl roll goods for domestic healthcare and export markets.
India
Healthcare infrastructure expansion under Ayushman Bharat creates specification entry points for compliant sheet vinyl in Maharashtra and Karnataka. The country's Bureau of Indian Standards is developing flooring performance benchmarks for institutional procurement. The Delhi-NCR corridor concentrates commercial renovation demand from government and private hospital networks.
France
Education sector procurement in Île-de-France favors Cradle to Cradle-certified linoleum for solvent-free composition. ANSM guidance on healthcare facility materials reinforces seamless flooring mandates for patient safety. The Lyon-Grenoble axis anchors specification loyalty for bio-based formulations in university and research facility construction.
Sheet Flooring Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and captive resin economics. The vendor base concentrates around manufacturers with verified low-VOC supply chains and established installer training networks. Three archetypes dominate: integrated resin producers, certification-focused specialists, and regional service bundlers. M&A activity targets installer network consolidation, while portfolio diversification pushes into bio-based binder development.
Within the integrated manufacturing tier, Mohawk Industries and Shaw Industries Group represent North American scale positions anchored by captive chlor-alkali capacity. Tarkett exemplifies the European certification-specialist archetype through Cradle to Cradle-validated linoleum lines serving healthcare framework agreements. These three occupy positions defined by supply chain control depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Mohawk Industries |
| Tarkett |
| Shaw Industries Group |
| Gerflor |
| Forbo |
| Interface |
| Armstrong Flooring |
| Beaulieu International Group |
| Milliken & Company |
| Others |
Supply Flow & Price Mechanics
Bio-based plasticizer substitution for legacy phthalate formulations is simultaneously redrawing raw material sourcing maps and compressing formulation economics across European export supply chains. Manufacturers reformulating for REACH Annex XVII compliance face extended R&D cycles and pilot line investments that widen cost spreads between compliant and non-compliant product tiers.
Pricing Analysis
Certification level (FloorScore, GREENGUARD Gold, Cradle to Cradle) creates the primary spread across commercial project bidding, with verified low-VOC supply chains commanding premium positioning in K-12 and healthcare construction. Three-tier pricing structure separates Cradle to Cradle-validated linoleum from FloorScore-certified vinyl and uncertified commodity roll goods. Cost compression in standard-grade vinyl is intensifying because LVT substitution pressure in multi-family residential channels forces margin sacrifice to defend volume. Facilities management departments with framework agreements show lowest price sensitivity, while fragmented general contractor bidding retains highest sensitivity.
Supply Chain Analysis
Inventory cycles for PVC resin and plasticizer feedstocks now stretch 60-90 days as manufacturers pre-position compliant compounds ahead of ECHA restriction timelines. Supply concentrates in Germany, China, and the United States for calendered vinyl roll goods, with the Yangtze River Delta and Frankfurt-Rhine-Main corridor anchoring respective export and specification-grade production. Raw material dependencies center on ethylene and propylene feedstocks, PVC resin, and bio-based linseed oil alternatives. Single-source vulnerability in chlor-alkali capacity creates concentration risk for non-integrated manufacturers. Distribution runs through national service networks with certified installer training programs, particularly for healthcare framework agreements bundling installation and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through facilities management framework agreements in France and the United Kingdom, displacing fragmented project-by-project bidding and rewarding manufacturers with bundled service capabilities.
For Market Incumbents: Secure captive chlor-alkali capacity or long-term resin offtake agreements to insulate margin stability from petrochemical input volatility. Deepen Cradle to Cradle and FloorScore certification portfolios ahead of ECHA restriction timelines to lock specification continuity in European healthcare and education procurement. LVT substitution pressure in North American residential channels demands defensive positioning through loose-lay installation speed or glue-down bundling with maintenance contracts. For New Entrants and Emerging Players: Differentiate on bio-based binder formulations targeting Dutch and French institutional bidding where solvent-free composition carries procurement weight. Target underpenetrated Indian healthcare infrastructure under Ayushman Bharat expansion, where hospital accreditation standards are beginning to specify anti-microbial flooring. Pursue digital printing convergence with linoleum substrates to challenge vinyl's aesthetic dominance in European education segments. For Investors and Strategic Acquirers: REACH Annex XVII acceleration on medium-chain chlorinated paraffins reshapes the acquisition landscape toward compounders with validated alternative stabilizer packages. Long-term viability favors manufacturers with backward integration into resin production and established take-back infrastructure for pending extended producer responsibility legislation. Target acquisition archetype: regional service bundlers with certified installer networks in consolidated healthcare procurement markets. Watch ECHA evaluation timelines as inflection signal for formulation compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Mohawk Industries sustains margin stability through captive chlor-alkali capacity across vinyl roll goods. |
| Cradle to Cradle Certification Investment | Tarkett anchors European healthcare specification through validated linoleum lines in framework agreements. |
| Installer Network Consolidation | Facilities management bundling demands national service coverage with certified training programs. |
| Bio-Based Binder Development | Forbo and Gerflor challenge vinyl aesthetics through linseed oil formulations with high-definition decoration. |
| Extended Producer Responsibility Infrastructure | California and New York legislation imposes end-of-life collection obligations requiring recycling network investment. |
Methodological Framework
A standing panel of facilities management directors, hospital procurement managers, calendering plant engineers, and flooring distribution channel heads provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA formaldehyde emission filings, ECHA restriction proposal databases, hospital procurement framework agreements in France and the United Kingdom, and SEC 10-K disclosures from listed manufacturers. Bottom-up volume modeling across product type, installation method, end user, and thickness segments was triangulated against top-down construction spend data.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled demand drivers including healthcare infection control mandates, REACH regulatory acceleration, and green building certification tailwinds. Segmentation dimensions spanned material chemistry, installation labor intensity, specification grade, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to construction spend elasticities and replacement cycle frequencies.
Material uncertainties — petrochemical feedstock volatility, ECHA restriction timeline acceleration, and state-level extended producer responsibility implementation — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory compliance cost pass-through and substitution elasticity between sheet goods and modular alternatives. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market