

Residential Carpet Roll Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Carpet Roll Market Insights
The split between premium wool-nylon blends and commodity polyester-olefin rolls is realigning how manufacturers structure their product portfolios. Mohawk Industries leverages its integrated fiber-to-finished-goods pipeline to sustain margin capture across both tiers. Shaw Industries Group anchors its position through large-scale tufting capacity concentrated in the southeastern United States. Engineered Floors differentiates via specialized PET recycling streams that feed lower-cost residential offerings.
A residential carpet roll is a continuous length of tufted or woven floor covering, typically manufactured in 12-foot widths with pile weights ranging from 20 to 60 ounces per square yard, designed for permanent installation in private dwellings. Nylon and triexta fiber categories command structural preference among homeowners prioritizing stain resistance and durability under heavy foot traffic. Polyester occupies the fastest-expanding volume tier as recycled-content formulations attract cost-conscious buyers in entry-level housing segments. Wool retains concentrated margin pools in custom and luxury applications despite its smaller overall share.
EPA regulations on formaldehyde emissions in composite wood products extend to carpet underlayment substrates, compelling reformulation across supply chains. California Air Resources Board (CARB) Phase 2 standards for VOCs from installation adhesives shape product approval timelines for national distribution. Carpet and Rug Institute (CRI) Green Label Plus certification functions as a de facto market access filter for rolls entering multi-family property management channels. Stakeholders must track how evolving state-level chemical disclosure laws redistribute compliance burdens between domestic mills and import-dependent distributors.
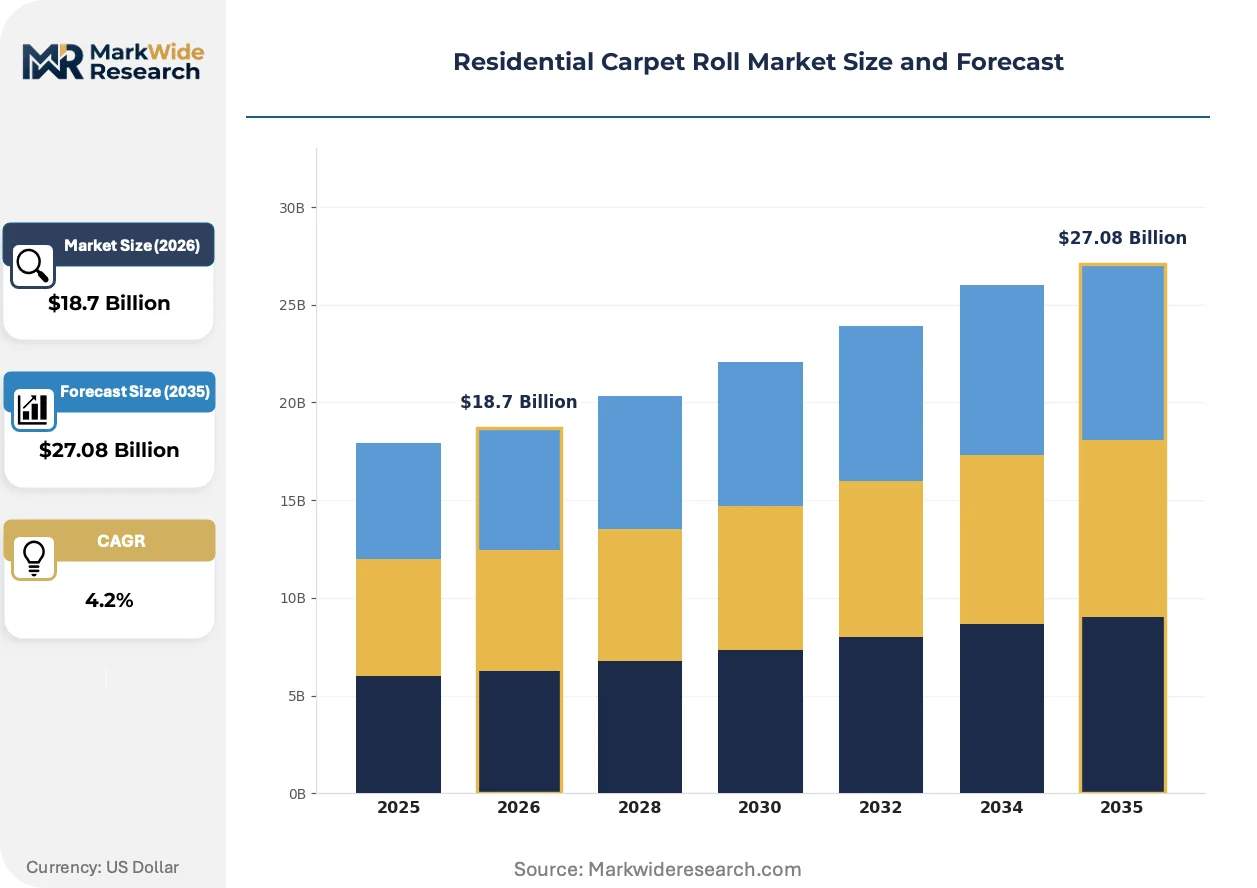
Market Dynamics
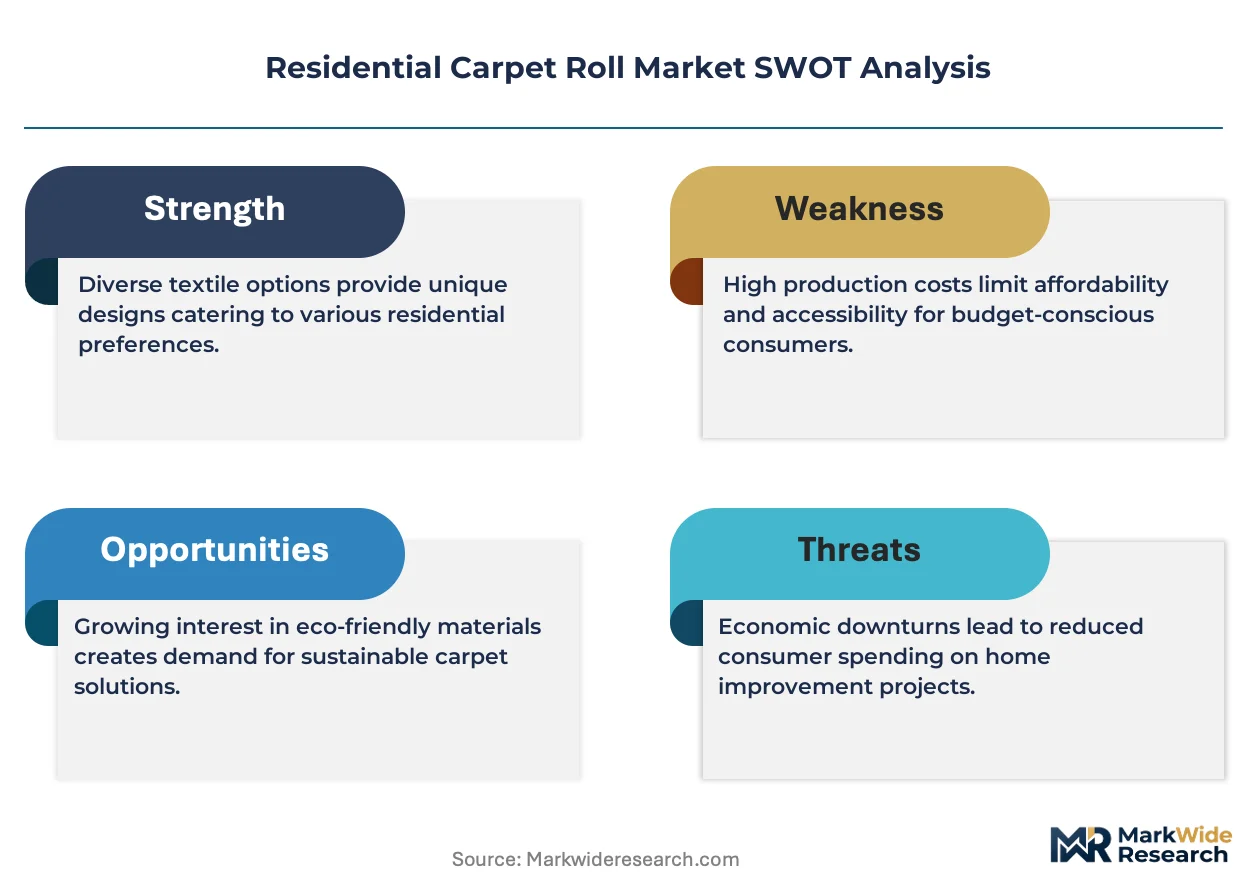
California's CARB Phase 2 VOC standards are compressing product approval timelines and forcing national distributors to reformulate adhesive portfolios or surrender shelf space to compliant competitors.
Growth Catalysts
- Sun Belt Housing Starts:Elevated residential construction across Florida, Texas, and Arizona is pulling 12-foot roll volumes through builder-direct channels. Multi-family developers specify CRI Green Label Plus certified products to satisfy property management procurement mandates.
- EPA Formaldehyde Rules:Extended emissions controls on composite wood underlayment substrates are accelerating substitution toward low-emission foam and rubber backing materials. Mills with pre-qualified supply chains capture specification lock-in.
- PET Recycling Infrastructure:Post-consumer bottle-to-fiber processing capacity is absorbing waste streams into residential carpet face yarns. Cost-conscious entry-level buyers respond to recycled-content price positioning without performance trade-offs.
Market Restraints
- Petroleum-Derived Input Volatility:Nylon 6,6 polymer and synthetic latex binder costs fluctuate with crude oil futures. Margin compression hits commodity polyester-olefin tiers where pricing power is weakest.
- Southeastern Supply Concentration:Tufting capacity clusters in Georgia and Alabama create hurricane and logistics disruption exposure. Single-region dependency limits geographic diversification for national distributors.
- Hard Surface Substitution:Luxury vinyl plank and engineered hardwood flooring is capturing renovation spend in moisture-prone applications. Carpet roll share compresses in kitchens, basements, and entryways.
Strategic Opportunities
- Arizona and Nevada Suburban Expansion:Master-planned communities outside Phoenix and Las Vegas specify builder-grade rolls at volume scales that justify dedicated mill capacity. First-mover distributors secure multi-year supply agreements.
- Low-VOC Adhesive Convergence:Water-based pressure-sensitive and hot-melt formulations are crossing over from commercial installation into residential retrofit. Certified applicators capture premium labor rates.
- Direct-to-Consumer Sample Programs:Digital color-matching and 18-inch square sample fulfillment is bypassing traditional retail showroom dependence. Online pure-plays build brand recognition before big-box shelf placement.
Industry Challenges
- Skilled Installer Shortage:Carpet and Rug Institute certification programs face enrollment gaps in stretching, seaming, and pattern-matching competencies. Labor bottlenecks extend project timelines and elevate callback rates.
- Multi-State Chemical Disclosure Burden:Washington State's Safer Products program and New York's emerging PFAS restrictions impose conflicting formulation requirements. Compliance teams must track divergent substance lists without unified federal preemption.
- Legacy ERP Integration:Mill scheduling systems struggle to synchronize recycled-content fiber traceability with lot-control requirements. Data architecture gaps delay sustainability marketing claims.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Carpet Roll Market Trends and Innovations
Triexta fiber chemistry and digital color customization are compressing traditional nylon-polyester segmentation while pulling specification power toward performance-certified tiers.
Triexta (polytrimethylene terephthalate) fiber technology is absorbing stain-resistance demand from households with pets and young children. Mohawk Industries' SmartStrand line anchors this shift, with specified uptake accelerating in suburban new-build channels. The chemistry is absorbing volume from solution-dyed nylon in the 30-45 ounce face weight segment where durability and cleanability trade-offs matter most.
California Air Resources Board (CARB) Phase 2 standards for installation adhesives are forcing national distributors to maintain dual inventory streams or abandon the state. The regulation compresses product approval timelines from 18 months to 9 months for reformulated low-VOC alternatives. Multi-family property managers in Texas and Florida are preemptively adopting CARB-compliant specifications to simplify procurement standardization.
Builder-direct specification consolidation is displacing retail showroom influence in new residential construction. National homebuilders in the Sun Belt negotiate master purchasing agreements that lock fiber type, color palette, and installation terms across hundreds of annual starts. Distributors without dedicated builder sales teams are losing specification access to vertically integrated mill-direct operations.
Residential Carpet Roll Market Segmentation
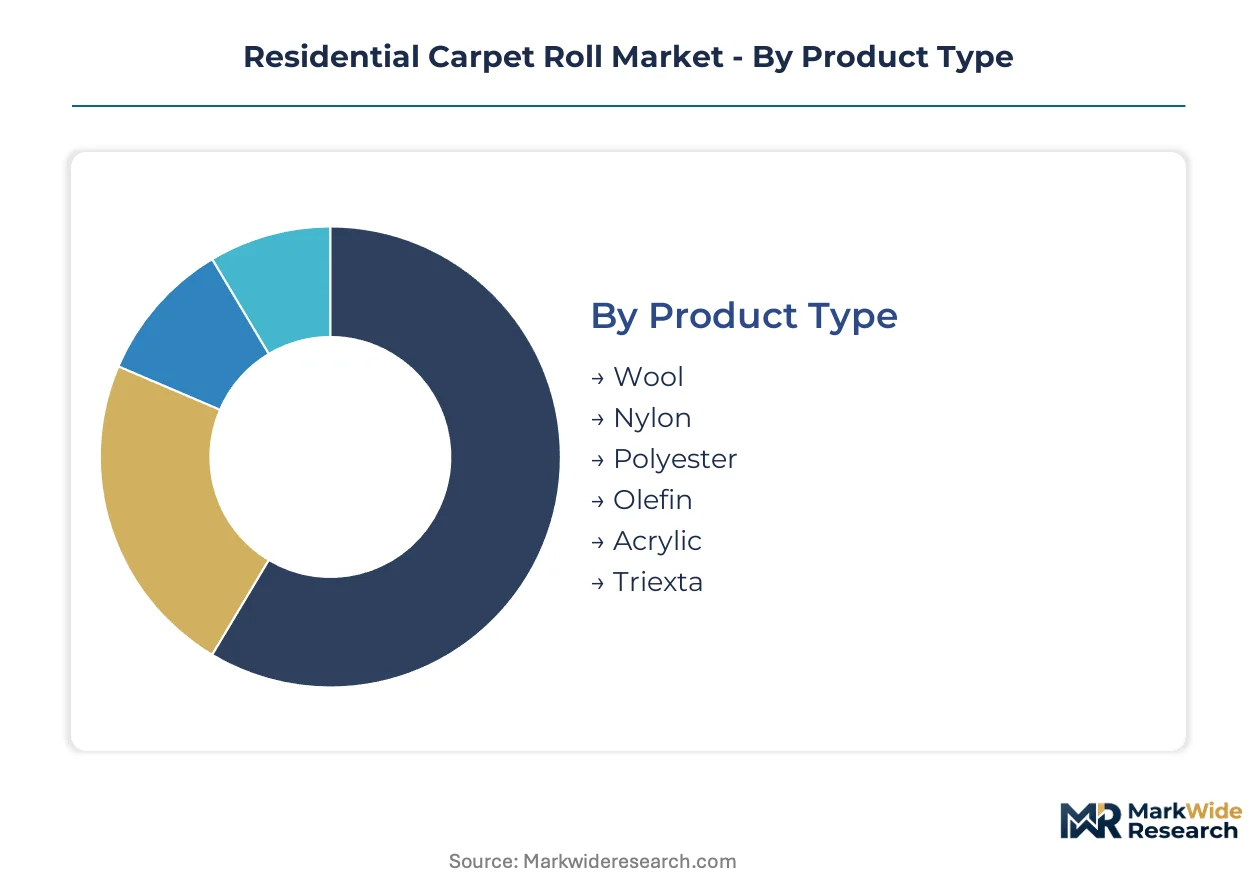
Residential carpet roll purchasing decisions track closely with replacement-cycle timing, room-specific wear patterns, and installation complexity. Segmentation reveals where specification power concentrates across fiber chemistry, room function, and buyer type.
Product Type:
Upgrade cycles vary dramatically by fiber chemistry, with durability expectations and stain-resistance claims driving re-purchase intervals.
- Nylon:Solution-dyed variants deliver the highest abrasion resistance and colorfastness under heavy foot traffic. Sun Belt builder-direct channels specify nylon for rental-grade properties where tenant turnover accelerates replacement schedules.
- Polyester:Recycled-content PET formulations now match commodity nylon on stain resistance at 15-20% lower installed cost. Entry-level suburban developments in Arizona and Nevada specify polyester rolls to hit price-per-square-foot targets without sacrificing CRI Green Label Plus compliance.
- Wool:Natural fiber retains concentrated specification in luxury custom homes where acoustic performance and tactile quality justify premium positioning.
- Olefin:Polypropylene chemistry resists moisture and chemical staining, limiting uptake to basement and utility room applications with lower aesthetic priority.
- Acrylic:Synthetic wool alternative occupies narrow niche in budget-conscious residential retrofits seeking natural-fiber appearance.
- Triexta:Mohawk's SmartStrand chemistry absorbs pet-owner demand through inherent stain resistance without topical treatments.
Volume placements concentrate in Polyester; the faster expansion belongs to Triexta.
Application:
Room function dictates pile weight, fiber selection, and moisture-management requirements across residential installations.
- Living Room:Formal entertaining spaces command 35-45 ounce face weights with pattern or texture options. Builder-direct specifications in Texas master-planned communities standardize neutral palettes to accelerate inventory turns.
- Bedroom:Comfort prioritization permits softer pile constructions and lighter traffic ratings. Florida retirement community developers specify bedroom-grade rolls at volume scales that justify dedicated mill production runs.
- Home Office:Chair caster traffic and equipment loads drive specification toward low-pile, high-density constructions with castor-chair ratings.
- Stairs:Safety codes and wear concentration require specialized narrow-width rolls with enhanced edge binding.
- Hallways:Linear traffic patterns favor loop constructions over cut pile for durability in connecting spaces.
- Playroom:Spill resistance and cleanability prioritize solution-dyed fibers with moisture barriers in backing systems.
Specification authority clusters in Living Room; Playroom is climbing the fastest as dedicated children's spaces proliferate in suburban floor plans.
Installation Method:
Cost tier and substrate condition determine method selection, with labor availability increasingly constraining option sets.
- Stretch-In:Conventional tackless strip installation dominates residential retrofit where subfloor condition permits. CRI-certified installer shortages in Georgia and Alabama extend project timelines for this labor-intensive method.
- Glue-Down:Direct adhesion to concrete slabs prevails in Florida and Arizona slab-on-grade construction where moisture barriers are mandatory.
- Peel & Stick:Pressure-sensitive adhesive backing targets DIY renovation segments with simplified tool requirements.
- Float:Interlocking or loose-lay systems accommodate uneven substrates without adhesive preparation.
- Tackless:Strip-and-pad method persists in upper-mid renovation segments seeking traditional carpet feel.
- Modular:Carpet tile formats enter residential through home office and basement applications seeking replaceable sections.
Method selection tracks regional construction practice; Glue-Down is gaining share fastest in Sun Belt slab markets.
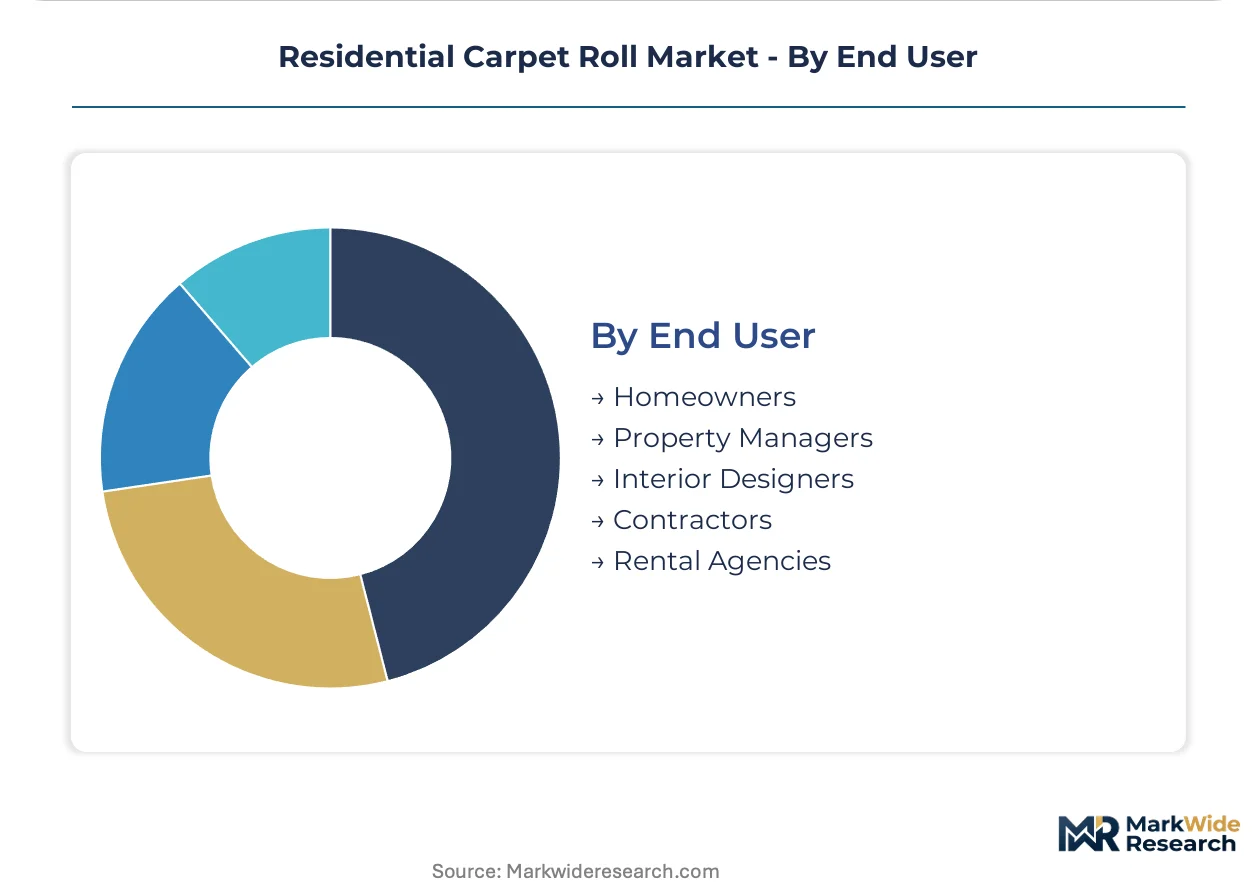
End User:
Customer type determines procurement channel, specification authority, and price sensitivity thresholds.
- Property Managers:Multi-family operators in Texas and Florida mandate CRI Green Label Plus certification and 10-year wear warranties through master purchasing agreements. Procurement centralization displaces retail influence in 100+ unit developments.
- Homeowners:Retail showroom and digital sample programs compete for renovation spend, with color-matching technology reducing purchase risk in online channels.
- Interior Designers:Custom residential projects specify wool-nylon blends through to-the-trade distribution with exclusive pattern access.
- Contractors:Builder-direct relationships with national homebuilders lock fiber type and color palette across annual start commitments.
- Rental Agencies:Turnover-driven replacement cycles prioritize commodity polyester with rapid availability and installer dispatch.
Procurement volume concentrates with Contractors; Property Managers are expanding most quickly as multi-family construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calhoun, Georgia anchors North American residential carpet roll manufacturing through concentrated tufting capacity and integrated fiber production corridors serving Sun Belt housing markets.
United States
Sun Belt suburban expansion across Florida, Texas, and Arizona pulls 12-foot roll volumes through builder-direct procurement channels. EPA formaldehyde emission rules on composite wood underlayment accelerate substitution toward low-emission foam backing systems. Georgia and Alabama tufting clusters face hurricane exposure risks that limit geographic diversification for national distributors.
Canada
Multi-family developers in Toronto and Vancouver specify CRI Green Label Plus certified products to satisfy property management procurement mandates. Health Canada maintains alignment with California CARB Phase 2 VOC standards for installation adhesives entering residential channels. Ontario-based distributors reformulate adhesive portfolios to maintain cross-border supply continuity.
Germany
REACH chemical registration requirements shape fiber chemistry decisions for residential rolls entering EU distribution networks. ECHA substance restrictions on PFAS and formaldehyde precursors compress product approval timelines for reformulated low-emission alternatives. Bavarian flooring manufacturers integrate recycled PET streams into entry-level residential offerings for cost-conscious export markets.
China
GB standards for indoor air quality and VOC emissions from building materials extend to carpet backing and adhesive systems in residential construction. MIIT industrial policy supports domestic fiber-to-finished-goods pipeline investments in Zhejiang and Jiangsu provinces. Yangtze River Delta manufacturers export polyester face yarns to Southeast Asian residential roll producers seeking cost-competitive inputs.
India
BIS certification requirements for textile floor coverings create compliance entry barriers for imported residential rolls. PLI scheme incentives support domestic tufting capacity expansion in Gujarat and Tamil Nadu serving middle-income housing segments. Mumbai and Delhi-NCR property developers specify builder-grade polyester rolls to hit price-per-square-foot targets in high-volume residential towers.
Residential Carpet Roll Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated fiber-to-finished-goods pipelines capture margin at scale while specialized recyclers and regional tufters occupy niche positioning. The vendor base separates into three archetypes: integrated majors with captive fiber supply, recycling-focused cost leaders, and specialty wool-nylon blend producers. Competitive moves concentrate on backward integration into polymer production and geographic expansion through dedicated mill capacity in Sun Belt growth corridors.
Among integrated North American manufacturers, Mohawk Industries, Shaw Industries Group, and Engineered Floors exemplify distinct strategic positioning archetypes. Mohawk represents the fully integrated model with captive fiber production sustaining margin capture across premium and commodity tiers. Shaw anchors scale-driven southeastern manufacturing concentration serving national builder-direct channels. Engineered Floors occupies the recycling-specialist position, converting post-consumer PET streams into cost-competitive residential offerings without performance trade-offs.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Interface |
| Engineered Floors |
| Beaulieu International Group |
| Milliken & Company |
| Tarkett |
| Inter IKEA Systems B.V. |
| Masland Carpets |
| Others |
Pricing and Supply Chain Analysis
Captive fiber-to-finished-goods integration anchors both supply security and margin capture across the residential carpet roll industry. Mohawk Industries' in-house polymer production and Shaw Industries' southeastern tufting concentration demonstrate how backward integration into nylon 6,6 and PET resin supply insulates pricing power from petroleum-derived input volatility.
Pricing Analysis
Value-based pricing tied to CRI Green Label Plus certification and wear-warranty outcomes separates premium nylon-triexta tiers from commodity polyester-olefin rolls. Certification grade and volume scale drive price differentiation, with multi-family property managers negotiating master purchasing agreements at 15-20% discounts to retail. Pricing pressure stems from recycled-content PET formulations compressing mid-tier margins without performance trade-offs. Entry-level suburban developers in Arizona and Nevada exhibit highest price sensitivity; luxury wool-nylon blend buyers demonstrate lowest.
Supply Chain Analysis
Freight cost exposure concentrates in Georgia-to-Sun Belt corridors where 12-foot roll dimensions limit intermodal flexibility and mandate dedicated flatbed capacity. Raw material supply draws from Texas and Louisiana petrochemical corridors for nylon polymer, Zhejiang province for recycled PET flake, and New Zealand for wool fiber. Single-source vulnerability runs through southeastern tufting clusters exposed to hurricane disruption. Distribution runs through builder-direct procurement channels, mill-direct regional distribution centers, and big-box retail intermediaries serving renovation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from California CARB Phase 2 compliance timelines is forcing smaller distributors to exit or sell, creating acquisition opportunities for scaled players with pre-qualified low-VOC adhesive portfolios.
For Market Incumbents: Extend specification lock-in through dedicated mill capacity in Phoenix and Las Vegas suburban corridors, securing multi-year builder-direct agreements before competitors qualify under compressed CARB timelines. Backward integration into PET recycling infrastructure insulates margin capture from petroleum volatility. Mohawk's SmartStrand chemistry and Shaw's southeastern scale demonstrate how fiber technology leadership and geographic manufacturing concentration defend position against hard surface substitution threats. For New Entrants and Emerging Players: DIY renovation homeowners represent an underserved buyer archetype bypassing traditional retail showroom dependence through digital color-matching and 18-inch sample fulfillment. Arizona and Nevada suburban expansion offers white-space entry through dedicated mill capacity serving master-planned communities at volume scales justifying production runs. Peel-and-stick pressure-sensitive adhesive formats provide go-to-market angle for installer-shortage markets seeking simplified tool requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated majors seeking PET recycling specialization or southeastern manufacturing footprint expansion. Five-to-ten year viability favors recyclers with post-consumer bottle-to-fiber processing capacity and distributors with CARB-compliant adhesive portfolios pre-qualified for national distribution. Watch for inflection when Washington State Safer Products program and New York PFAS restrictions trigger additional state-level chemical disclosure burdens forcing second-wave exits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Recycling | Post-consumer bottle-to-fiber capacity absorbs waste streams into cost-competitive residential face yarns. |
| Low-VOC Adhesive Portfolio Reformulation | Water-based and hot-melt formulations crossing from commercial into residential retrofit capture CARB compliance premiums. |
| Sun Belt Dedicated Mill Capacity | Phoenix and Las Vegas production runs serve master-planned community specifications at volume scale. |
| Direct-to-Consumer Sample Programs | Digital color-matching and 18-inch square fulfillment bypass retail showroom dependence for renovation spend. |
| CRI Green Label Plus Certification Investment | Certification functions as de facto market access filter for multi-family property management channels. |
Research Methodology
Multi-period observation of housing starts, fiber price indices, and regulatory approval timelines anchored the trend analysis, supplemented by interviews with mill operations directors, multi-family property procurement managers, CRI-certified installation contractors, and adhesive formulation chemists. Secondary validation drew from EPA formaldehyde emission filings, CARB Phase 2 product databases, customs trade records for PET flake imports, and SEC 10-K disclosures from publicly traded flooring manufacturers. Bottom-up volume modeling across fiber chemistry tiers triangulated against top-down housing construction forecasts.
Input-output matrices mapped nylon 6,6 polymer costs, recycled PET pricing spreads, and labor availability indices to residential roll production economics across the projection horizon. Segmentation dimensions included fiber chemistry, room application, installation method, and end-user procurement channel. CAGRs derived from regression against housing start correlations and replacement cycle timing. Industry-specific forecast inputs incorporated CRI certification adoption rates and state-level chemical disclosure law expansion trajectories.
Revisions become necessary when EPA formaldehyde rule extensions, additional state PFAS restrictions, or hurricane disruptions to southeastern manufacturing clusters materialize beyond modeled scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.