
 Saudi Arabia Floor Covering Market | 2026-2036
Saudi Arabia Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Floor Covering Market Analytics
Digital surface printing is reconfiguring how decorative layers bond to vinyl and laminate substrates, enabling shorter production runs with customized regional aesthetics. Tarkett Middle East LLC leverages its European R&D base to supply heterogeneous vinyl with enhanced wear layers for high-traffic commercial installations. Saudi Ceramic Company anchors domestic tile output through integrated frit and glaze operations at its Riyadh industrial complex. Mohawk Industries Inc. competes in the premium carpet segment through specialized solution-dyed nylon formulations engineered for Gulf climate conditions.
Floor covering encompasses finished materials installed over structural subfloors to provide walking surfaces, thermal insulation, acoustic dampening, and interior aesthetics; technical specifications span wear-layer thickness measured in mils, slip resistance coefficients, and fire-rating classifications under ASTM E648 or EN 13501-1 protocols. The product-type dimension shows vinyl gaining share in healthcare and education projects due to seam-welded hygiene performance, while carpet retains dominance in hospitality guest rooms where acoustic comfort and underfoot luxury drive specification. Material-grade polypropylene competes aggressively on price in residential rental stock, whereas hardwood commands premium positioning in high-end villa developments across Riyadh's Diplomatic Quarter and Jeddah waterfront districts.
The Saudi Building Code enforces fire-performance and slip-resistance standards that filter out uncertified imports at customs checkpoints, while SFDA oversight of volatile organic compound emissions shapes adhesive and coating formulations available for interior applications. Municipal permitting authorities in Riyadh, Jeddah, and Dammam now require third-party test reports for floor coverings in public buildings, tightening market access for suppliers lacking accredited laboratory partnerships. Stakeholders must monitor how the Saudi Green Building Forum's evolving criteria for indoor environmental quality will redirect specification priorities toward low-emitting materials and recycled-content products.
Market Dynamics
Diriyah Gate and Qiddiya entertainment city developments are compressing procurement timelines for hospitality-grade floor finishes, forcing specification decisions earlier in project cycles and privileging suppliers with Riyadh-based inventory positions.
Growth Catalysts
- Hospitality construction surge:Hotel developers across Riyadh and Jeddah are specifying premium vinyl and carpet for guest rooms and lobbies, accelerating volume commitments from domestic distributors.
- Saudi Building Code enforcement:Fire-resistance and slip-resistance mandates now require third-party test reports at municipal permitting checkpoints, filtering out uncertified imports and elevating compliant domestic producers.
- Digital surface printing:This technology enables shorter production runs with customized regional aesthetics, allowing manufacturers to respond faster to project-specific color and pattern requirements.
Market Restraints
- Petrochemical feedstock volatility:Vinyl resin and synthetic fiber costs fluctuate with crude oil derivatives, compressing margins for domestic manufacturers lacking long-term polymer supply contracts.
- SFDA emission protocols:Volatile organic compound limits on adhesives and coatings restrict formulation options, forcing reformulation investments that smaller importers cannot absorb.
- Hardwood substitution ceiling:Natural timber faces moisture degradation in Gulf climate conditions, limiting penetration in high-humidity applications despite premium positioning in villa developments.
Strategic Opportunities
- Eastern Province healthcare expansion:Dammam medical complexes present untapped demand for seam-welded vinyl flooring with infection-control properties, a specification priority absent from current supplier coverage.
- Saudi Green Building Forum criteria:Evolving indoor environmental quality standards will redirect public project specifications toward low-emitting materials and recycled-content products.
- Direct-to-developer digital platforms:Online specification tools are bypassing traditional distributor networks, enabling manufacturers to capture margin previously allocated to wholesale intermediaries.
Industry Challenges
- Accredited laboratory partnerships:Municipal permitting authorities now reject test reports from non-recognized facilities, forcing suppliers to secure SFDA-accepted certification relationships or exit public building segments.
- Installation skill scarcity:Seam-welding and subfloor preparation for high-performance vinyl requires trained technicians, and vocational programs have not scaled to match project velocity in the Central Region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Floor Covering Market |
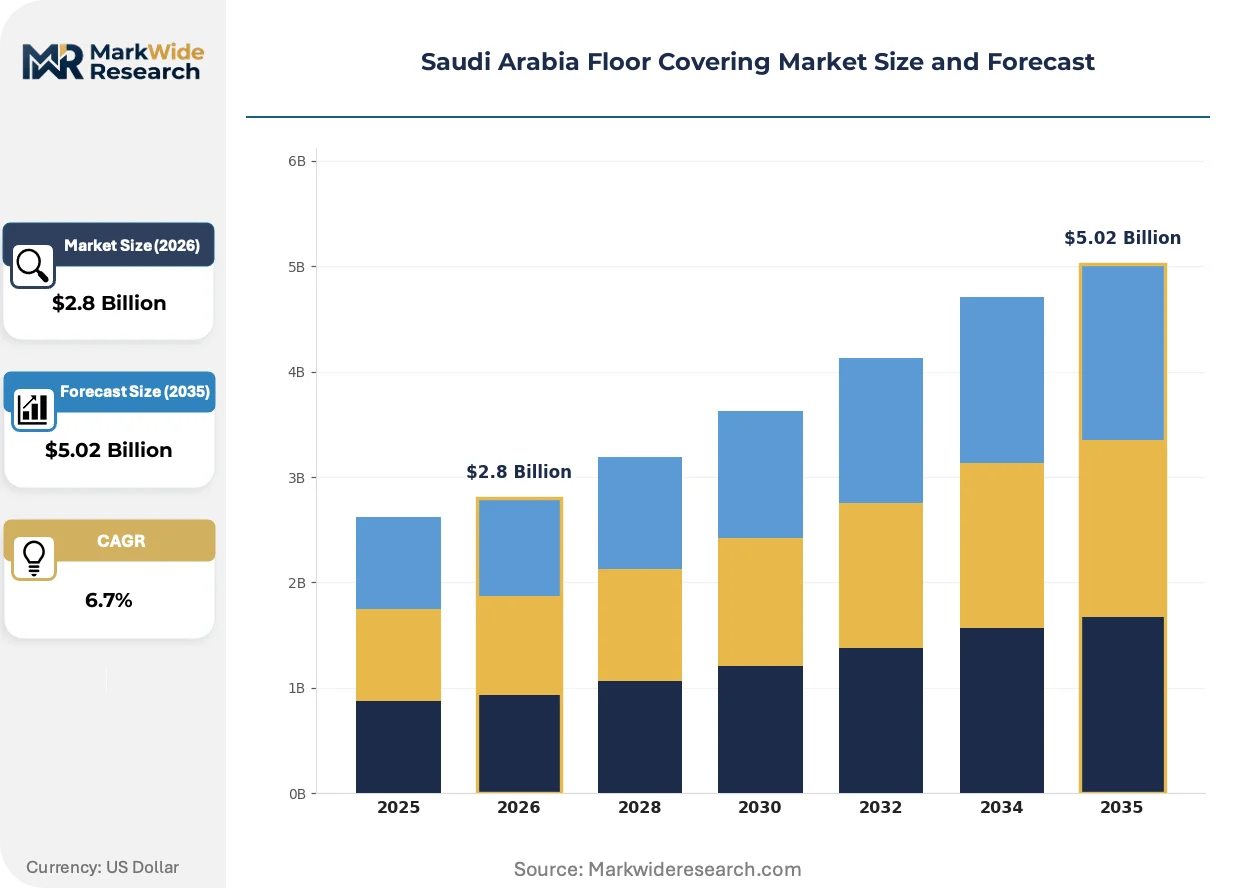
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Vinyl, Wood, Laminate End User: Residential, Commercial, Hospitality, Industrial Material: Nylon, Polypropylene, Hardwood, Bamboo Installation Type: Direct Glue, Floating, Staple Down, Stretch-In |
| Companies Covered | Tarkett Middle East LLC, RAK Ceramics PJSC, Saudi Ceramic Company, Arabian Tile Company Ltd, Prime Floor KSA, Al Sorayai Group, Mohawk Industries Inc., Saudi Industrial Flooring Co., Al Abdullatif Industrial Investment Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Floor Covering Market Evolving Landscape
Surface engineering and compliance automation are compressing product development cycles while elevating performance thresholds for commercial installations across Saudi Arabia's megaproject pipeline.
Digital inkjet printing on ceramic and porcelain tiles is virtualizing how decorative layers bond to substrates, enabling batch sizes as small as fifty square meters with customized geometric patterns. Hospitality developers in Jeddah's waterfront district are specifying these short-run capabilities for boutique hotel lobbies. This technology is virtualizing the traditional economies of scale that favored mass-produced imports, allowing domestic tile producers to compete on personalization rather than volume.
SFDA oversight of volatile organic compound emissions is tightening adhesive and coating formulations available for interior applications. Manufacturers must now submit comprehensive emission test data before customs clearance, adding documentation burden but creating competitive separation for prepared suppliers. Healthcare and education segments are most affected, with project specifications increasingly preemptively excluding non-compliant product categories.
Developer procurement teams are consolidating vendor relationships around full-service flooring contractors who assume subfloor preparation, installation, and maintenance liability. This bundling displaces the traditional model of separate material purchase and labor contracting. The shift is most visible in Riyadh's commercial tower segment, where single-source accountability reduces project management overhead for general contractors managing multiple trades.
Saudi Arabia Floor Covering Market Segmentation
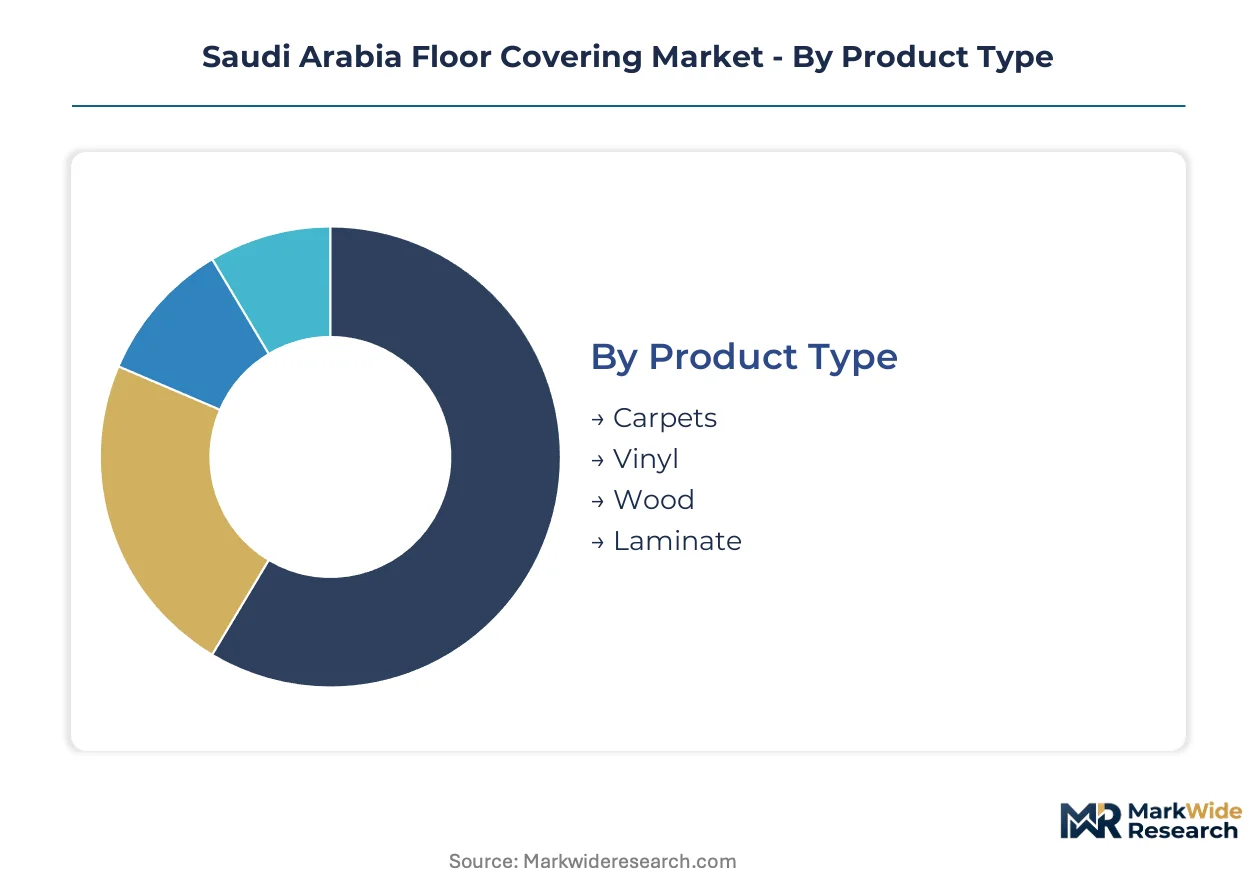
Floor covering procurement in Saudi Arabia fragments across performance specifications, installation methods, and climate resilience requirements. Specification committees at Riyadh megaprojects weight fire ratings, wear-layer durability, and SFDA emission compliance differently across building types.
Product Type:
Mature segments dominate volume, while emerging substrates gain specification in specialized applications.
- Carpets:Solution-dyed nylon and polypropylene broadloom constructions deliver acoustic dampening and underfoot thermal comfort. Hospitality developers across Jeddah waterfront districts specify premium cut-pile and loop-pile constructions for guest room luxury positioning, though SFDA VOC protocols constrain adhesive selection for direct-glue installations.
- Vinyl:Heterogeneous and homogeneous sheet products with seam-welded joints provide infection-control performance for healthcare and education segments. Riyadh's Central Region hospital expansions are compressing procurement timelines for suppliers with compliant inventory positions near Diriyah Gate construction zones.
- Wood:Engineered hardwood planks with aluminum oxide wear layers compete in high-end villa developments despite moisture degradation risks in Gulf humidity conditions.
- Laminate:High-density fiberboard cores with melamine-impregnated decorative papers offer cost-competitive alternatives for residential rental stock in Dammam's Eastern Province housing clusters.
Carpets handle the majority of throughput in hospitality and residential segments; vinyl is expanding most quickly in healthcare and education specifications.
End User:
Customer procurement authority concentrates in project-scale decisions rather than fragmented retail purchasing.
- Residential:Villa owners in Riyadh's Diplomatic Quarter and Jeddah waterfront districts specify imported hardwood and premium carpet for aesthetic differentiation. SFDA emission testing requirements for adhesives and underlayments filter out uncertified product lines at customs clearance.
- Commercial:Office tower developers in Riyadh consolidate vendor relationships around full-service flooring contractors assuming installation and maintenance liability. This bundling displaces traditional separate material purchase and labor contracting models.
- Hospitality:Hotel procurement teams specify premium finishes earlier in project cycles due to compressed construction timelines at Qiddiya entertainment city developments.
- Industrial:Warehouse and logistics facilities prioritize slip-resistance coefficients and point-load durability over aesthetic considerations, with municipal permitting requiring third-party test reports.
Commercial applications anchor current volume commitments; hospitality specifications are climbing the fastest as megaproject pipelines accelerate.
Material:
Feedstock cost structures and climate performance shape specification viability across substrate categories.
- Nylon:Solution-dyed formulations engineered for Gulf ultraviolet exposure and sand abrasion dominate premium carpet segments. Mohawk Industries supplies specialized BCF nylon to hospitality developers requiring bleach-cleanable performance in high-traffic lobbies.
- Polypropylene:Olefin fiber competes aggressively on price for residential rental stock and budget hospitality installations, though crush resistance limitations constrain specification in heavy commercial applications.
- Hardwood:Natural timber faces moisture absorption challenges in high-humidity coastal zones, limiting penetration despite premium positioning in luxury villa developments.
- Bamboo:Rapid-renewable grass-based flooring gains specification interest from Saudi Green Building Forum criteria, though supply chain maturity lags established timber alternatives.
Nylon handles the majority of synthetic fiber volume; bamboo is gaining specification fastest among sustainability-oriented developers.
Installation Type:
Subfloor conditions and performance requirements dictate method selection across building typologies.
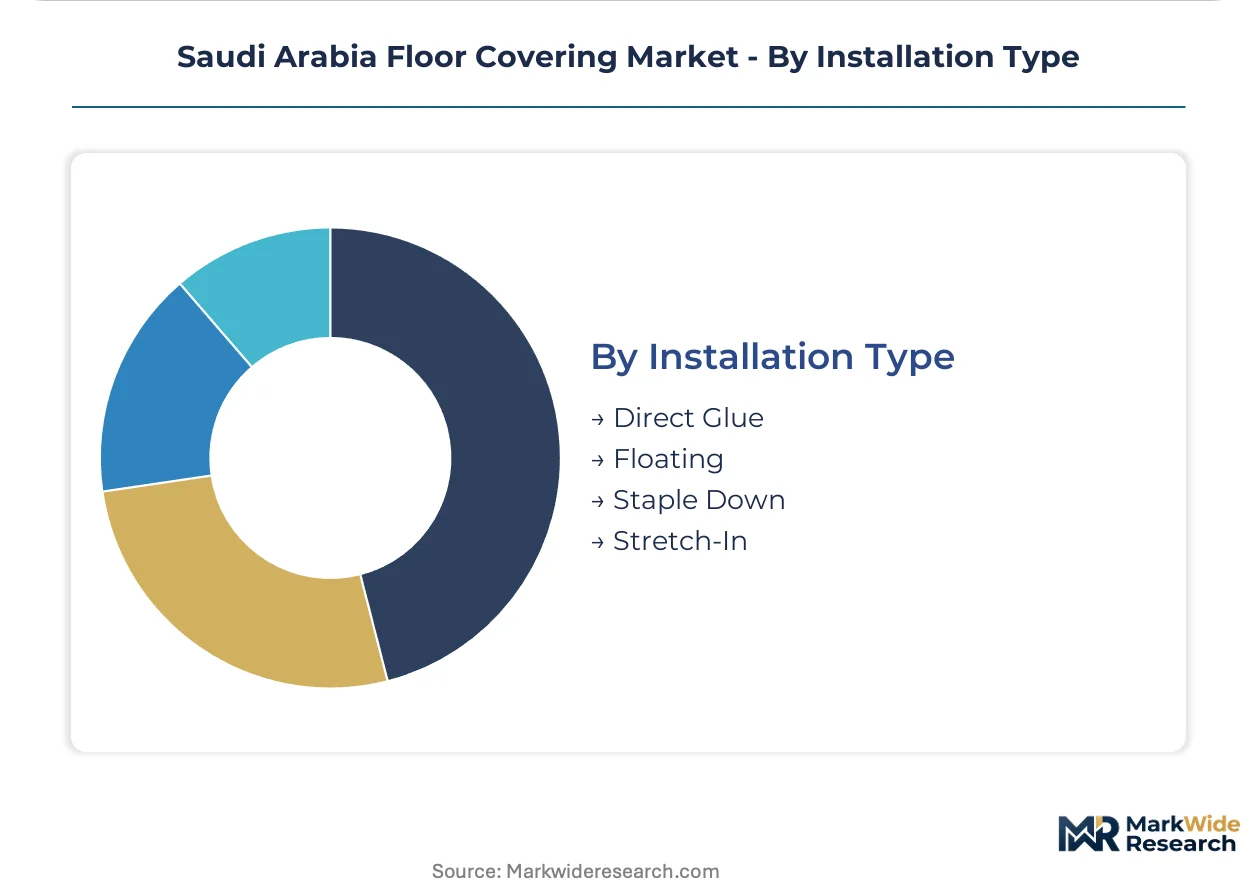
- Direct Glue:Full-spread adhesive application provides dimensional stability for sheet vinyl and carpet tile in high-traffic commercial environments. SFDA oversight of volatile organic compound emissions in adhesive formulations restricts product availability for interior applications.
- Floating:Click-lock and loose-lay systems enable faster installation cycles for laminate and engineered wood in residential developments where moisture barriers address slab conditions.
- Staple Down:Traditional carpet installation over wood subfloors persists in villa renovations and low-rise residential construction.
- Stretch-In:Tackless strip installation for broadloom carpet allows future replacement flexibility in hospitality guest rooms where refresh cycles accelerate.
Direct glue methods handle the majority of commercial and healthcare throughput; floating installations are expanding fastest in residential volume housing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates in Riyadh-based megaproject developers, Eastern Province healthcare operators, and Western Region hospitality investors. These buyer archetypes drive specification patterns across Saudi Arabia's floor covering demand centers.
Riyadh
Diriyah Gate and Qiddiya entertainment city developments compress procurement timelines for premium finishes. The Saudi Building Code enforces fire-resistance and slip-resistance standards at municipal permitting checkpoints. Riyadh's Central Region industrial complex anchors domestic tile output through integrated frit and glaze operations.
Eastern Province
Dammam medical complexes generate untapped demand for seam-welded vinyl with infection-control properties. SFDA oversight of volatile organic compound emissions shapes adhesive formulations available for interior applications. The region's healthcare expansion pipeline outpaces current supplier coverage for specialized flooring specifications.
Western Region
Jeddah waterfront hotel projects specify premium carpet and vinyl for guest room luxury positioning. Municipal permitting authorities require third-party test reports for floor coverings in public buildings. Jeddah's hospitality construction surge privileges suppliers with compliant inventory positions near active development zones.
NEOM Northwest
The giga-project zone experiments with sustainable material specifications aligned to Saudi Green Building Forum criteria. SFDA material safety protocols filter uncertified imports at customs entry points. NEOM's procurement teams consolidate vendor relationships around full-service contractors assuming installation liability.
Asir and Southern Regions
Residential villa developments in cooler highland zones specify engineered hardwood despite Gulf humidity constraints. The Saudi Building Code's indoor air quality standards constrain adhesive selection for direct-glue installations. Local distributors maintain limited inventory depth compared to Central and Western Region hubs.
Saudi Arabia Floor Covering Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Saudi Arabia's floor covering procurement networks. Consolidated domestic ceramic producers anchor volume supply, while European and North American specialists capture premium hospitality and healthcare specifications. Three archetypes dominate: integrated tile manufacturers with captive raw material supply, full-service flooring contractors bundling installation and maintenance liability, and import-dependent distributors serving residential renovation segments. Competitive moves center on securing SFDA-accepted laboratory partnerships for compliance documentation and compressing delivery timelines through Riyadh-based inventory positioning.
Among integrated domestic producers, Saudi Ceramic Company exemplifies the captive-supply archetype through its Riyadh industrial complex operations. Tarkett Middle East LLC occupies a position representing European R&D-backed supply for high-traffic commercial installations. Mohawk Industries Inc. anchors the premium carpet segment through specialized fiber formulations. These three companies represent distinct competitive vectors: domestic vertical integration, foreign technology transfer, and climate-adapted product engineering.
| Leading Market Players |
|---|
| Tarkett Middle East LLC |
| RAK Ceramics PJSC |
| Saudi Ceramic Company |
| Arabian Tile Company Ltd |
| Prime Floor KSA |
| Al Sorayai Group |
| Mohawk Industries Inc. |
| Saudi Industrial Flooring Co. |
| Al Abdullatif Industrial Investment Co. |
| Others |
Value Network & Pricing Analysis
Jeddah Islamic Port container corridors transmit petrochemical feedstock volatility directly into domestic vinyl resin pricing, concentrating margin pressure on manufacturers lacking long-term polymer supply contracts while enabling Riyadh-based distributors to command geographic premiums for compliant inventory positions near Diriyah Gate construction zones.
Pricing Analysis
Cost-plus contracts with Brent crude indexation dominate vinyl resin procurement, forcing domestic manufacturers to absorb margin compression when oil derivatives spike. Price differentiation hinges on SFDA emission certification tier and wear-layer durability grade, with compliant premium products commanding substantial premiums over uncertified imports. Pricing pressure stems from petrochemical feedstock volatility, particularly for polypropylene fiber competing in residential rental stock. Budget hospitality developers exhibit highest price sensitivity, whereas Riyadh megaproject procurement teams prioritize compliance and delivery reliability over unit cost.
Supply Chain Analysis
Export-control regimes on European digital printing technology limit surface engineering equipment flows to domestic tile producers, constraining short-run customization capabilities. Manufacturing concentrates in Saudi Arabia, China, and Italy for ceramic and porcelain tiles; Germany and Belgium for heterogeneous vinyl; and the United States for solution-dyed nylon carpet fiber. Raw material dependencies include vinyl resin from petrochemical crackers, frit and glaze compounds from integrated ceramic operations, and synthetic fiber from polymer extrusion facilities. Single-source vulnerability pervades European R&D-backed equipment supply. Distribution runs through Riyadh-based full-service flooring contractors bundling installation and maintenance liability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia floor covering market is recovering from cyclical lows as hospitality construction surges accelerate procurement velocity across Riyadh and Jeddah megaproject pipelines.
For Market Incumbents: Build regulatory compliance moats by securing SFDA-accepted laboratory partnerships before municipal permitting authorities reject non-recognized test reports. Deepen backward integration into frit and glaze operations to insulate margins from ceramic raw material volatility. Expand Riyadh inventory positions to capture compressed procurement timelines at Qiddiya entertainment city developments.
For New Entrants and Emerging Players: Eastern Province healthcare facilities in Dammam represent the most penetrable entry point, with seam-welded vinyl specifications outpacing current supplier coverage for infection-control flooring. Direct-to-developer digital platforms bypass traditional distributor networks and capture margin previously allocated to wholesale intermediaries. Target full-service contracting capabilities rather than material-only supply to align with procurement team consolidation trends.
For Investors and Strategic Acquirers: Domestic ceramic producers with captive raw material supply and integrated frit operations present durable acquisition targets given regulatory barriers to import substitution. Long-term viability centers on compliance infrastructure rather than volume scale. Monitor Saudi Green Building Forum indoor environmental quality criteria evolution as the critical signal for specification redirection toward low-emitting materials.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Laboratory Partnership | Secures market access as municipal permitting rejects non-accredited test reports. |
| Riyadh Inventory Positioning | Captures compressed procurement timelines at Diriyah Gate and Qiddiya developments. |
| Backward Integration into Frit Supply | Insulates ceramic producers from raw material cost volatility at integrated operations. |
| Direct-to-Developer Platform Launch | Bypasses distributor networks to capture margin previously allocated to wholesale intermediaries. |
| Full-Service Contracting Capability | Aligns with procurement team consolidation around single-source installation and maintenance liability. |
Research Methodology
A standing panel of hospitality procurement directors, healthcare facilities managers, ceramic plant operations heads, and municipal permitting officials provided ongoing calibration across the study period. Primary interviews with flooring contractors, distributor inventory planners, and SFDA compliance officers combined with secondary validation from Saudi Building Code documentation, customs import records, and Saudi Green Building Forum technical criteria. Bottom-up project pipeline enumeration and top-down construction spend allocation triangulated market sizing across product and end-use segments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with low-case assumptions incorporating petrochemical feedstock price spikes and high-case assumptions reflecting accelerated megaproject commissioning. Segmentation dimensions modeled encompassed product type, end-use application, material substrate, installation method, and regional procurement cluster. CAGRs derived from weighted average of project-based demand curves and replacement cycle analysis, with specific inputs including hospital expansion timelines and hospitality room-night supply forecasts.
Practitioners should monitor SFDA emission protocol amendments and Saudi Building Code fire-rating revisions for early signals of specification redirection. Forecasts reflect assumptions regarding megaproject completion schedules and petrochemical price stability. Material shifts in crude oil derivative pricing or customs enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market