
 Carpet Market | 2026-2036
Carpet Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Market Intelligence
ISO 14001 environmental management certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Mohawk Industries leverages captive nylon polymerization to sustain margin control across North American distribution. Interface specializes in closed-loop recycling systems that differentiate its offering within corporate sustainability procurement channels. Shaw Industries Group dominates residential broadloom through integrated fiber-to-finished-goods manufacturing scale.
Carpets are textile floor coverings constructed from tufted or woven pile yarns attached to primary and secondary backing layers, with pile weights typically ranging from 16 to 60 ounces per square yard depending on performance grade. Their primary commercial purpose is to provide thermal insulation, acoustic dampening, and wear-resistant surfacing in interior environments. Nylon segments command the highest durability premiums in commercial hospitality applications where traffic density exceeds residential thresholds by an order of magnitude. Carpet tiles are capturing installation-method share in institutional retrofit projects where downtime minimization overrides first-cost considerations across healthcare and education facilities.
The EPA's persistent organic pollutant restrictions and California's Proposition 65 disclosure mandates are tightening chemical content thresholds for stain-resistant treatments and adhesive systems. REACH compliance in European markets is forcing reformulation of per- and polyfluoroalkyl substance chemistries historically embedded in performance-grade products. Stakeholders must monitor evolving state-level extended producer responsibility legislation that threatens to shift end-of-life collection costs upstream to manufacturers without established reclamation infrastructure.
Market Dynamics
The EU Green Deal's material traceability mandates are forcing fiber sourcing restructuring across the value chain, bifurcating supplier qualification tiers and redirecting procurement flows toward certified origins.
Growth Catalysts
- REACH chemical reformulation deadlines:European ECHA enforcement is accelerating substitution of legacy stain-resistant chemistries, creating first-mover advantage for compliant producers.
- Hospitality sector procurement expansion:Luxury hotel chains in Dubai, Singapore, and the Maldives are specifying high-durability nylon for high-traffic common areas.
- India commercial real estate concentration:Mumbai and Bangalore corridor development is generating sustained institutional demand for carpet tile installations.
Market Restraints
- Caprolactam feedstock volatility:Nylon 6 polymer input costs fluctuate with benzene derivative pricing, compressing margin predictability for non-integrated manufacturers.
- China synthetic fiber oversupply:Concentrated polyester and polypropylene capacity in Zhejiang and Jiangsu provinces exerts persistent price pressure on commodity segments.
- California Proposition 65 disclosure friction:Adhesive and backing layer chemical notification requirements add compliance overhead to US distribution.
Strategic Opportunities
- Saudi hospitality construction pipeline:Giga-project developments around NEOM and Red Sea tourism zones represent underpenetrated demand for premium broadloom.
- Extended producer responsibility tailwinds:Emerging state-level EPR legislation in New York and California creates reclamation infrastructure investment incentives.
- Digital twin specification tools:Convergence of BIM software with material databases enables pre-construction visualization, shortening sales cycles for contract dealers.
Industry Challenges
- ISO 14001 auditor capacity constraints:Certification backlog delays supplier qualification timelines for European retail procurement channels.
- Legacy dyehouse wastewater retrofit requirements:Capital intensity of closed-loop water systems strains mid-tier manufacturers without parent-company balance sheet support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Market |
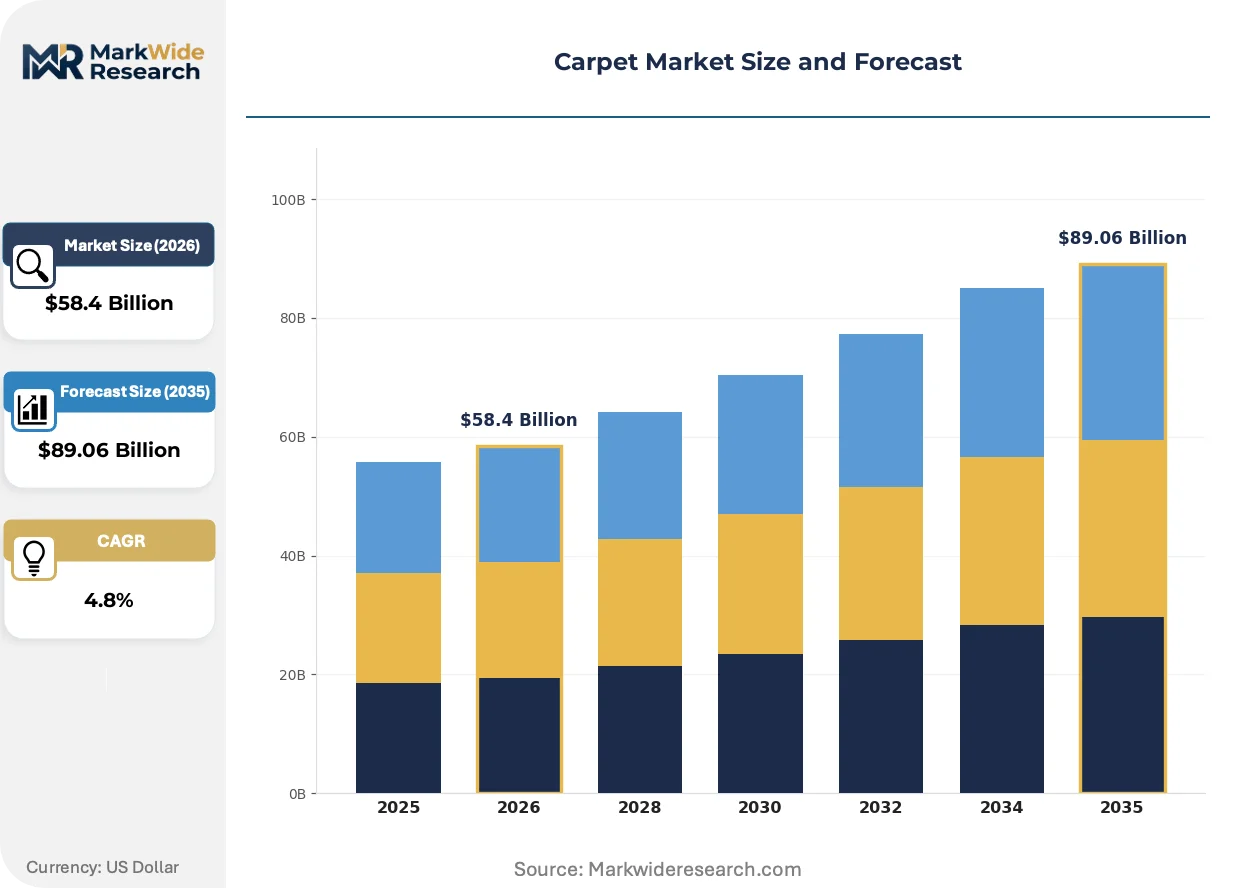
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $89.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wool, Nylon, Polyester, Olefin End User: Residential, Commercial, Hospitality, Institutional Style: Berber, Saxony, Frieze, Shag Installation Method: Glue Down, Stretch In, Loose Lay, Carpet Tiles |
| Companies Covered | Tarkett, Milliken & Company, Mohawk Industries, Victoria PLC, Tai Ping Carpets International Limited, Shaw Industries Group, Oriental Weavers, Interface, Beaulieu International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Market Strategic Shifts & Innovations
Material chemistry and installation methodology are undergoing parallel transformation, with regulatory pressure and operational efficiency demands compressing traditional product lifecycles and sourcing patterns.
Recycled content nylon is decomposing the virgin polymer premium structure in commercial specification channels. Corporate sustainability procurement teams at technology headquarters and financial services firms are mandating post-consumer recycled fiber minimums. This shift is compressing price differentiation between closed-loop and conventional supply chains.
EPA persistent organic pollutant restrictions are tightening discharge thresholds for per- and polyfluoroalkyl substance treatments used in stain-resistant finishes. Manufacturing facilities in Georgia and South Carolina are retrofitting coating lines to meet quarterly reporting requirements. Hospitality and healthcare segments are accelerating qualification of fluorine-free alternatives to maintain project eligibility.
Specification workflows are migrating toward platform-based material libraries that integrate environmental product declarations directly into design software. Architecture and interior design firms are bypassing traditional dealer showrooms for digital sampling and virtual rendering. This channel compression is most visible in North American commercial retrofit projects where speed-to-decision overrides tactile evaluation.
Carpet Market Segmentation
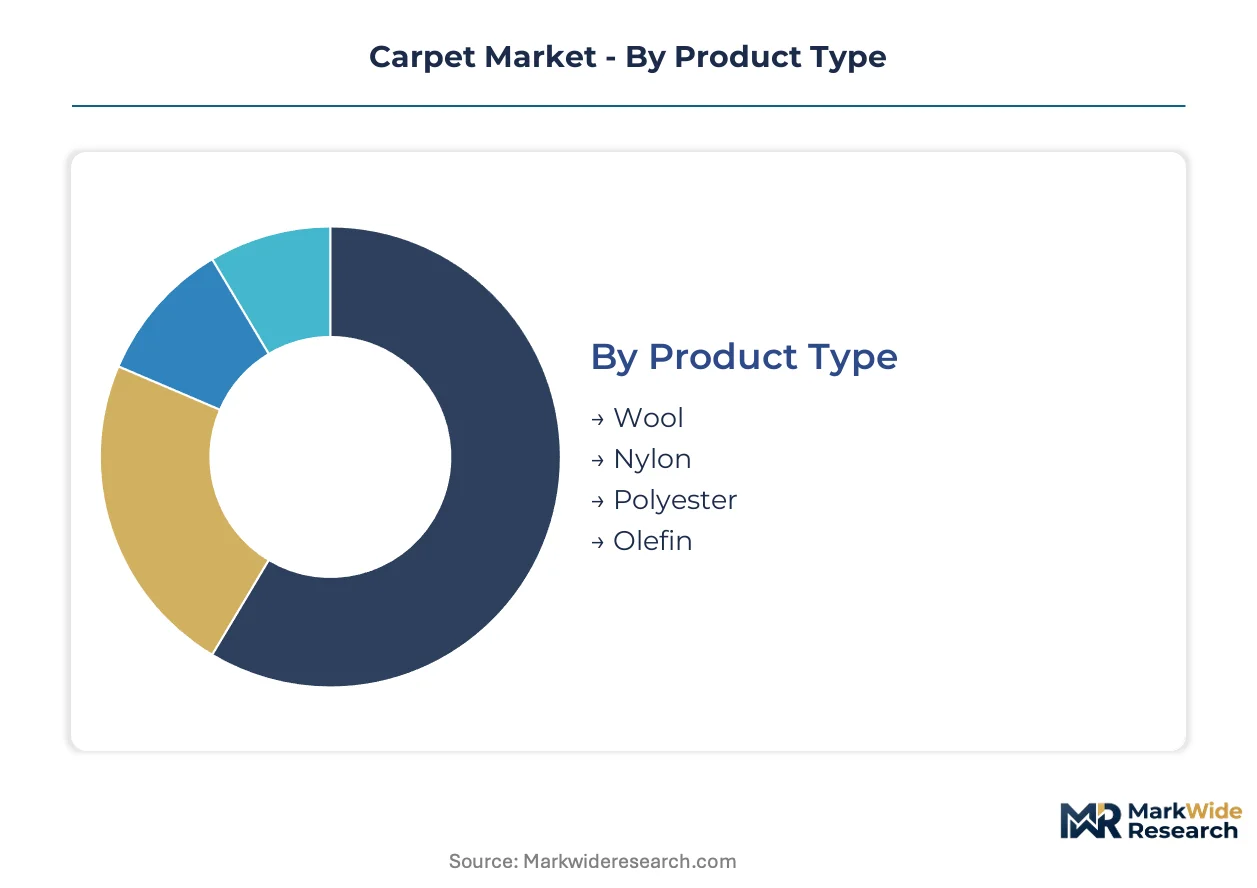
Carpet segmentation reveals how fiber chemistry, end-use performance requirements, and installation logistics partition margin pools across distinct supply chains. Understanding these divisions exposes where specification power concentrates and where commoditization pressure is most acute.
Product Type:
Nylon and wool command the highest margin premiums due to durability performance and natural fiber scarcity respectively, while polyester and olefin compete on first-cost positioning in volume residential channels.
- Nylon:Synthetic polymer formed through caprolactam ring-opening polymerization, delivering superior resilience and stain resistance under heavy traffic loads. Demand concentrates in luxury hotel lobbies and corporate headquarters where replacement cycles must exceed ten years; REACH chemical reformulation deadlines are accelerating qualification of bio-based feedstock variants.
- Wool:Natural protein fiber harvested from sheep fleece, prized for inherent flame resistance and acoustic absorption without chemical additives. Procurement from New Zealand and British farms is tightening under EU Green Deal traceability mandates, compressing supply elasticity for premium residential and boutique hospitality projects.
- Polyester:Petroleum-derived fiber offering colorfastness and recycled content potential at lower price points than nylon. PET bottle feedstock integration is expanding among Chinese and Indian producers.
- Olefin:Polypropylene-based fiber resisting moisture and chemical degradation, dominant in outdoor and basement applications where mildew resistance overrides softness requirements.
Nylon holds installed capacity across North American and European polymerization assets. Polyester is rotating up the share rankings through recycled content cost advantages.
End User:
Volume concentration diverges sharply between replacement-driven residential maintenance and project-based commercial specification where architect relationships determine vendor selection.
- Commercial:Office buildings, retail centers, and healthcare facilities specifying carpet tile for modular replacement and subfloor access. Mumbai and Bangalore corridor development is generating sustained institutional demand for high-cycle durability products.
- Hospitality:Luxury hotel chains, cruise vessels, and resort casinos requiring fire-rated broadloom with pattern continuity across large surface areas. Dubai and Singapore procurement teams are mandating ISO 14001 certification as a baseline qualification.
- Residential:Single-family and multi-family housing driven by renovation cycles and new construction absorption. Builder-grade specifications prioritize installed cost over lifecycle performance.
- Institutional:Education facilities, government buildings, and transportation hubs where public procurement regulations favor domestic content and recycled material minimums.
Commercial holds installed capacity across contract dealer networks. Hospitality is rotating up the share rankings through giga-project pipelines in Saudi Arabia and the Maldives.
Style:
Construction geometry determines tufting machinery configuration and dye application methods, creating production line lock-in that segments manufacturing specialization.
- Berber:Level loop pile with flecked coloration hiding soil in high-traffic zones. Dominates commercial and institutional specification in the US Southeast and Midwest where maintenance budgets constrain cleaning frequency.
- Saxony:Dense, cut-pile surface with uniform directionality delivering formal aesthetics. Residential master bedroom and hospitality suite applications prioritize tactile luxury over durability metrics.
- Frieze:Tightly twisted cut pile with curled surface texture resisting footprint marking and vacuum trails. Gaining specification in active residential households with pets and children.
- Shag:Long, loose pile exceeding one inch in height, revived through retro design trends in boutique hospitality and residential statement installations.
Berber holds installed capacity across commercial-focused tufting assets. Frieze is rotating up the share rankings through performance-positioned residential marketing.
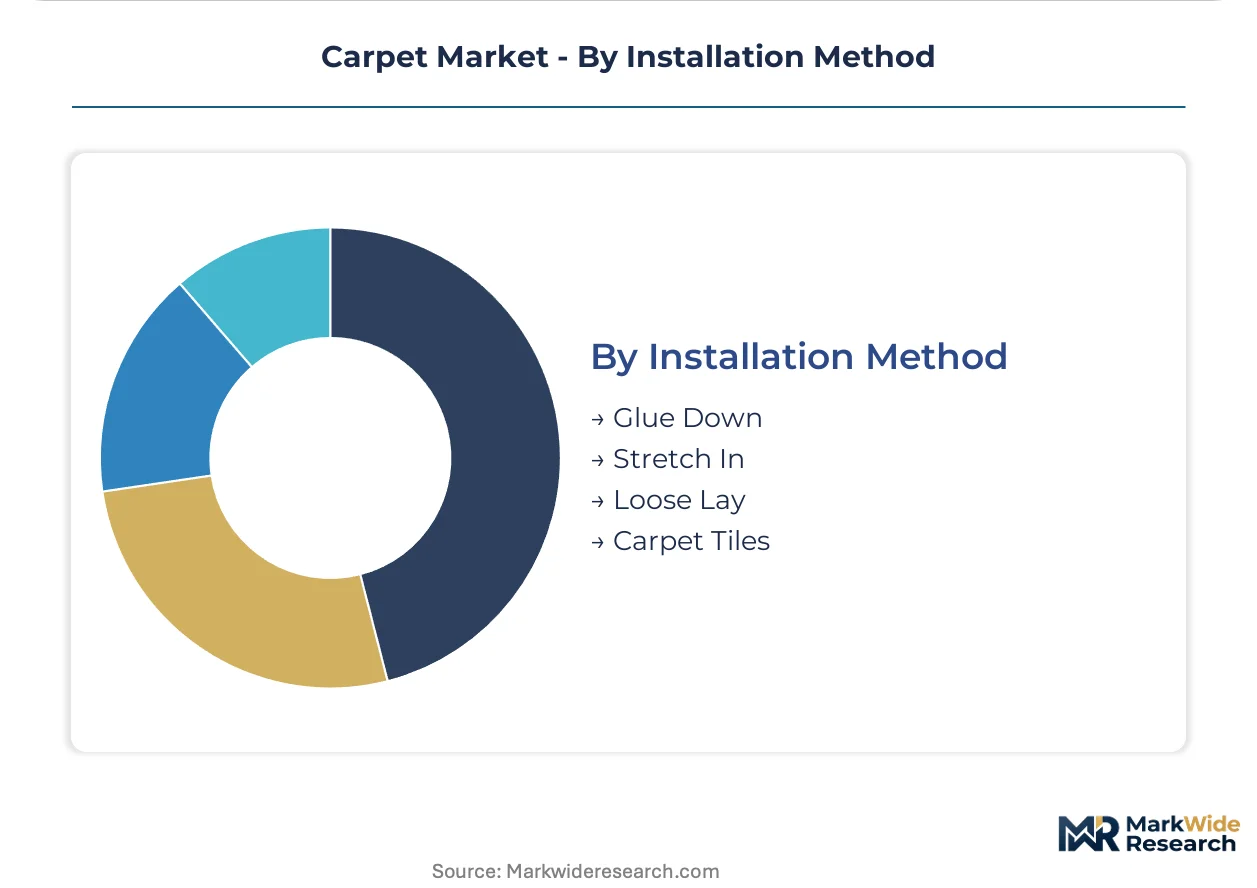
Installation Method:
Labor skill requirements and project downtime tolerance bifurcate distribution channels between professional contractor dependence and owner-occupant self-installation.
- Carpet Tiles:Modular 18-inch or 24-inch squares with integral backing enabling quarter-turn patterning and selective replacement. Healthcare and education retrofit projects in North America and Western Europe specify these for minimized operational disruption during renovation.
- Glue Down:Direct adhesive application to concrete or wood subfloors, mandatory for commercial broadloom in high-traffic corridors where dimensional stability prevents buckling.
- Stretch In:Tack strip perimeter anchoring allowing cushion layering and future removal, standard in residential applications where tenant turnover drives replacement cycles.
- Loose Lay:Friction and weight-based positioning without adhesive or mechanical fastening, limited to temporary installations and specific luxury vinyl composite hybrid products.
Glue Down holds installed capacity across commercial contractor relationships. Carpet Tiles is rotating up the share rankings through healthcare and education specification momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury hotel procurement teams and corporate sustainability officers concentrate purchasing power across four distinct national markets. Each geography presents unique regulatory friction and infrastructure maturity that shapes vendor qualification timelines.
United States
Commercial real estate retrofit cycles and hospitality renovation pipelines drive specification volume. EPA persistent organic pollutant restrictions tighten discharge thresholds for stain-resistant chemistries, forcing Georgia and South Carolina coating line retrofits. The Southeast manufacturing corridor around Dalton, Georgia anchors integrated fiber-to-finished-goods production capacity.
Germany
Corporate headquarters procurement and healthcare facility modernization sustain commercial carpet tile demand. REACH compliance through ECHA enforcement accelerates substitution of legacy per- and polyfluoroalkyl substance treatments. The Rhine-Ruhr industrial belt hosts specialized dyehouse operations adapting to closed-loop water system mandates.
India
Mumbai and Bangalore commercial corridor development generates institutional demand for high-cycle durability products. Bureau of Indian Standards certification requirements and state-level building code harmonization create compliance complexity for imported specifications. The Panipat wool clustering in Haryana faces EU Green Deal traceability restructuring for premium residential exports.
China
Zhejiang and Jiangsu synthetic fiber oversupply exerts price pressure on polyester and polypropylene commodity segments. MIIT dual carbon goals and GB standards enforcement accelerate wastewater treatment capital deployment. The Yangtze River Delta concentration of PET bottle feedstock integration supports recycled content cost advantages.
Saudi Arabia
NEOM and Red Sea tourism zone giga-projects represent underpenetrated demand for premium broadloom specification. SFDA and MOHAP building material safety protocols intersect with international hospitality brand procurement standards. Western Region construction pipelines concentrate installation contractor capacity around Jeddah logistics corridors.
Carpet Market Key Industry Players
Player mix skews toward integrated polymer producers and specialized sustainability-focused fabricators. Market structure exhibits tiered consolidation with three to five dominant integrated manufacturers controlling upstream fiber supply. Strategic archetypes include captive nylon polymerization specialists, closed-loop recycling system operators, and hospitality-focused broadloom specification houses. Competitive moves center on backward integration into caprolactam supply and geographic expansion into Saudi hospitality construction pipelines.
Within the integrated manufacturing tier, Mohawk Industries and Shaw Industries Group represent scale-driven archetypes with captive fiber production. Interface exemplifies sustainability-differentiated positioning through closed-loop recycling system investment. Tai Ping Carpets International Limited anchors hospitality-focused specification expertise for luxury hotel procurement channels.
| Leading Market Players |
|---|
| Tarkett |
| Milliken & Company |
| Mohawk Industries |
| Victoria PLC |
| Tai Ping Carpets International Limited |
| Shaw Industries Group |
| Oriental Weavers |
| Interface |
| Beaulieu International Group |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with benzene derivative indexation lock in caprolactam supply visibility for integrated nylon producers while exposing non-captive manufacturers to margin volatility when feedstock costs spike. This contract structure concentrates pricing power among polymerization-integrated players in Georgia and South Carolina while compressing returns for converters dependent on spot resin markets.
Pricing Analysis
Cost-plus contracts indexed to benzene futures dominate caprolactam procurement, anchoring nylon fiber pricing to petrochemical volatility. Three-tier pricing structure across performance-grade, commercial-specification, and builder-grade levels separates ISO 14001-certified premiums from commodity tiers. Pricing pressure stems from Zhejiang polyester oversupply bleeding into residential replacement channels. Residential builder-grade buyers exhibit highest price sensitivity; hospitality procurement teams prioritize lifecycle durability over first cost.
Supply Chain Analysis
Dalton, Georgia tufting capacity concentration creates a chokepoint where two-thirds of North American broadloom output passes through a fifty-mile corridor. Raw material flows draw from caprolactam polymerization in South Carolina, PET bottle flake processing in Zhejiang, and wool scouring in Panipat, Haryana. Tariff exposure on Chinese polyester staple fiber imports threatens margin structure for non-integrated tile producers. Distribution runs through contract dealer networks for commercial specification and big-box retail for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIM-integrated material libraries are transforming carpet specification into a platform economics dynamic where data interoperability determines vendor inclusion. EPD-embedded digital workflows create ecosystem lock-in for early movers.
For Market Incumbents: Consolidate captive caprolactam supply through backward integration into benzene derivative refining or secure ten-year offtake agreements before REACH reformulation deadlines tighten qualified supplier pools. Defend hospitality channel position by accelerating ISO 14001 auditor certification for tier-two dyehouse partners facing European procurement qualification backlogs. For New Entrants and Emerging Players: Lead with fluorine-free stain-resistant chemistry platforms targeting California Proposition 65 disclosure requirements as the entry wedge. Saudi giga-project hospitality pipelines represent the most penetrable geography for premium broadloom specification. Pursue direct architect specification through BIM library partnerships rather than dealer channel dependence. For Investors and Strategic Acquirers: Capital is best deployed toward closed-loop recycling system operators with established reclamation infrastructure ahead of New York and California extended producer responsibility legislation activation. Five-to-ten year viability favors producers with integrated fiber-to-finished-goods manufacturing scale. Monitor state-level EPR rulemaking timelines as the inflection signal for reclamation asset valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive polymerization secures margin control against benzene derivative volatility for nylon producers. |
| Closed-Loop Recycling System Investment | Interface-style reclamation infrastructure qualifies producers for corporate sustainability procurement mandates. |
| BIM Library Partnership Development | EPD-embedded digital specifications compress sales cycles and bypass traditional dealer showroom dependence. |
| Fluorine-Free Chemistry Platform Launch | EPA persistent organic pollutant compliance maintains project eligibility in hospitality and healthcare segments. |
| Saudi Hospitality Specification Push | NEOM and Red Sea tourism zones represent underpenetrated demand for premium broadloom with pattern continuity. |
Research Approach
A standing panel of contract dealer principals, hospitality procurement directors, carpet mill operations executives, and commercial architect specification leads provided ongoing calibration against secondary validation from customs trade data, SEC manufacturing filings, ECHA REACH registration databases, and Bureau of Indian Standards certification records. Bottom-up volume triangulation across fiber type, end-use segment, and installation method converged with top-down macroeconomic anchoring.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated fiber chemistry, performance grade tier, installation methodology, and regional regulatory cluster dimensions. CAGRs were derived from fitted trend analysis applied to historical shipment data and forward-projected construction pipeline indicators including commercial real estate absorption and hospitality renovation cycles.
Forecasts assume regulatory continuity in EPA discharge thresholds, REACH chemical reformulation timelines, and California Proposition 65 disclosure mandates; material policy shifts would require re-modeling of compliance cost trajectories and qualified supplier pool dynamics. Practitioners should keep alternative scenarios live as state-level extended producer responsibility legislation and EU Green Deal traceability enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Floor Covering Market