
 Japan Floor Covering Market | 2026-2036
Japan Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Floor Covering Market Foresight
Specialty flooring retailers in Osaka and Nagoya is tilting toward direct-to-contractor models, bypassing traditional wholesale layers. TOLI Corporation leverages its captive textile production to control carpet grade consistency from fiber to finished roll. DAIKEN Corporation anchors the engineered wood segment through integrated forestry-to-mill operations in Hokkaido. LIXIL Corporation competes across multiple product types with centralized logistics hubs serving both residential and commercial channels.
Japan floor covering encompasses surface materials installed over structural subfloors to provide wear resistance, acoustic dampening, and aesthetic finish, with thickness tolerances typically ranging from 2 mm for sheet vinyl to 15 mm for engineered hardwood planks. These products serve primarily to protect building interiors while enabling rapid refurbishment of aging housing stock and commercial interiors. Vinyl systems lead volume through water-resistant formulations suited to Japan's humid summers and compact residential layouts, while hardwood commands margin pools in premium residential renovation where natural material specifications carry cultural weight. Carpet maintains position in hospitality and senior care facilities where underfoot comfort and slip resistance carry regulatory significance, though textile faces substitution pressure from high-density vinyl plank in commercial specifications.
METI energy efficiency guidelines and JIS standards for indoor formaldehyde emissions shape product certification requirements, with the Building Standards Law amendments tightening VOC thresholds for adhesives used in glue-down installations. PMDA oversight of antimicrobial flooring claims in healthcare settings adds a secondary compliance layer for manufacturers targeting medical facility specifications. Stakeholders must monitor how upcoming JIS revisions for recycled content thresholds will reshape material sourcing strategies across domestic supply chains.
Market Dynamics
Japan's floor covering sector is compressing under the weight of Building Standards Law revisions that tighten VOC thresholds for adhesives, forcing manufacturers to reformulate product lines and recertify installation systems ahead of compliance deadlines.
Growth Catalysts
- Condominium stock renewal:The Greater Tokyo Area's aging tower inventory is accelerating replacement cycles, with unit owners associations driving bulk flooring upgrades during mandatory seismic retrofit windows.
- METI energy efficiency guidelines:Thermal performance mandates for building envelopes are expanding demand for insulated subfloor systems that integrate with floor covering specifications.
- Click-lock vinyl systems:Tool-free installation technology is virtualizing traditional glue-down methods in residential renovation, shortening project timelines for aging-in-place modifications.
Market Restraints
- Petrochemical input volatility:Vinyl resin and polyurethane adhesive feedstock costs fluctuate with naphtha pricing, compressing margin pools for mid-tier sheet vinyl producers.
- Domestic forestry supply concentration:Engineered hardwood manufacturers depend on Hokkaido timber operations, exposing production schedules to regional weather disruptions and transport bottlenecks.
- Formaldehyde emission thresholds:JIS standards for indoor air quality create technical barriers for imported laminate products that lack Japan-specific certification testing.
Strategic Opportunities
- Osaka-Nagoya corridor bypass:Specialty retailers are testing direct-to-contractor fulfillment models that eliminate wholesale markups and capture margin from professional installation channels.
- Recycled content mandates:Upcoming JIS revisions for post-consumer material thresholds will reward domestic manufacturers with captive recycling infrastructure.
- Healthcare antimicrobial specifications:PMDA oversight of infection-control flooring claims creates a compliance moat for suppliers willing to navigate pharmaceutical-grade documentation requirements.
Industry Challenges
- Certification timeline compression:Overlapping METI, JIS, and PMDA approval tracks for multi-function flooring products extend time-to-market for innovation launches.
- Installation labor scarcity:Glue-down specialty contractors face attrition as younger workers avoid solvent-exposure trades, constraining capacity for premium hardwood specification fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Floor Covering Market |
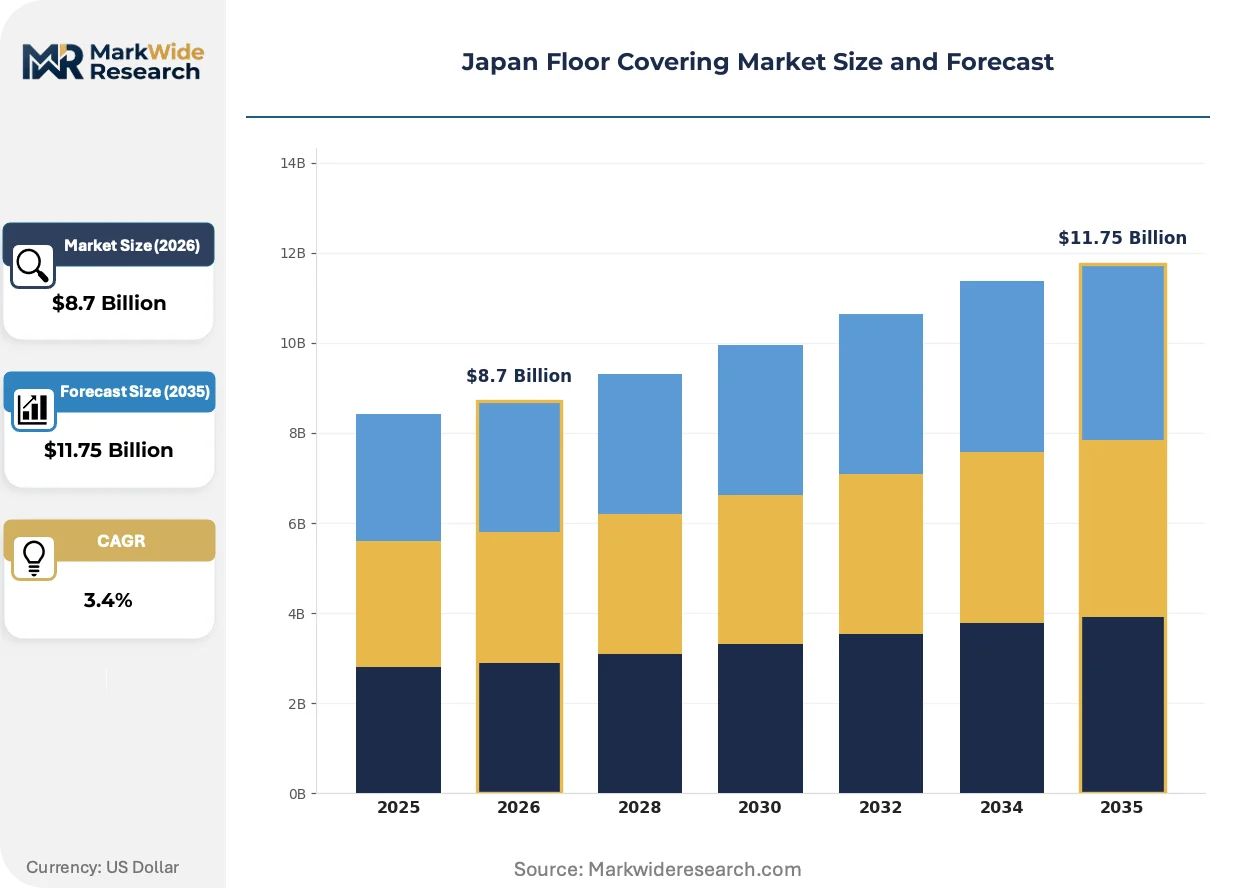
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminate, Vinyl, Hardwood, Carpet End User: Residential, Commercial, Industrial, Hospitality Material: Polyvinyl Chloride, Wood, Textile, Rubber Installation Type: Glue-down, Click-lock, Loose lay, Nail-down |
| Companies Covered | TOLI Corporation, DAIKEN Corporation, Sincol Co Ltd, Sangetsu Corporation, Hisamatsu Seito Co Ltd, Danto Tile Co., Ltd., TOYOTEX, LIXIL Corporation, TOTO Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Floor Covering Market Shifts & Advancements
Digital visualization tools and modular installation systems are restructuring how Japanese buyers specify and source floor coverings, collapsing the traditional showroom-to-contractor information chain.
Photorealistic rendering software is virtualizing the residential selection process, allowing condominium owners to overlay material options onto unit photographs before physical sampling. Major renovation platforms in Tokyo and Yokohama have integrated these tools into their contractor matching services, compressing the decision window from weeks to days. The technology is virtualizing the role of traditional sample libraries and reducing return rates for specialty orders.
METI's phased implementation of stricter formaldehyde emission classifications under JIS A 1460 is forcing adhesive manufacturers to accelerate water-based formulation development. Flooring installers now face mandatory certification updates to handle low-VOC products with modified open times and bonding characteristics. The Kansai region's commercial renovation sector is absorbing the steepest compliance costs as older inventory requires full substrate remediation.
Buyer concentration among large-scale condominium associations is consolidating procurement authority away from individual unit owners. These associations now negotiate master supply agreements directly with manufacturers, bypassing the fragmented retail channel that historically served Tokyo's renovation market. The shift is most visible in tower renewal projects exceeding 500 units, where specification uniformity overrides aesthetic individualization.
Japan Floor Covering Market Segmentation
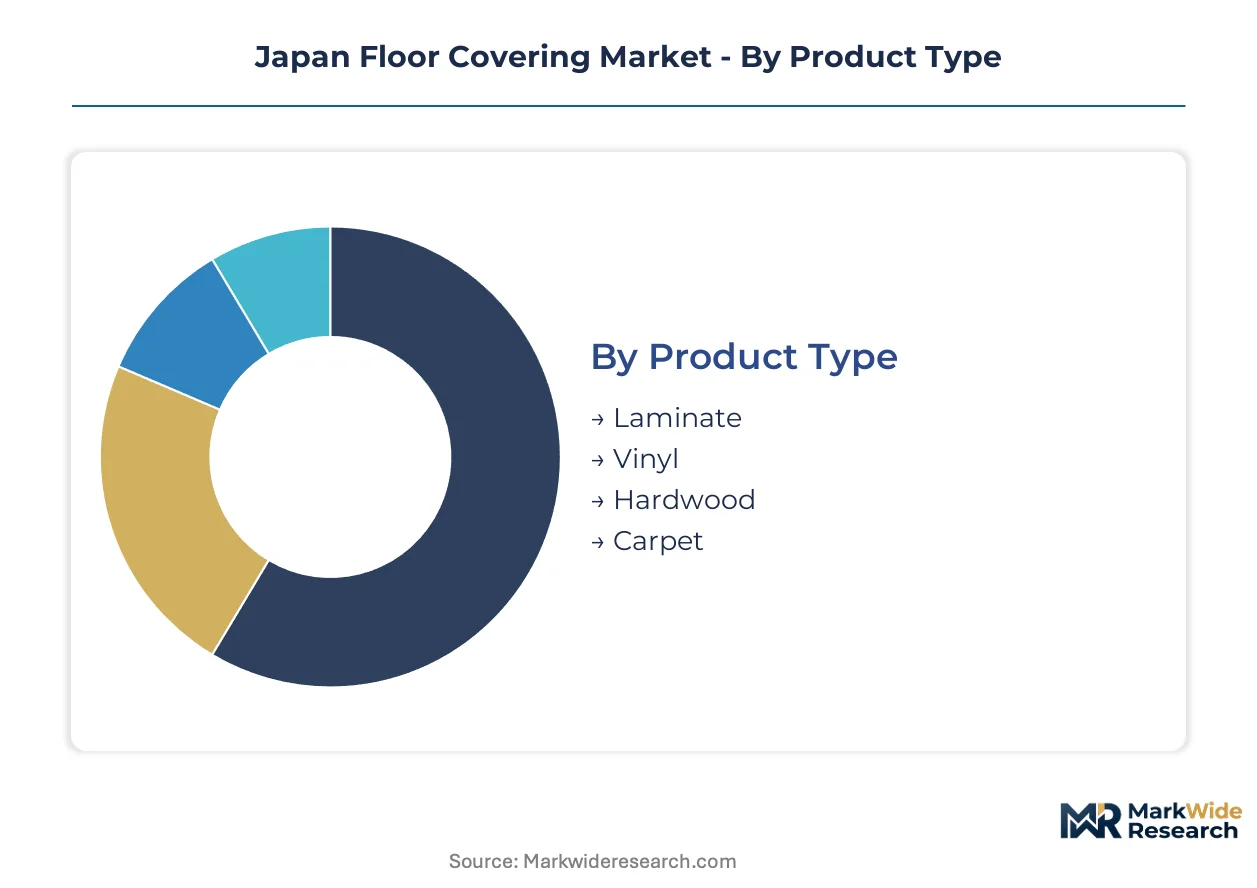
Segmentation in Japan's floor covering market reveals how distinct customer requirements reshape service intensity and technical support investments. Each dimension carries implications for inventory depth, certification documentation, and installer training commitments.
Product Type:
After-sales service intensity varies sharply across flooring categories, with warranty claim rates and technical support demands dictating distributor staffing models.
- Vinyl:Polymer-based sheet and plank formulations dominate volume through water-resistant specifications suited to humid climates. Demand concentrates in Greater Tokyo Area condominium renovations where click-lock systems enable rapid unit turnover during mandatory seismic retrofit windows.
- Carpet:Tufted and woven textile constructions require specialized maintenance protocols and stain remediation services. Hospitality properties in Osaka and senior care facilities across Aichi Prefecture drive specification volume where acoustic dampening and slip resistance carry regulatory weight under METI guidelines.
- Hardwood:Solid and engineered timber products command premium positioning through natural material specifications with cultural resonance in residential applications.
- Laminate:High-density fiberboard core systems face substitution pressure from vinyl plank alternatives due to JIS formaldehyde emission certification barriers for imported products.
Vinyl holds the largest share; momentum sits with carpet in institutional specifications.
End User:
Cost tier stratification separates specification authority between individual decision-makers and centralized procurement committees.
- Residential:Single-family homeowners and condominium unit owners prioritize rapid installation and minimal disruption. The Greater Tokyo Area's aging tower inventory accelerates replacement cycles through bulk association negotiations.
- Commercial:Office and retail tenants demand durable surfaces with accelerated depreciation schedules. Kansai region commercial renovation absorbs steepest compliance costs for substrate remediation under METI emission standards.
- Hospitality:Hotels and ryokan properties balance aesthetic differentiation with high-traffic durability requirements.
- Industrial:Manufacturing and logistics facilities specify chemical-resistant and anti-fatigue surfaces for safety compliance.
Residential captures the greatest volume; hospitality delivers the steepest expansion trajectory through inbound tourism recovery.
Material:
Supply concentration in Hokkaido forestry and petrochemical complexes determines regional production scheduling and transport cost structures.
- Polyvinyl Chloride:Resin-based formulations lead volume through moisture resistance and price accessibility. Naphtha feedstock volatility compresses margin pools for mid-tier sheet producers.
- Wood:Domestic timber from Hokkaido operations anchors engineered hardwood production, exposing schedules to regional weather disruptions.
- Textile:Nylon and wool fiber systems serve institutional comfort specifications with antimicrobial treatment requirements.
- Rubber:Synthetic and natural elastomer compounds address industrial safety and acoustic isolation applications.
Polyvinyl Chloride dominates installed volume; wood materials gain share fastest in premium renovation segments.
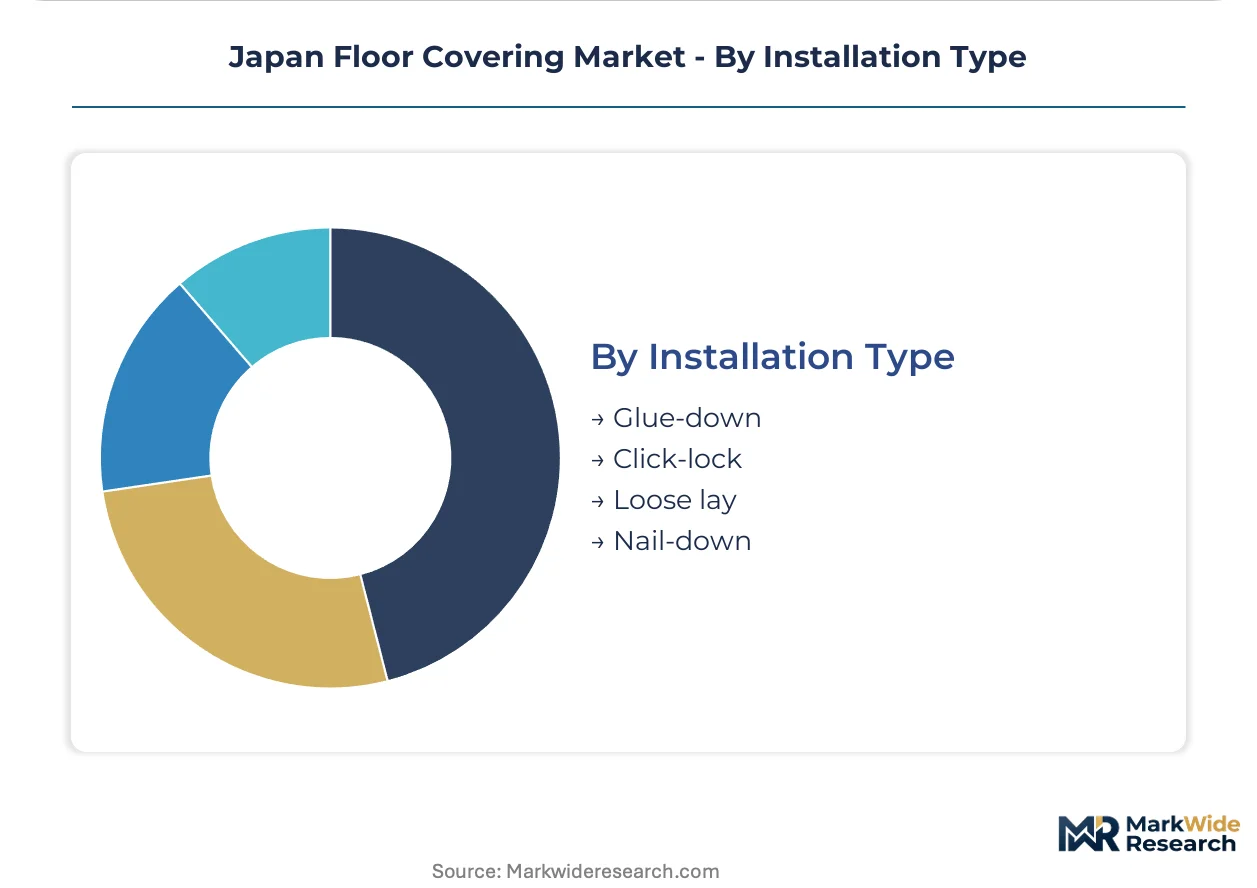
Installation Type:
Customer type segmentation separates professional contractors from tool-capable residential buyers, reshaping distribution margin capture.
- Click-lock:Mechanical fastening systems eliminate adhesive curing time and specialized labor requirements. Tool-free installation technology virtualizes traditional glue-down methods in aging-in-place modifications.
- Glue-down:Full-spread adhesive applications demand certified installers with solvent-exposure tolerance, constraining capacity as younger workers exit the trade.
- Loose lay:Friction-fit and weighted systems enable rapid deployment and future removal for temporary commercial installations.
- Nail-down:Traditional mechanical fastening for solid hardwood over wood subfloors requires skilled carpentry labor.
Glue-down retains the largest installed base; click-lock systems are expanding most quickly through residential renovation channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tōkaidō Shinkansen corridor binds Japan's floor covering demand centers into a single economic spine, moving materials and specifications between the capital region, Nagoya manufacturing belt, and Osaka commercial hub.
Greater Tokyo Area
Condominium tower associations drive bulk procurement for seismic retrofit windows. METI building energy codes tighten thermal performance requirements for flooring systems. The Koto and Minato wards concentrate hospitality renovation where vinyl plank displaces carpet in high-traffic specifications.
Kansai Region
Osaka specialty retailers test direct-to-contractor fulfillment models. JIS formaldehyde emission revisions force substrate remediation in older commercial inventory. The Nishi-Umeda and Namba districts anchor hospitality specification volume for inbound tourism recovery.
Chubu Region
Nagoya manufacturing spillover sustains industrial flooring demand for anti-fatigue and chemical-resistant surfaces. PMDA oversight of antimicrobial claims shapes healthcare facility specifications. The Sakae and Meieki districts concentrate senior care construction where slip-resistant surfaces carry regulatory weight.
Hokkaido
Integrated forestry-to-mill operations anchor engineered hardwood supply. Regional weather disruptions expose transport bottlenecks for timber-dependent producers. The Sapporo metropolitan area drives residential new construction with natural material specifications.
Kyushu
Fukuoka's startup ecosystem attracts co-working and flexible office construction with rapid-install flooring requirements. Municipal green building incentives reward low-VOC adhesive specifications. The Tenjin and Hakata districts concentrate commercial renovation absorbing compliance costs for emission standards.
Japan Floor Covering Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying raw materials and intermediate goods. The vendor base compresses into three functional layers: captive-forestry hardwood producers, petrochemical-derived vinyl formulators, and textile-integrated carpet manufacturers. Consolidation pressure concentrates among mid-tier sheet vinyl producers exposed to naphtha feedstock volatility. Dominant competitive moves include backward integration into resin production and geographic expansion through direct-to-contractor distribution bypasses.
Among integrated Japanese manufacturers, TOLI Corporation and DAIKEN Corporation exemplify distinct archetypes: the former represents textile-integrated carpet specialists with captive fiber production, while the latter anchors engineered hardwood through Hokkaido forestry control. LIXIL Corporation occupies a platform position spanning multiple product categories with centralized logistics infrastructure. These three companies illustrate how supply chain configuration determines margin capture in a market tightening around emission compliance and installation labor scarcity.
| Leading Market Players |
|---|
| TOLI Corporation |
| DAIKEN Corporation |
| Sincol Co Ltd |
| Sangetsu Corporation |
| Hisamatsu Seito Co Ltd |
| Danto Tile Co., Ltd. |
| TOYOTEX |
| LIXIL Corporation |
| TOTO Ltd. |
| Others |
Supply & Pricing Matrix
Hokkaido forestry operations and Kawasaki petrochemical complexes anchor upstream supply, concentrating margin capture among integrated manufacturers with captive timber or resin production while exposing mid-tier formulators to feedstock volatility.
Pricing Analysis
Volume-discount tiering structures separate condominium association master agreements from individual unit owner transactions. Three-tier pricing stratifies across JIS A 1460 premium certification, standard compliance, and economy grades without full emission testing. Pricing pressure stems from naphtha-linked vinyl resin costs that compress margins for sheet producers lacking backward integration. Single-family homeowners exhibit highest price sensitivity; hospitality developers in Tokyo's Minato Ward absorb premium positioning for specification uniformity.
Supply Chain Analysis
Tariff exposure between Japan and Southeast Asian laminate exporters dominates supply chain risk as JIS formaldehyde certification barriers restrict non-compliant imports. Geographic concentration centers on Hokkaido timber, Kawasaki petrochemical complexes, and Osaka textile mills. Raw material dependencies include vinyl chloride monomer, polyurethane adhesive precursors, and nylon fiber. Distribution runs through manufacturer-direct fulfillment to large contractors, bypassing traditional wholesale layers in the Osaka-Nagoya corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's floor covering sector tracks cyclical recovery through condominium stock renewal waves triggered by mandatory seismic retrofit windows in Greater Tokyo Area towers.
For Market Incumbents: Pre-empt click-lock vinyl substitution by accelerating water-based adhesive certification ahead of Building Standards Law compliance deadlines. Deepen captive forestry control in Hokkaido to offset weather-driven supply disruptions. Secure installer training capacity before glue-down contractor attrition constrains premium hardwood fulfillment. For New Entrants and Emerging Players: Direct-to-contractor fulfillment models in the Kansai region represent the most penetrable entry point, bypassing entrenched wholesale relationships. Healthcare antimicrobial flooring specifications under PMDA oversight offer regulatory-moat positioning against commodity competitors. Lead with digital visualization tools integrated into renovation platform contractor-matching services. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive resin or timber supply and established JIS certification infrastructure. Long-term viability hinges on emission compliance capability rather than scale alone. Monitor JIS recycled content threshold revisions as the signal for material sourcing strategy inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive vinyl chloride supply insulates margin pools from naphtha volatility at Kawasaki complexes. |
| Water-Based Adhesive Certification | Building Standards Law compliance creates technical moat against imported laminate competitors. |
| Direct-to-Contractor Distribution Expansion | Osaka-Nagoya corridor bypass captures margin from professional installation channel consolidation. |
| Healthcare Antimicrobial Specification Investment | PMDA oversight documentation requirements filter out commodity suppliers in medical facility procurement. |
| Digital Visualization Platform Integration | Photorealistic rendering tools compress decision windows for condominium association bulk procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with flooring manufacturers, installation contractors, condominium association procurement officers, and METI regulatory affairs specialists; and secondary validation through JIS standard documentation, Building Standards Law amendment filings, customs trade records for vinyl resin imports, and corporate sustainability disclosures from integrated forestry operators. Bottom-up unit economics triangulated against top-down construction spending data across prefectural statistical yearbooks.
Forecast inputs incorporated product type segmentation by installation method, material chemistry, and end-use vertical alongside geographic demand clustering around seismic retrofit corridors. CAGRs derived from trend extrapolation of replacement cycle acceleration, energy code adoption curves, and tourism-driven hospitality construction permits. Modeled variables included adhesive formulation transition timelines and installer labor pool attrition rates.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, inbound tourism recovery velocity, or naphtha pricing volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation schedules and substitution elasticity between vinyl and hardwood specifications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market