
 Indoor Flooring Market | 2026-2036
Indoor Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Flooring Market Foresight
Skilled flooring installer availability is rotating toward acute shortage in mature economies while emerging markets expand apprenticeship pipelines. Mohawk Industries leverages captive tile manufacturing across multiple continents to sustain margin stability. Shaw Industries Group anchors North American carpet and hard-surface supply through integrated fiber-to-finish operations. Tarkett competes on healthcare and education specification strength with phthalate-free vinyl formulations.
Indoor flooring encompasses finished surface materials installed above structural subfloors, spanning engineered wood composites, PVC-based resilient layers, fired clay ceramics, and textile-backed carpet systems rated for abrasion resistance, slip coefficients, and VOC emissions. Its primary purpose is to provide durable, safe, and aesthetically specified walking surfaces for occupied buildings. Laminates and vinyl capture expanding share in residential renovation as homeowners prioritize water resistance and DIY compatibility. Tiles retain specification dominance in commercial healthcare applications where infection control and longevity override first-cost considerations. Carpets contract in mainstream office buildouts but sustain margin pools in hospitality and senior living segments requiring acoustic dampening.
The US EPA oversees formaldehyde emission standards under TSCA Title VI, compelling composite wood flooring producers to certify chain-of-custody compliance. The EU ECHA enforces REACH restrictions on phthalate plasticizers in vinyl flooring, redirecting formulation investments toward bio-based plasticizer alternatives. China's SAMR implements GB standards for indoor air quality that disqualify non-compliant flooring imports from public procurement. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
Formaldehyde emission limits under China's GB standards and the US EPA's TSCA Title VI are compressing composite wood flooring supply chains while redirecting specification toward low-VOC resilient alternatives. Manufacturers face simultaneous compliance burdens across multiple jurisdictions with divergent testing protocols.
Growth Catalysts
- GB Standard Tightening:China's SAMR enforcement of stricter indoor air quality thresholds disqualifies high-emission imports from public procurement, accelerating domestic low-VOC production capacity.
- Healthcare Specification:Infection control protocols in hospital construction favor large-format ceramic tiles with antimicrobial surface treatments over organic alternatives.
- Click-Lock Installation:Mechanical fastening systems eliminate adhesive curing time, allowing Indian residential contractors to compress project schedules by 40-50 percent.
Market Restraints
- Petrochemical Feedstock Volatility:PVC resin prices fluctuate with ethylene and chlorine market swings, compressing margin stability for vinyl flooring producers.
- Skilled Installer Concentration:Mature economies face acute shortages of certified flooring mechanics, constraining renovation throughput in Germany and Japan.
- REACH Plasticizer Restrictions:ECHA limitations on phthalate formulations force reformulation investments without immediate price recovery mechanisms.
Strategic Opportunities
- India Urban Corridors:Metro rail expansion around Mumbai, Bangalore, and Hyderabad generates sustained multi-family housing demand favoring rapid-install resilient surfaces.
- Bio-Based Plasticizers:Epoxidized soybean oil and citrate ester alternatives open premium positioning for phthalate-free vinyl targeting European education and healthcare sectors.
- Direct Contractor Platforms:Digital procurement channels bypass traditional distributor markups for mid-scale commercial renovation projects in Southeast Asia.
Industry Challenges
- Cross-Border Certification Lag:Divergent VOC testing methods between EPA, ECHA, and SAMR create 6-12 month product validation timelines for multi-jurisdiction suppliers.
- Legacy Subfloor Compatibility:Moisture emission from aging concrete slabs in renovation projects triggers adhesive failures and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Flooring Market |
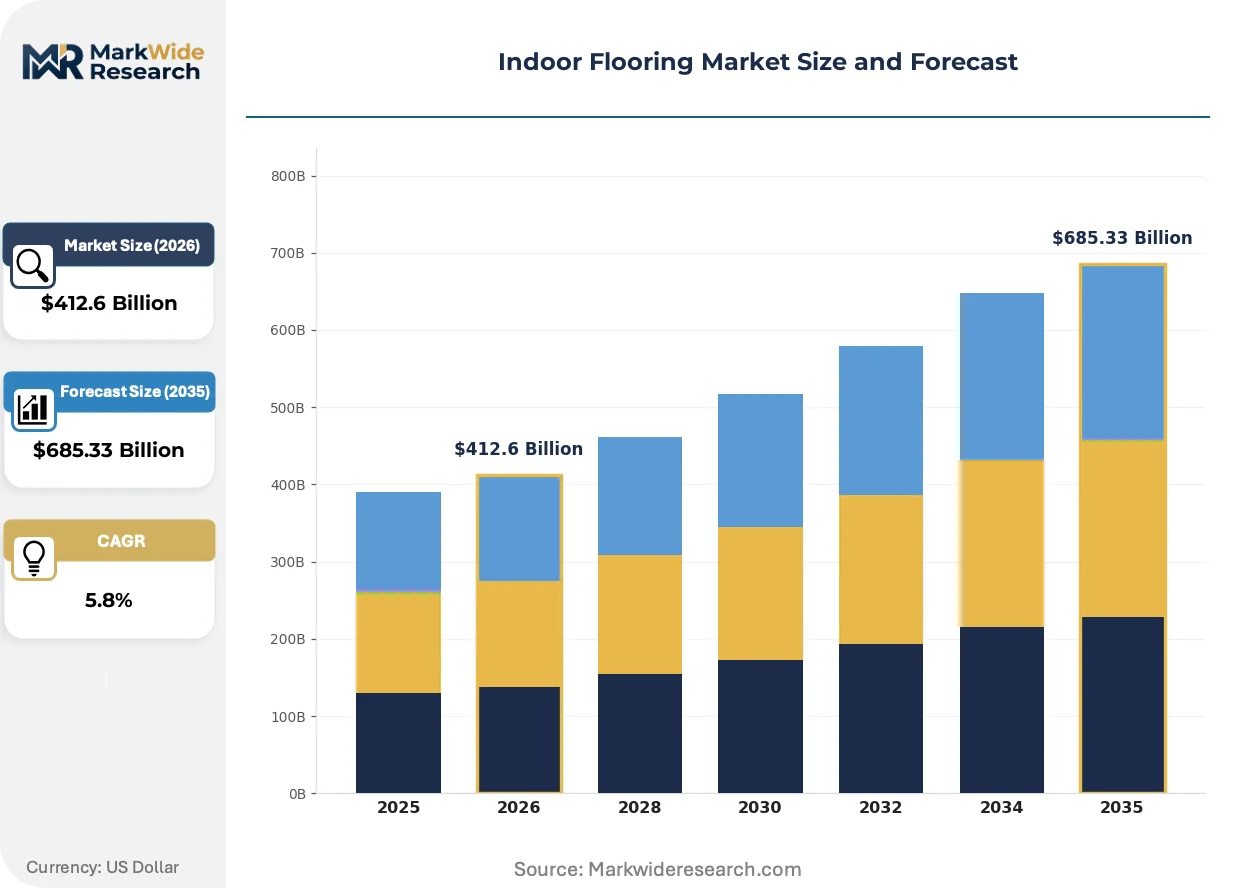
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $685.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Laminates, Vinyl, Tiles, Carpets Application: Residential, Commercial, Educational, Healthcare End User: Homeowners, Contractors, Architects, Designers Installation Type: DIY, Professional, Self-Adhesive, Click-Lock |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Tarkett, Armstrong Flooring, Inc., Forbo International SA, Interface, Inc., Beaulieu International Group, Ecore International, Mannington Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Flooring Market Shifts & Advancements
Surface technology convergence with digital manufacturing is collapsing traditional material boundaries while regulatory chemistry restrictions force formulation reinvention. Specification patterns increasingly prioritize performance certification over brand heritage.
Luxury vinyl tile with rigid core construction is supplanting traditional laminate in residential basements and commercial hospitality spaces where moisture resistance determines longevity. Property managers in US multifamily housing favor floating installations that minimize subfloor preparation costs. The shift compresses demand for conventional high-pressure laminate while expanding vinyl's addressable market into moisture-prone zones previously reserved for ceramic.
ECHA's REACH Annex XVII restrictions on phthalate plasticizers in vinyl flooring compel producers to validate bio-based alternatives through migration testing protocols. Reformulation investments concentrate in calendering operations serving European healthcare and education specification channels. German flooring distributors now require third-party phthalate-free certification as a listing prerequisite, filtering non-compliant imports from tender participation.
Facility managers in US commercial office buildouts increasingly specify flooring through performance-based maintenance contracts rather than upfront material procurement. Service providers assume lifecycle responsibility for surface condition, shifting capital allocation from product margin to installed-base service revenue. The model concentrates in Class A office assets in Dallas, Atlanta, and Chicago where tenant improvement allowances compress initial spend authority.
Indoor Flooring Market Segmentation
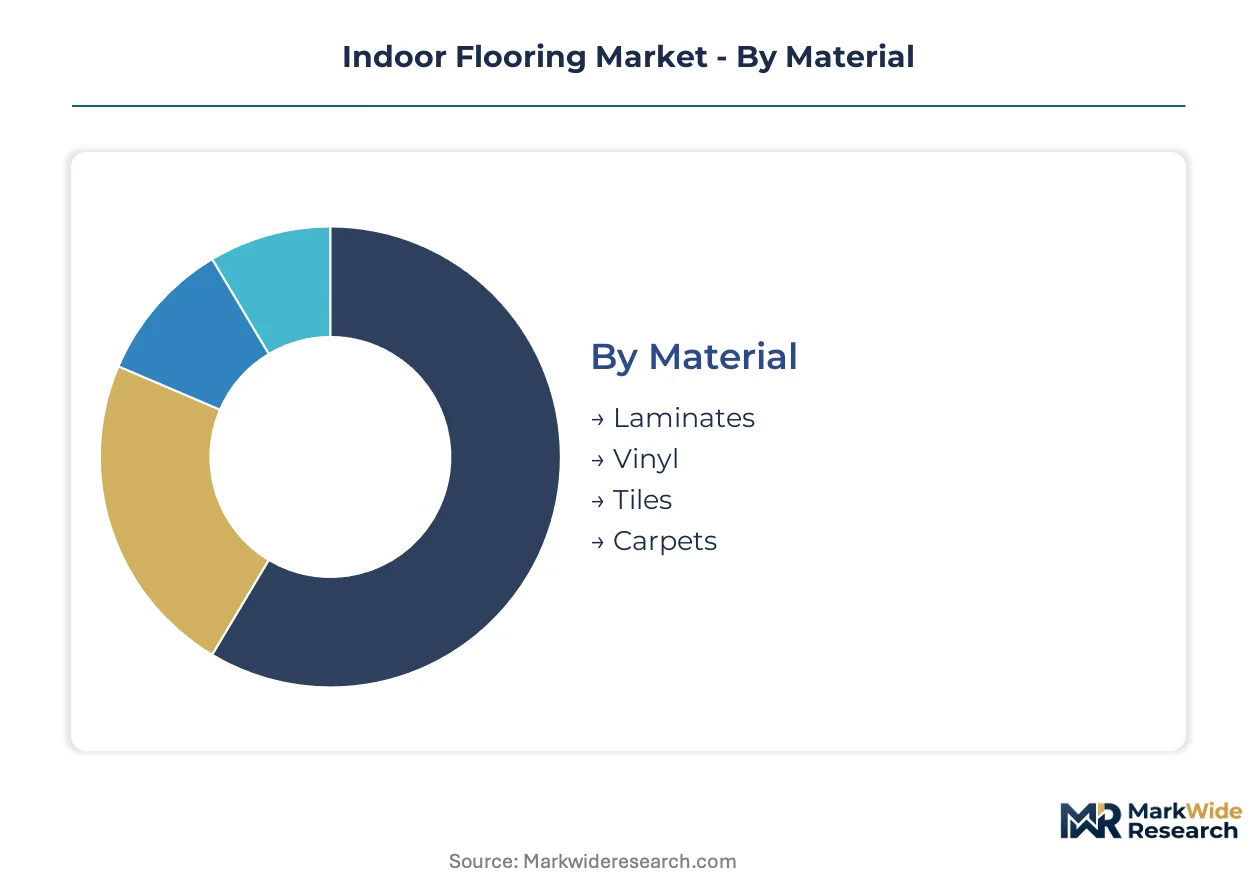
Segmentation in the indoor flooring market reveals how specification authority flows through distinct procurement channels. Material selection, application context, and installation method collectively determine margin capture and channel strategy for manufacturers and distributors.
Material:
Channel mix varies sharply by material chemistry. Vinyl and laminates dominate big-box retail and direct-to-contractor platforms. Tiles and carpets flow through specification-heavy architectural channels and specialized flooring distributors.
- Vinyl:PVC-based resilient layers with rigid core construction deliver moisture resistance and dimensional stability. Demand concentrates in US multifamily housing basements and Indian urban residential corridors where contractors prioritize speed over subfloor preparation. Rigid core vinyl is displacing laminate in moisture-prone zones previously reserved for ceramic.
- Tiles:Fired clay ceramics and porcelain offer abrasion resistance, slip coefficient control, and antimicrobial surface compatibility. Specification concentrates in hospital construction across China and Germany where infection control protocols override first-cost considerations. Large-format formats dominate new healthcare buildouts.
- Laminates:High-pressure composite wood surfaces with decorative paper overlays and aluminum oxide wear layers. Cost-sensitive residential renovation in European markets sustains volume despite moisture vulnerability limitations.
- Carpets:Textile-backed systems with nylon or polypropylene face fibers rated for acoustic dampening and thermal insulation. Hospitality and senior living segments in Japan and the US sustain margin pools as mainstream office specification contracts.
By volume, vinyl leads. By growth pace, tiles are climbing the fastest.
Application:
Cost tier stratification separates specification-heavy commercial segments from price-driven residential markets. Premium performance certifications command 40-60% markups over baseline products within the same material category.
- Residential:Single-family and multi-family housing drives volume through renovation and new construction cycles. Indian metro rail corridors around Mumbai and Hyderabad generate sustained demand for rapid-install resilient surfaces.
- Commercial:Office, retail, and hospitality buildouts specify through performance-based maintenance contracts rather than upfront procurement. Service providers in Dallas, Atlanta, and Chicago assume lifecycle responsibility for surface condition.
- Healthcare:Hospital and clinic construction mandates infection control, chemical resistance, and seamless cleaning protocols. ECHA REACH restrictions on phthalates redirect European healthcare specification toward bio-based plasticizer formulations.
- Educational:K-12 and university facilities balance durability against tight capital budgets. German distributors now require third-party phthalate-free certification as a listing prerequisite for educational tenders.
Residential captures the highest unit volume. Healthcare delivers the steepest expansion trajectory for premium-certified products.
End User:
Customer type determines information requirements and decision velocity. Homeowners research online; architects demand technical documentation; contractors prioritize availability and logistics.
- Contractors:General and specialty flooring mechanics in India and Southeast Asia favor click-lock systems that compress project schedules. Skilled installer shortages in Germany and Japan constrain renovation throughput regardless of material preference.
- Homeowners:DIY-capable consumers in US and Australian markets drive water-resistant laminate and vinyl demand through retail and direct-to-consumer platforms.
- Architects:Design professionals specify through performance certification databases, prioritizing VOC emission documentation and chain-of-custody compliance for LEED and WELL building standards.
- Designers:Interior design consultants influence material selection in hospitality and luxury residential segments where aesthetic differentiation commands premium positioning.
Contractors move the highest product tonnage. Architects drive the fastest specification change toward certified low-emission materials.
Installation Type:
Installation method shapes labor cost structure and project timeline risk. Mechanical fastening systems reduce skilled labor dependency; adhesive applications demand substrate preparation expertise.
- Click-Lock:Mechanical fastening systems eliminate adhesive curing time, allowing 40-50% schedule compression in Indian residential construction. Floating installations minimize subfloor preparation costs in US multifamily renovation.
- DIY:Self-installation by homeowners concentrates in peel-and-stick vinyl and loose-lay carpet tile formats where tooling requirements remain minimal.
- Professional:Full-service installation by certified mechanics handles complex substrates, moisture mitigation, and warranty-backed performance guarantees. Acute shortages of certified flooring mechanics constrain renovation throughput in mature economies.
- Self-Adhesive:Pressure-sensitive backing systems target quick-turn commercial refresh projects where downtime minimization outweighs longevity considerations.
Professional installation handles the largest project scale. Click-lock systems are gaining share fastest across residential and light commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors the dominant geography through GB standard enforcement that redirects specification toward low-emission resilient surfaces. The US EPA and ECHA impose parallel compliance burdens with divergent testing protocols. India's urban construction corridors generate volume demand for rapid-install systems.
United States
Multifamily housing basements and hospitality renovation drive rigid core vinyl specification. The EPA's TSCA Title VI compels composite wood flooring producers to certify chain-of-custody compliance. Dallas, Atlanta, and Chicago concentrate Class A office assets where performance-based maintenance contracts displace upfront procurement.
China
Public procurement disqualification of high-emission imports accelerates domestic low-VOC production capacity. SAMR implements GB standards for indoor air quality that tighten formaldehyde limits. Commercial real estate developers in Beijing and Shanghai specify low-VOC resilient surfaces as compliance thresholds rise.
Germany
Healthcare and education specification channels demand phthalate-free vinyl formulations. ECHA's REACH Annex XVII restrictions redirect calendering operations toward bio-based plasticizer alternatives. Flooring distributors in North Rhine-Westphalia require third-party certification as a listing prerequisite.
India
Metro rail expansion around Mumbai, Bangalore, and Hyderabad generates sustained multi-family housing demand. The Bureau of Indian Standards enforces quality benchmarks for construction materials in public infrastructure. Contractors in these urban corridors favor click-lock vinyl installation for 40-50 percent schedule compression.
Japan
Hospitality and senior living segments sustain carpet specification for acoustic dampening requirements. METI oversees industrial standards that influence building material procurement in commercial construction. Skilled installer shortages in Kanto and Kansai regions constrain renovation throughput regardless of material preference.
Indoor Flooring Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive manufacturing and fiber-to-finish operations distinguishing the upper tier from distribution-dependent specialists. The structure rewards backward integration into raw material supply and penalizes pure-play traders exposed to petrochemical feedstock volatility. Three archetypes dominate: integrated multinationals with continental manufacturing footprints, regional specialists with specification strength in institutional channels, and private-label suppliers serving big-box retail. Competitive moves concentrate on geographic diversification to escape single-jurisdiction regulatory risk and portfolio expansion into adjacent surface categories.
Among North American integrated manufacturers, Mohawk Industries, Shaw Industries Group, and Armstrong Flooring exemplify the scale-driven archetype with multi-continental production assets. Tarkett occupies a position representing European specification strength in healthcare and education channels. These named entities anchor the competitive landscape without exhausting its diversity, as regional specialists and private-label suppliers fill gaps in price-driven residential segments and emerging market construction corridors.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Tarkett |
| Armstrong Flooring, Inc. |
| Forbo International SA |
| Interface, Inc. |
| Beaulieu International Group |
| Ecore International |
| Mannington Mills, Inc. |
| Others |
Supply & Pricing Matrix
Phthalate-free plasticizer substitution in European vinyl flooring is redrawing raw material sourcing maps while compressing margin structures for producers locked into legacy supply contracts. This chemistry pivot simultaneously elevates bio-based feedstock regions and erodes price competitiveness for conventional formulations across healthcare and education specification channels.
Pricing Analysis
Geographic price spreads between Asia-Pacific manufacturing origins and European specification markets have widened as REACH compliance costs layer onto delivered product values. Three-tier pricing structure across premium-certified, standard-grade, and economy-level products dominates procurement frameworks, with certification grade and volume scale as primary differentiation drivers. Cost compression in mid-tier segments is intensifying because of ethylene feedstock volatility and reformulation investments. Residential renovation contractors in India and Southeast Asia exhibit highest price sensitivity, while German healthcare specifiers accept premium positioning for phthalate-free documentation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg are extending order-to-delivery cycles for ceramic tile and vinyl imports. Manufacturing concentrates in China for ceramic and resilient flooring, Germany for technical textiles and specialized vinyl calendering, and India for emerging rapid-install production capacity. Raw material dependencies rest on PVC resin from ethylene-chlorine complexes, kaolin clay for ceramic bodies, and bio-based plasticizer feedstocks from soybean processing regions. Single-source vulnerability in phthalate-free additive supply creates exposure for European producers. Distribution runs through specification-heavy architectural distributors in developed markets and direct-contractor platforms in emerging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified flooring mechanic shortages across Germany and Japan are constraining installed-base growth regardless of material innovation velocity, creating a bottleneck where supply of skilled labor determines market expansion ceiling more than product availability.
For Market Incumbents: Compound specification lock-in through captive certification programs for installer networks, defending against modular flooring entrants that bypass traditional mechanics. Anchor margin stability by backward integration into rigid core substrate production in India and Southeast Asia. Prioritize ECHA-compliant phthalate-free formulation capacity to maintain European healthcare and education channel access as distributors harden listing prerequisites. For New Entrants and Emerging Players: Fast-tracked GB standard certification for low-VOC resilient surfaces opens procurement access to Chinese public infrastructure projects where SAMR enforcement disqualifies incumbent imports. Target Indian metro rail corridor contractors with click-lock product lines that compress installation schedules against conventional adhesive systems. Pursue direct-to-contractor digital platforms in Southeast Asia to circumvent established distributor markups and capture price-sensitive commercial renovation volume. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors integrated manufacturers with captive raw material positions and multi-continental production footprints. Long-term viability hinges on supply chain control that insulates against petrochemical volatility and jurisdiction-specific compliance fragmentation. Acquisition focus should center on regional specialists with specification strength in healthcare or education channels and underdeveloped backward integration. Monitor ECHA plasticizer restriction expansion timelines as inflection signal for bio-based formulation investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rigid Core Substrate | Captive SPC supply secures margin stability against PVC resin volatility in India manufacturing. |
| Phthalate-Free Certification Program | ECHA-compliant documentation becomes mandatory listing prerequisite for German healthcare distributors. |
| Installer Network Certification | Proprietary mechanic training defends specification control against modular floating-floor entrants. |
| Direct Contractor Platform Launch | Digital procurement bypasses distributor markups in Southeast Asian commercial renovation segments. |
| GB Standard Compliance Fast-Track | SAMR-aligned low-VOC validation unlocks Chinese public infrastructure procurement disqualifying imports. |
Research Methodology
Initial hypotheses were tested against primary input from flooring contractor operations managers, ceramic tile plant engineers, specification architects at healthcare projects, and procurement leads at German distributors, then refined through secondary validation against customs trade data, BIS construction material quality filings, SEC manufacturer disclosures, and ECHA REACH restriction updates. Bottom-up volume estimates from installation square footage and top-down value reconstructions from producer revenue disclosures were triangulated to converge on segment sizing.
Variance decomposition across material chemistry, application end-use, installation method, and regional regulatory cluster anchored the analytical framework over the projection horizon. CAGRs were derived from installed-base growth rates, replacement cycle timing, and new construction pipeline indicators specific to healthcare facility buildouts and Indian urban residential corridors. Modeled inputs incorporated ECHA plasticizer restriction phase-in schedules and SAMR GB standard enforcement intensity assumptions.
Underlying assumptions cover regulatory compliance timelines, petrochemical feedstock price bands, and skilled labor availability trends, with deviation risk concentrated in ECHA restriction expansion scope and Indian infrastructure execution pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market