
 Saudi Arabia Carpet and Rugs Market | 2026-2036
Saudi Arabia Carpet and Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Carpet and Rugs Market Analytics
Premium-grade wool and silk-blend specifications is rotating toward dominance as hospitality and high-end residential buyers upgrade quality thresholds. Shaw Industries Group leverages its manufacturing scale to supply large-format commercial installations across the Kingdom. Taif Carpets anchors its position through deep specialization in traditional Saudi weaving patterns and regional design heritage. Al Sorayai Group competes by controlling integrated production from yarn spinning through finished rug distribution.
Carpets and rugs are textile floor coverings manufactured through tufting, weaving, or needle-felting processes using pile heights typically ranging from 3mm to 25mm, designed to provide thermal insulation, acoustic dampening, and interior aesthetic enhancement in built environments. Machine-made carpets dominate volume throughput due to cost efficiency and rapid production cycles, while handmade segments command concentrated margin pools from luxury collectors and palace-grade commissions. Wool material grades sustain premium positioning in heritage and hospitality applications, whereas polyester and nylon formulations lead commercial and healthcare sectors where stain resistance and durability specifications drive procurement decisions.
SFDA textile safety protocols and SASO quality certification requirements shape product compliance costs and import screening intensity for both domestic manufacturers and foreign suppliers. The Saudi Building Code and Giga-project master plans mandate fire-retardant and low-VOC material standards that filter available supplier pools. Stakeholders must monitor how Vision 2030 construction timelines and evolving municipal aesthetic guidelines redirect specification priorities across residential, commercial, and hospitality end-use channels.
Market Dynamics
Vision 2030 giga-project construction timelines are compressing procurement cycles and elevating fire-retardant certification requirements across Saudi Arabia's built environment sector.
Growth Catalysts
- SFDA textile safety protocols:Mandated flame-resistance testing is filtering out low-grade imports and creating procurement windows for certified domestic manufacturers serving hospitality developments in Riyadh.
- Luxury hospitality expansion:Palace-grade hotel developments in Jeddah's Red Sea Project corridor are commissioning custom wool-silk blends with 12-18 month production timelines.
- Central Region construction concentration:Riyadh's Diriyah Gate and Qiddiya master plans are anchoring specification demand for large-format commercial carpets across mixed-use districts.
Market Restraints
- Wool input cost volatility:New Zealand and Australian merino wool auctions are subject to climate-driven supply swings that compress margin predictability for premium-grade manufacturers.
- Import screening intensity:SASO quality certification requirements at Jeddah Islamic Port are extending customs clearance timelines for Turkish and Iranian suppliers.
- Polyester-nylon substitution pressure:Healthcare and education sectors are specifying synthetic pile for stain resistance, constraining wool's addressable market in institutional verticals.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar's residential stock lacks equivalent high-end retail distribution compared to Riyadh and Jeddah corridors.
- Digital specification platforms:Architects and interior designers are migrating material selection to BIM-integrated libraries that reward suppliers with 3D asset libraries and real-time inventory visibility.
- Saudi Building Code fire standards:Mandatory low-VOC and smoke-density ratings for commercial occupancies above three stories are disqualifying uncertified competitors from mid-market tenders.
Industry Challenges
- Master weaver skill scarcity:Traditional hand-knotting expertise concentrated in Taif and Al-Ahsa is not replenishing at rates matching heritage commission demand.
- SASO certification timeline friction:Laboratory testing backlogs for pile density and colorfastness are extending product-to-market cycles by 8-14 weeks for new entrants.
- Legacy inventory mismatch:Distributors holding pre-2023 stock without updated fire-retardant labels face write-down pressure as municipal enforcement tightens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Carpet and Rugs Market |
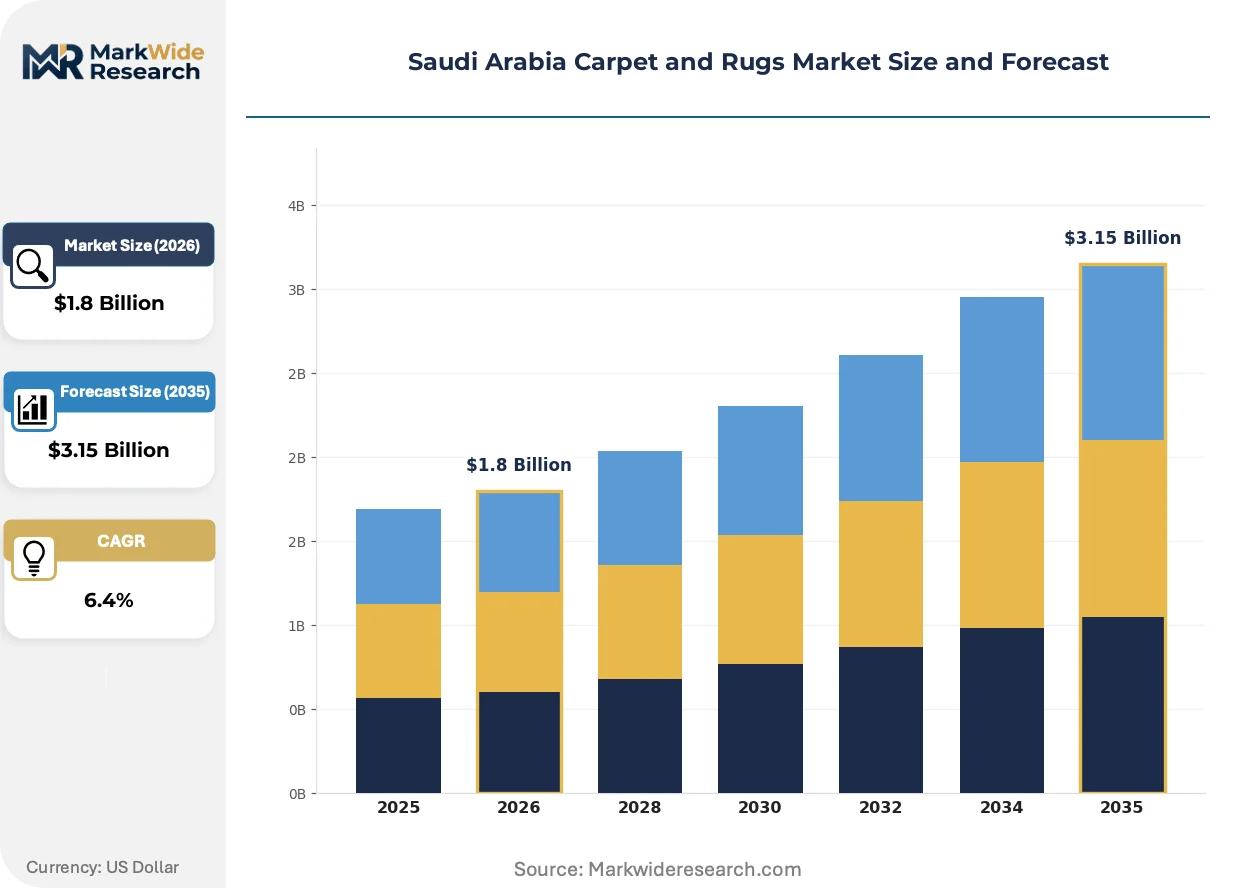
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handmade, Machine-made, Carpet Tiles, Area Rugs Material: Wool, Nylon, Polyester, Jute Design Style: Traditional, Modern, Transitional, Contemporary End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | Shaw Industries Group, Taif Carpets, Al Sorayai Group, Merinos, Balta Group, Al Abdullatif Industrial Investment Co, Mohawk Industries, Al Kaffary Group, Oriental Weavers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Carpet and Rugs Market Evolving Landscape
Material science advances and procurement digitization are compressing specification cycles while elevating performance thresholds across Saudi Arabia's contract interiors sector.
Solution-dyed nylon fiber technology is supplanting conventional piece-dyed alternatives in high-traffic commercial installations. Hospitality procurement teams in Jeddah and Riyadh are specifying this material for 15-year wear warranties in ballroom and corridor applications. The shift is compressing maintenance cost projections and displacing wool-nylon blends in mid-tier hotel segments.
SASO's 2024 technical regulation updates for textile floor coverings are mandating enhanced smoke toxicity testing for products installed in healthcare and education occupancies. Domestic manufacturers with in-house testing facilities are absorbing compliance costs faster than import-dependent distributors. Hospital procurement departments in Riyadh are now requiring batch-specific test certificates prior to purchase order release.
Direct-to-designer digital sampling is displacing traditional showroom-dependent specification patterns. Architecture firms handling giga-project interiors are requesting AR-enabled rug visualization tools that overlay true-scale patterns onto floor plans. This behavioral shift is most visible among Riyadh-based practices managing multiple simultaneous hospitality and residential tower developments.
Saudi Arabia Carpet and Rugs Market Segmentation
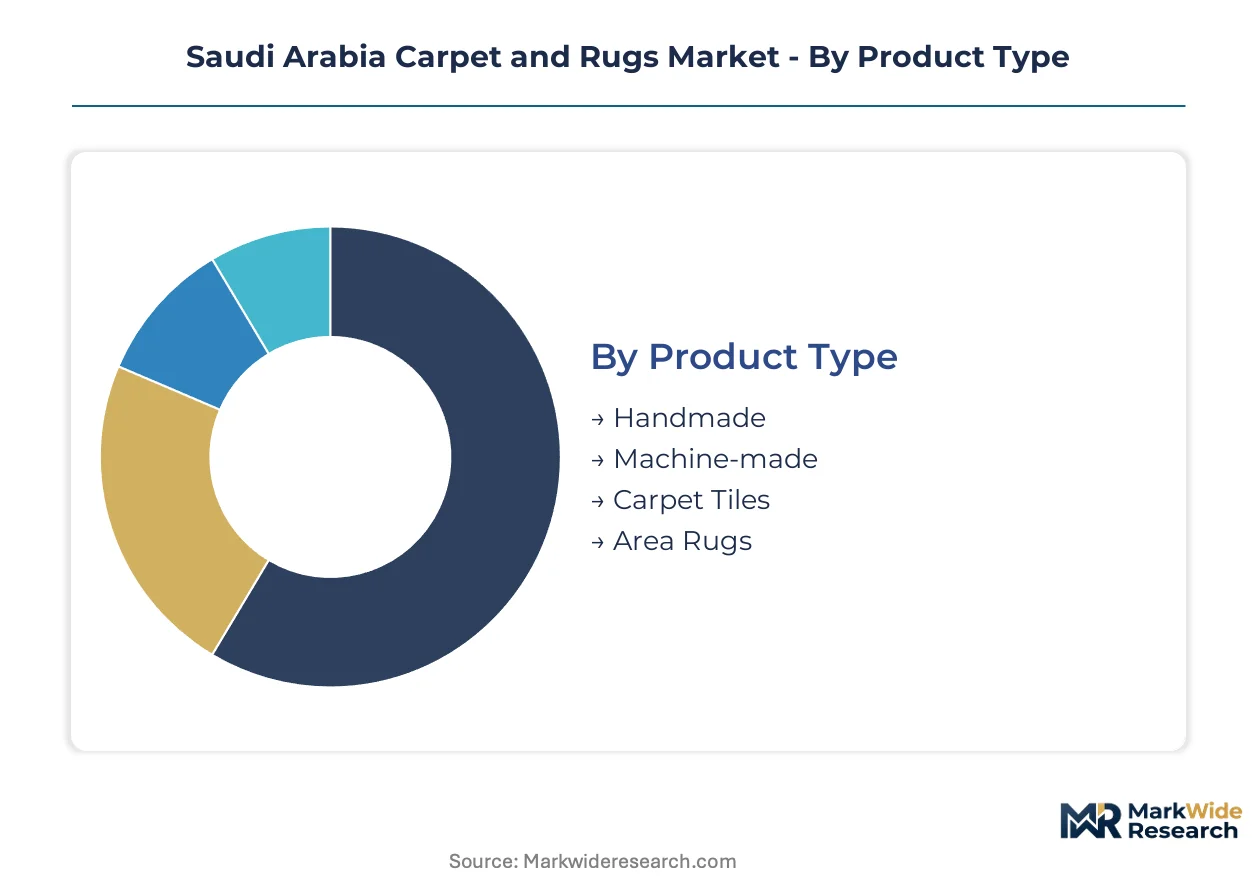
Segmentation in Saudi Arabia's carpet and rugs market reveals how procurement priorities diverge across construction verticals, material specifications, and design traditions. Specification patterns in Riyadh's giga-projects differ markedly from heritage restoration commissions in Taif, requiring suppliers to maintain parallel production capabilities.
Product Type:
Machine-made carpets face intensifying substitution pressure from carpet tiles in commercial fit-outs, while handmade segments defend position through irreplaceable craft heritage.
- Machine-made:Tufted and woven constructions utilizing high-speed looms deliver pile densities of 800-2000 stitches per square meter. Hospitality procurement teams in Jeddah's Red Sea Project corridor specify these for rapid-turnover guest room installations where 7-10 year replacement cycles dominate capital planning.
- Handmade:Hand-knotted and flat-weave techniques employing Persian, Turkish, and indigenous Saudi knot densities require 6-18 months production timelines. Palace-grade commissions from Riyadh's Diriyah Gate heritage district sustain this segment despite labor scarcity in traditional weaving centers.
- Carpet Tiles:Modular 50cm x 50cm and 1m x 1m formats with bitumen or PVC backing enable targeted replacement in high-traffic zones.
- Area Rugs:Finished dimensions typically 1.5m x 2.4m to 3m x 4m serve as anchor pieces in residential majlis and corporate reception spaces.
Machine-made carpets anchor the volume base while carpet tiles gain share at the steepest rate.
Material:
Cost tier stratification separates premium natural fibers from volume synthetics, with procurement budgets in healthcare and education sectors driving divergence.
- Wool:New Zealand and Australian merino grades with 32-40 micron fiber diameters provide inherent flame resistance meeting SFDA textile safety protocols. Luxury hospitality developments in Riyadh specify wool-silk blends for lobby and ballroom installations where 25-year lifecycle costing justifies premium first cost.
- Polyester:Solution-dyed PET formulations deliver stain resistance and colorfastness specifications required by Saudi Building Code healthcare occupancies. Hospital procurement departments across the Central Region favor this material for clinical corridors and patient room applications.
- Nylon:Type 6 and Type 6,6 polymers with solution-dyed coloration provide 15-year wear warranties in commercial installations.
- Jute:Natural bast fiber constructions serve transitional residential applications and sustainable design specifications.
Polyester commands the largest shipment volumes while wool maintains the highest margin per square meter.
Design Style:
Application context determines specification—heritage restoration projects enforce strict traditional requirements while corporate interiors favor clean-lined alternatives.
- Traditional:Geometric and floral motifs derived from Islamic art traditions, including Oushak, Heriz, and indigenous Najdi patterns. Diriyah Gate and AlUla restoration projects mandate these specifications for cultural authenticity compliance.
- Modern:Minimalist color fields and abstract geometries align with international hospitality brand standards. Qiddiya entertainment district hotels specify these for guest room and corridor installations.
- Transitional:Blended motifs incorporating traditional borders with simplified field patterns bridge residential and light commercial applications.
- Contemporary:Bold-scale patterns and experimental colorways serve boutique hospitality and executive residential segments.
Traditional designs retain dominant share in heritage-adjacent developments while modern specifications expand most quickly in new-build commercial towers.
End User:
Customer type segmentation reveals how fire-retardant certification requirements and maintenance protocols reshape supplier qualification across verticals.
- Hospitality:Palace-grade hotels and serviced apartments demand custom wool-silk blends with batch-specific SFDA flame-resistance certificates. Jeddah's Red Sea Project and Riyadh's King Abdullah Financial District anchor specification volume for luxury fit-outs.
- Commercial:Office towers, retail centers, and mixed-use developments specify solution-dyed nylon and carpet tiles for 10-15 year depreciation schedules. Municipal enforcement of Saudi Building Code low-VOC standards filters supplier pools in Riyadh and Jeddah.
- Residential:Villa compounds and apartment stock across the Central Region drive area rug and broadloom demand.
- Healthcare:Hospitals and clinics require antimicrobial treatments and smoke-toxicity compliance under SASO's 2024 technical regulation updates.
Commercial applications generate the highest shipment volumes while hospitality commands the steepest premium per square meter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows from Turkey and Iran face extended clearance timelines at Jeddah Islamic Port, while domestic production concentrates in Riyadh and Taif to serve giga-project demand. Central Region construction activity absorbs the majority of certified output, with Eastern Province retail distribution lagging established Riyadh-Jeddah corridors.
Riyadh
Diriyah Gate and Qiddiya master plans drive specification volume for palace-grade wool-silk blends and large-format commercial installations. SFDA textile safety protocols filter supplier pools through mandatory flame-resistance testing for hospitality fit-outs. King Abdullah Financial District anchors corporate procurement of solution-dyed nylon carpet tiles for 10-15 year depreciation schedules.
Eastern Province
Dammam and Khobar residential stock generates steady area rug demand without equivalent high-end retail distribution depth found in Riyadh corridors. Municipal enforcement of Saudi Building Code fire standards remains less intensive than Central Region checkpoints. Jubail industrial zone suppliers serve petrochemical sector office fit-outs with synthetic broadloom specifications.
Western Region
Jeddah's Red Sea Project corridor commissions custom production with 12-18 month timelines for luxury hospitality developments. SASO quality certification requirements at Jeddah Islamic Port extend customs clearance for Turkish and Iranian imports. Makkah hospitality infrastructure around the Holy Mosque sustains seasonal pilgrimage-driven replacement cycles.
Taif
Traditional hand-knotting expertise concentrates in this heritage weaving center, though master weaver skill scarcity constrains commission throughput. Al-Ahsa oasis settlements supplement regional craft capacity for Najdi pattern specifications. Heritage restoration projects in Diriyah mandate cultural authenticity compliance that reinforces Taif's specialized positioning.
Saudi Arabia Carpet and Rugs Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and production scale dimensions. Domestic manufacturers with in-house SFDA testing facilities absorb compliance costs faster than import-dependent distributors, creating tiered qualification barriers. Three archetypes dominate: integrated spin-to-distribution conglomerates, heritage craft specialists, and multinational scale suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as Vision 2030 timelines compress procurement cycles.
Within the heritage specialist tier, Taif Carpets anchors traditional Saudi weaving pattern expertise, while Al Sorayai Group exemplifies integrated production control from yarn spinning through finished distribution. Shaw Industries Group represents multinational scale supply for large-format commercial installations across the Kingdom. These three occupy distinct positioning vectors—craft heritage, vertical integration, and manufacturing scale—that shape competitive dynamics without direct segment overlap.
| Leading Market Players |
|---|
| Shaw Industries Group |
| Taif Carpets |
| Al Sorayai Group |
| Merinos |
| Balta Group |
| Al Abdullatif Industrial Investment Co |
| Mohawk Industries |
| Al Kaffary Group |
| Oriental Weavers |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month production timelines for palace-grade wool-silk commissions concentrate pricing power with domestic manufacturers holding certified spinning capacity, while rapid-turnover machine-made segments face margin compression from polyester-nylon substitution. This lead-time stratification splits the market into premium craft pools anchored by heritage weaving centers and volume tiers tethered to synthetic fiber import flows through Jeddah Islamic Port.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across commercial and hospitality fit-outs, with pricing stratifying across premium wool-silk blends, standard solution-dyed nylon, and economy polyester broadloom tiers. Price differentiation rests on SFDA flame-resistance certification grade and volume scale, with certified domestic suppliers commanding measurable premiums over import-dependent distributors. Cost compression in economy synthetics is intensifying because healthcare and education procurement teams prioritize stain resistance over natural fiber premiums. Healthcare procurement departments exhibit highest price sensitivity due to budget caps, while palace-grade hospitality buyers demonstrate lowest sensitivity given lifecycle costing frameworks.
Supply Chain Analysis
Container availability constraints on Turkey-Iran trade lanes into Jeddah Islamic Port are extending customs clearance timelines and elevating landed costs for synthetic fiber shipments. Geographic supply concentration draws from Turkey, Iran, and domestic Saudi production clusters around Riyadh and Taif. Raw material dependencies rest on New Zealand and Australian merino wool auctions, solution-dyed nylon polymer feedstock, and PVC-bitumen backing substrates. Single-source vulnerability runs through master weaver skill scarcity in traditional craft centers. Distribution runs through architect-specification channels, hospitality procurement consortia, and retail showroom networks across Riyadh-Jeddah corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospitality procurement consortia managing multiple simultaneous giga-project fit-outs, fragmenting supplier leverage across smaller-scale residential and healthcare accounts. This consolidation elevates qualification barriers for uncertified competitors while rewarding scale suppliers with integrated testing facilities.
For Market Incumbents: Compound certification advantages by expanding in-house SFDA testing capacity to absorb compliance costs faster than import-dependent rivals, and deepen backward integration into yarn spinning to buffer wool input volatility from Australasian auction swings. Synthetic substitution pressure from healthcare procurement teams threatens premium wool addressable market share, making captive supply of solution-dyed fiber grades a critical defensive lever. For New Entrants and Emerging Players: Differentiate on digital specification capabilities by building BIM-integrated 3D asset libraries that align with Riyadh-based architecture firms migrating material selection to AR-enabled visualization platforms. White-space targets concentrate in Eastern Province residential distribution gaps around Dammam and Khobar, and in carpet tile modular formats for commercial replacement cycles. A direct-to-designer sampling model bypasses legacy showroom-dependent specification patterns. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned heritage weaving operations in Taif and Al-Ahsa facing succession gaps, offering cultural authenticity compliance capabilities for Diriyah Gate restoration mandates. Long-term viability favors integrated spin-to-distribution platforms with certified testing infrastructure over pure import-distribution models exposed to SASO clearance friction. Watch for inflection signals in municipal enforcement intensity of Saudi Building Code fire standards across secondary cities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yarn Spinning | Captive wool and synthetic fiber supply buffers margin volatility from Australasian auction swings and polymer feedstock fluctuations. |
| SFDA Certification Investment | In-house flame-resistance testing facilities compress product-to-market cycles and filter uncertified competitors from hospitality tenders. |
| Digital Specification Platform Launch | BIM-integrated 3D asset libraries align procurement patterns with Riyadh architecture firms adopting AR-enabled visualization tools. |
| Eastern Province Distribution Expansion | Dammam and Khobar retail network buildout addresses underpenetration relative to established Riyadh-Jeddah corridors. |
| Heritage Craft Capacity Acquisition | Master weaver workshop consolidation secures Najdi pattern expertise for Diriyah Gate cultural authenticity compliance mandates. |
Research Methodology
A spread of perspectives from hospitality procurement directors, commercial fit-out contractors, heritage weaving workshop managers, and SFDA compliance officers converged on the working assumptions driving this analysis. Primary field engagement combined structured interviews with secondary validation against customs trade records, SASO technical regulation filings, Saudi Building Code enforcement bulletins, and Vision 2030 giga-project development databases. Bottom-up shipment estimates triangulated against top-down construction spend allocations across the Central Region.
Segmentation dimensions modeled include product type, material grade, design style, and end-use vertical across the projection horizon. CAGRs were derived from construction pipeline velocity, procurement cycle compression, and certification penetration curves. Industry-specific forecast inputs incorporated wool auction price banding, solution-dyed nylon technology adoption rates, and municipal enforcement intensity of fire-retardant standards.
Decision-makers should treat outputs as directional under sustained Vision 2030 construction commitment and stable Australasian wool supply; material deviation in either assumption would warrant model refresh. Specific risks that could revise trajectories include accelerated polyester-nylon substitution in institutional verticals, extended SASO laboratory testing backlogs, or master weaver attrition beyond replacement rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Decorative Rugs Market