
 US Terrazzo Market | 2026-2036
US Terrazzo Market Size, Share, and Industry Trends Forecast 2026-2036
US Terrazzo Market Intelligence
The direct sales channel between manufacturers and large architectural firms is reconfiguring supply chains for major commercial projects in the US. This shift prioritizes custom capabilities and project-specific material sourcing. Concord Terrazzo Company, Inc. specializes in precast terrazzo products for such large-scale applications. David Allen Company, Inc. leverages its reputation as a high-end installer to secure specifications in institutional markets, while RBC Industries, Inc. competes through its broad portfolio of epoxy resin systems.
Terrazzo is a composite flooring material consisting of chips of marble, quartz, granite, or glass set in a cementitious or polymeric binder. The surface is ground and polished to produce a smooth, uniformly textured finish valued for its durability and design flexibility. Epoxy terrazzo continues to gain share as a product type due to its superior performance and rapid cure times. Commercial buildings, including airports and hospitals, remain the dominant end-user segment, prioritizing the material's lifecycle cost advantages.
Environmental Protection Agency (EPA) regulations on volatile organic compounds (VOCs) influence the formulation of epoxy terrazzo systems. Concurrently, flooring specifications in public facilities must adhere to slip resistance standards outlined by the Americans with Disabilities Act (ADA). These standards directly impact material selection and surface finishing techniques. Installer skill in both resin-based and traditional cementitious methods will determine market leadership and project outcomes.
Market Dynamics
The push for sustainable building practices, particularly those aligned with LEED certification requirements, is the central force shaping the US terrazzo market. This demand from institutional and commercial sectors prioritizes materials with high recycled content, low VOC emissions, and superior lifecycle cost advantages over initial installation expenses.
Growth Catalysts
- LEED Certification Alignment:Public and commercial construction projects increasingly specify materials that contribute to LEED points, favoring terrazzo for its use of recycled aggregates and long-term durability, which reduces replacement cycles.
- Healthcare Sector Expansion:The construction of hospitals and clinics, which require seamless, non-porous, and low-maintenance flooring to meet stringent hygiene standards, provides a consistent demand stream for epoxy and cementitious terrazzo systems.
- Public Infrastructure Investment:States like Florida and Texas are channeling significant funds into public buildings, airports, and educational facilities, where terrazzo's durability and low lifecycle cost are primary specification criteria.
Market Restraints
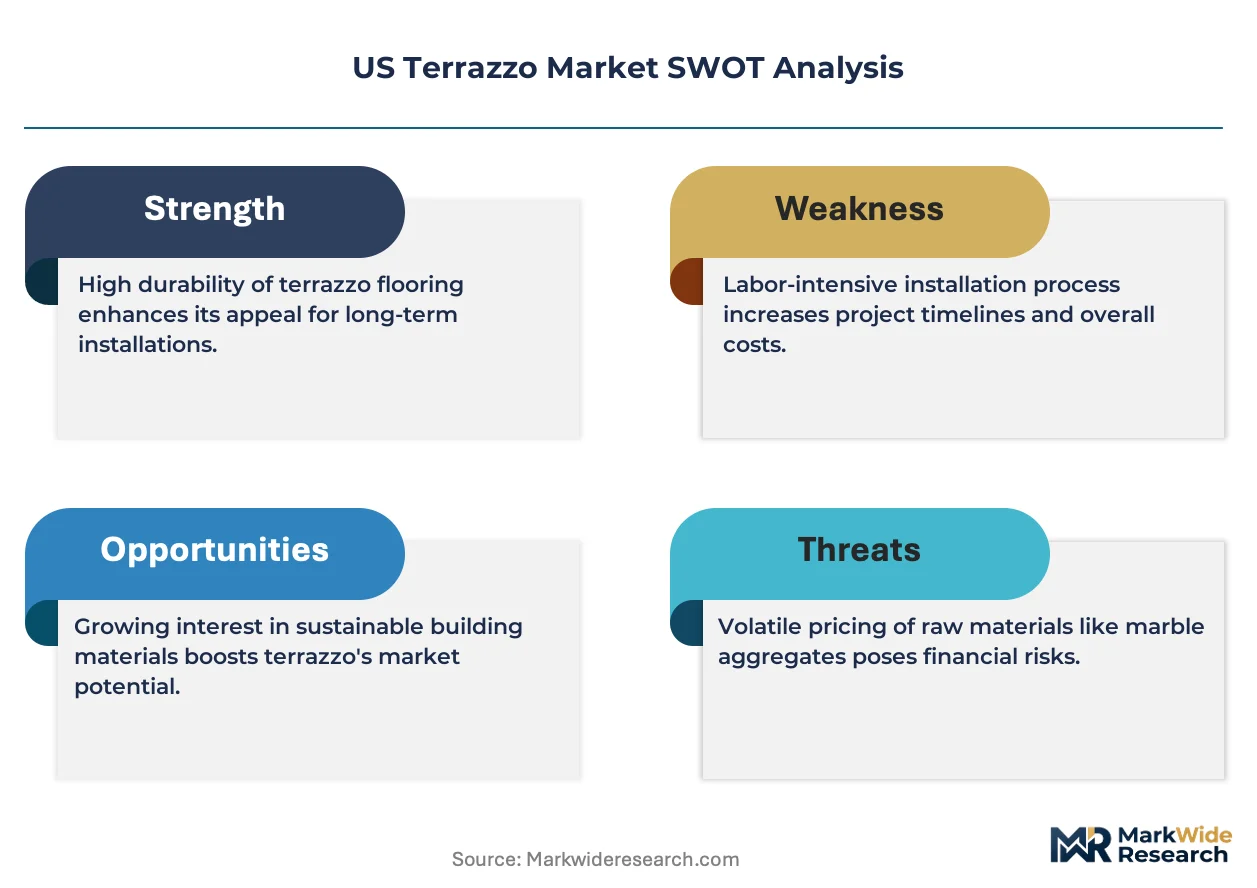
- High Upfront Installation Cost:The initial capital outlay for terrazzo installation, including extensive surface preparation and skilled labor, is substantially higher than for materials like luxury vinyl tile (LVT), deterring some budget-conscious projects.
- Installer Skill Scarcity:Achieving a high-quality, durable terrazzo finish is highly dependent on the expertise of installation crews, and a shortage of certified, experienced artisans creates project bottlenecks and quality control risks.
- Competition from Polished Concrete:Polished concrete offers a similar aesthetic and durability profile at a potentially lower cost point, presenting a direct substitute threat, especially in commercial projects where budgets are constrained.
Strategic Opportunities
- Bio-Based Epoxy Resins:Developing and marketing epoxy systems derived from renewable, bio-based sources can attract specifiers focused on maximizing sustainability metrics beyond recycled content, creating a new premium product tier.
- High-End Residential Applications:Targeting the luxury single-family and multi-family residential market with custom precast terrazzo elements like countertops and stairs represents an underpenetrated segment beyond commercial strongholds.
- Digital Design and Specification Platforms:Creating BIM-compatible digital tools and online customizer platforms allows architects to visualize and specify custom terrazzo mixes, streamlining the design-to-order process for large projects.
Industry Challenges
- Installer Training and Certification Gaps:The industry faces a persistent challenge in developing a new generation of skilled terrazzo mechanics, with a gap between the pace of market growth and the availability of formal apprenticeship programs.
- Aggregate Sourcing Volatility:Securing consistent quality and color for specific marble, glass, and granite aggregates for large-scale projects is a logistical challenge, susceptible to quarry availability and transportation cost fluctuations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Terrazzo Market |
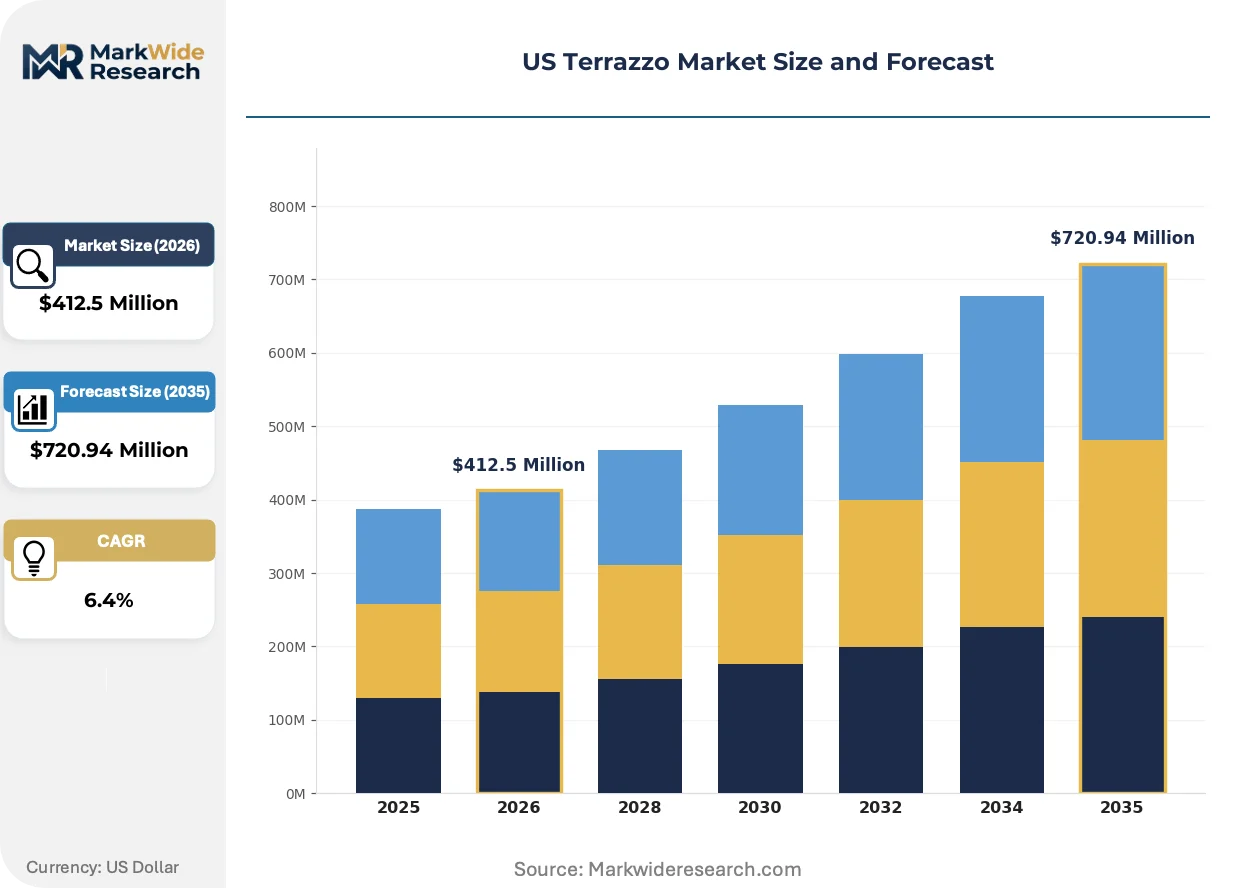
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curved Terrazzo, Precast Terrazzo, Aggregates, Epoxy Terrazzo Installation Method: Diamond Polishing, Traditional Method, Cementitious Method, Resin Method End User: Commercial Buildings, Educational Institutions, Retail Spaces, Residential Distribution Channel: Direct Sales, Online Retail, Distributors, Contractors |
| Companies Covered | RBC Industries, Inc., John Caretti & Co., Concord Terrazzo Company, Inc., General Polymers, Inc., Key Resin Company, LLC, David Allen Company, Inc., The Venice Art Terrazzo Co., Inc., TERRAZZCO, American Terrazzo Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Terrazzo Market Strategic Shifts & Innovations
Material science advancements and evolving architectural specifications are driving product development in the US terrazzo market. These shifts prioritize performance, environmental compliance, and more efficient project workflows from design through installation.
Rapid-curing epoxy resin systems are a key product evolution allowing for faster project turnarounds. Commercial end-users in renovation projects for airports and hospitals adopt these systems to minimize operational downtime. This focus on accelerated installation is rendering obsolete the multi-week curing timelines of conventional cement-based terrazzo.
Environmental Protection Agency (EPA) regulations limiting volatile organic compounds (VOCs) influence the formulation of terrazzo binders and sealers. This has forced manufacturers to develop 100% solids epoxy systems and low-VOC water-based sealants for compliance. The commercial segment, especially in states like California, now specifies low-VOC materials as a default.
A significant behavioral change involves large architectural firms engaging directly with manufacturers for major projects, bypassing traditional distribution. This disintermediation is visible in large-scale commercial work where firms seek custom precast capabilities. The result is a supply chain reconfiguration favoring manufacturers with strong in-house design and fabrication support.
US Terrazzo Market Segmentation
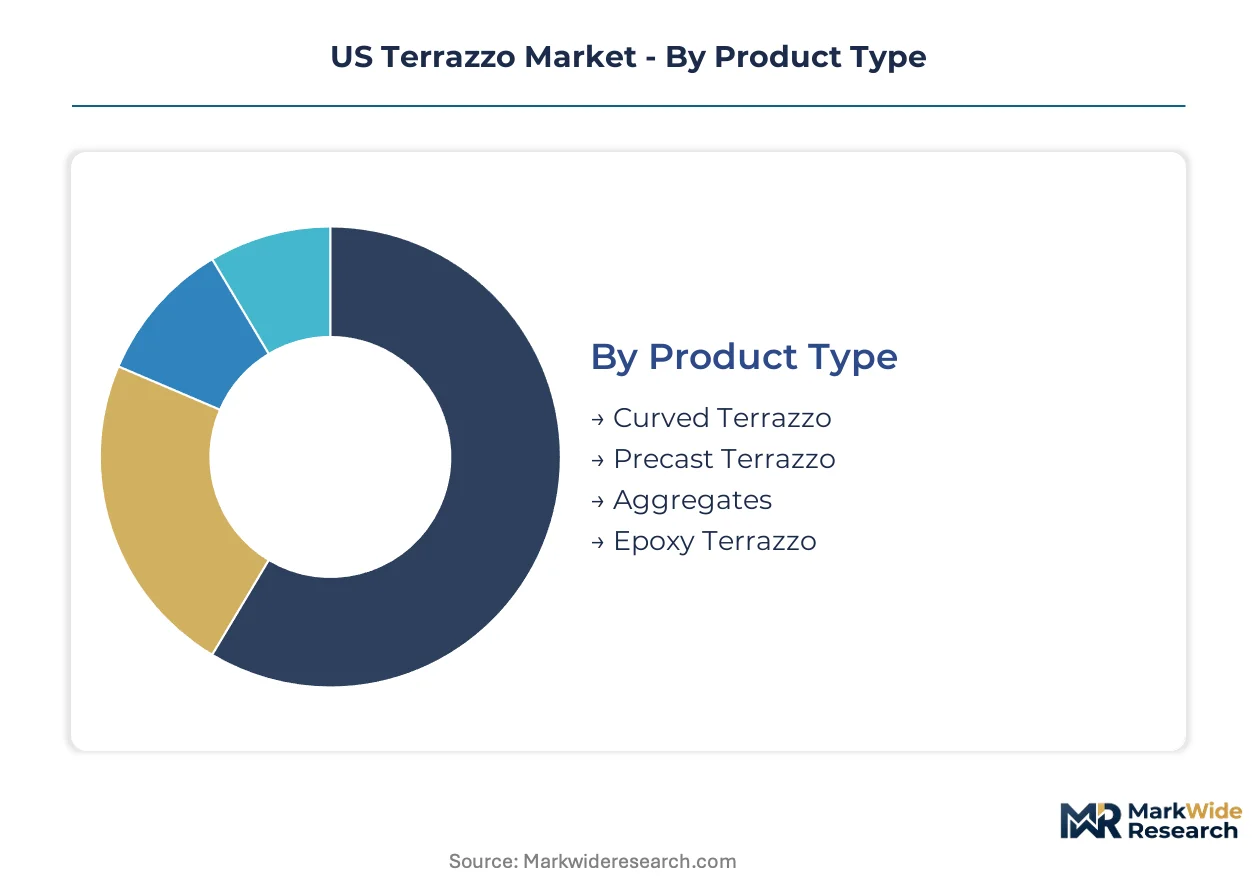
The US terrazzo market encompasses diverse product types, installation methods, end-user applications, and distribution channels. Understanding these segments clarifies where demand is concentrated and how specific material properties or application techniques drive market value. This granular view reveals distinct competitive landscapes and varying levels of project complexity across the industry.
Product Type:
The turnover rate for terrazzo products varies significantly, with raw aggregates experiencing the fastest transactional cycles due to continuous project demand, while custom precast elements often involve longer design-to-delivery timelines.
- Epoxy Terrazzo:This composite flooring uses epoxy resin binders with aggregate chips, known for its superior performance, rapid cure times, and chemical resistance. Demand in US commercial buildings, including airports and hospitals, is particularly strong due to its lifecycle cost advantages and ability to minimize operational downtime.
- Precast Terrazzo:These factory-fabricated terrazzo elements, such as stairs, countertops, and wall panels, offer custom design flexibility and consistent quality. Architectural firms increasingly specify precast products for large-scale commercial projects in the US, valuing manufacturers with robust in-house design and fabrication support.
- Aggregates:These are the crushed stone, marble, granite, or glass chips embedded in the terrazzo matrix. The consistent supply of quality aggregates is a critical logistical challenge for large US projects, susceptible to quarry availability and transportation cost fluctuations.
- Curved Terrazzo:This specialized product type allows for seamless, flowing designs in complex architectural features. Specification in high-end US residential and bespoke commercial projects values its aesthetic flexibility.
Epoxy Terrazzo dominates the installed base. Precast Terrazzo is where expansion concentrates.
Installation Method:
Installation methods differentiate projects by their technical requirements and the specific performance characteristics they deliver for various applications.
- Resin Method:This technique utilizes epoxy or other polymeric binders, allowing for thinner applications and faster cure times compared to traditional cement-based systems. Commercial renovations in US healthcare facilities and airports frequently employ resin methods to minimize disruption and expedite project completion.
- Traditional Method:This refers to cementitious terrazzo systems, often poured in place with metal divider strips, requiring extensive on-site labor and longer curing periods. Public infrastructure projects in states like Florida and Texas continue to specify traditional methods for their proven durability and historical aesthetic.
- Diamond Polishing:This finishing technique involves grinding the cured terrazzo surface with progressively finer diamond abrasives to achieve a smooth, high-gloss finish. US facilities requiring stringent hygiene standards, such as hospitals, prioritize diamond-polished surfaces for ease of cleaning and maintenance.
- Cementitious Method:This method uses Portland cement as the binder, offering robustness and suitability for exterior applications or areas with high moisture. US educational institutions often select cementitious terrazzo for its long-term resilience in high-traffic corridors.
The Resin Method is gaining share the fastest. Traditional Method holds a substantial market presence.
End User:
Customer type significantly influences material selection, with commercial clients prioritizing durability and lifecycle costs, while residential clients often seek custom aesthetic solutions.
- Commercial Buildings:This segment includes office complexes, airports, and convention centers, where terrazzo is valued for its extreme durability, low maintenance, and long lifecycle. US commercial projects prioritize materials that contribute to LEED certification and offer superior lifecycle cost advantages over initial installation expenses.
- Educational Institutions:Schools and universities specify terrazzo for its ability to withstand heavy foot traffic, resist staining, and provide a hygienic, seamless surface. Public infrastructure investments in US states like Texas are driving consistent demand for terrazzo in new school construction.
- Retail Spaces:Shopping malls and retail outlets use terrazzo for its aesthetic versatility, brand integration capabilities, and ease of cleaning in high-traffic environments. US retail renovations are increasingly adopting rapid-curing epoxy terrazzo systems to minimize store downtime.
- Residential:This segment includes luxury single-family homes and multi-family residences, primarily for custom precast elements like countertops, stairs, and shower pans. High-end US residential projects seek unique designs and bespoke material finishes.
Commercial Buildings generate the largest volume of terrazzo installations. Educational Institutions are expanding most quickly.
Distribution Channel:
The volume of material flow through distribution channels varies, with direct sales increasingly handling large, custom project volumes, while distributors manage broader product portfolios for smaller contractors.
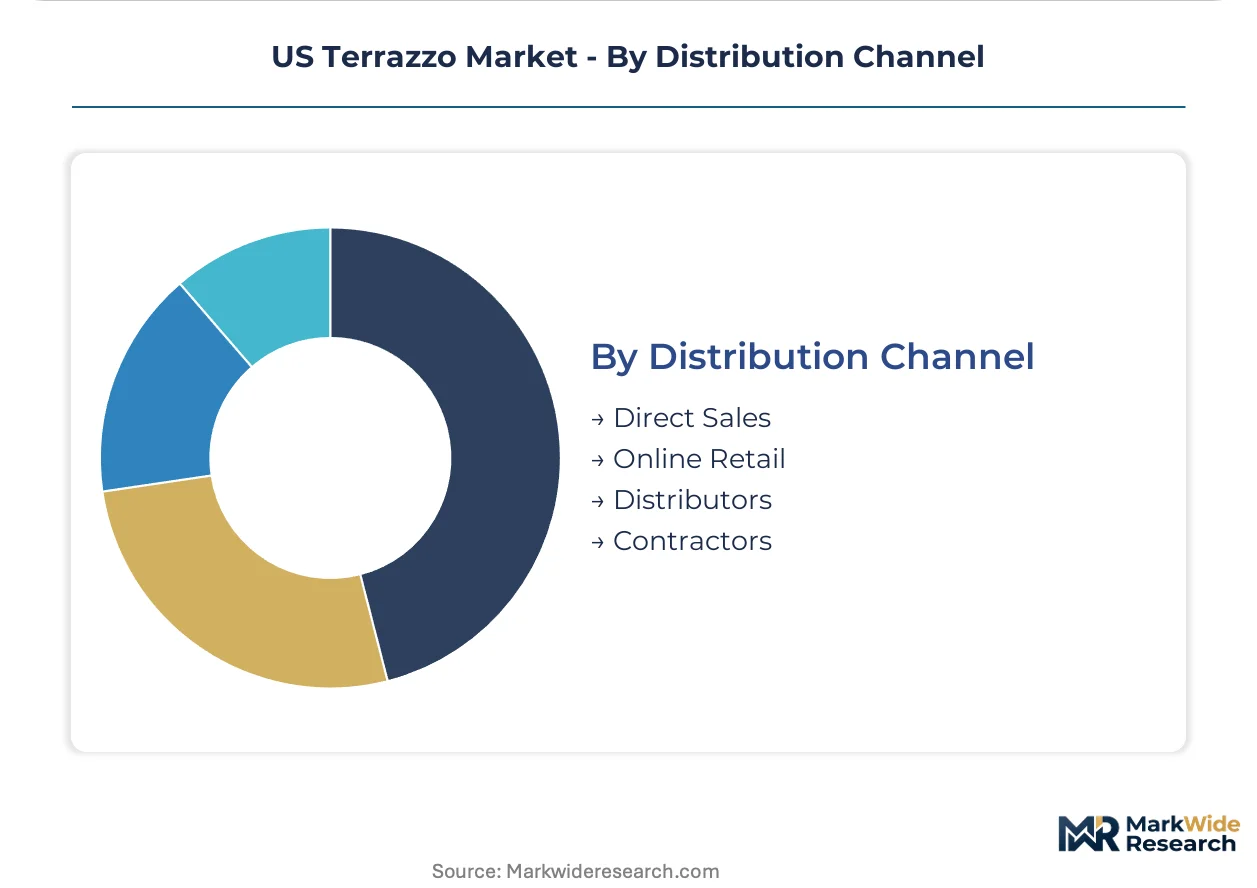
- Direct Sales:Manufacturers engage directly with large architectural firms and general contractors for major commercial and institutional projects. This channel prioritizes custom capabilities and project-specific material sourcing for US-based large-scale construction.
- Distributors:These intermediaries supply terrazzo materials, aggregates, and binders to smaller contractors and local installers. US distributors offer convenience and a broader selection of standard products for regional projects.
- Contractors:Installation contractors often procure materials directly from manufacturers or through distributors, depending on project scale and material specificity. The scarcity of skilled US terrazzo installers creates project bottlenecks and quality control risks.
- Online Retail:This channel facilitates the sale of smaller quantities of aggregates, repair kits, or specialized tools, primarily for niche applications or DIY projects. Online platforms serve a growing segment of US consumers seeking convenient access to terrazzo-related products.
Direct Sales accounts for the largest share of high-value projects. Contractors are climbing the fastest in terms of direct procurement influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for terrazzo manufacturers exhibits asymmetry, with high-growth states like Florida and Texas commanding premium rates due to robust public and commercial construction. Conversely, more mature markets in the Northeast Corridor face greater competitive pressure and established pricing benchmarks. This dynamic reflects varying levels of project pipeline and installer availability across US regions.
Florida
Demand for terrazzo in Florida stems from significant investments in educational institutions and healthcare facilities. State-level initiatives supporting public infrastructure projects align with ADA compliance for flooring specifications. The Miami metropolitan area sees consistent specification for high-durability flooring in new commercial developments and public spaces.
Texas
Public infrastructure investments drive terrazzo demand across Texas, especially for new airport terminals and university expansions. LEED certification requirements frequently influence material selection for large-scale commercial projects in the state. The Dallas-Fort Worth urban cluster demonstrates strong activity in both public and private sector construction, requiring durable flooring solutions.
California
Stringent Environmental Protection Agency (EPA) regulations regarding VOC emissions influence epoxy terrazzo formulations in California. The state's focus on sustainable building practices, often linked to LEED certification, favors materials with recycled content. Major urban centers like Los Angeles and San Francisco consistently specify terrazzo for high-traffic commercial spaces, including airports.
Northeast Corridor
Renovation projects in established educational and healthcare facilities fuel terrazzo demand throughout the Northeast Corridor. Adherence to ADA slip resistance standards is a critical factor for flooring specifications in public buildings. The Boston-New York-Washington D.C. megalopolis features numerous historical restoration projects and new institutional builds, emphasizing long-term material value.
US Terrazzo Market Key Industry Players
Specialized fabricators and installation specialists split the US terrazzo market, reflecting a bifurcated competitive landscape. The market exhibits a tiered structure, with a few larger players offering comprehensive solutions and numerous smaller, regional installers. Strategic archetypes include manufacturers focusing on custom precast elements and firms emphasizing high-end installation services or broad material portfolios for resin systems. Competitive moves center on establishing direct sales channels with architectural firms and expanding custom fabrication capabilities for complex projects.
Within the specialized fabrication tier, Concord Terrazzo Company, Inc. exemplifies a manufacturer focusing on precast terrazzo products for large-scale applications, often through direct engagement with architectural firms. David Allen Company, Inc. occupies a position as a high-end installer, leveraging its reputation to secure specifications in institutional markets requiring meticulous execution. RBC Industries, Inc. represents a material provider, competing through its broad portfolio of epoxy resin systems for diverse commercial and public projects. These entities demonstrate varied approaches to securing project involvement and market share across the US.
| Leading Market Players |
|---|
| RBC Industries, Inc. |
| John Caretti & Co. |
| Concord Terrazzo Company, Inc. |
| General Polymers, Inc. |
| Key Resin Company, LLC |
| David Allen Company, Inc. |
| The Venice Art Terrazzo Co., Inc. |
| TERRAZZCO |
| American Terrazzo Company |
| Others |
Cost & Logistics Intelligence
Aggregate sourcing volatility, particularly for specialized marble and glass chips, directly influences margin pools for custom precast terrazzo manufacturers and large-scale project installers in the US.
Pricing Analysis
Configured-to-order terrazzo elements command a premium over standard material specifications, reflecting design complexity and custom aggregate blends. The dominant pricing model remains project-based, negotiated through contracts for large commercial and institutional undertakings. Price differentiation stems from the customization level and the specific aggregate types used, such as rare marbles or recycled glass. Pricing softness emerges from the competition with polished concrete, especially in budget-conscious commercial projects. Commercial buildings, prioritizing lifecycle cost advantages, demonstrate lower price sensitivity compared to projects with strict upfront budget constraints.
Supply Chain Analysis
Specialized precast fabricators, such as Concord Terrazzo Company, hold significant capacity for custom elements, influencing material flow for large US projects. Raw material dependencies center on marble, quartz, granite, and glass chips, along with epoxy resin systems. A structural risk involves aggregate sourcing volatility, susceptible to quarry availability and transportation cost fluctuations for specific colors and sizes. Distribution runs through direct sales channels to large architectural firms for major projects and through distributors for smaller contractors and regional installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US terrazzo market is experiencing a cyclical recovery, driven by sustained public infrastructure investment in educational and healthcare facilities.
For Market Incumbents: Harden core competencies in skilled labor and rapid-curing epoxy systems to counter the competitive threat from polished concrete. Invest in advanced installer training and certification programs to mitigate skill scarcity across the US. Deepen direct sales relationships with major architectural firms, leveraging custom fabrication capabilities for complex project specifications. Expand internal R&D for low-VOC and bio-based resin formulations to meet evolving EPA regulations.
For New Entrants and Emerging Players: Build out niche capabilities in bio-based epoxy resins and digital design platforms to penetrate the US luxury residential market. Target underpenetrated segments like custom precast elements for high-end homes and specialized renovation projects. A go-to-market angle involves offering BIM-compatible design tools that streamline specification for architects and designers. Focus on rapid-curing systems for smaller commercial renovations to minimize operational downtime.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized precast manufacturers with strong in-house design capabilities and proprietary low-VOC resin formulations. Long-term viability hinges on the continued push for sustainable building practices and lifecycle cost advantages in public and commercial construction. Acquire firms with established direct sales channels to architectural firms or those developing advanced installer training academies. A signal to watch is the adoption rate of bio-based epoxy resins in LEED-certified projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Custom Precast Capacity | Increases ability to meet demand for bespoke architectural elements in US commercial projects. |
| Invest in Bio-Based Epoxy R&D | Aligns with LEED certification and EPA regulations, attracting environmentally conscious specifiers in California. |
| Develop Digital Design Platforms | Streamlines specification for architectural firms, accelerating custom project workflows in Texas. |
| Establish Installer Training Programs | Addresses the critical scarcity of skilled labor, improving project outcomes and quality control across the Northeast Corridor. |
| Secure Long-Term Aggregate Contracts | Mitigates sourcing volatility for critical raw materials, ensuring consistent supply for large-scale US projects. |
Research Approach
The analysis maps terrazzo product types and end-user applications, each validated through primary interviews with architectural firm principals, general contractors, and material manufacturers. Secondary validation utilized EPA regulations, ADA standards, construction project databases, and LEED project registries. The approach combined bottom-up market sizing with top-down validation to ensure comprehensive coverage of the US market.
The assumption set held fixed stable regulatory environments and consistent construction spending across the analysis window, while varying material costs and labor availability. The analytical framework projected demand across product type, installation method, end-user, distribution channel, and regional market segments. CAGRs were derived from historical growth trends and projected construction activity, with key inputs including public infrastructure budgets and commercial construction starts.
Stress conditions across economic downturns and significant shifts in building codes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding material science advancements and sustained demand for durable flooring solutions. Quarterly review of public construction spending and material price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market