
 A2 Lactose-free Milk Market | 2026-2036
A2 Lactose-free Milk Market Size, Share, and Industry Trends Forecast 2026-2036
A2 Lactose-free Milk Market Insights
Consolidation among health-conscious adult buyers and simultaneous fragmentation across infant nutrition purchasers is restructuring procurement patterns across the A2 lactose-free milk value chain. The a2 Milk Company dominates proprietary A2 protein sourcing and brand recognition in premium channels. Fonterra anchors large-scale dairy processing infrastructure across Oceania. Nestlé competes through specialized infant nutrition formulations that incorporate A2 lactose-free bases.
A2 lactose-free milk denotes dairy from cows selectively bred to produce only the A2 beta-casein protein variant, with lactose enzymatically broken into glucose and galactose via lactase treatment to achieve sub-0.01% residual lactose content suitable for malabsorption-sensitive consumers. UHT milk extends shelf stability and unlocks distribution into convenience stores and pharmacies lacking cold-chain capacity. Fresh milk commands premium positioning in supermarkets and specialty stores where perishability signals quality. Online retailers represent the fastest-growing distribution channel as subscription models capture recurring household purchases.
FDA dairy identity standards and USDA organic certification requirements govern product labeling and market access in the United States, while EFSA nutrition and health claims regulations shape permissible digestive benefit statements across European markets. FSANZ food standards in Australia enforce A2 protein provenance verification and lactose threshold testing protocols that manufacturers must satisfy for retail placement. Stakeholders should monitor evolving enzymatic processing patents and regional labeling precedents that will determine which formulations achieve preferred retail positioning without triggering medicinal classification.
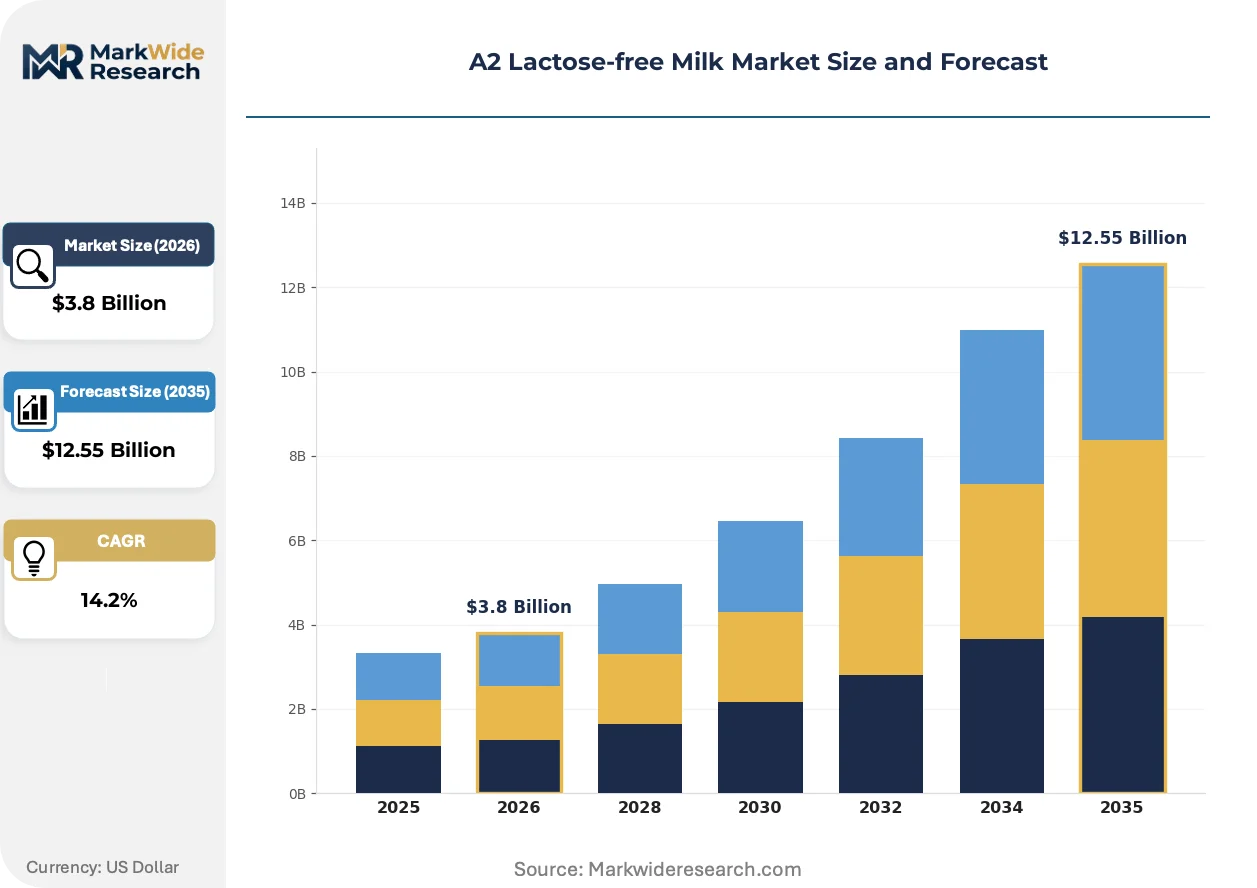
Market Dynamics
Enzymatic hydrolysis patents and A2 protein sourcing infrastructure are concentrating competitive advantage among processors with captive dairy herds and in-house lactase capabilities. This technical moat is reshaping who can enter premium retail channels.
Growth Catalysts
- FDA Dairy Identity Standards:Updated labeling requirements in the United States clarify A2 protein and lactose-free claims, reducing consumer confusion and accelerating retail placement for compliant products.
- Adult Digestive Sensitivity Cohort:Health-conscious consumers over 35 with self-diagnosed lactose intolerance are migrating from plant-based alternatives back to animal dairy with verified A2 beta-casein provenance.
- Enzymatic Hydrolysis:Advances in lactase immobilization and continuous-flow processing are reducing residual lactose variance below 0.01% thresholds while preserving flavor profiles.
Market Restraints
- A2 Herd Conversion Costs:Dairy farmers face 18-24 month genetic testing and breeding cycles to establish A2-only milking populations, constraining raw material scalability.
- Australian Supply Concentration:Proprietary A2 protein verification infrastructure and consumer education density in Australia create geographic dependency for premium positioning.
- Plant-Based Substitution:Oat and almond milk variants with comparable price points and improved barista functionality capture price-sensitive households.
Strategic Opportunities
- Subscription Direct-to-Consumer:Recurring delivery models bypass traditional retail slotting fees and capture lifetime value from households with chronic digestive conditions.
- Infant Nutrition Formulations:Pediatric applications with A2 lactose-free bases address parental concerns about protein digestibility during early development.
- FSANZ Export Harmonization:Australian verification protocols are being adopted by regulators in Southeast Asian markets, opening channel access for pre-certified producers.
Industry Challenges
- A2 Genetic Certification Timeline:Third-party beta-casein testing and herd registry maintenance impose recurring compliance burdens on upstream suppliers.
- Cold-Chain Integration Complexity:Fresh milk variants require refrigerated logistics coordination with retailers whose pharmacy and convenience store footprints lack consistent temperature control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2 Lactose-free Milk Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Milk, UHT Milk, Flavored Milk, Organic Milk, Pasteurized Milk Packaging Type: Carton, Bottle, Pouch, Tetra Pak, Glass Bottle End User: Infants, Adults, Athletes, Elderly, Pregnant Women Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Pharmacies, Convenience Stores |
| Companies Covered | The a2 Milk Company, Fonterra, Horizon Organic, Shunya Farms, Provilac Dairy Farms Private Limited, Vinamilk, GCMMF, Freedom Foods Group, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2 Lactose-free Milk Market Trends and Innovations
Processing technology convergence and regulatory labeling precision are compressing the gap between specialty dairy and mass-market accessibility. These forces are redefining who controls value capture in the A2 lactose-free segment.
Continuous-flow enzymatic hydrolysis with immobilized lactase enzymes is unifying flavor stability and shelf-life extension in UHT formats. Adult consumers with recurring digestive sensitivity are adopting these products for workplace and travel consumption. This unification is compressing the premium that fresh milk traditionally commanded over extended-shelf-life alternatives.
FSANZ food standards enforcement in Australia mandates A2 protein provenance verification and sub-0.01% lactose threshold testing for retail placement. Manufacturers must maintain dual certification streams for domestic and export markets. Infant nutrition brands are responding by segregating production lines to prevent cross-contamination with standard dairy processing.
Household purchasing is migrating toward subscription-based replenishment models through online retailers and direct brand platforms. Supermarket dairy case slotting fees and perishability-driven waste are losing their historical lock on volume distribution. This behavioral pivot is most visible in Australian metropolitan markets where A2 protein awareness enables premium pricing acceptance without physical shelf presence.
A2 Lactose-free Milk Market Segmentation
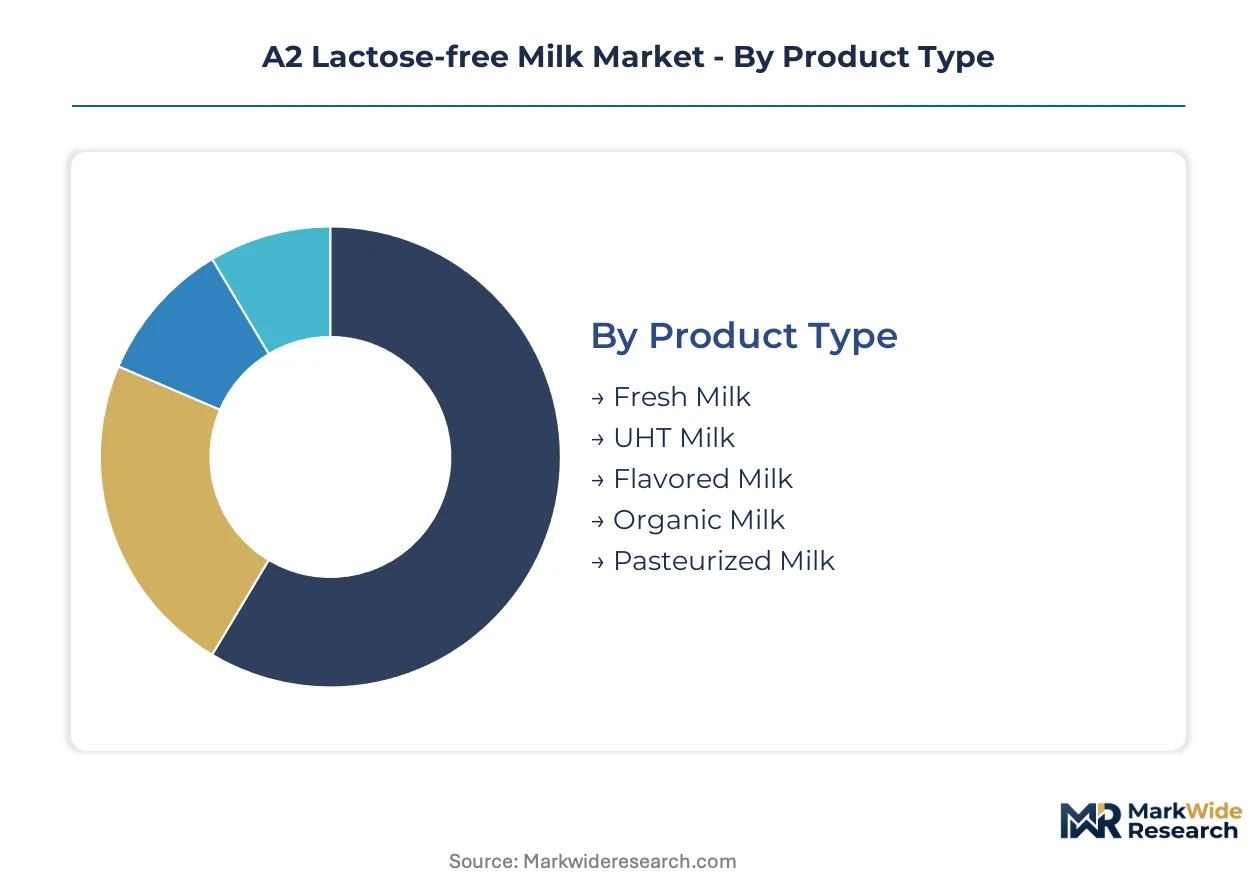
A2 lactose-free milk segmentation reflects divergent buyer priorities across perishability tolerance, packaging sustainability preferences, and chronic condition management needs. Manufacturers configure production lines and certification protocols around these fracture lines to capture premium positioning without cross-contamination risks.
Product Type:
Perishability tolerance and usage occasion determine which A2 lactose-free format commands household replenishment frequency.
- UHT Milk:Extended shelf stability through ultra-high temperature processing enables ambient distribution into pharmacy and convenience channels lacking refrigeration. Australian metropolitan households with travel-intensive lifestyles drive recurring bulk purchases of single-serve UHT formats for workplace consumption.
- Fresh Milk:Cold-chain dependent product with sub-21-day shelf life signals quality through perishability in supermarket dairy cases. Health-conscious adult consumers over 35 with self-diagnosed lactose intolerance in Australian capital cities pay premium multiples for refrigerated A2 lactose-free fresh milk with verified beta-casein provenance.
- Flavored Milk:Cocoa and vanilla variants mask residual enzymatic notes from lactase hydrolysis, expanding acceptance among pediatric users.
- Organic Milk:Dual certification with USDA organic standards restricts sourcing to A2 herds raised without synthetic inputs, constraining supply scalability.
- Pasteurized Milk:Intermediate shelf life between fresh and UHT formats serves regional dairy processors with limited aseptic packaging infrastructure.
Volume sits with UHT formats; growth tilts toward fresh milk in premium Australian metropolitan channels.
Packaging Type:
Material cost tiers and retail channel requirements segment packaging selection across mass-market and specialty positioning.
- Tetra Pak:Aseptic carton technology enables ambient distribution with 6-12 month shelf stability, critical for pharmacy and convenience store penetration where cold-chain infrastructure is inconsistent. Australian A2 lactose-free brands leverage Tetra Pak's rectangular format efficiency for direct-to-consumer subscription shipping.
- Carton:Gable-top refrigerated cartons dominate supermarket dairy case placement for fresh milk variants, with per-unit material costs below bottle alternatives. Specialty stores in Australian urban centers specify cartons with A2 protein verification printing to signal digestive benefit claims at point of purchase.
- Bottle:HDPE and PET formats support resealable consumption across multi-day household use.
- Pouch:Flexible film reduces shipping cube and material weight for e-commerce fulfillment.
- Glass Bottle:Returnable deposit systems in select Australian regions serve premium positioning with sustainability signaling.
Mass-market penetration clusters with Tetra Pak; premium differentiation favors glass and specialized carton formats.
End User:
Physiological sensitivity severity and nutritional requirement intensity determine formulation specificity and pricing acceptance.
- Adults:Consumers over 35 with self-diagnosed lactose intolerance and irritable bowel sensitivity represent the expanding addressable base, migrating from oat and almond alternatives back to animal dairy with verified A2 beta-casein. Australian consumer education density enables premium pricing without clinical prescription requirements.
- Infants:Pediatric nutrition applications demand segregated production lines and FSANZ-compliant A2 protein verification to prevent cross-contamination with standard dairy processing. Parental concern about protein digestibility during early development drives formulation premiums in specialty pharmacy channels.
- Athletes:Post-workout recovery positioning with rapid gastric emptying claims targets performance nutrition segments.
- Elderly:Calcium absorption and digestive comfort marketing addresses aged-care facility procurement.
- Pregnant Women:Fetal development nutrition positioning requires obstetric channel endorsement.
Household expenditure concentrates with adult users; pediatric applications command the steepest per-liter pricing premiums.
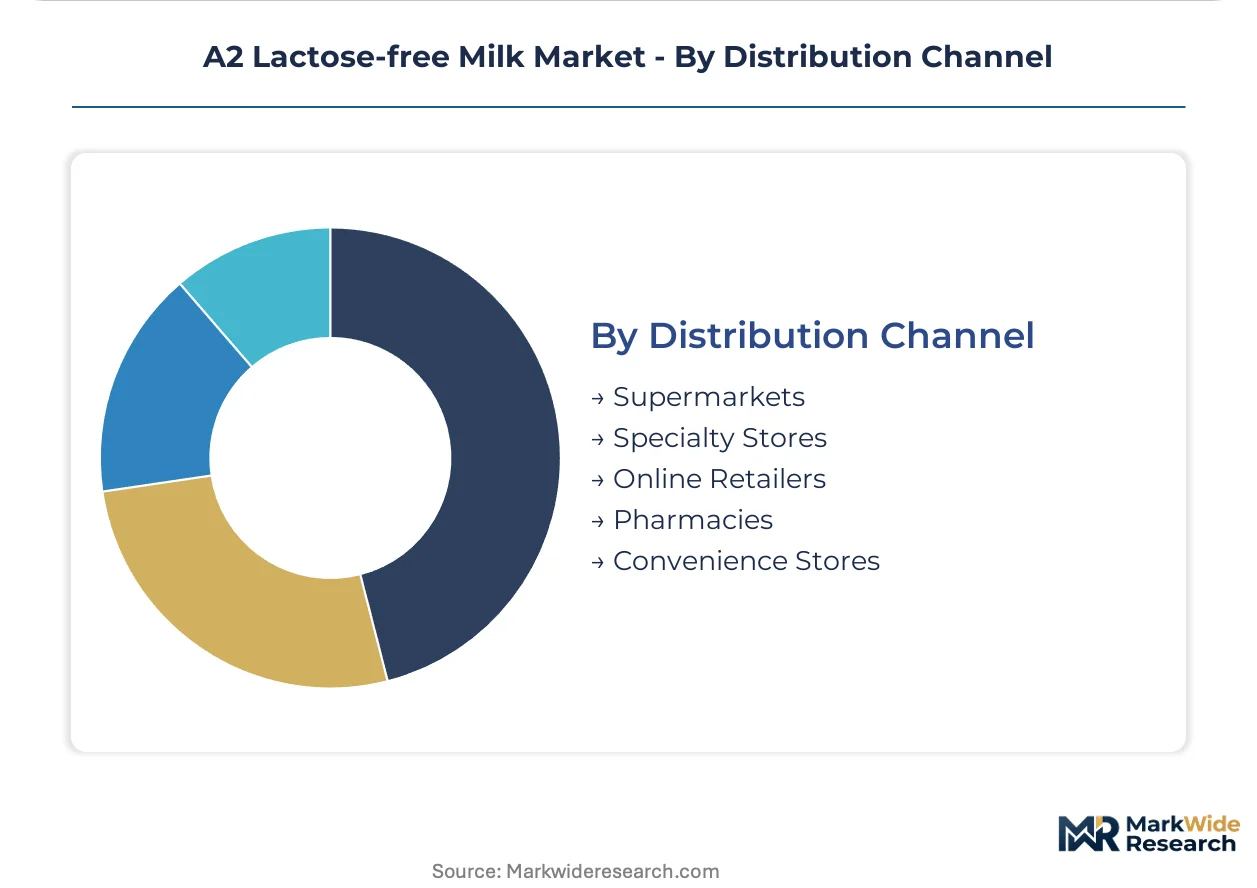
Distribution Channel:
Physical shelf presence versus digital replenishment models restructure margin capture and customer lifetime value economics.
- Online Retailers:Subscription-based replenishment bypasses supermarket slotting fees and captures recurring revenue from households managing chronic digestive conditions. Australian metropolitan markets with established A2 protein awareness show highest conversion rates for direct brand platform subscriptions.
- Supermarkets:Refrigerated dairy case placement commands slotting fees and perishability-driven waste risk, but remains essential for trial purchase and brand visibility. Major Australian chains require FSANZ verification documentation for A2 protein and lactose-free claim authorization.
- Specialty Stores:Health food and organic retailers provide educated staff consultation for digestive sensitivity positioning.
- Pharmacies:Clinical channel access requires medicinal-adjacent classification avoidance through careful labeling compliance.
- Convenience Stores:Ambient UHT placement targets immediate consumption and travel occasions.
Transaction volume flows through supermarkets; customer lifetime value expansion tilts toward online subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in Australia, where A2 protein sourcing infrastructure and consumer education density enable premium positioning without clinical prescription requirements. Adult consumers with self-diagnosed lactose intolerance in metropolitan markets drive recurring household expenditure. Regulatory verification protocols established by FSANZ are now propagating into adjacent Asia-Pacific markets.
Australia
Health-conscious adults over 35 with digestive sensitivity concerns represent the fastest-expanding end-use cohort, migrating from plant-based alternatives back to verified A2 beta-casein dairy. FSANZ food standards enforce A2 protein provenance verification and sub-0.01% lactose threshold testing for retail placement. Sydney and Melbourne metropolitan clusters show highest conversion rates for subscription-based direct-to-consumer replenishment models.
United States
FDA dairy identity standards updated in recent years clarify A2 protein and lactose-free claims, reducing consumer confusion and accelerating retail placement for compliant formulations. The FDA and USDA jointly govern organic certification requirements that constrain dual-certified A2 organic supply scalability. California's Central Valley dairy belt anchors domestic A2 herd conversion efforts, though 18-24 month genetic testing cycles constrain raw material expansion.
China
Parental concern about protein digestibility during early development drives pediatric nutrition applications with A2 lactose-free bases. SAMR and national food safety standards govern dairy import requirements and domestic production licensing. Shanghai and Beijing metropolitan markets concentrate demand for premium imported A2 formulations, with cross-border e-commerce channels capturing recurring household purchases.
United Kingdom
Health-conscious adult consumers with irritable bowel sensitivity are adopting A2 lactose-free variants as workplace and travel consumption options. EFSA nutrition and health claims regulations shape permissible digestive benefit statements across European markets. London and Southeast England retail clusters require careful labeling compliance to avoid medicinal-adjacent classification in pharmacy channels.
Germany
Performance nutrition segments targeting post-workout recovery with rapid gastric emptying claims are expanding A2 lactose-free adoption among athletic consumers. EFSA and national food safety authorities enforce strict health claim substantiation requirements. Bavaria's dairy processing infrastructure supports regional A2 protein sourcing, though herd conversion timelines lag Australian scale.
A2 Lactose-free Milk Market Competitive Landscape
Australian producers anchor the premium-tier with proprietary A2 protein verification infrastructure; New Zealand specialists hold large-scale dairy processing capacity across Oceania. The competitive structure concentrates around three strategic archetypes: A2 genetic certification specialists with captive herd control, enzymatic hydrolysis processors with in-house lactase capabilities, and diversified dairy multinationals with segregated infant nutrition production lines. Dominant competitive moves include backward integration into A2 herd genetics and strategic partnerships with subscription platform operators.
Within the A2 genetic certification tier, The a2 Milk Company exemplifies proprietary protein sourcing and brand recognition in premium channels. Fonterra anchors large-scale dairy processing infrastructure with Oceania-wide distribution reach. Nestlé occupies a position exemplifying diversified infant nutrition specialists incorporating A2 lactose-free bases into pediatric formulations.
| Leading Market Players |
|---|
| The a2 Milk Company |
| Fonterra |
| Horizon Organic |
| Shunya Farms |
| Provilac Dairy Farms Private Limited |
| Vinamilk |
| GCMMF |
| Freedom Foods Group |
| Nestlé |
| Others |
Pricing and Supply Chain Analysis
FSANZ A2 protein provenance verification mandates gate both qualified supply access and premium-tier pricing authorization in Australian retail channels. These dual certification requirements concentrate pricing power among processors with in-house lactase capabilities and captive A2 herd genetics, while excluding commodity dairy operators from premium positioning.
Pricing Analysis
Volume concentration in UHT formats competes against margin capture in fresh milk and infant nutrition segments. Pricing stratifies across premium, standard, and economy tiers based on A2 genetic certification grade and cold-chain delivery infrastructure. Cost compression in standard UHT tiers intensifies because oat and almond milk alternatives capture price-sensitive households. Adult digestive sensitivity consumers over 35 in Australian metropolitan markets show least price sensitivity, while convenience-store UHT purchasers exhibit highest elasticity.
Supply Chain Analysis
Cold-chain freight costs and ambient distribution logistics split procurement economics between fresh and UHT formats. Raw material sourcing draws from Australia, New Zealand, and California's Central Valley dairy belt, with enzymatic hydrolysis inputs resting on immobilized lactase supply from specialized biotech processors. Single-source vulnerability in A2 genetic testing infrastructure creates herd conversion bottlenecks. Distribution runs through supermarket dairy cases for trial purchases and direct-to-consumer subscription platforms for recurring household replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
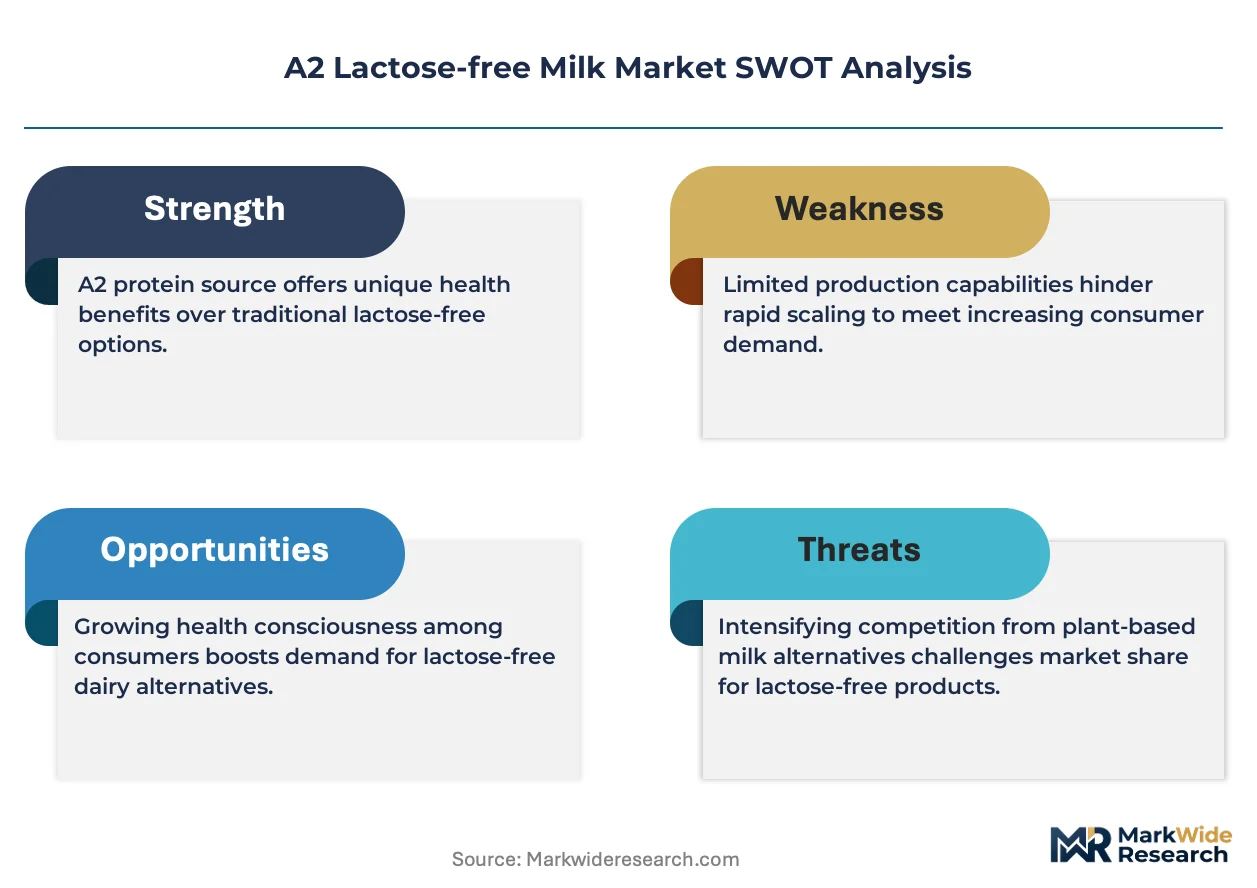
The A2 lactose-free milk market functions as a vertical-integration race where proprietary A2 herd genetics and in-house lactase processing capabilities determine who captures premium-tier margins. Players are pursuing backward integration into captive dairy herds as the decisive upstream lever.
For Market Incumbents: Anchor premium positioning through exclusive A2 genetic certification partnerships with Australian dairy cooperatives, locking in raw material scarcity against plant-based substitution threats. Expand enzymatic hydrolysis capacity in-house to preserve flavor stability margins and prevent technology licensing dependency. For New Entrants and Emerging Players: Capture white-space in Southeast Asian pharmacy channels where FSANZ export harmonization protocols are opening pre-certified access for Australian-verified producers. Pediatric nutrition formulations with segregated production lines offer the most penetrable segment, with direct-to-consumer subscription models providing the lowest customer acquisition friction. For Investors and Strategic Acquirers: FDA dairy identity standard clarifications are the leading indicator that US retail placement acceleration will favor early-compliant processors with established A2 protein verification infrastructure. Long-term viability over the projection horizon hinges on proprietary genetic certification assets rather than commodity processing scale. Acquisition targets should display dual FSANZ verification and enzymatic hydrolysis patent portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into A2 Herd Genetics | Captures raw material scarcity premium and locks out commodity dairy competitors from FSANZ-compliant supply. |
| In-House Enzymatic Hydrolysis Investment | Preserves flavor stability margins and eliminates technology licensing costs for sub-0.01% lactose thresholds. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and captures lifetime value from chronic digestive condition households. |
| FSANZ Export Harmonization Certification | Opens pharmacy channel access in Southeast Asian markets adopting Australian verification protocols. |
| Segregated Infant Nutrition Production Lines | Prevents cross-contamination risks and commands steepest per-liter pricing premiums in pediatric applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted with dairy processing executives, A2 herd genetics specialists, enzymatic hydrolysis technology providers, supermarket category buyers, and FSANZ compliance officers. FDA dairy identity standards, EFSA nutrition claims registers, and FSANZ food standards documentation provided regulatory boundary conditions. Bottom-up volume modeling triangulated against top-down expenditure estimates across consumer segments.
Product type, packaging format, end-user physiological sensitivity severity, and distribution channel economics were modeled at segment-level granularity across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated A2 herd conversion timelines, enzymatic processing patent expirations, and subscription platform penetration rates by metropolitan market density.
The model holds under stable FSANZ verification enforcement and FDA labeling clarity; deviation in plant-based milk functionality improvements or A2 genetic testing cost collapses would shift volume projections. Forecasts reflect documented assumptions about consumer education density and cold-chain infrastructure expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Non-Dairy Ice Cream Market