
 Oat Drinks Market | 2026-2036
Oat Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Drinks Market Analysis
Enzymatic hydrolysis and lipid optimization technology is tilting oat drink production toward creamier mouthfeel profiles that rival dairy in espresso applications. Oatly Group AB leverages its proprietary enzymatic process and early foodservice partnerships to sustain premium positioning in café channels. Danone S.A. anchors European retail shelf space through Alpro's established distribution infrastructure. Califia Farms competes on barista-specific formulations with extended foaming stability.
Oat drinks are aqueous suspensions of hydrolyzed oat starch and beta-glucan fiber, typically processed through enzymatic liquefaction and homogenization to achieve particle sizes below 5 microns for colloidal stability and sensory neutrality in hot and cold beverages. Barista-grade formulations command disproportionate margin pools due to higher fat emulsion requirements and certified performance standards in professional coffee equipment. Original and unsweetened variants dominate volume, while chocolate and fortified segments capture premium pricing through added mineral and vitamin positioning.
The European Food Safety Authority and FDA govern allergen labeling and nutrient content claims, while EU REACH and F-Gas Regulation indirectly shape sustainable processing equipment investments. These frameworks compel manufacturers to substantiate protein claims and document supply chain deforestation risks. Stakeholders must monitor evolving plant-based dairy terminology restrictions and carbon labeling mandates that will determine market access and consumer communication strategies.
Market Dynamics
Enzymatic hydrolysis technology is compressing production timelines while elevating mouthfeel standards, forcing capital retooling across mid-scale manufacturers who previously relied on conventional milling approaches.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sustainability disclosures and carbon footprint thresholds are accelerating clean-label formulation investments among European processors.
- Specialty coffee channel penetration:Café chains in Germany, the United Kingdom, and the United States now specify oat milk as default dairy alternatives, creating pull-through demand for barista-grade formulations.
- Beta-glucan fiber positioning:Functional health claims tied to cholesterol management are expanding oat drinks into clinical nutrition and wellness retail segments.
Market Restraints
- Raw oat supply concentration:Premium milling-grade oats concentrate in Nordic and Baltic growing regions, exposing processors to weather-driven input volatility.
- Enzyme cost structure:Proprietary amylase and lipase formulations required for premium mouthfeel carry 3-4x cost premiums over commodity alternatives.
- EU plant-based labeling restrictions:Pending terminology limitations on "milk" and "dairy" descriptors create compliance friction for cross-border marketing.
Strategic Opportunities
- Fortified pediatric and senior nutrition:Mineral and vitamin enrichment protocols developed for Nordic welfare systems are transplantable to North American clinical channels.
- Extended-shelf-stable UHT formats:Aseptic packaging convergence with enzymatic stabilization enables ambient distribution in Southeast Asian convenience retail.
- US Inflation Reduction Act biofuel credits:Oat starch byproduct streams qualify for renewable fuel incentives, improving coproduct economics for integrated processors.
Industry Challenges
- Colloidal stability certification:Professional coffee equipment manufacturers impose proprietary foam-retention standards that require 12-18 month validation cycles.
- Enzyme engineering talent scarcity:Food biochemists with lipid optimization expertise command premium compensation in competing pharmaceutical sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Drinks Market |
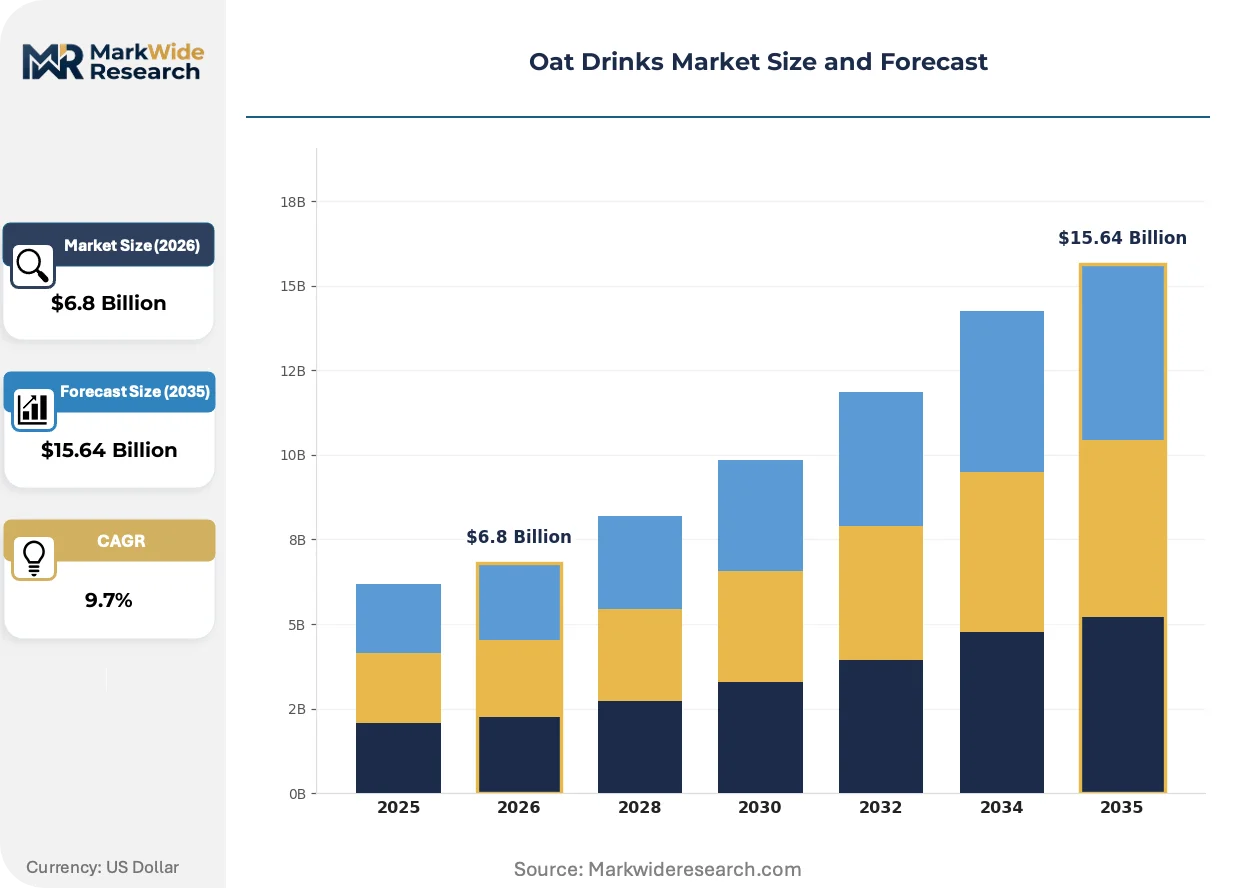
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Original, Chocolate, Vanilla, Barista Formulation: Sweetened, Unsweetened, Flavored, Fortified Packaging Type: Carton, Bottle, Tetra Pak, Can Distribution Channel: Supermarkets, Health Stores, Online Retailers, Specialty Stores |
| Companies Covered | Oatly Group AB, Danone S.A., Califia Farms, Campbell Soup Company, Chobani LLC, HP Hood LLC, The Hain Celestial Group Inc., Pacific Foods of Oregon LLC, Alpro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Drinks Market Emerging Trajectories
Formulation science and packaging engineering are converging to extend oat drinks beyond beverage applications into cooking, baking, and frozen dessert categories previously dominated by dairy analogues.
High-pressure processing combined with microfiltration is hybridizing traditional thermal pasteurization approaches. Equipment suppliers in Denmark and the Netherlands report 40% capacity expansion orders from oat-dedicated facilities. This hybridization is compressing the quality gap between refrigerated and shelf-stable formats, enabling single-SKU distribution strategies.
EU REACH chemical registration requirements and F-Gas Regulation phase-down schedules are compelling processor investments in CO2-based refrigeration and closed-loop solvent recovery. Manufacturers in Sweden and Finland now document supply chain deforestation risks through EUDR-aligned traceability platforms. Barista-grade production lines face the steepest compliance cost escalation due to clean-in-place chemical intensity.
Direct-to-foodservice procurement bypasses traditional retail brokerage in major metropolitan markets. Roasters in Melbourne, Portland, and Copenhagen now contract directly with oat drink processors for custom fat-content formulations. This disintermediation concentrates volume with vertically integrated suppliers who control enzymatic IP and regional milling assets.
Oat Drinks Market Segmentation
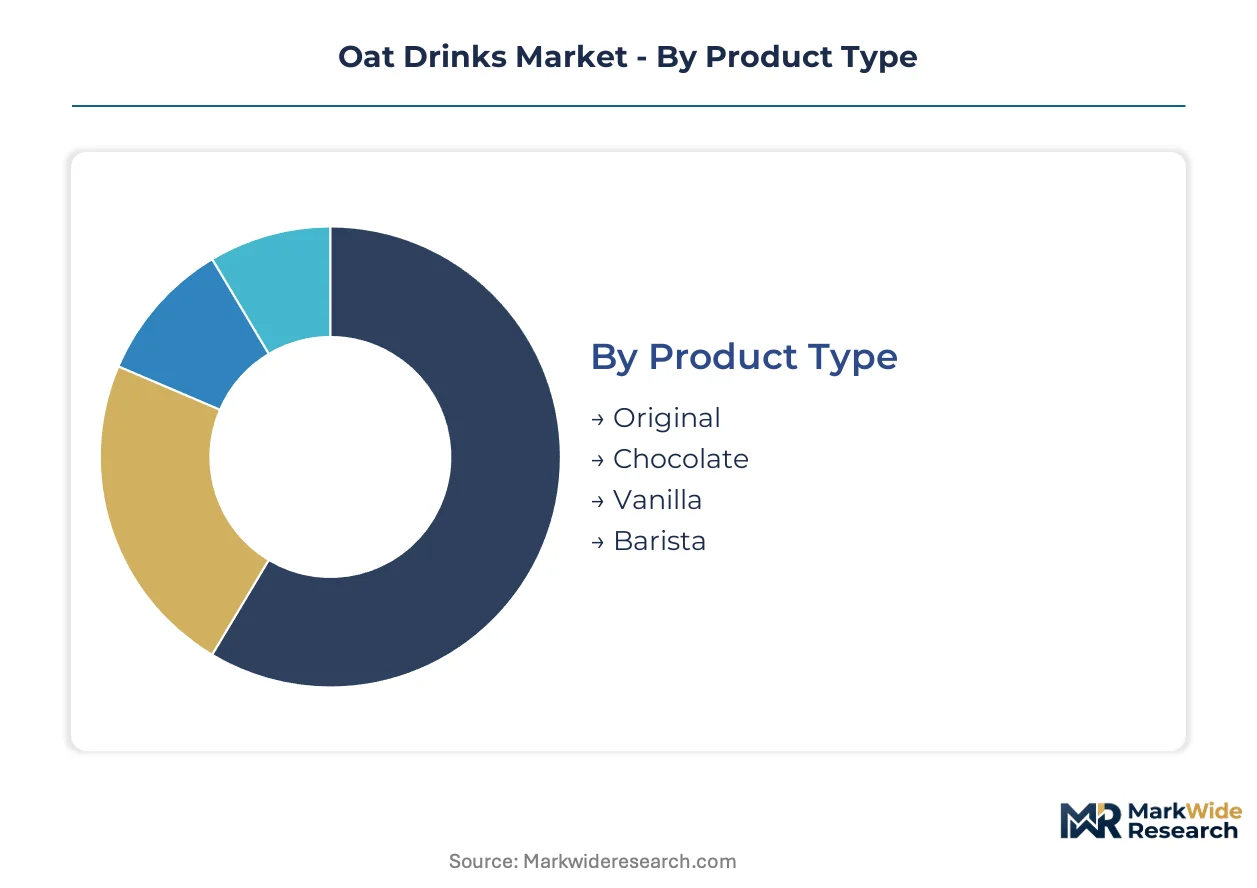
Oat drink segmentation reveals distinct margin architectures across formulation grades and channel access tiers. Product type and packaging format decisions determine whether processors capture foodservice premiums or compete on retail velocity.
Product Type:
Mature formats anchor volume while specialty grades extract disproportionate margin from café channels.
- Original:Unflavored base formulations with standardized beta-glucan content between 0.5-1.0%. German and British supermarkets move the highest absolute volumes through private-label and branded shelf placements.
- Chocolate:Cocoa-infused variants with added mineral fortification targeting pediatric and wellness segments. United States natural channel retailers and Nordic welfare procurement systems drive specialized formulation demand.
- Vanilla:Extract-flavored positioning for home-barista applications and smoothie bases. Compact SKU footprint limits dedicated production line investment.
- Barista:High-fat emulsion formulations engineered for steam wand stability and latte art retention. Melbourne, Portland, and Copenhagen roasters specify custom fat-content contracts directly with processors holding enzymatic IP.
Original handles the majority of throughput; Barista is the fastest mover on share.
Formulation:
Cost tier stratification separates commodity positioning from clinical-grade premium capture.
- Sweetened:Cane sugar or oat syrup solids added post-hydrolysis for palatability in mass-market conversion. Standard retail velocity in United States conventional grocery.
- Unsweetened:Zero-added-sugar positioning aligned with clean-label and ketogenic dietary protocols. Dominates German and British volume due to EFSA-compliant health claim eligibility.
- Flavored:Seasonal and limited-run variants (caramel, matcha, turmeric) testing market expansion beyond core coffee adjacency. Higher markdown risk in refrigerated sets.
- Fortified:Calcium, vitamin D, and B12 enrichment meeting clinical nutrition standards. Nordic welfare system protocols and United States senior nutrition programs specify these formulations for reimbursable distribution.
Unsweetened commands the widest retail distribution; Fortified is climbing the fastest on per-unit margin contribution.
Packaging Type:
Supply concentration in aseptic equipment shapes geographic deployment feasibility.
- Carton:Gable-top paperboard with polyethylene liners for refrigerated distribution. Dominates European retail due to established dairy infrastructure reuse.
- Bottle:PET or HDPE formats for single-serve convenience and visual differentiation. United States grab-and-go channel preference drives shape innovation.
- Tetra Pak:Aseptic brick packaging enabling ambient shelf stability. Southeast Asian convenience retail expansion depends on this format's logistics tolerance.
- Can:Aluminum formats for on-premise dispensing and cocktail mixology applications. Emerging in United States specialty coffee and bar channels.
Carton handles the majority of throughput; Tetra Pak is gaining share fastest in export-oriented production.
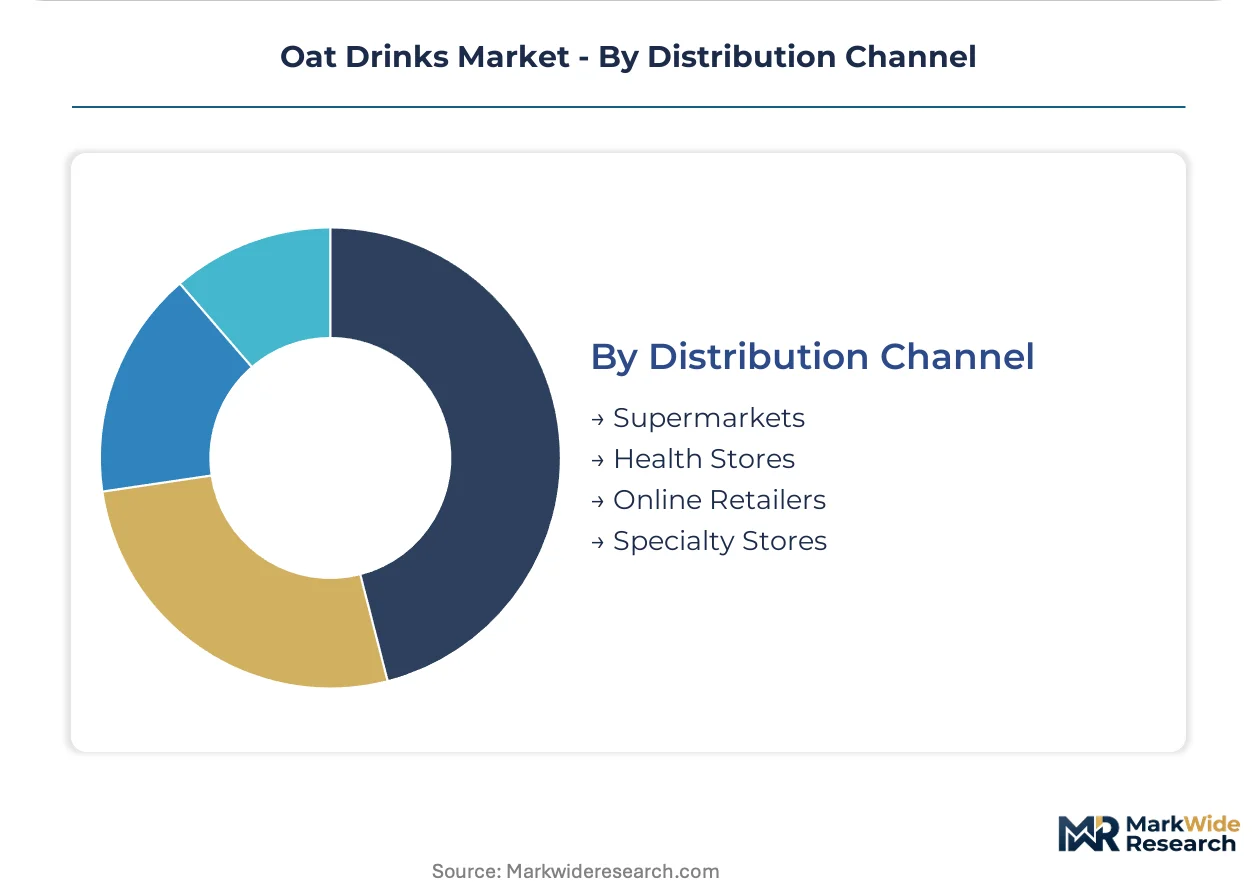
Distribution Channel:
Customer type determines margin structure and brand control intensity.
- Supermarkets:High-velocity retail with slotting fee barriers and private-label substitution risk. German and British multiples concentrate volume through centralized procurement.
- Health Stores:Independent natural channel with educated staff recommendation influence. United States regional chains maintain stricter ingredient transparency standards than conventional retail.
- Online Retailers:Direct-to-consumer and platform-mediated subscription models. Enables fortified and flavored variant testing with lower shelf-risk exposure.
- Specialty Stores:Coffee equipment retailers and culinary supply shops. Barista-grade formats command price premiums through technical specification validation.
Supermarkets handle the majority of throughput; Specialty Stores are expanding most quickly on per-liter margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Café chain procurement managers in Germany, the United Kingdom, and the United States drive the bulk of barista-grade volume. These buyers specify enzymatic performance standards that ripple back through Nordic milling supply chains.
United States
Specialty coffee roasters in Portland and Los Angeles contract directly with processors for custom fat-content formulations. FDA allergen labeling rules govern protein claim substantiation on fortified variants. Pacific Northwest production clusters now document supply chain deforestation risks through emerging traceability platforms.
Germany
Discounters and organic multiples move the highest absolute volumes of unsweetened base formulations through centralized procurement. EU Farm to Fork Strategy carbon disclosure mandates accelerate clean-label investments among domestic processors. Berlin-Brandenburg facilities report 40% capacity expansion orders for oat-dedicated lines.
United Kingdom
Supermarket private-label substitution pressures branded shelf placements in conventional retail. EFSA beta-glucan health claim eligibility drives functional positioning in wellness segments. London café chains specify oat milk as default dairy alternatives, creating pull-through demand for high-fat emulsion grades.
Sweden
Nordic welfare system procurement protocols specify clinical-grade fortification standards for reimbursable distribution. REACH chemical registration requirements and F-Gas Regulation phase-down schedules compel CO2-based refrigeration investments. Stockholm-Uppsala milling clusters control premium-grade oat supply for enzymatic hydrolysis feedstock.
Australia
Melbourne roasters pioneered direct-to-processor contracting models now replicated in Copenhagen and Portland. The country's national food standards code governs plant-based dairy terminology and mineral fortification limits. Victoria-based production facilities face steep compliance cost escalation from clean-in-place chemical intensity regulations.
Oat Drinks Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin architectures. The structure tiers between vertically integrated multinationals with captive milling assets and enzymatic-IP specialists focused on foodservice penetration. Two archetypes dominate: scale-driven retailers leveraging established dairy infrastructure, and barista-grade formulators commanding premium through performance certification. Competitive moves concentrate on strategic partnerships with roasting equipment manufacturers and geographic licensing of proprietary enzyme formulations.
Within the enzymatic-IP tier, Oatly Group AB exemplifies the foodservice-first archetype through its proprietary process positioning. Danone S.A. occupies the retail-scale vector, anchoring European shelf space through established distribution infrastructure. Califia Farms represents the barista-specialist position, competing on formulation stability in professional coffee applications.
| Leading Market Players |
|---|
| Oatly Group AB |
| Danone S.A. |
| Califia Farms |
| Campbell Soup Company |
| Chobani LLC |
| HP Hood LLC |
| The Hain Celestial Group Inc. |
| Pacific Foods of Oregon LLC |
| Alpro |
| Others |
Supply Flow & Price Mechanics
Nordic milling-grade oat concentration in Sweden and Finland concentrates upstream leverage among processors controlling enzymatic IP, pushing margin pools downstream toward barista-grade formulation tiers and direct-to-foodservice contracting channels.
Pricing Analysis
Cost-plus contracts with Nordic oat indexation dominate procurement between millers and processors, creating price transparency that compresses spreads on commodity-grade formulations. Pricing stratifies across premium, standard, and economy tiers based on fat emulsion performance and certified foam-retention standards. Cost compression in unsweetened retail SKUs is intensifying because German and British supermarket private-label substitution erodes branded shelf space. Discounter buyers exhibit highest price sensitivity; Melbourne and Copenhagen roasters contracting directly for custom fat-content formulations show lowest sensitivity due to performance-linked specification requirements.
Supply Chain Analysis
Contract manufacturing concentration sits with Danish and Dutch equipment suppliers reporting capacity expansion orders from oat-dedicated facilities, while Nordic toll processors handle enzymatic hydrolysis stages. Geographic supply concentration centers on Sweden, Finland, and Germany for premium milling-grade oats; Canada and the United States for feedstock diversification. Raw material dependencies include proprietary amylase and lipase formulations, aseptic packaging substrates, and food-grade beta-glucan testing reagents. Single-source vulnerability around specialty enzyme suppliers exposes mid-scale processors to input cost volatility. Distribution runs through refrigerated dairy infrastructure reuse in European retail, ambient Tetra Pak logistics for Southeast Asian export, and direct-to-roaster contracting in Pacific Northwest and Australian metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through direct-to-processor contracting by specialty coffee roasters, fragmenting traditional retail brokerage intermediation and concentrating volume with vertically integrated suppliers holding captive milling assets.
For Market Incumbents: Insulate barista-grade margin pools by locking multi-year enzymatic IP licensing agreements with roasting equipment manufacturers facing 12-18 month foam-retention validation cycles. Accelerate backward integration into Nordic milling clusters to secure premium-grade oat feedstock against weather-driven input volatility from Baltic growing regions. For New Entrants and Emerging Players: Southeast Asian convenience retail represents the most penetrable white-space target, where UHT Tetra Pak formats enable ambient distribution without refrigerated infrastructure investment. Target senior nutrition and clinical reimbursement channels in North America with fortified formulations transplantable from Nordic welfare system protocols. Lead with direct-to-institutional procurement bypassing slotting fee barriers in conventional supermarket retail. For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic-IP specialists with established foodservice penetration rather than scale-driven retail players facing private-label substitution pressure. Long-term viability over a multi-year horizon hinges on defensible lipid optimization technology and regional milling asset control. Monitor EUDR-aligned traceability platform adoption rates as an inflection indicator for supply chain compliance cost escalation and market access differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic IP Licensing Expansion | Locks in 12-18 month validation cycles with coffee equipment manufacturers seeking foam-retention certification. |
| Backward Integration into Nordic Milling | Secures premium-grade oat supply from Stockholm-Uppsala clusters against Baltic weather volatility. |
| UHT Tetra Pak Format Development | Enables ambient distribution in Southeast Asian convenience retail without cold-chain infrastructure. |
| Direct-to-Foodservice Procurement Bypass | Concentrates volume with Melbourne and Copenhagen roasters specifying custom fat-content contracts. |
| EUDR-Aligned Traceability Investment | Documents deforestation risks for EU market access under Farm to Fork Strategy disclosure mandates. |
Methodological Framework
A standing panel of oat drink processors, specialty coffee roasters, enzymatic equipment suppliers, and Nordic grain procurement managers provided ongoing calibration across the analysis window. Primary interviews with foodservice channel buyers and retail category managers combined with secondary validation from EFSA guidance documents, EU REACH chemical registration databases, FDA allergen labeling filings, and Nordic welfare system procurement protocols. Bottom-up volume modeling across formulation grades triangulated against top-down category spend estimates from retail audit data and foodservice distribution records.
Scenario-bracketing around regulatory acceleration and enzyme cost volatility framed the projection horizon. Segmentation dimensions modeled include product type, formulation grade, packaging format, and distribution channel complexity. CAGRs were derived from trend extrapolation adjusted for channel penetration saturation curves and substitution elasticity between oat and alternative plant-based formats. Forecast inputs incorporated EUDR compliance timeline assumptions and specialty coffee equipment manufacturer certification pipeline data.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by pharmaceutical-sector enzyme engineering recruiters would shift outcomes through talent scarcity escalation. Quarterly review of Nordic oat harvest yield forecasts, EFSA plant-based terminology rulings, and roasting equipment manufacturer validation queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Milk Alternatives Market