
 Pea Milk Market | 2026-2036
Pea Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Milk Market Outlook
Barista-grade protein stability is reorganizing the competitive landscape for premium pea milk positioning. Ripple Foods leverages its proprietary pea-protein extraction platform to anchor supply consistency across North American retail channels. Califia Farms sustains brand recognition through extended shelf-stable product lines, while Sproud competes on carbon-neutral sourcing credentials in European markets.
Pea milk is an aqueous emulsion derived from yellow split peas, typically containing 7-8 grams of protein per 240-milliliter serving and manufactured through aqueous extraction followed by homogenization and ultra-high-temperature processing. The formulation serves as a functional dairy alternative in beverage, culinary, and food-service applications where thermal stability and neutral flavor profiles matter. Unsweetened variants dominate volume in health-conscious retail segments, while flavored formulations capture margin pools through premium positioning in specialty channels. Online retail is expanding fastest among distribution channels, though supermarkets still control the majority of physical shelf-space negotiations.
The FDA oversees plant-based dairy labeling standards and nutrient fortification requirements in the United States, while the USDA regulates organic certification pathways that affect premium-tier product access. The EFSA evaluates novel protein safety claims within European markets, shaping cross-border formulation strategies for exporters. Stakeholders must monitor evolving allergen disclosure mandates and protein-content threshold debates that could redefine category boundaries between pea milk and blended plant-based alternatives.
Market Dynamics
Barista-grade foam stability requirements are compressing formulation margins while forcing pea protein suppliers to invest in proprietary extraction IP. Specialty coffee chains now specify protein denaturation temperatures in procurement contracts.
Growth Catalysts
- Clean-label mandates:The FDA's updated plant-based dairy guidance is accelerating reformulation investments among beverage manufacturers seeking label clarity.
- Food-service procurement:Pacific Northwest metropolitan cafés are specifying pea milk in multi-year supply agreements for foam-stable espresso applications.
- Carbon accounting frameworks:EU Green Deal reporting requirements are steering European retailers toward legume-based alternatives with verifiable Scope 3 reductions.
Market Restraints
- Input cost volatility:Yellow split pea prices fluctuate with Canadian prairie harvest yields, squeezing margin predictability for processors.
- Technical limitation:Beany off-flavor compounds persist in standard aqueous extraction, requiring expensive enzymatic treatment or masking additives.
- Substitution threat:Oat milk's established barista positioning and lower price point capture price-sensitive café operators.
Strategic Opportunities
- Underpenetrated geography:India's FSSAI plant-based beverage category remains nascent, offering first-mover positioning for protein-fortified variants.
- Regulatory tailwind:USDA organic certification pathways enable premium-tier pricing in natural retail channels.
- Technology convergence:Precision fermentation of pea protein isolates combined with cellular agriculture techniques could compress production costs.
Industry Challenges
- Skill gap in extrusion technology:Few food engineers possess expertise in high-shear pea protein texturization for beverage applications.
- Capex intensity:Ultra-high-temperature processing lines require seven-figure investments that strain mid-cap entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Milk Market |
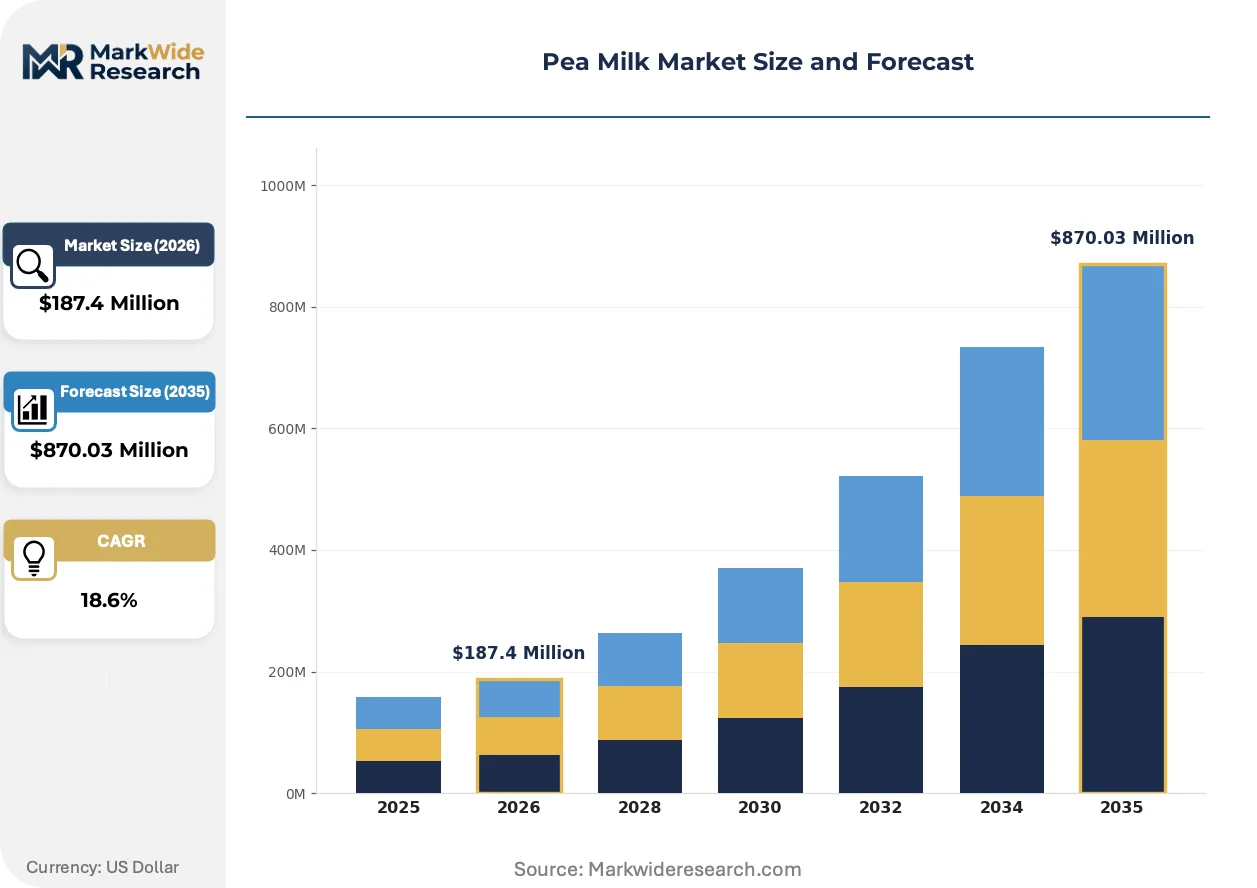
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Organic Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Vegan Consumers, Health-Conscious Individuals, Lactose-Intolerant Individuals, Food Service Providers Packaging Type: Bottles, Cartons, Pouches, Tetra Packs |
| Companies Covered | Good Karma Foods, Califia Farms, Ripple Foods, Snappea Foods, So Delicious Dairy Free, Sproud, Bolthouse Farms, Devon Garden Foods, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Milk Market Strategic Shifts
Formulation science is pivoting toward protein functionality rather than flavor masking. Thermal stability and emulsion behavior now drive R&D resource allocation ahead of taste engineering.
Membrane filtration technology is miniaturizing. Ceramic microfiltration systems now enable on-site protein concentration at smaller processing facilities. Regional dairy cooperatives in Wisconsin and Vermont are piloting these modular units. The technology is miniaturizing capital requirements for entry, fragmenting production geography away from centralized Midwest plants.
REACH registration requirements for novel protein isolates are tightening purity documentation standards. European exporters must submit expanded toxicological dossiers to ECHA. German and Dutch ingredient suppliers are absorbing compliance costs into premium pricing, widening the transatlantic cost gap for finished beverages.
Café procurement committees now require sensory validation data before contract execution. Third-party foam-stability testing from certified laboratories has replaced in-house cupping trials. This specification escalation concentrates supplier relationships with laboratories in California's Bay Area food-tech corridor, where testing infrastructure clusters near formulation R&D facilities.
Pea Milk Market Segmentation
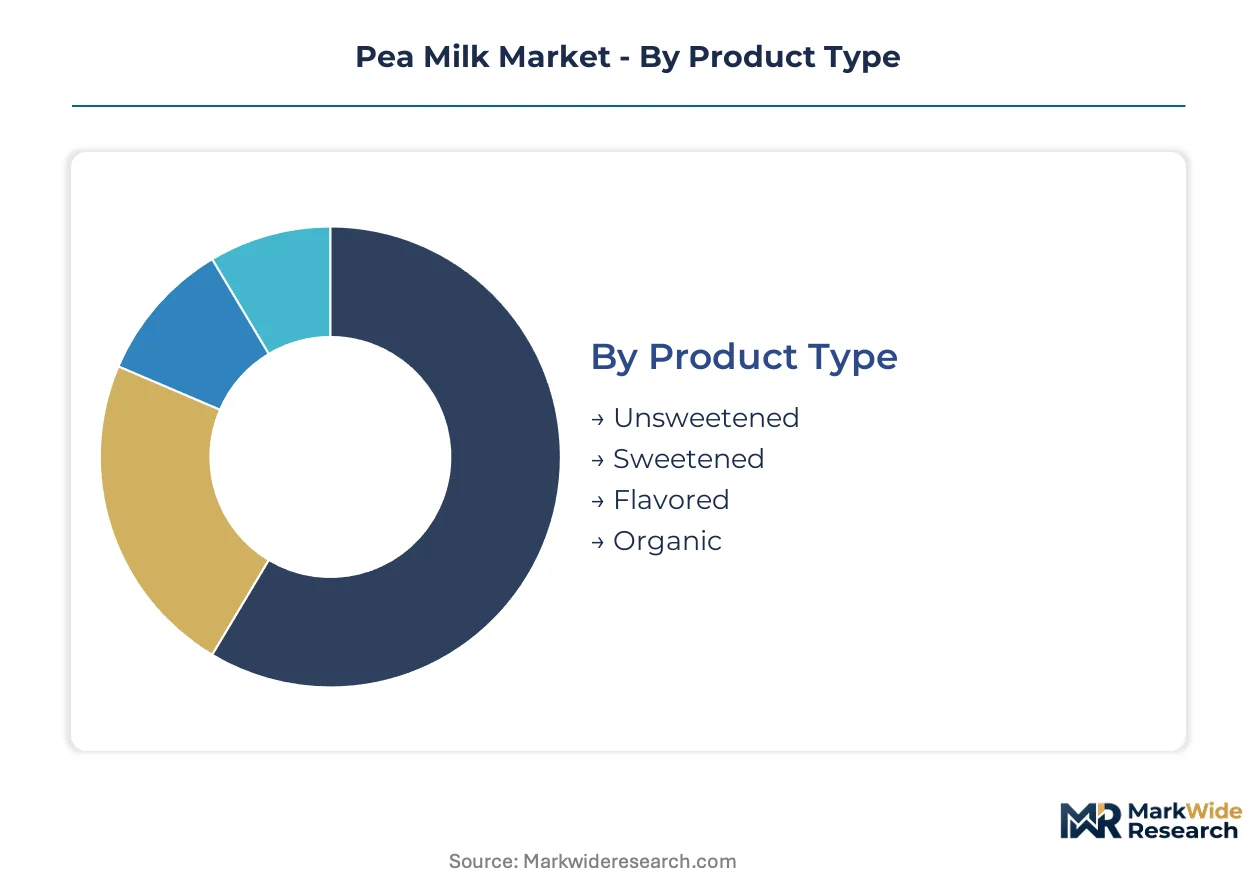
Pea milk's functional versatility across beverage, culinary, and food-service applications creates distinct performance requirements by segment. Procurement specifications from specialty coffee chains and clean-label retail mandates are compressing formulation standards unevenly across product types and channels.
Product Type:
Unsweetened variants face the most intense substitution pressure from oat milk's barista-grade positioning, forcing protein-content differentiation as the primary defense.
- Unsweetened:Contains 7-8 grams of protein per 240-milliliter serving with no added sugars. Bay Area food-tech corridor retailers specify this variant for health-conscious consumers seeking minimal ingredient lists; oat milk's lower price point squeezes margin room in café procurement.
- Flavored:Vanilla, chocolate, and barista-specific formulations incorporate masking additives to neutralize beany off-notes. Specialty channels in the Pacific Northwest metropolitan clusters drive demand where premium positioning offsets enzymatic treatment costs.
- Sweetened:Added cane sugar or alternative sweeteners broaden household penetration. Mainstream supermarket placement depends on price parity with almond milk.
- Organic:USDA certification pathway enables tiered pricing in natural retail channels. Input cost volatility from certified yellow split pea sourcing constrains processor margins.
Unsweetened retains volume leadership; flavored holds the steepest expansion curve.
Distribution Channel:
Channel economics stratify sharply between capital-light digital entry and shelf-space negotiation leverage.
- Online Retail:Direct-to-consumer subscriptions and third-party marketplace listings enable rapid SKU testing with minimal working capital. California's Bay Area food-tech corridor hosts the densest concentration of pea milk-focused e-commerce operations.
- Supermarkets:Control majority physical shelf-space negotiations. Slotting fees and promotional calendars favor established beverage portfolios with multi-category leverage.
- Health Food Stores:Regional chains in the Pacific Northwest prioritize clean-label credentials and local supplier relationships over national brand recognition.
- Specialty Shops:Independent grocers and gourmet retailers stock premium-tier variants with extended shelf-stable formats. Limited refrigerated case space restricts SKU breadth.
Supermarkets retain volume leadership; online retail climbs the fastest.
End User:
User segments diverge on protein functionality requirements versus taste preference tolerance.
- Food Service Providers:Specialty coffee chains now specify protein denaturation temperatures and foam-stability metrics in multi-year supply agreements. Third-party sensory validation from Bay Area laboratories has replaced in-house cupping trials.
- Vegan Consumers:Ethical positioning and complete dairy avoidance drive loyalty. Price sensitivity varies by household income bracket.
- Health-Conscious Individuals:Prioritize protein density and minimal processing. Unsweetened variants dominate this segment.
- Lactose-Intolerant Individuals:Functional dairy replacement rather than lifestyle choice. Oat milk and almond milk compete aggressively on taste familiarity.
Food service providers retain volume leadership; health-conscious individuals gain share fastest.
Packaging Type:
Packaging selection tracks supply chain infrastructure and retail format requirements.
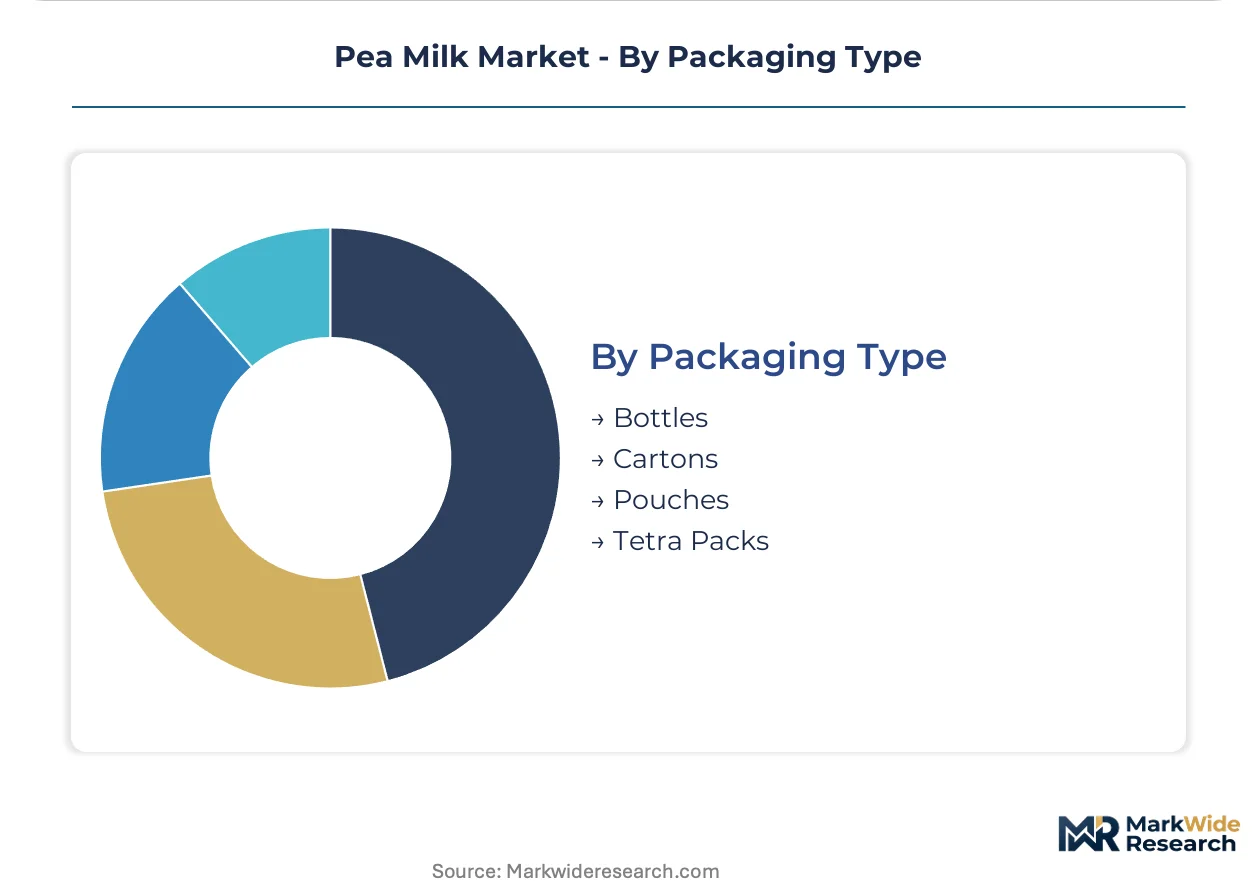
- Tetra Packs:Aseptic brick format enables ambient distribution with twelve-month shelf stability. Extended supply radius suits national retail expansion.
- Cartons:Refrigerated gable-top format dominates conventional dairy case placement. Regional dairy cooperative infrastructure in Wisconsin and Vermont supports this format.
- Bottles:Clear PET or glass formats emphasize visual differentiation. Premium positioning in specialty channels justifies higher unit costs.
- Pouches:Flexible format reduces shipping cube and material weight. Limited to online retail and food-service bulk procurement.
Tetra packs retain volume leadership; pouches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows for pea milk ingredients concentrate in North American and European corridors, with yellow split pea protein isolates crossing the Atlantic to serve formulation facilities on both continents. Trade volumes track regulatory divergence between FDA and EFSA standards, creating parallel certification requirements for multi-continental suppliers.
United States
Bay Area food-tech corridor demand from specialty coffee chains and clean-label retailers drives procurement volume. FDA updated plant-based dairy labeling guidance in 2023, accelerating reformulation investments among domestic beverage manufacturers. Pacific Northwest metropolitan clusters in Seattle and Portland specify pea milk in multi-year food-service supply agreements.
Canada
Prairie provinces supply the majority of North American yellow split pea feedstock, with Saskatchewan and Manitoba harvest yields determining input cost volatility for downstream processors. Canadian Food Inspection Agency oversees organic certification pathways that enable premium-tier pricing in cross-border US natural retail channels. Vancouver and Toronto host the densest concentrations of plant-based beverage R&D facilities outside California.
Germany
EU Green Deal carbon accounting frameworks steer retailer procurement toward legume-based alternatives with verifiable Scope 3 reductions. ECHA REACH registration requirements for novel protein isolates tighten purity documentation standards, expanding compliance costs for German ingredient suppliers. Berlin and Hamburg anchor continental distribution networks for pea protein isolates serving Scandinavian and Benelux markets.
United Kingdom
London specialty coffee chains and independent barista cafés specify foam-stable pea milk formulations in procurement contracts. Food Standards Agency allergen disclosure mandates shape labeling requirements for blended plant-based alternatives containing pea protein. Manchester and Bristol host emerging formulation facilities targeting food-service channel expansion.
India
FSSAI plant-based beverage category regulations remain nascent, offering first-mover positioning for protein-fortified variants entering through urban metro markets. Import tariffs on processed plant-based beverages protect domestic dairy interests while creating opportunities for local manufacturing joint ventures. Mumbai and Bangalore food-tech incubators pilot pea protein extraction technologies adapted to regional yellow pea varieties.
Pea Milk Market Competitive Environment
Listed leaders compete with private specialists across capital access and speed-to-market dimensions, producing a bifurcated structure where scale advantages concentrate in publicly traded entities while agility resides in venture-backed entrants. The vendor base spans three strategic tiers: extraction-technology owners controlling proprietary protein platforms, brand marketers reliant on toll manufacturing arrangements, and private-label suppliers serving retail channel consolidation. Dominant competitive moves include backward integration into yellow split pea sourcing and technology licensing agreements that transfer extraction IP across geographic markets.
Within the technology-owner archetype, Ripple Foods and Califia Farms exemplify divergent strategic positions. Ripple Foods occupies a position anchored in proprietary pea-protein extraction platforms that supply consistency across North American retail channels. Califia Farms exemplifies brand-marketing specialization through extended shelf-stable product line architectures. Sproud represents the sustainability-differentiated tier, with carbon-neutral sourcing credentials shaping European market positioning.
| Leading Market Players |
|---|
| Good Karma Foods |
| Califia Farms |
| Ripple Foods |
| Snappea Foods |
| So Delicious Dairy Free |
| Sproud |
| Bolthouse Farms |
| Devon Garden Foods |
| Nestlé |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for yellow split pea processors compress margin buffers when Canadian prairie harvests underperform, tethering pricing power to Saskatchewan and Manitoba yield volatility rather than brand differentiation alone. This lead-time exposure forces beverage manufacturers into forward-contracting positions that lock in protein-isolate costs ahead of formulation runs, amplifying working capital intensity for mid-cap entrants lacking multi-year supply agreements.
Pricing Analysis
Food-service procurement committees anchor pricing structures through multi-year supply agreements specifying protein denaturation thresholds and foam-stability metrics. Three-tier pricing stratifies across premium barista-grade, standard retail, and economy private-label levels, with USDA organic certification commanding tier separation. Cost compression in the unsweetened segment intensifies as oat milk's lower price point captures price-sensitive café operators. Quick-service restaurant chains exhibit highest price sensitivity; specialty coffee chains with sensory-validation requirements show lowest.
Supply Chain Analysis
Canada and the United States anchor yellow split pea cultivation and protein-isolate production, with Saskatchewan prairie harvests feeding North American extraction facilities. Downstream formulation draws from pea protein isolates, enzymatic treatment inputs, and aseptic packaging materials. Single-source vulnerability concentrates in Canadian prairie weather exposure and its harvest yield impacts. Distribution runs through refrigerated dairy cooperative networks in Wisconsin and Vermont alongside ambient Tetra Pak channels serving national retail expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea milk's platform economics inflect around interoperability between extraction-technology licensing and barista-grade formulation standards, with Ripple Foods' proprietary platform illustrating how IP control enables ecosystem rent capture across multiple brand partnerships.
For Market Incumbents: Shield market position through backward integration into Saskatchewan yellow split pea sourcing and captive supply of protein-isolate capacity. Oat milk's entrenched barista positioning and lower price point threaten volume retention in food-service channels. Certification investment in USDA organic pathways defends premium-tier pricing against private-label encroachment in natural retail. For New Entrants and Emerging Players: Lead with India's FSSAI-nascent plant-based beverage category as the most penetrable geography, where import tariffs on processed alternatives protect domestic manufacturing joint ventures. Protein-fortified variants targeting urban metro markets offer white-space positioning ahead of regulatory codification. Direct-to-consumer subscriptions enable rapid SKU testing with minimal slotting-fee exposure. For Investors and Strategic Acquirers: Long-term, this sits as a technology-licensing play because extraction-IP ownership compounds value through recurring royalty streams across geographic markets. Target acquisition archetypes include modular ceramic microfiltration technology owners and Bay Area food-tech corridor formulation facilities. The signal to watch is specialty coffee chain procurement committees mandating third-party sensory validation from certified laboratories as a contract prerequisite.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Extraction | Saskatchewan sourcing contracts insulate margin predictability from prairie harvest volatility. |
| Barista-Grade Formulation Certification | FDA labeling clarity investments enable premium positioning in Pacific Northwest café procurement. |
| Modular Microfiltration Technology Deployment | Ceramic systems in Wisconsin and Vermont fragment production geography away from Midwest plants. |
| Carbon-Neutral Sourcing Credentialing | EU Green Deal Scope 3 reporting steers European retailer procurement toward verified legume alternatives. |
| Direct-to-Consumer Channel Expansion | Bay Area e-commerce operations enable rapid SKU testing without supermarket slotting-fee burdens. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA plant-based dairy guidance documents, EFSA novel protein safety evaluations, USDA organic certification databases, and trade flow records for yellow split pea protein isolates. Primary interviews engaged extraction-technology engineers, specialty coffee chain procurement directors, beverage formulation scientists, and natural retail category buyers. Secondary validation drew from SEC beverage manufacturer filings, ECHA REACH registration dossiers, and food-service supply agreement specifications. Bottom-up volume modeling triangulated against top-down category spend analysis.
Segmentation dimensions modeled include product type, distribution channel, end-user application, and packaging format across the projection horizon. CAGRs derived from weighted-average growth assumptions applied to volume and value outputs. Industry-specific forecast inputs incorporated Canadian prairie harvest yield correlations, enzymatic treatment cost curves, and specialty coffee chain procurement contract tenors throughout the forecast period.
Forecasts assume regulatory continuity in FDA plant-based labeling standards and EFSA novel protein evaluation frameworks; material policy shifts would require re-modeling. Specific risks include FSSAI category codification in India, REACH purity documentation tightening in Europe, and allergen disclosure mandate evolution affecting blended alternative formulations. Recalibration cycles align with material shifts in Canadian harvest yields, coffee chain procurement specification escalation, and carbon accounting framework adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market