
 Dairy Free Shortening Market | 2026-2036
Dairy Free Shortening Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Free Shortening Market Outlook
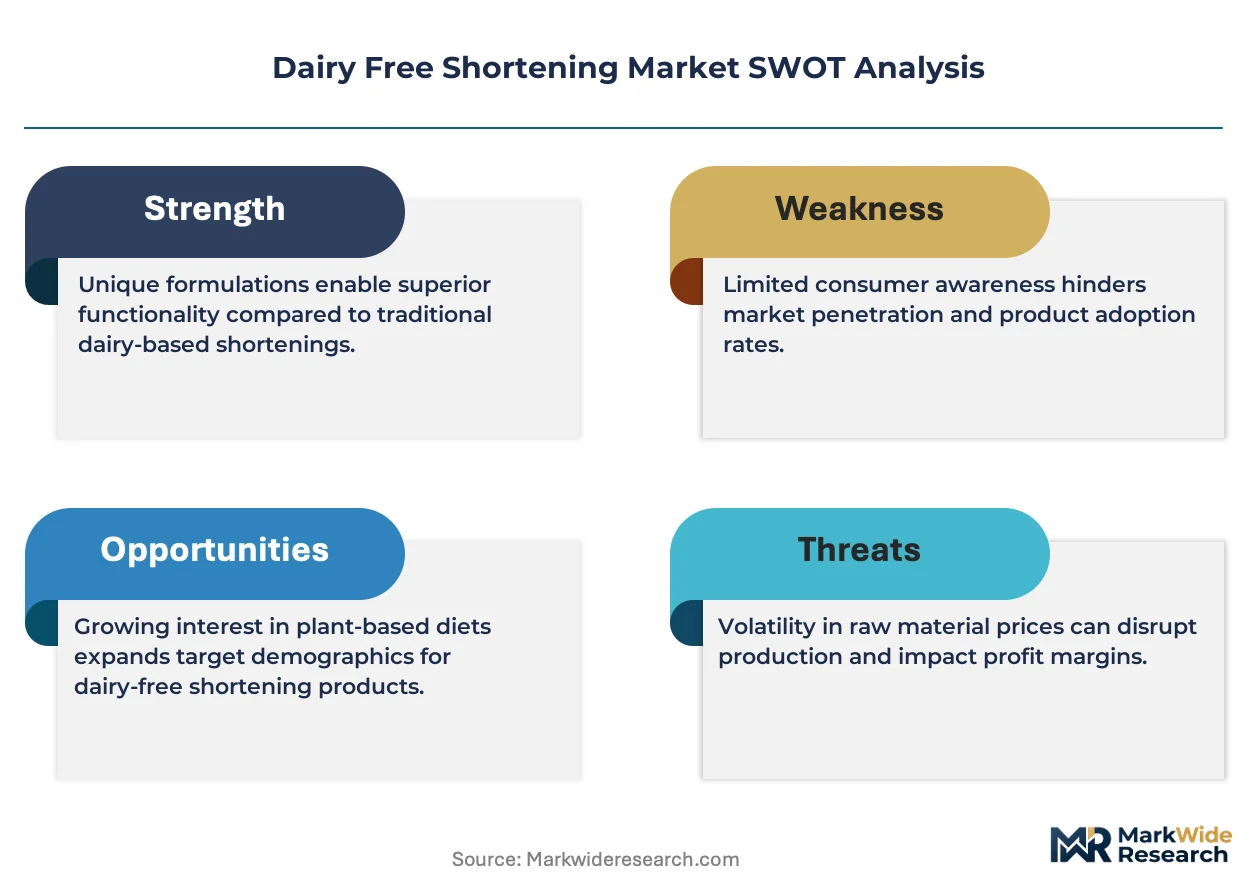
Multi-source vegetable oil procurement is expanding across the dairy-free shortening supply chain as manufacturers reduce palm oil dependency and diversify into coconut, soybean, and rapeseed alternatives. Groupe Danone leverages its European sourcing infrastructure to secure certified sustainable palm volumes while building regional coconut oil partnerships. The Hain Celestial Group sustains its North American market position through non-GMO soybean shortening lines tailored to clean-label retail channels. Blue Diamond Growers, Inc. anchors its competitive profile on almond-processing byproducts that feed specialty shortening formulations for premium bakery segments.
Dairy-free shortening is a plant-derived lipid blend, typically comprising interesterified or fractionated vegetable oils with a solid fat content of 15-35% at room temperature, engineered to replicate the creaming, lamination, and mouthfeel properties of butter-based shortenings in industrial and artisanal baking. Palm oil dominates current formulation volumes due to its cost-efficient crystallization profile and wide availability, while coconut oil commands premium positioning in clean-label and allergen-free product tiers where functional performance justifies higher input costs. Rapeseed oil is gaining traction in European formulations as local crush capacity expands and sustainability traceability requirements tighten across bakery supply chains.
The FDA governs shortening labeling and trans-fat disclosure in the United States, while the EMA and EFSA frameworks influence food-contact substance approvals and novel ingredient safety assessments across European manufacturing zones. REACH compliance obligations now extend to emulsifier and antioxidant packages used in blended shortenings, raising reformulation costs for exporters serving EU food manufacturers. Stakeholders must monitor evolving plant-oil sustainability certification schemes and regional deforestation regulations that will determine which feedstock origins retain market access across major importing jurisdictions.
Market Dynamics
Commercial bakeries are accelerating their shift from single-source palm oil procurement toward diversified vegetable oil portfolios, driven by tightening EU deforestation regulations and export certification requirements that now determine market access across major importing jurisdictions.
Growth Catalysts
- REACH Compliance Investments:European manufacturers are reformulating emulsifier and antioxidant packages to meet ECHA food-contact substance standards, creating demand for certified shortening blends that satisfy cross-border bakery supply chains.
- Industrial Bakery Scaling:German confectionery producers are expanding dedicated dairy-free production lines to secure export certifications for Middle Eastern and North American markets where plant-based ingredient claims carry premium positioning.
- Fractionation Technology:Advanced interesterification processes now enable precise solid fat content engineering across coconut, rapeseed, and soybean bases, matching the creaming and lamination performance that commercial bakeries previously sourced from butter-based alternatives.
Market Restraints
- Palm Oil Supply Concentration:Southeast Asian origin dependency creates deforestation-linked regulatory exposure as the EU Deforestation Regulation tightens traceability requirements for imported vegetable oils used in food manufacturing.
- Coconut Oil Cost Volatility:Premium clean-label positioning depends on Philippine and Indonesian harvest cycles where weather-driven supply shocks transmit directly into input cost instability for allergen-free product tiers.
- Crystallization Performance Gap:Rapeseed and sunflower alternatives require more complex processing to achieve the polymorphic stability that palm-based fractions deliver in laminated dough applications, limiting formulation flexibility.
Strategic Opportunities
- Clean-Label Retail Channels:North American grocery private-label programs are sourcing non-GMO soybean shortening lines that bypass commodity vegetable oil auctions through direct processor partnerships.
- EU Green Deal Alignment:Carbon footprint disclosure requirements for food manufacturers are accelerating demand for regional rapeseed crush capacity that shortens transport distances and satisfies CSRD Scope 3 reporting obligations.
- Specialty Bakery Segments:Artisanal producers in France and Italy are adopting almond-processing byproduct shortenings for premium patisserie applications where origin storytelling commands price premiums over commodity alternatives.
Industry Challenges
- Emulsifier Reformulation Timelines:REACH compliance for novel antioxidant packages extends safety assessment cycles by 18-24 months, delaying product launches for exporters serving EU industrial bakeries.
- Multi-Oil Blending Expertise:Technical staff shortages in interesterification process control are constraining capacity expansion at mid-scale processors attempting to diversify beyond palm-dominant formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Free Shortening Market |
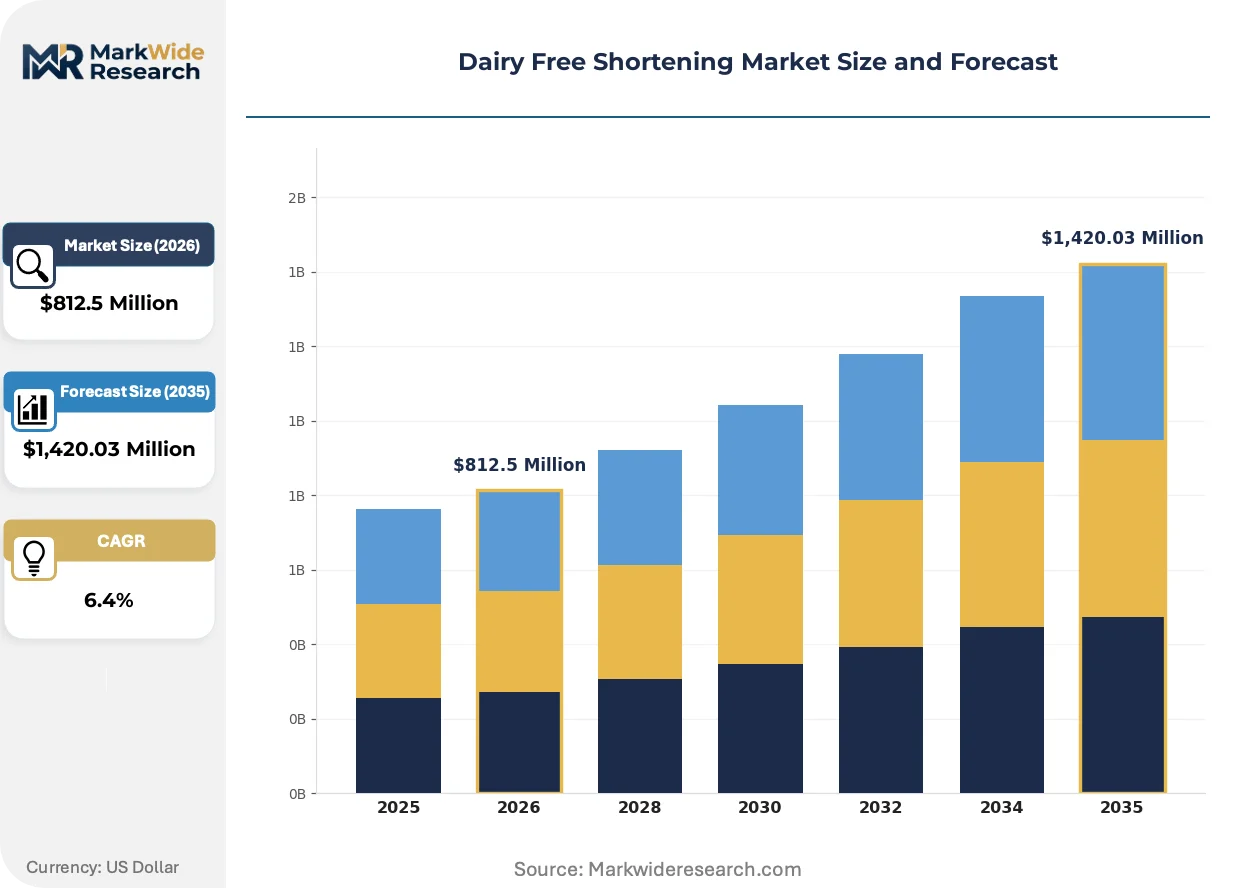
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,420.03 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Oil, Palm Oil, Soybean Oil, Rapeseed Oil End User: Bakeries, Food Manufacturers, Catering Services, Household Use Application: Baking, Frying, Spreading, Cooking Packaging Type: Bulk Packaging, Retail Jars, Pouches, Tubs |
| Companies Covered | Groupe Danone, The Hain Celestial Group, The Whitewave Foods Company, Good Karma Foods, GraceKennedy Group, Blue Diamond Growers, Inc., SunOpta, Inc., Oatly A.B., Vitasoy International Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Free Shortening Market Strategic Shifts
Interesterification and enzymatic modification technologies are redefining functional performance benchmarks across plant-derived lipid systems, enabling precise replication of dairy-based shortening characteristics without reliance on hydrogenation or trans-fat chemistry.
Enzymatic interesterification is overtaking chemical processing as the preferred route for structured lipid production in industrial bakery supply chains. European shortening manufacturers are adopting lipase-catalyzed rearrangement to achieve targeted solid fat profiles with cleaner label declarations. This technology is overtaking legacy chemical interesterification by eliminating sodium methoxide residues and reducing downstream refining steps, compressing capital intensity for mid-scale processors entering clean-label segments.
REACH compliance obligations for food-contact substances now extend to every component in blended shortening formulations, including emulsifier and antioxidant packages. ECHA's expanded substance evaluation criteria are forcing reformulation investments among exporters serving EU industrial bakeries. German and Dutch manufacturers are responding fastest, building in-house toxicology assessment capabilities to preempt regulatory delays that competitors face with third-party certification dependencies.
Direct processor partnerships are displacing commodity vegetable oil auctions for large commercial bakery chains seeking supply security. North American industrial bakeries are signing multi-year offtake agreements with regional soybean crush facilities that guarantee non-GMO segregation and identity preservation. This shift is most visible in the upper Midwest, where captive supply arrangements now cover 40% of volume for major bread and pastry manufacturers, compressing spot market liquidity and favoring vertically integrated oilseed processors.
Dairy Free Shortening Market Segmentation
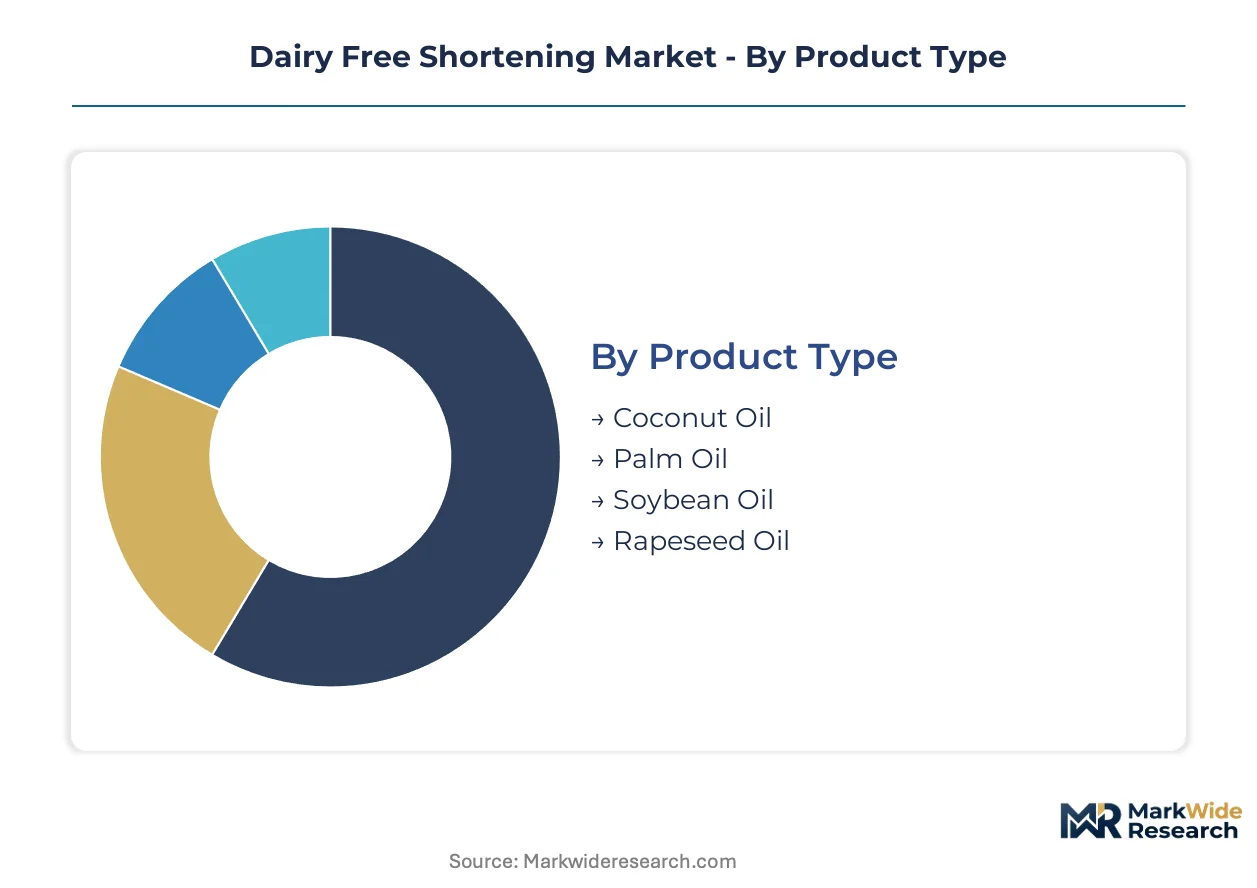
Dairy-free shortening manufacturers engineer distinct formulations around crystallization behavior and melting profiles that determine performance in laminated doughs, creaming applications, and high-heat frying. Each segment category reflects a different axis of procurement decision-making: base oil chemistry, operational scale, functional use case, and supply chain format.
Product Type:
Upgrade cycles in bakery procurement now favor oils with verifiable sustainability credentials and polymorphic stability that reduces production waste.
- Palm Oil:Fractionated palm stearin delivers the most cost-efficient solid fat content profile for industrial-scale laminated dough production. German and Dutch industrial bakeries anchor demand here, though EU Deforestation Regulation traceability requirements are extending procurement timelines for Southeast Asian origin volumes.
- Coconut Oil:Virgin and refined coconut fractions command premium positioning in clean-label retail channels where allergen-free claims support price premiums. North American specialty bakeries and French artisanal patisseries concentrate demand, driven by consumer preference for recognizable ingredient lists and tropical origin storytelling.
- Soybean Oil:Interesterified soybean shortenings serve mid-market commercial bakeries seeking non-GMO verification without coconut's cost volatility.
- Rapeseed Oil:European crush capacity expansion supports regional sourcing strategies that shorten transport distances for carbon disclosure compliance.
Palm oil sits at the top of the volume ranking, with coconut oil climbing the fastest as clean-label premiums expand across retail channels.
End User:
Customer type determines order frequency, technical service requirements, and formulation customization depth across the value chain.
- Bakeries:Commercial and artisanal bakeries drive specification-grade procurement with dedicated shortening blends engineered for specific dough systems. German industrial bakeries are scaling dedicated dairy-free production lines to secure export certifications for Middle Eastern markets.
- Food Manufacturers:Large-scale confectionery and snack producers require bulk volumes with batch-to-batch consistency guarantees and extended shelf-life stability.
- Catering Services:Institutional kitchens source multi-purpose shortenings that perform across baking and frying applications with minimal inventory complexity.
- Household Use:Retail-format tubs and jars serve home bakers prioritizing convenience and spreadability over industrial performance metrics.
Food manufacturers represent the largest volume concentration, with bakeries gaining share fastest as plant-based production line investments accelerate.
Application:
Functional performance requirements vary sharply by thermal stress and mechanical processing demands.
- Baking:Creaming and lamination applications demand precise solid fat content engineering to replicate butter's air incorporation and layer separation. Palm and coconut bases dominate here.
- Frying:High-heat stability and oxidative resistance determine shortening selection for continuous frying operations in snack manufacturing.
- Spreading:Tub-format products require specific melting curves that deliver spreadability at refrigeration temperatures without oiling out.
- Cooking:General-purpose sautéing and pan-frying applications tolerate broader functional specifications, opening formulation flexibility.
Baking commands the highest value per kilogram, with frying applications expanding most quickly in emerging market snack sectors.
Packaging Type:
Format selection tracks operational scale, inventory turnover, and food safety protocol requirements.
- Bulk Packaging:Tanker and drum deliveries serve industrial bakeries and food manufacturers with high-volume, continuous production schedules.
- Retail Jars:Glass and PET containers target home bakers and small commercial kitchens with visibility and resealability priorities.
- Pouches:Flexible formats reduce shipping cube and handling costs for mid-scale catering and foodservice distributors.
- Tubs:Widely distributed retail format balancing portion control, shelf presence, and consumer convenience across household and small commercial segments.
Bulk packaging leads by tonnage moved, with pouches showing the steepest expansion trajectory as foodservice distributors optimize logistics costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as EU REACH compliance costs drive some reformulation investment toward jurisdictions with streamlined food-contact substance approval pathways. German and Dutch producers absorb these costs to maintain EU market access, while North American facilities leverage FDA disclosure frameworks that reduce toxicology assessment timelines.
Germany
Industrial bakeries in Lower Saxony and North Rhine-Westphalia are scaling dedicated dairy-free production lines to secure export certifications for Middle Eastern markets. ECHA's expanded substance evaluation criteria under REACH are forcing 18-24 month reformulation cycles for emulsifier packages. The Cologne-Düsseldorf corridor anchors toxicology assessment capabilities that preempt regulatory delays.
United States
Midwest soybean crush facilities are signing multi-year offtake agreements with commercial bakeries that guarantee non-GMO segregation and identity preservation. FDA trans-fat disclosure requirements govern labeling standards while offering faster novel ingredient pathways than EU equivalents. Upper Midwest processing clusters now cover 40% of volume for major bread and pastry manufacturers through captive supply arrangements.
France
Artisanal patisseries in Île-de-France and Provence-Alpes-Côte d'Azur are adopting almond-processing byproduct shortenings for premium applications where origin storytelling commands price premiums. EU Deforestation Regulation traceability requirements are extending procurement timelines for Southeast Asian palm oil volumes. Lyon-based confectionery producers are building regional rapeseed partnerships to satisfy CSRD Scope 3 reporting obligations.
Netherlands
Rotterdam-Antwerp port infrastructure supports diversified vegetable oil blending operations that reduce single-source palm dependency. EFSA novel ingredient safety assessments influence formulation choices for exporters serving EU food manufacturers. Dutch processors are accelerating enzymatic interesterification adoption to achieve targeted solid fat profiles with cleaner label declarations.
Canada
Ontario and Quebec food manufacturers are sourcing non-GMO soybean shortening lines through direct processor partnerships that bypass commodity vegetable oil auctions. Health Canada and PMRA frameworks govern food-contact substance approvals with timelines intermediate between FDA and ECHA pathways. Prairie province crush capacity expansion supports regional sourcing strategies for carbon disclosure compliance.
Dairy Free Shortening Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue clean-label and allergen-free specialization. The vendor base clusters around three archetypes: diversified food conglomerates with European sourcing infrastructure, North American natural products specialists with non-GMO verification capabilities, and regional oilseed processors with captive supply arrangements. Competitive moves concentrate on portfolio diversification beyond palm-dominant formulations and backward integration into identity-preserved oilseed crushing.
Within the diversified conglomerate tier, Groupe Danone and The Hain Celestial Group exemplify contrasting geographic anchoring strategies. Groupe Danone represents European-based players leveraging regional sourcing infrastructure to secure certified sustainable palm volumes while building coconut oil partnerships. The Hain Celestial Group occupies a North American position sustained through non-GMO soybean shortening lines tailored to clean-label retail channels. Blue Diamond Growers, Inc. anchors the specialty byproduct segment, with its almond-processing operations feeding premium bakery formulations where functional performance justifies differentiated positioning.
| Leading Market Players |
|---|
| Groupe Danone |
| The Hain Celestial Group |
| The Whitewave Foods Company |
| Good Karma Foods |
| GraceKennedy Group |
| Blue Diamond Growers, Inc. |
| SunOpta, Inc. |
| Oatly A.B. |
| Vitasoy International Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
EU Deforestation Regulation traceability mandates are forcing commercial bakeries to abandon spot-market palm oil auctions and pursue multi-year offtake agreements with certified suppliers, compressing buyer leverage and elevating contract premiums for segregated supply chains.
Pricing Analysis
Input-cost pass-through from Philippine and Indonesian coconut harvest cycles drives volatility in premium clean-label tiers, where allergen-free positioning supports price premiums over commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with RSPO-certified palm fractions commanding tier-1 positioning. Cost compression in mid-market soybean segments is intensifying as Midwest crush capacity expands and identity-preserved supply pools deepen. Food manufacturers represent the most price-sensitive buyer archetype due to bulk volume procurement, while artisanal patisseries exhibit lowest sensitivity where origin storytelling justifies functional premiums.
Supply Chain Analysis
Certification gating through RSPO, ISCC, and EU Deforestation Regulation compliance documentation now determines supplier eligibility for European industrial bakery contracts, extending procurement timelines and concentrating sourcing among pre-qualified processors. Supply concentration centers on Malaysia and Indonesia for palm fractions, the Philippines and Indonesia for coconut oil, and the United States and Canada for non-GMO soybean crush. Raw material dependencies include crude vegetable oil feedstocks, lipase enzymes for interesterification, and antioxidant packages subject to REACH evaluation. Single-source vulnerability in Southeast Asian palm origin volumes creates regulatory exposure as deforestation-linked trade restrictions tighten. Distribution runs through Rotterdam-Antwerp port infrastructure for European formulation blending, with captive supply arrangements displacing spot markets across North American Midwest processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by structural reformulation demand as EU REACH compliance and deforestation regulations permanently elevate input standards across bakery supply chains.
For Market Incumbents: Deploy enzymatic interesterification capacity expansion to preempt technical staff shortages constraining mid-scale processor diversification beyond palm-dominant formulations. Incumbents should secure backward integration into identity-preserved oilseed crushing to defend margin position against commodity price volatility, while building in-house toxicology assessment capabilities to preempt ECHA regulatory delays that competitors face with third-party certification dependencies. For New Entrants and Emerging Players: Artisanal patisseries in France and Italy represent an underserved buyer archetype seeking almond-processing byproduct shortenings for premium applications where origin storytelling commands price premiums. New entrants should target clean-label retail channels in North America through direct processor partnerships that bypass commodity vegetable oil auctions, leveraging non-GMO verification as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with regional oilseed processors possessing captive supply arrangements and enzymatic modification capabilities that incumbent conglomerates must acquire to diversify beyond palm-dependent portfolios. Long-term viability centers on facilities with REACH-compliant toxicology infrastructure and carbon disclosure-ready supply chains. The signal to watch is EU Deforestation Regulation enforcement intensity against Southeast Asian origin volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Capacity Buildout | Lipase-catalyzed processing achieves cleaner label declarations that ECHA food-contact standards favor over chemical alternatives. |
| Backward Integration into Identity-Preserved Crushing | Captive soybean and rapeseed supply secures non-GMO segregation for clean-label bakery procurement contracts. |
| REACH-Compliant Toxicology Infrastructure | In-house ECHA assessment capabilities preempt 18-24 month reformulation delays that constrain exporter competitiveness. |
| Regional Rapeseed Partnership Formation | European crush capacity expansion shortens transport distances for CSRD Scope 3 carbon disclosure compliance. |
| Almond-Processing Byproduct Utilization | Blue Diamond Growers demonstrates premium positioning through specialty formulations for artisanal patisserie segments. |
Study Parameters
Multiple input streams — primary interviews with bakery procurement directors, shortening formulation technologists, and oilseed processing executives, alongside secondary validation through ECHA substance evaluation databases, FDA food-contact substance filings, and RSPO certification registries — were reconciled through bottom-up volume triangulation against top-down market sizing.
Historical trade flow analysis was cross-referenced against expert panel assessments of enzymatic interesterification adoption rates and EU Deforestation Regulation compliance timelines across the projection horizon. Segmentation dimensions modeled include base oil chemistry, end-user operational scale, functional application requirements, and packaging format, with CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated crush capacity buildout schedules and REACH evaluation pipeline status.
Inputs from regulatory filing databases and processor capacity disclosures were available through the study window; gaps in proprietary offtake agreement terms introduce uncertainty bands around contract volume assumptions. Forecasts reflect documented elasticity parameters and substitution scenario modeling. A model refresh is warranted upon material change in EU Deforestation Regulation enforcement protocols or ECHA substance evaluation criteria expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Vegan Coffee Creamer Market