
 Hempseed Milk Market | 2026-2036
Hempseed Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Hempseed Milk Market Foresight
Coffeehouse chains and specialty beverage outlets is repositioning hempseed milk from niche health stores to mainstream café menus. Pacific Foods of Oregon leverages its West Coast manufacturing infrastructure to supply food service channels with shelf-stable formulations. Manitoba Harvest Hemp Foods anchors its position through backward integration into Canadian hemp cultivation. Elmhurst 1925 differentiates via its zero-additive, water-only extraction process that preserves complete protein content.
Hempseed milk is an aqueous emulsion produced from shelled hemp seeds through cold milling and homogenization, typically containing omega-3 and omega-6 fatty acids in a 3:1 ratio alongside complete plant protein. The product serves commercial and residential buyers seeking allergen-free alternatives to soy and nut milks. Unsweetened formulations lead volume sales among health-conscious households, while flavored variants capture the fastest growth in fitness center vending and post-workout retail. Tetra Pak packaging dominates margin pools due to extended ambient shelf life and reduced cold-chain logistics costs.
The FDA oversees hemp ingredient safety under the Food Safety Modernization Act, while USDA organic certification governs premium tier positioning. Health Canada and EFSA novel food frameworks shape cross-border product registration timelines. Stakeholders must monitor evolving THC threshold enforcement and organic labeling harmonization as determinants of market access and price architecture.
Market Dynamics
Hempseed milk supply chains face a structural pivot as EFSA novel food authorization compresses cross-border registration timelines while specialty cafés demand foam-stable formulations that match dairy performance.
Growth Catalysts
- EFSA Novel Food Streamlining:The EU's consolidated safety assessment framework reduces hemp-derived ingredient approval cycles, enabling faster product launches across Germany, France, and the Netherlands.
- Café Channel Expansion:Specialty coffee chains in Berlin and Hamburg now specify hempseed milk for latte art applications, creating pull-through demand from dairy-alternative distributors.
- Cold Milling Advancements:High-pressure homogenization equipment preserves omega-3 fatty acid ratios during aqueous extraction, improving sensory profiles for unsweetened retail formulations.
Market Restraints
- THC Threshold Enforcement Variance:Health Canada maintains 10ppm limits while some US states enforce stricter thresholds, fragmenting formulation standardization and compliance costs.
- Shelled Hemp Seed Concentration:Canadian Prairie provinces supply 70% of North American raw material, exposing processors to single-origin crop failure and freight rate volatility.
- Protein Denaturation Limits:Thermal pasteurization degrades edestin protein bioavailability, constraining shelf-stable product claims versus refrigerated alternatives.
Strategic Opportunities
- Fitness Center Vending Penetration:Post-workout retail channels in California and Colorado show unserved demand for flavored, high-protein hempseed milk SKUs with electrolyte fortification.
- USDA Organic Premium Tier:Certification gaps in current supply create first-mover advantage for vertically integrated processors capturing organic price premiums in natural grocery.
- Tetra Pak Ambient Distribution:Extended shelf-life packaging enables direct-to-retail models in Southeast Asian markets lacking cold-chain infrastructure for nut and oat alternatives.
Industry Challenges
- Homogenization Technician Scarcity:Food science programs produce few specialists in plant-milk emulsion stability, forcing manufacturers to train in-house or poach from dairy alternatives.
- Dual Certification Timelines:Simultaneous USDA Organic and EFSA novel food approvals require parallel documentation streams, stretching regulatory affairs capacity at mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hempseed Milk Market |
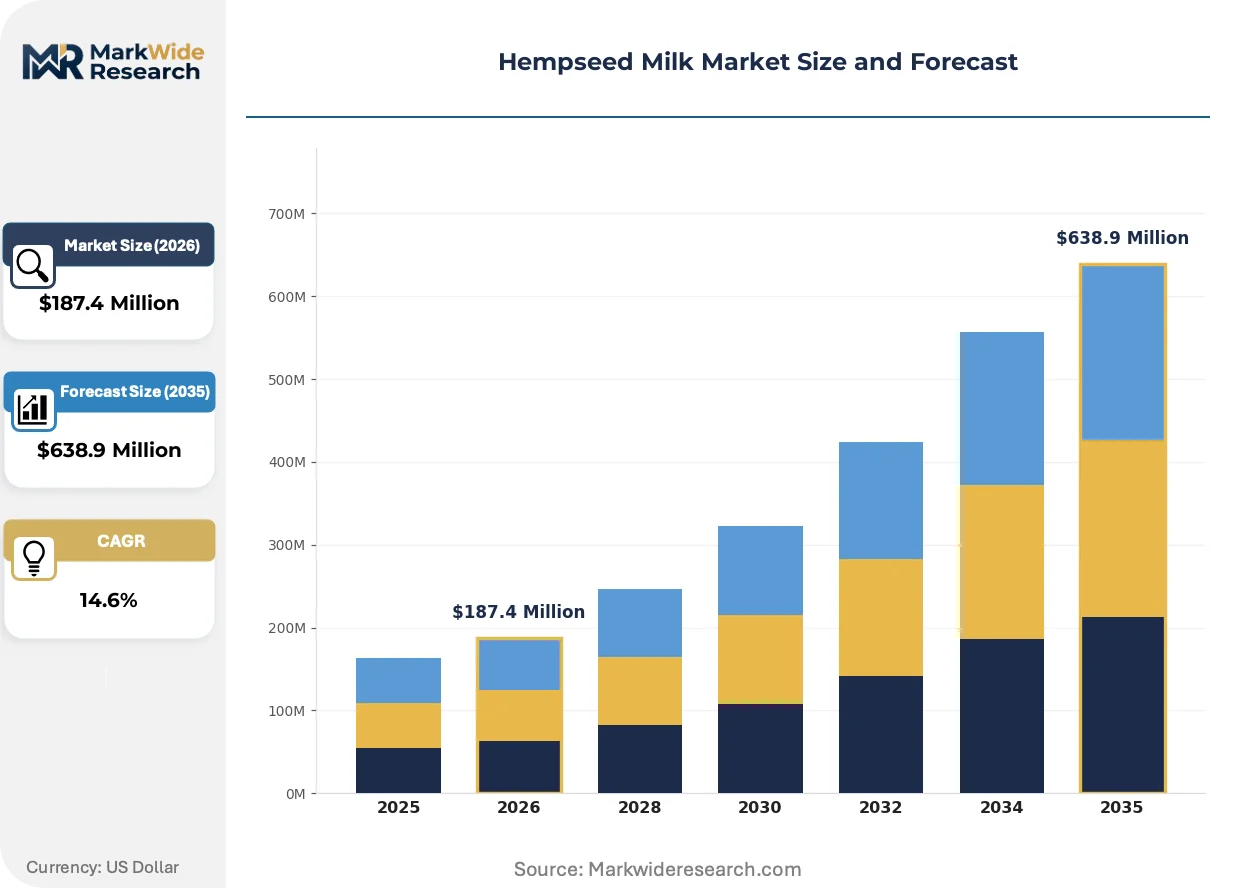
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened, Unsweetened, Flavored, Organic Packaging Type: Bottle, Carton, Can, Tetra Pak Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores End User: Households, Food Service, Fitness Centers, Cafés |
| Companies Covered | Pacific Foods of Oregon, Hudson River Foods, Good Hemp Food, Living Harvest Foods, Manitoba Harvest Hemp Foods, SunOpta, Good Mylk Co., Elmhurst 1925, California Natural Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hempseed Milk Market Shifts & Advancements
Formulation science and packaging engineering are compressing the functional gap between hempseed milk and dairy, while regulatory harmonization and channel experimentation rewrite go-to-market economics.
High-pressure processing is overtaking conventional thermal pasteurization as the dominant safety intervention for hempseed milk. Cold-brew coffee chains in Portland and Austin now specify HPP-treated base liquids for their house-made hemp lattes. This shift preserves complete protein integrity and extends refrigerated shelf life without the cooked flavor notes that previously limited café adoption.
REACH-compliant food contact materials are mandating migration-tested barrier layers for aseptic cartons. EFSA's updated plastic regulation FCM 2023/2006 forces Tetra Pak converters to validate new laminate structures, adding 8-12 months to packaging qualification. German organic retailers have responded by accelerating shelf-stable glass bottle trials for premium-positioned hempseed milk lines.
Baristas now specify hempseed milk by foam-ability grade rather than brand name, compressing supplier switching costs. Third-wave coffee shops in Melbourne and Copenhagen grade alternatives on micro-foam stability and latte art definition, treating hempseed milk as a commodity input. This specification shift rewards processors investing in lecithin-free emulsification systems that deliver consistent steam performance across equipment types.
Hempseed Milk Market Segmentation
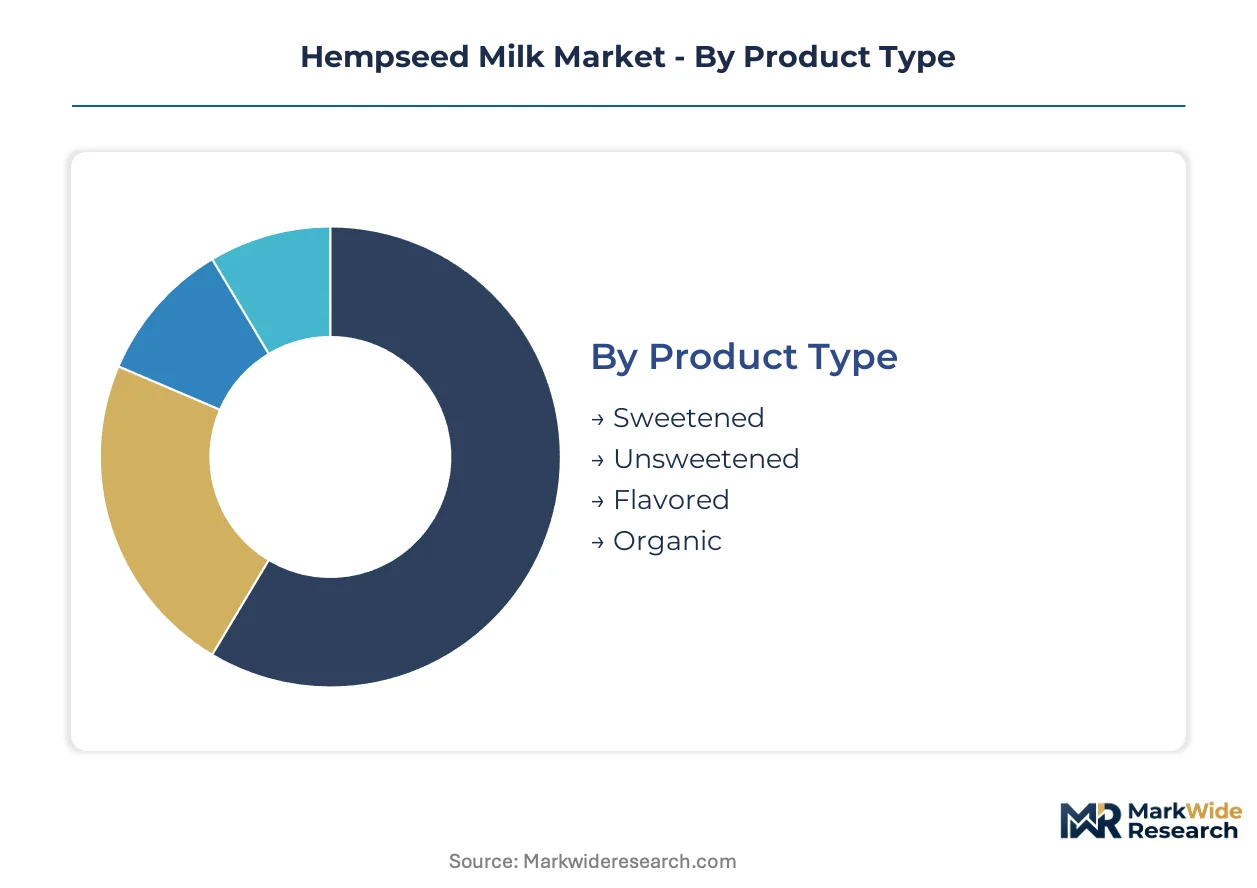
Hempseed milk processors must align capital deployment with segment-specific margin profiles. Product formulation, packaging technology, and channel access each demand distinct upfront investment thresholds that reshape competitive entry barriers.
Product Type:
Capital intensity peaks at organic certification and flavor development, where laboratory infrastructure and third-party audit cycles extend payback periods.
- Sweetened:Formulations incorporate cane sugar, date syrup, or monk fruit extract to mask hemp's grassy undertones. German retailers in Berlin and Hamburg stock these variants for flexitarian households transitioning from dairy. Demand concentrates in conventional supermarkets seeking entry-level price points for trial purchases.
- Unsweetened:Cold-milled aqueous emulsions with zero added sugars preserve the 3:1 omega-3 to omega-6 fatty acid ratio. Health-conscious households in California and Colorado drive volume, prioritizing clean-label credentials over palatability compromises. This segment absorbs the bulk of installed capacity; flavored variants are expanding most quickly.
- Flavored:Vanilla, chocolate, and matcha infusions target post-workout consumption occasions. Fitness center vending channels in Denver and Austin specify electrolyte-fortified SKUs.
- Organic:USDA certification requires three-year transition periods for hemp cultivation and dedicated processing lines. Natural grocery chains command 40-60% price premiums.
Unsweetened formulations anchor volume throughput; flavored SKUs capture the steepest expansion trajectory in fitness and food service channels.
Packaging Type:
Margin architecture diverges sharply between ambient-stable formats requiring aseptic filling lines versus refrigerated alternatives with lower equipment barriers.
- Bottle:PET and glass containers serve premium organic lines in German health food stores. Glass trials accelerated after EFSA's updated food contact material regulations delayed laminate qualifications.
- Carton:Gable-top refrigerated cartons dominate North American natural grocery placement. Pacific Foods of Oregon leverages existing West Coast filling infrastructure for this format.
- Can:Aluminum formats target convenience store single-serve consumption in Japan and South Korea. METI recycling compliance adds compliance overhead.
- Tetra Pak:Aseptic brick cartons enable Southeast Asian market entry where cold-chain infrastructure remains underdeveloped. REACH-compliant barrier validation cycles currently stretch 8-12 months.
Tetra Pak configurations command the widest margin pools; bottle formats are climbing the fastest in European premium channels.
Distribution Channel:
Customer acquisition economics vary by channel—supermarkets demand slotting fees, while direct-to-consumer platforms require digital infrastructure investment.
- Supermarkets:Conventional grocery chains in Germany and the Netherlands allocate shelf space based on scan velocity guarantees. Manitoba Harvest Hemp Foods secures placement through backward integration into Canadian cultivation.
- Online Retail:Subscription models and bulk purchasing concentrate in California and Colorado. Elmhurst 1925's zero-additive positioning performs strongly in Amazon's natural grocery algorithm.
- Health Food Stores:Independent retailers in Berlin and Copenhagen curate hempseed milk alongside CBD and hemp protein SKUs.
- Convenience Stores:Single-serve chilled placements target grab-and-go occasions in Japanese urban corridors.
Supermarkets absorb the bulk of volume throughput; online retail is gaining share fastest in North American metro markets.
End User:
Application-specific formulation requirements create divergent R&D investment priorities across user categories.
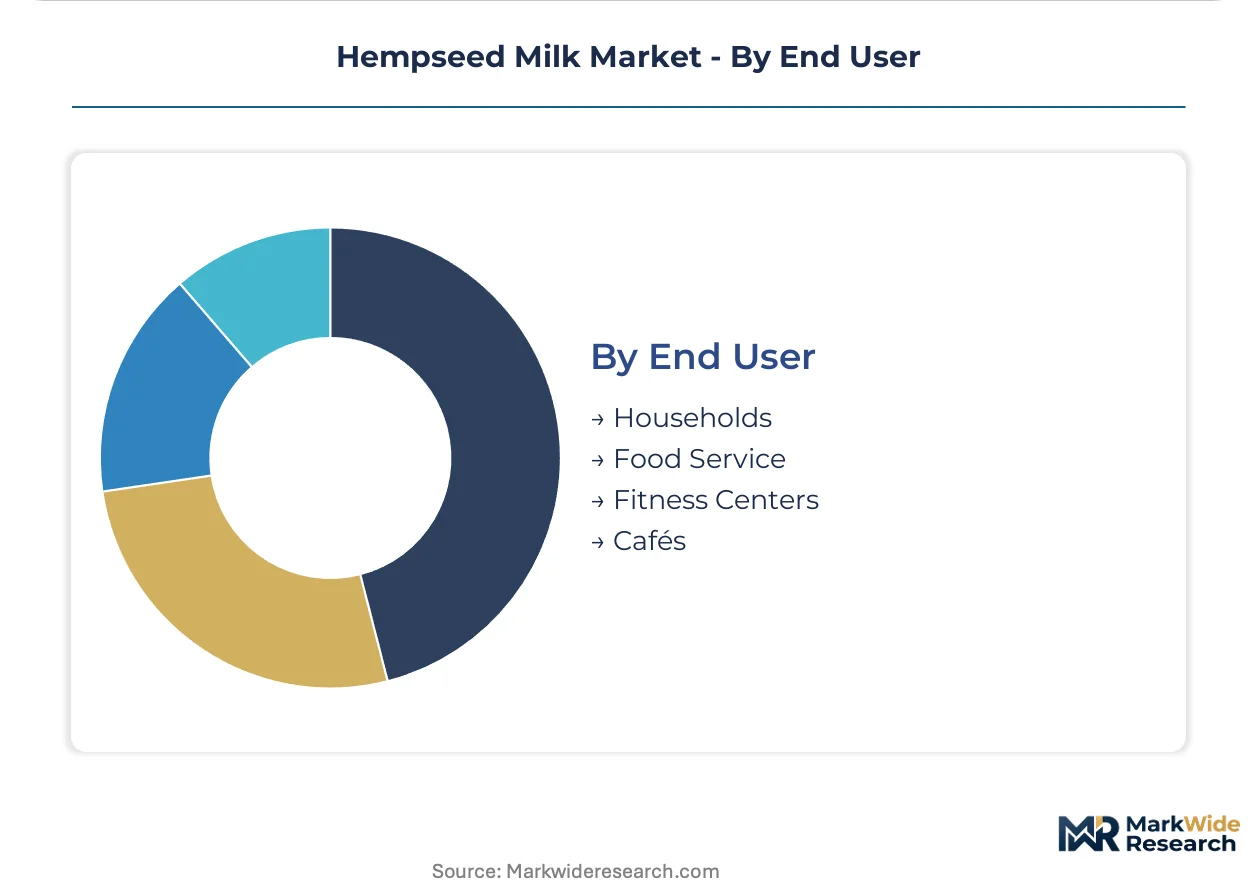
- Households:Bulk purchasing of unsweetened multi-serve containers dominates residential consumption in German and Dutch urban centers. Refrigerated storage constraints limit adoption in smaller European apartments.
- Food Service:Specialty coffee chains in Melbourne and Copenhagen now specify hempseed milk by foam-ability grade rather than brand name. Third-wave cafés grade alternatives on micro-foam stability and latte art definition.
- Fitness Centers:Post-workout retail channels in California and Colorado show unserved demand for high-protein, electrolyte-fortified formulations.
- Cafés:Berlin and Hamburg coffeehouses drove early adoption through vegan and flexitarian consumer clustering. Cold-brew chains in Portland and Austin specify HPP-treated base liquids for house-made hemp lattes.
Households anchor installed capacity; fitness centers are expanding most quickly as protein fortification technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian Prairie provinces supply the bulk of raw shelled hemp seed, while consumption clusters concentrate in Germany, the United States, and select Asian markets. This production-consumption divide shapes logistics costs and regulatory compliance pathways across export corridors.
United States
California and Colorado households drive unsweetened formulation demand through natural grocery channels. The FDA oversees hemp ingredient safety under the Food Safety Modernization Act, creating compliance baselines for interstate commerce. Pacific Northwest cold-brew coffee chains specify HPP-treated hempseed milk base liquids for house-made lattes.
Germany
Berlin and Hamburg anchor European adoption among vegan and flexitarian consumer clusters. EFSA novel food authorization requirements have streamlined ingredient compliance pathways for hemp-derived products entering German retail. Bavarian health food stores curate hempseed milk alongside CBD and hemp protein SKUs in integrated plant-based sections.
Canada
Manitoba and Saskatchewan cultivation belts supply 70% of North American raw material, exposing processors to single-origin crop risk. Health Canada maintains 10ppm THC limits for hemp food products, shaping formulation standardization. Prairie province processors leverage backward integration into cultivation to secure organic certification timelines.
Japan
Tokyo and Osaka convenience stores stock single-serve chilled hempseed milk for urban grab-and-go occasions. METI recycling compliance adds packaging overhead for aluminum can formats targeting fitness channels. Kanto region vending operators trial electrolyte-fortified SKUs in post-workout retail locations.
Australia
Melbourne third-wave coffee shops grade hempseed milk alternatives on micro-foam stability and latte art definition. The TGA regulates hemp food imports with novel food assessments that parallel EFSA frameworks. Sydney natural grocery chains command premium shelf placement for certified organic formulations.
Hempseed Milk Market Competitive Landscape
Top-tier vendors anchor premium organic positioning, while mid-scale processors compete on food service channel access. The vendor base stratifies across three capability tiers: vertically integrated cultivator-processors, contract manufacturing specialists, and private-label formulators. Strategic archetypes include backward-integrated seed processors, Tetra Pak aseptic specialists, and clean-label extraction innovators. Dominant competitive moves span organic certification races and café channel specification capture.
Among North American cultivator-processors, Manitoba Harvest Hemp Foods and Pacific Foods of Oregon exemplify the backward-integrated archetype with Prairie province and West Coast manufacturing footprints respectively. Elmhurst 1925 occupies a position within the clean-label specialist tier, representing zero-additive extraction positioning. These three anchors illustrate how geographic concentration of raw material and processing infrastructure shapes competitive differentiation across organic and food service market segments.
| Leading Market Players |
|---|
| Pacific Foods of Oregon |
| Hudson River Foods |
| Good Hemp Food |
| Living Harvest Foods |
| Manitoba Harvest Hemp Foods |
| SunOpta |
| Good Mylk Co. |
| Elmhurst 1925 |
| California Natural Products |
| Others |
Supply & Pricing Matrix
USDA organic certification gates both qualified supply and premium-tier pricing access, forcing processors to absorb three-year cultivation transition costs before capturing the forty to sixty percent price premiums that natural grocery chains command. This regulatory threshold compresses margins for aspirants while erecting a barrier-to-entry moat for incumbents with certified acreage already in production.
Pricing Analysis
Margin tightening in standard-tier unsweetened formulations reflects input cost volatility from Canadian Prairie province crop yields. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels stratifies the market, with USDA certification and foam-stability performance grading as the primary differentiation drivers. Cost-down pressure on economy tiers accelerates because supermarket slotting fees absorb upstream savings. Food service buyers exhibit the lowest price sensitivity due to specification-by-performance contracts, while conventional supermarket shoppers drive the hardest volume discounts.
Supply Chain Analysis
Direct-to-food-service channels handle hyperscale café chain demand through dedicated tanker deliveries of HPP-treated base liquids. Raw material supply draws from Canadian Prairie provinces, German organic cooperatives, and Australian hemp cultivation belts. Critical dependencies include shelled hemp seed, high-pressure homogenization equipment, and REACH-compliant Tetra Pak barrier laminates. Single-source vulnerability concentrates in Manitoba and Saskatchewan cultivation zones that feed seventy percent of North American processing capacity. Distribution runs through temperature-controlled logistics networks for refrigerated cartons and ambient-stable aseptic corridors for Southeast Asian export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food authorization functions as a cost-of-compliance story, creating a barrier-to-entry moat for processors with parallel documentation capacity and EU regulatory affairs expertise.
For Market Incumbents: Acquire certified organic cultivation acreage to lock in premium-tier supply security before three-year transition timelines elongate. Deepen backward integration into Canadian Prairie province seed processing to defend against crop failure volatility and capture margin pools currently paid to third-party suppliers. Prioritize in-house high-pressure homogenization technician training to reduce poaching vulnerability from dairy alternative competitors. For New Entrants and Emerging Players: Begin with fitness center vending channels in California and Colorado where electrolyte-fortified flavored SKUs face unserved demand and lower slotting fee barriers than supermarkets. Target Tetra Pak ambient distribution partnerships for Southeast Asian markets lacking cold-chain infrastructure, using extended shelf-life formulations to bypass refrigerated logistics investments that incumbents have already sunk. For Investors and Strategic Acquirers: USDA organic certification completion announcements are the leading indicator that a processor has cleared the highest-margin tier's entry barrier and can sustain pricing power. Five-to-ten year viability favors vertically integrated cultivator-processors with captive supply of certified seed and in-house HPP capacity. Monitor EFSA novel food approval timelines as the signal for European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cultivation | Captures organic price premiums and insulates supply from Prairie province crop volatility. |
| HPP Equipment Deployment | Preserves complete protein integrity for café foam-stability specifications and extends refrigerated shelf life. |
| EFSA Novel Food Parallel Filing | Compresses cross-border registration timelines and unlocks German retail channel access. |
| Tetra Pak Aseptic Line Qualification | Enables Southeast Asian market entry where cold-chain infrastructure remains underdeveloped. |
| Fitness Center Vending SKU Development | Addresses unserved post-workout demand in Colorado and California with electrolyte-fortified formulations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this hempseed milk market assessment. Primary interviews with food service procurement directors, Tetra Pak packaging engineers, organic certification auditors, and hemp cultivation cooperative managers validated demand assumptions and supply constraints. Secondary sources included Health Canada THC threshold enforcement records, EFSA novel food submission databases, USDA organic handler certificates, and refrigerated logistics rate indices. Bottom-up volume modeling by SKU and channel triangulated against top-down category spend estimates from natural grocery retail audits.
Segment-level granularity modeled product type, packaging format, distribution channel, and end-user application across the projection horizon. CAGRs derived from historical volume trajectories, elasticity-adjusted price forecasts, and channel penetration curves. Industry-specific inputs incorporated hemp seed yield volatility from Prairie province agricultural statistics, HPP equipment capacity expansion pipelines, and café chain menu specification surveys from Berlin, Melbourne, and Portland.
Underlying measurement precision varies by segment; unsweetened household formulations and Tetra Pak ambient distribution carry tighter precision than emerging fitness center vending channels. Forecasts reflect assumptions about EFSA authorization streamlining, THC threshold enforcement stability, and cold-chain infrastructure development in target export markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Dairy-Free Ice Creams Market