
 US Lactose-Free Dairy Market | 2026-2036
US Lactose-Free Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
US Lactose-Free Dairy Market Insights
USDA Organic certification is collapsing the window for new entrants without established supplier networks or multi-year conversion timelines. Chobani leverages its Greek yogurt infrastructure to dominate lactose-free cultured product lines. Danone S.A. competes through specialized fermentation protocols that yield clean-label, low-lactose formulations. Organic Valley sustains cooperative-scale procurement across Upper Midwest farms, anchoring its supply base against commodity volatility.
US lactose-free dairy comprises fluid milk, fermented products, and fresh cheeses treated with lactase enzyme to hydrolyze disaccharide sugars into glucose and galactose, yielding digestible nutrition for hypolactasic consumers while preserving conventional taste and mouthfeel. The primary commercial purpose is to retain dairy-category spending from households that would otherwise migrate to plant-based alternatives. Milk remains the volume anchor within product type segmentation, though yogurt commands disproportionate margin contribution due to premium positioning and shorter production cycles. Online retail represents the fastest-growing distribution channel, while supermarkets still control the majority of household purchase occasions through dedicated cold-chain shelf sets.
FDA nutrition labeling standards and USDA organic requirements jointly govern ingredient declarations, enzyme processing disclosures, and animal welfare claims that shape consumer trust and retail access. State-level dairy compacts in Wisconsin and New York impose additional fluid milk grading protocols that affect interstate shipment eligibility for lactose-free variants. Stakeholders must monitor evolving FDA guidance on fermentation-derived enzymes and state enforcement of dairy identity standards to anticipate reformulation costs and label revision timelines.
Market Dynamics
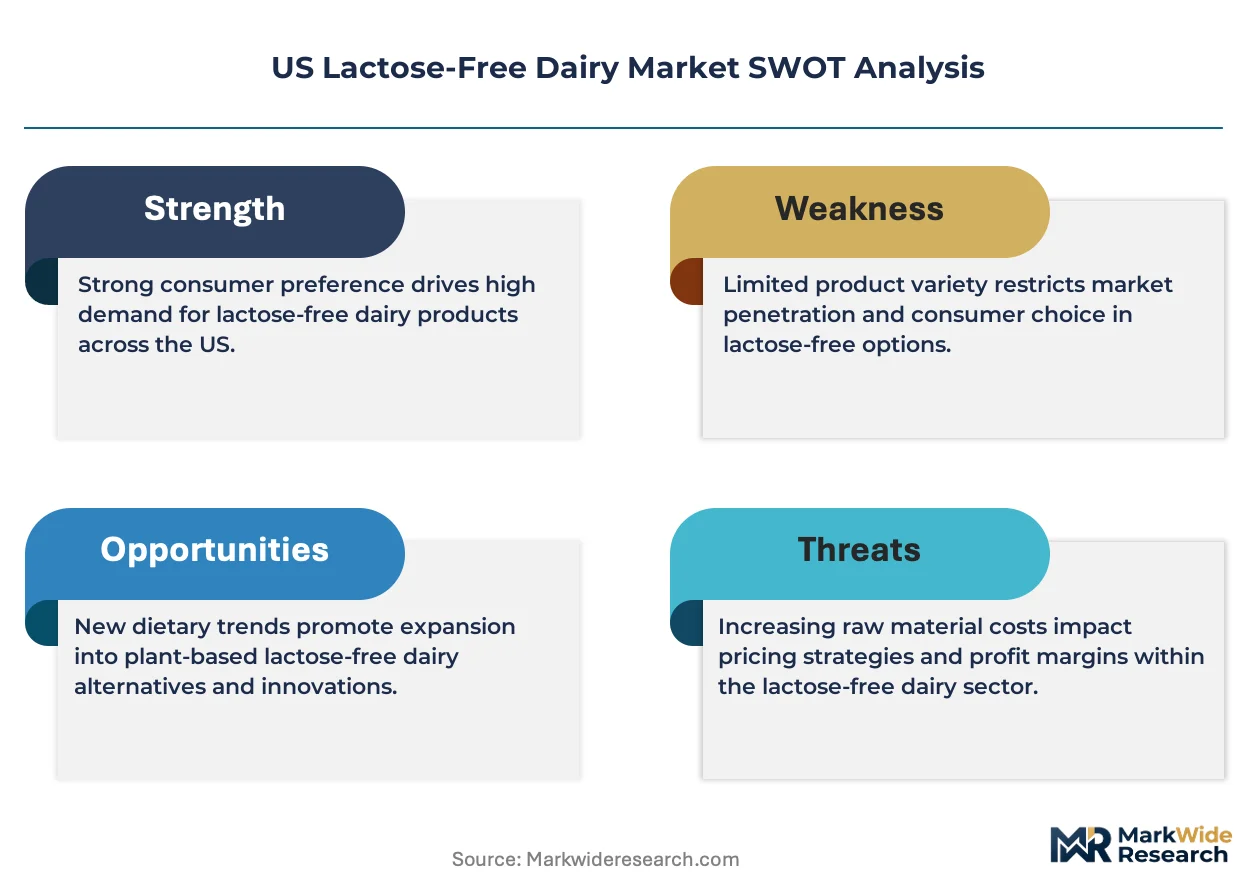
FDA labeling rules for plant-adjacent dairy alternatives are pressuring conventional lactose-free brands to sharpen positioning claims. This regulatory friction is compressing marketing windows and forcing enzymatic processing disclosures that reshape competitive differentiation.
Growth Catalysts
- Digestive wellness positioning:Mainstream shoppers without diagnosed lactose intolerance now purchase lactose-free SKUs for perceived gut health benefits. Grocery retailers are expanding dedicated cold-chain shelf sets to capture this broader demand pool.
- IRA bioenergy provisions:Federal incentives for anaerobic digesters on dairy operations reduce methane compliance costs. Upper Midwest cooperatives leverage these credits to stabilize organic milk premiums against commodity volatility.
- Enzymatic hydrolysis advances:Precision lactase dosing protocols now preserve protein structures previously degraded in thermal processing. This technology enables cleaner-label fluid milk with extended refrigerated shelf life.
Market Restraints
- Organic feed input costs:Non-GMO corn and soybean prices fluctuate with Midwest growing conditions. USDA Organic certification requires three-year land conversion timelines that lock in cost structures before revenue realization.
- California processing concentration:Fluid milk grading and enzymatic treatment capacity clusters in the Central Valley. Interstate shipment eligibility under state dairy compacts creates geographic supply vulnerabilities.
- Oat and almond substitution:Barista-formulated plant alternatives achieve price parity in foodservice channels. Younger demographics display weaker brand loyalty to dairy-origin products.
Strategic Opportunities
- Premium fresh cheese white space:Lactose-free mozzarella and ricotta remain underdeveloped versus fluid milk and yogurt. Artisan producers in Wisconsin and Vermont could capture margin through specialty retail and direct-to-restaurant supply.
- Direct-to-consumer cold-chain logistics:Subscription models bypass supermarket slotting fees and build recurring revenue. Northeast urban corridors show highest trial rates for home-delivered cultured products.
- Fermentation-derived enzyme approvals:FDA guidance updates on precision-fermentation lactase would unlock non-animal processing claims. Clean-label positioning would differentiate against traditional fungal-derived enzymes.
Industry Challenges
- Multi-year organic certification timelines:Conventional dairies face revenue gaps during land conversion. Cooperative pooling arrangements must absorb member farms through three-year transition periods.
- Cold-chain integrity at scale:Lactose-free products require tighter temperature controls than conventional dairy due to altered sugar profiles. Distributor network upgrades demand capital deployment ahead of volume justification.
- Enzyme supplier concentration:Commercial lactase production concentrates with three specialty chemical manufacturers. Formulation flexibility depends on negotiating supply security with limited alternative sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Lactose-Free Dairy Market |
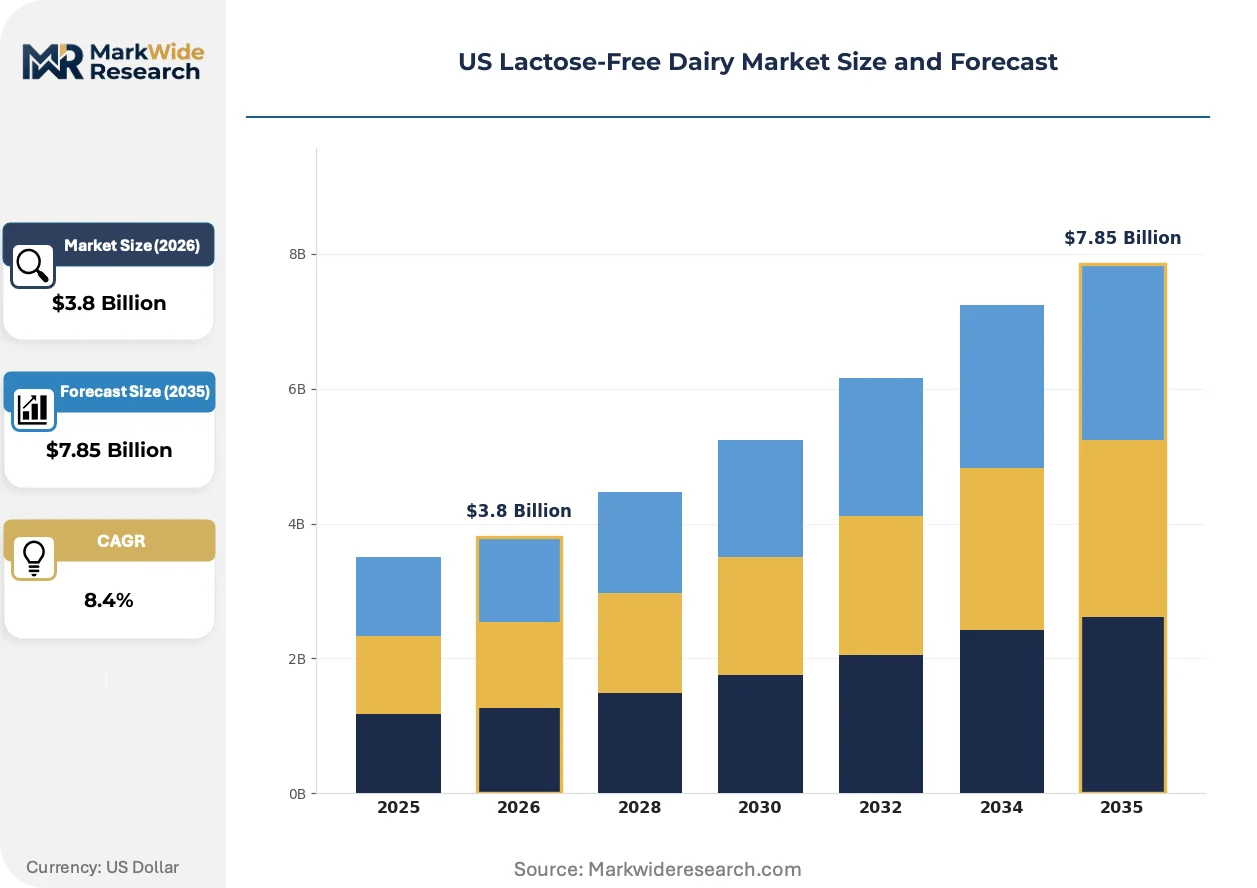
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Cream Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores End User: Households, Restaurants, Cafes, Institutions Packaging Type: Bottles, Cartons, Tetra Packs, Cups |
| Companies Covered | Dairy Farmers of America, Fage, The Coca-Cola Company, Prairie Farms Dairy, Land O'Lakes, Inc., Nestlé S.A., Chobani, Organic Valley, Danone S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Lactose-Free Dairy Market Trends and Innovations
Precision fermentation and enzymatic processing advances are redefining what lactose-free dairy can claim on label and deliver on taste. These technical shifts intersect with regulatory pressure and channel evolution to reshape competitive positioning.
Precision-fermentation lactase is supplanting traditional fungal-derived enzymes in premium formulations. Clean-label brands in the Northeast and California are adopting this technology fastest. The shift enables animal-free processing claims that command shelf space in Whole Foods and specialty retail.
FDA nutrition labeling standards for plant-adjacent dairy alternatives are forcing enzymatic disclosure specificity. Brands must now distinguish lactose-free claims from dairy-free positioning on front-of-package. Fluid milk processors in Wisconsin and New York face compressed reformulation timelines to maintain retail access.
Online subscription models for cultured products are disrupting conventional supermarket purchase patterns. Direct-to-consumer channels capture higher lifetime value through recurring delivery of yogurt and kefir. Urban California households show strongest adoption, with Northeast metropolitan areas following.
US Lactose-Free Dairy Market Segmentation
Channel dynamics in US lactose-free dairy vary sharply by product form and purchase occasion. Supermarket cold-chain infrastructure still governs fluid milk volume, while online platforms capture trial-heavy yogurt subscriptions. Understanding where each segment concentrates demand reveals margin architecture and capital deployment priorities.
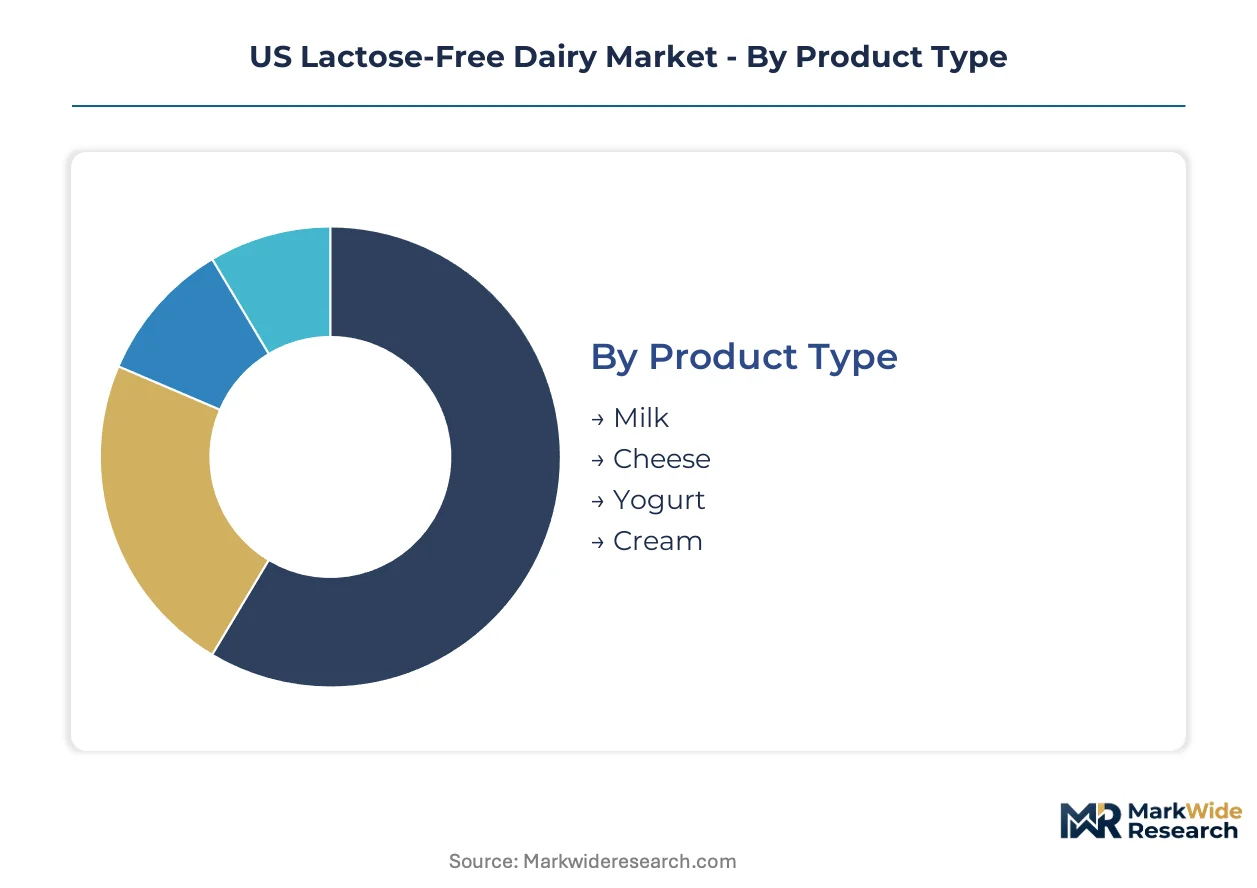
Product Type:
Fluid milk commands the highest absolute tonnage through grocery retail, though margin profiles diverge dramatically across enzymatically treated formats. Channel placement determines price realization more than formulation cost in this category.
- Milk:Lactase-hydrolyzed fluid milk retains the category's volume anchor, with enzymatic processing converting lactose into glucose and galactose for hypolactasic consumers. California and Northeast urban corridors drive demand through dedicated supermarket cold sets, though refrigerated shelf-life constraints limit direct-to-consumer penetration.
- Yogurt:Greek and traditional cultured products achieve premium pricing through shorter production cycles and probiotic positioning. Chobani's Upstate New York fermentation infrastructure dominates lactose-free cultured supply, with Northeast metropolitan households showing highest subscription trial rates.
- Cheese:Fresh mozzarella and ricotta remain underdeveloped versus fluid applications, with enzymatic treatment complexity slowing Wisconsin artisan scale-up.
- Cream:Coffee-service and home cooking applications concentrate demand in urban California markets with specialty retail access.
Milk dominates installed base. Yogurt is where expansion concentrates.
Distribution Channel:
Cost tier stratification separates mass-market accessibility from premium convenience positioning. Capital requirements for cold-chain integrity scale non-linearly with channel sophistication.
- Supermarkets:Dedicated lactose-free shelf sets in Kroger, Safeway, and regional banners control household replenishment purchases. Slotting fees and refrigerated logistics favor established processors with multi-SKU negotiating leverage.
- Online Retail:Subscription models for cultured products bypass supermarket margin extraction, with recurring delivery capturing lifetime value in Boston, New York, and San Francisco metropolitan areas. Cold-chain packaging costs currently constrain fluid milk viability.
- Health Stores:Whole Foods and regional co-ops prioritize precision-fermentation enzyme claims and organic certification, commanding 15-30% price premiums over conventional retail.
- Convenience Stores:Single-serve yogurt and flavored milk concentrates in travel corridors and college towns, with limited lactose-free SKU penetration outside major metropolitan catchments.
Supermarkets anchor volume throughput. Online retail is gaining share fastest.
End User:
Application requirements dictate formulation specifications and packaging formats across consumption occasions. Institutional procurement runs on annual contracts with stringent nutritional compliance.
- Households:Weekly replenishment of fluid milk and multi-pack yogurt drives supermarket velocity, with digestive wellness claims expanding purchase incidence beyond diagnosed intolerance.
- Restaurants:Wisconsin and Vermont artisan cheese producers supply white-tablecloth accounts with lactose-free fresh mozzarella, though foodservice penetration lags retail.
- Cafes:Barista-formulated oat alternatives compete directly for coffee-service cream positioning, pressuring lactose-free dairy to demonstrate foam stability and neutral flavor.
- Institutions:School districts and healthcare facilities in California and New York specify lactose-free fluid milk for nutritional compliance, with USDA commodity programs influencing procurement.
Households dominate consumption volume. Restaurants represent the steepest expansion trajectory.
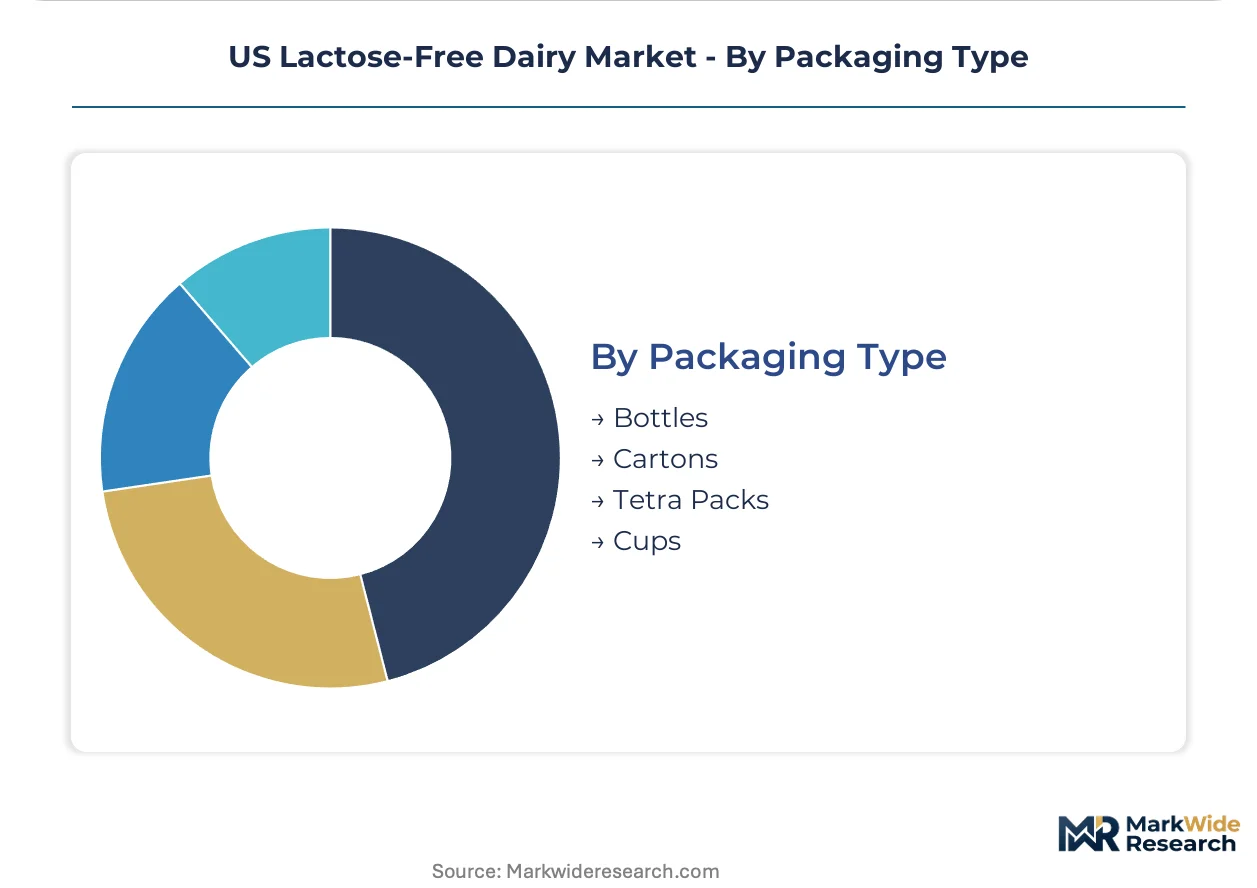
Packaging Type:
Supply concentration in Midwest converting facilities shapes format availability and cost structures. Material specifications interact with FDA enzyme disclosure requirements.
- Bottles:HDPE and PET formats dominate fluid milk in retail cold cases, with California processors preferring square-shoulder designs for logistics efficiency.
- Cartons:Gable-top paperboard maintains cost advantage for half-gallon and gallon milk in conventional supermarkets.
- Tetra Packs:Aseptic processing enables ambient distribution for UHT-treated lactose-free milk, extending reach in convenience and emergency stock-up channels.
- Cups:Single-serve polypropylene dominates yogurt portion control, with Northeast dairy cooperatives investing in in-mold labeling for premium differentiation.
Cartons govern fluid milk economics. Bottles retain premium positioning strength.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban households with diagnosed lactose intolerance and wellness-motivated mainstream buyers concentrate demand in coastal metropolitan corridors. FDA labeling enforcement and state dairy compacts create regulatory patchworks that processors must navigate. Interstate shipment eligibility hinges on compliance with fluid milk grading protocols in major producing states.
California
Los Angeles and San Francisco metropolitan areas drive premium lactose-free fluid milk and yogurt velocity through Whole Foods and specialty retail channels. California's state dairy compact enforces stringent fluid milk grading that affects enzymatically treated product eligibility for interstate commerce. Central Valley processing clusters concentrate lactase treatment capacity, creating geographic supply vulnerabilities during heat events.
Northeast Corridor
Boston, New York, and Philadelphia urban households show highest subscription trial rates for direct-to-consumer cultured products. FDA nutrition labeling rules for plant-adjacent alternatives pressure regional processors to clarify enzymatic processing disclosures on front-of-package claims. Upstate New York fermentation infrastructure anchors lactose-free Greek yogurt supply for metropolitan distribution.
Upper Midwest
USDA Organic certification timelines lock Wisconsin and Minnesota cooperatives into three-year land conversion commitments before revenue realization. IRA bioenergy provisions for anaerobic digesters reduce methane compliance costs for member farms in Organic Valley's cooperative network. Madison and Minneapolis-St. Paul serve as procurement and processing hubs for organic lactose-free fluid milk.
Southeast
Atlanta and Miami metropolitan areas represent underpenetrated demand for premium lactose-free fresh cheese relative to fluid milk saturation. State-level dairy identity standards in Florida and Georgia create additional label revision requirements for enzymatically treated products. Charlotte and Nashville emerge as distribution nodes for refrigerated logistics networks serving expanding supermarket shelf sets.
Pacific Northwest
Seattle and Portland consumers prioritize precision-fermentation enzyme claims and organic certification in health store channels. Regional cooperatives leverage shorter supply chains to maintain cold-chain integrity for cultured products with altered sugar profiles. Portland's specialty food manufacturing base supports artisan scale-up for lactose-free fresh mozzarella targeting white-tablecloth restaurant accounts.
US Lactose-Free Dairy Market Competitive Landscape
Player mix skews toward diversified dairy conglomerates with existing fermentation infrastructure and cooperative-scale organic networks. Consolidation around Greek yogurt specialists and national beverage companies creates tiered competitive dynamics. Two strategic archetypes dominate: vertically integrated dairy cooperatives with captive organic supply, and multinational CPG platforms leveraging beverage distribution networks. Capacity expansion in enzymatic treatment facilities and strategic partnerships for precision-fermentation enzyme sourcing represent the dominant competitive moves.
Within the cooperative archetype, Organic Valley and Land O'Lakes, Inc. occupy positions anchored by member-farm procurement networks across the Upper Midwest. Among multinational platforms, Danone S.A. and Nestlé S.A. exemplify scale-driven market presence through diversified dairy and beverage portfolios. Chobani represents the specialized fermentation infrastructure archetype, with Upstate New York operations supporting lactose-free cultured product supply. These three company groupings illustrate how competitive positioning depends on supply base control, processing technology access, and channel reach rather than single-vector differentiation.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Fage |
| The Coca-Cola Company |
| Prairie Farms Dairy |
| Land O'Lakes, Inc. |
| Nestlé S.A. |
| Chobani |
| Organic Valley |
| Danone S.A. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day refrigerated shelf-life constraints for enzymatically treated fluid milk compress working capital cycles and amplify pricing power for processors with captive cold-chain infrastructure. This inventory velocity differential separates national cooperatives from regional bottlers and shapes margin capture across USDA organic and conventional tiers.
Pricing Analysis
Cost-plus contracts indexed to Chicago Mercantile Exchange Class III milk futures dominate procurement between Upper Midwest cooperatives and retail banners. Pricing stratifies across premium, standard, and economy tiers based on USDA Organic certification and precision-fermentation enzyme claims. Cost compression in conventional fluid milk intensifies as barista-formulated oat alternatives achieve foodservice price parity. Quick-service restaurants and institutional buyers exhibit highest price sensitivity, while Northeast metropolitan households purchasing direct-to-consumer cultured products show lowest elasticity.
Supply Chain Analysis
The United States anchors fluid milk grading and enzymatic treatment capacity, with California's Central Valley and Wisconsin's Madison corridor hosting concentration. Raw material flows draw from non-GMO corn and soybean inputs for organic feed, lactase enzymes from three specialty chemical manufacturers, and HDPE packaging from Midwest converting facilities. Single-source vulnerability in precision-fermentation lactase supply creates formulation inflexibility during FDA guidance transitions. Distribution runs through supermarket cold-chain networks for replenishment purchases, with direct-to-consumer subscription models bypassing slotting fees in Boston, New York, and San Francisco metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in this market rests on scarce fermentation infrastructure and three-year organic certification timelines that lock out opportunistic entrants. Processor scale and cooperative procurement networks function as the binding constraints on expansion.
For Market Incumbents: Secure multi-year supply agreements with precision-fermentation enzyme suppliers before FDA guidance updates reshape clean-label claims. Expand Upstate New York and Central Valley treatment capacity to capture Northeast and California demand concentration. Vertical integration into anaerobic digester installations under IRA bioenergy provisions reduces methane compliance costs and stabilizes organic milk premiums against commodity volatility. For New Entrants and Emerging Players: Lead with premium fresh cheese white space in Wisconsin and Vermont artisan channels, where lactose-free mozzarella and ricotta remain underdeveloped versus fluid milk saturation. Target direct-to-consumer subscription models in Northeast urban corridors, where highest trial rates for home-delivered cultured products bypass supermarket slotting barriers. Position on precision-fermentation enzyme claims to command Whole Foods shelf space against conventional fungal-derived formulations. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative-scale procurement networks and fermentation infrastructure face finite expansion paths. Acquisition targets include Upper Midwest organic dairies mid-conversion through USDA three-year timelines, where revenue gaps create distressed entry valuations. Watch FDA guidance updates on fermentation-derived enzymes as the signal for clean-label differentiation premiums to widen or compress.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Enzyme Partnership | Unlocks non-animal processing claims for Whole Foods and specialty retail shelf access. |
| Direct-to-Consumer Cold-Chain Buildout | Bypasses Kroger and Safeway slotting fees while capturing recurring revenue in Boston and San Francisco. |
| Organic Certification Timeline Acquisition | Secures Upper Midwest supply base with completed three-year land conversion before revenue realization. |
| Anaerobic Digester Infrastructure Deployment | Leverages IRA bioenergy credits to stabilize organic milk premiums against Class III futures volatility. |
| Fresh Cheese Artisan Scale-Up | Captures margin through specialty retail and white-tablecloth restaurant supply in underpenetrated segments. |
Research Methodology
The analysis maps fluid milk, yogurt, cheese, and cream sub-sectors, each validated through cooperative procurement managers, enzymatic processing engineers, supermarket category buyers, and direct-to-consumer logistics operators. Primary interviews with USDA certification specialists and FDA regulatory affairs consultants combined with secondary validation from FDA labeling guidance documents, USDA organic program records, and Chicago Mercantile Exchange dairy futures data. Bottom-up volume modeling triangulated against top-down category spend estimates from Nielsen retail audit data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user application, and packaging format, with enzymatic processing technology tier as an industry-specific dimension. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity estimates, incorporating IRA bioenergy credit absorption rates and precision-fermentation enzyme adoption curves as forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of plant-adjacent dairy alternative labeling or abrupt shifts in organic feed input costs would require recalibration. Forecasts reflect documented assumptions regarding enzymatic treatment capacity expansion and cold-chain integrity maintenance. Recalibration cycles align with material shifts in FDA guidance updates, state dairy compact enforcement, and bioenergy credit program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Dairy Alternatives Market