
 Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market | 2026-2036
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market Foresight
South Africa's pharmaceutical manufacturing base is fragmenting as local production struggles to match import volumes of patented SGLT2 inhibitors. AstraZeneca leverages its cardiovascular outcome data to sustain premium positioning across private hospital chains in the Gulf. Boehringer Ingelheim anchors its regional presence through established partnerships with government tenders in Egypt and Saudi Arabia.
Sodium-dependent glucose co-transporter 2 inhibitors constitute a class of oral hypoglycemic agents that block glucose reabsorption in the proximal renal tubule by inhibiting SGLT2 protein function, thereby inducing glucosuria and reducing plasma glucose independent of insulin secretion. These agents serve primary clinical purposes in type 2 diabetes management while demonstrating proven cardiorenal protective effects that have expanded their therapeutic utility. Among product types, dapagliflozin and empagliflozin dominate prescription volumes due to established cardiovascular and chronic kidney disease indications that command preferential formulary placement. Tablet formulations lead delivery mode adoption given manufacturing simplicity and patient compliance advantages, though injectable alternatives are gaining traction in hospital settings where adherence monitoring is intensive.
Saudi Arabia's SFDA, South Africa's SAHPRA, and the UAE's Ministry of Health and Prevention collectively shape market access through varying bioequivalence requirements and pricing controls that delay generic entry while protecting originator revenue streams. Egypt's drug authority and Israel's Ministry of Health impose additional localization mandates that influence distribution strategies for multinational suppliers. Stakeholders must monitor evolving cardiorenal label expansions and tender pricing pressures as Gulf health systems consolidate procurement under national insurance frameworks.
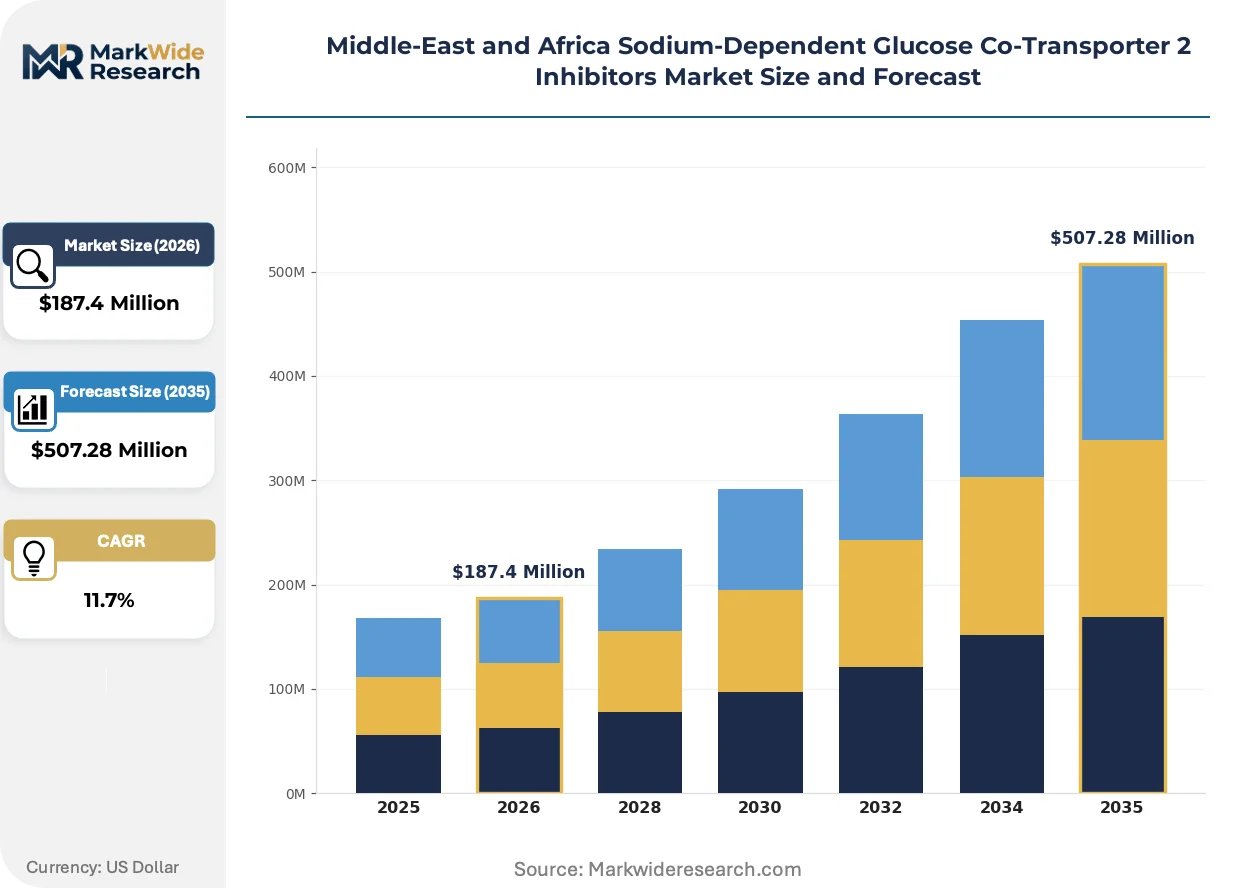
Market Dynamics
Cardiorenal label expansions for SGLT2 inhibitors are restructuring prescribing hierarchies across Middle-East and Africa health systems, as Saudi Arabia's SFDA and South Africa's SAHPRA prioritize therapies with proven heart failure and chronic kidney disease outcomes in national formularies.
Growth Catalysts
- SFDA Accelerated Pathways:Saudi Arabia's streamlined registration for cardiovascular-proven diabetes therapies compresses time-to-market for agents with EMPA-REG and DAPA-HF data, privileging hospital formulary placement.
- Specialized Diabetes Center Expansion:Gulf states are constructing dedicated cardiometabolic units that institutionalize SGLT2 inhibitor protocols for dual diabetes-heart failure management.
- Reimbursement Framework Evolution:National insurance schemes in the UAE and Saudi Arabia are expanding coverage beyond glycemic control to explicit cardiorenal indications, broadening eligible patient pools.
Market Restraints
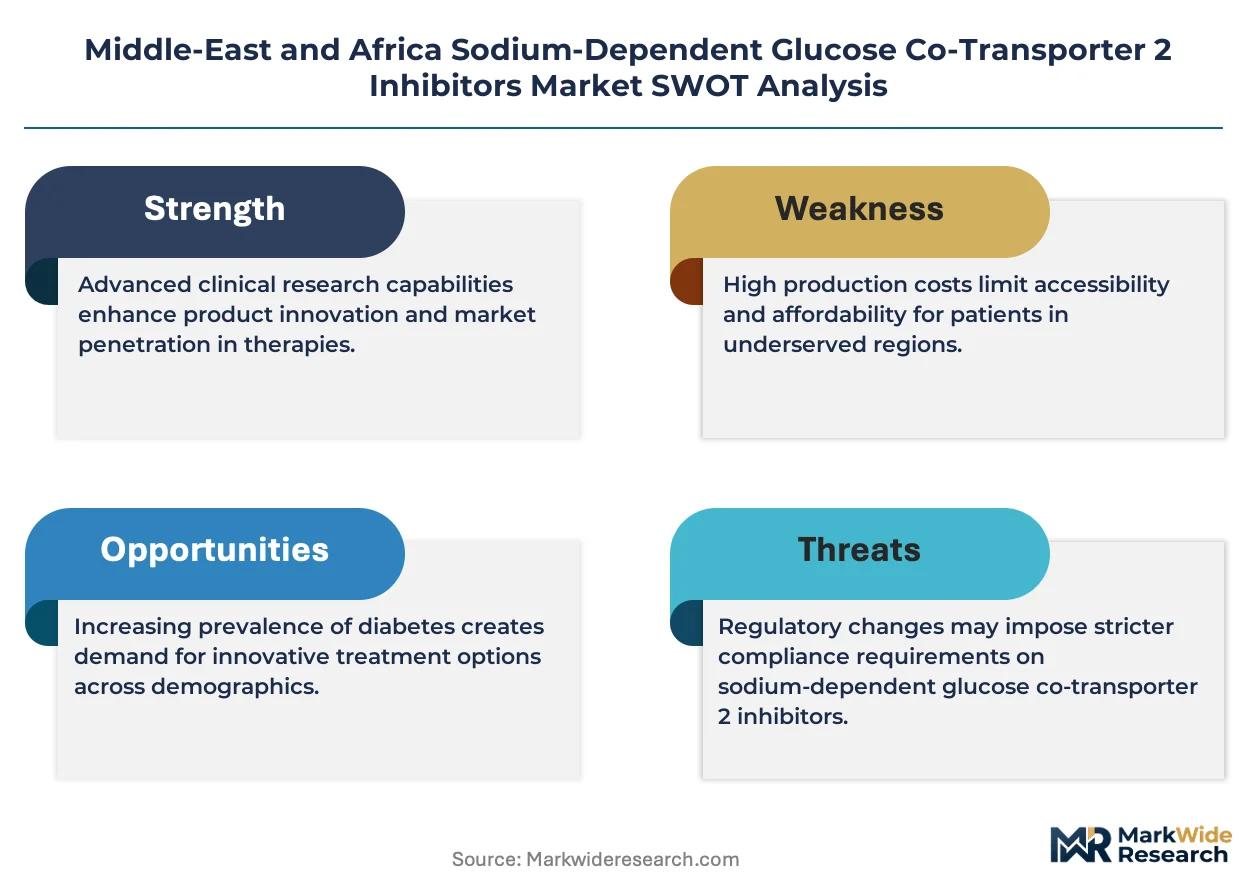
- Originator Patent Thickets:Compound and formulation patents on dapagliflozin and empagliflozin block generic entry, maintaining price premiums that strain public tender budgets in Egypt and Nigeria.
- Import Dependency:Local pharmaceutical manufacturing across South Africa and North Africa captures minimal SGLT2 inhibitor volume, exposing supply chains to currency volatility and shipping disruptions.
- Bioequivalence Stringency:SAHPRA and Israel's Ministry of Health impose complex pharmacokinetic study requirements that delay generic approvals and sustain originator market control.
Strategic Opportunities
- Underpenetrated Sub-Saharan Markets:Nigeria, Kenya, and Ethiopia present whitespace where diabetes prevalence is climbing but SGLT2 inhibitor access remains limited to private hospital tiers.
- Fixed-Dose Combination Expansion:SGLT2 inhibitor-metformin and SGLT2 inhibitor-GLP-1 receptor agonist combinations address polypharmacy burden in aging Gulf state populations with high comorbidity rates.
- Localization Mandates:Egypt's drug authority and Saudi Arabia's Vision 2030 pharmaceutical localization incentives create partnership pathways for multinational manufacturers to establish regional fill-finish operations.
Industry Challenges
- Specialized Prescriber Training:Endocrinology and cardiology specialists require updated protocols for SGLT2 inhibitor initiation in reduced ejection fraction patients, creating educational infrastructure demands that outpace medical society curriculum updates.
- Supply Chain Cold-Chain Integrity:Temperature-controlled distribution networks for SGLT2 inhibitor tablets remain underdeveloped in secondary cities across South Africa's Eastern Cape and Nigeria's northern states, risking product degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dapagliflozin, Empagliflozin, Canagliflozin, Ertugliflozin End User: Hospitals, Clinics, Pharmacies, Homecare Indication: Type 2 Diabetes, Cardiovascular Disease, Chronic Kidney Disease, Weight Management Delivery Mode: Tablets, Injectable, Oral Solution, Others |
| Companies Covered | Eli Lilly and Company, AstraZeneca, Boehringer Ingelheim, Janssen Pharmaceuticals, Bristol-Myers Squibb, Merck & Co., Johnson & Johnson Services, Glenmark Pharmaceuticals, Lexicon Pharmaceuticals, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market Shifts & Advancements
Digital therapeutics integration and real-world evidence generation are restructuring how SGLT2 inhibitors demonstrate value to Middle-East and Africa payers, moving beyond trial data to continuous outcomes monitoring.
Continuous glucose monitoring systems paired with SGLT2 inhibitor therapy are rendering obsolete traditional HbA1c-based titration protocols in Saudi Arabia's King Faisal Specialist Hospital network and Dubai's private diabetes chains. Endocrinologists in these institutions now adjust SGLT2 inhibitor dosing based on time-in-range metrics rather than quarterly lab values. This shift is compressing the interval between therapy initiation and cardiorenal outcome documentation.
SAHPRA's 2023 guidance on cardiovascular outcome trial requirements for new diabetes therapies is forcing manufacturers to submit regional subgroup analyses from existing mega-trials or conduct dedicated local studies. The industrial consequence is delayed registration for agents lacking Middle-East and Africa patient representation in original trial cohorts. Products with pre-existing Saudi and South African enrollment, such as those from AstraZeneca's DAPA-HF program, secure preferential formulary placement.
Hospital procurement departments across the Gulf are unbundling SGLT2 inhibitor purchasing from traditional broad diabetes portfolio contracts, creating standalone tender categories that reward cardiorenal outcome data over volume discounts. This disintermediation of bundled purchasing is most visible in Abu Dhabi's SEHA network and Saudi Arabia's National Unified Procurement Company, where separate cardiovascular and diabetes committees now independently evaluate SGLT2 inhibitor value propositions.
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market Segmentation
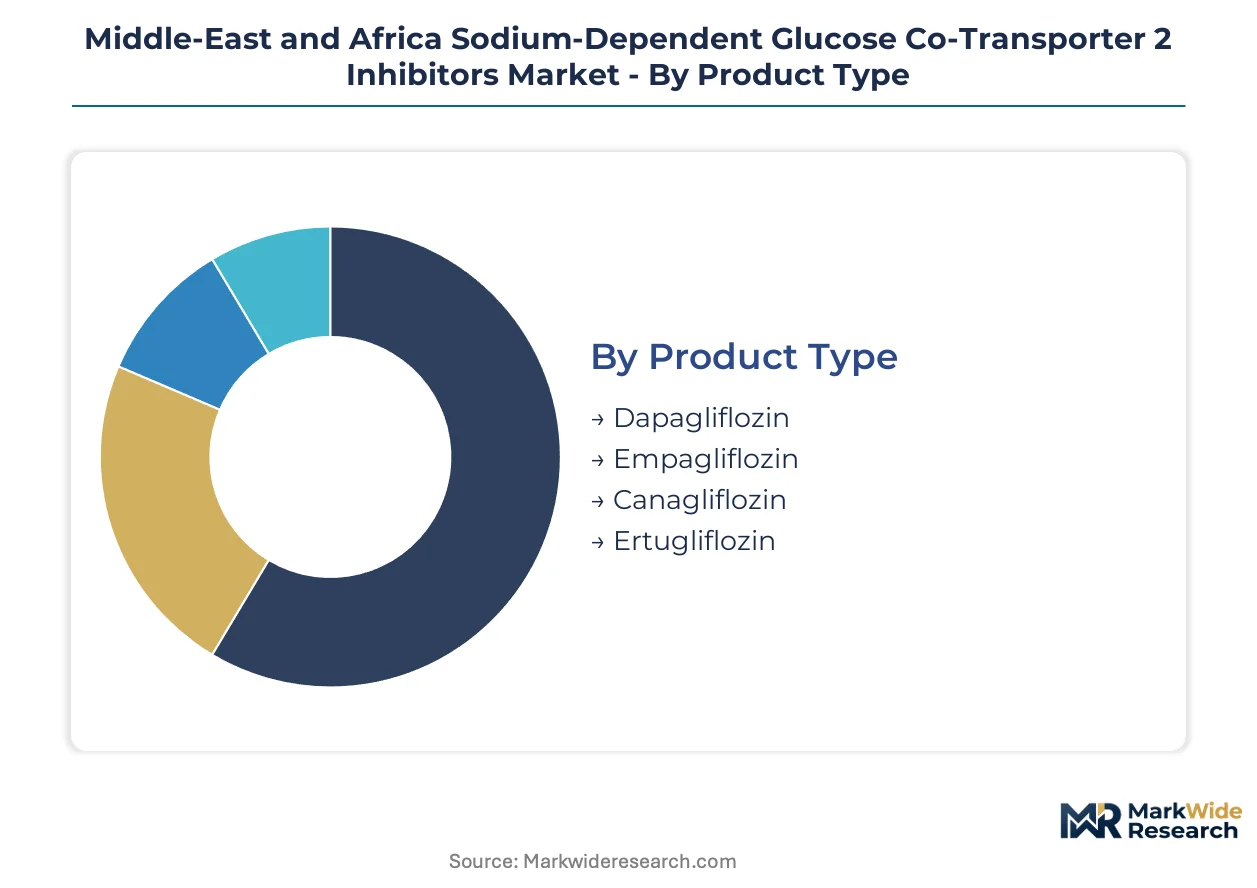
SGLT2 inhibitor segmentation across the Middle-East and Africa reflects divergent clinical priorities between Gulf state hospital systems and fragmented primary care networks in Sub-Saharan Africa. Prescribing patterns split between cardiorenal indication expansion in Saudi Arabia and South Africa versus glycemic-focused use in markets with limited specialist access.
Product Type:
Dapagliflozin and empagliflozin command distinct positioning based on cardiovascular outcome trial penetration across Saudi Arabia's SFDA-approved formularies and South Africa's SAHPRA reimbursement lists.
- Dapagliflozin:This SGLT2 inhibitor blocks renal glucose reabsorption through high-selectivity SGLT2 protein inhibition. Demand concentrates in Dubai's private hospital chains and Riyadh's National Guard Health Affairs facilities where DAPA-HF data drives heart failure protocol adoption.
- Empagliflozin:The agent demonstrates sustained glucosuric effect with established chronic kidney disease indications. Egyptian government tenders and Johannesburg's private cardiology practices prioritize this molecule for renal-protective prescribing in diabetic populations.
- Canagliflozin:This compound maintains formulary presence in UAE Ministry of Health and Prevention procurement frameworks despite amputation risk warnings limiting new initiations.
- Ertugliflozin:The newest entrant faces delayed registration across SAHPRA and Israel's Ministry of Health due to cardiovascular outcome study requirements.
The dominant share belongs to dapagliflozin, while empagliflozin is closing the gap fastest through chronic kidney disease label expansion.
End User:
Institutional prescribing hierarchies separate Gulf state centralized procurement from Nigeria's pharmacy-driven dispensing patterns.
- Hospitals:Cardiometabolic units in Saudi Arabia's National Unified Procurement Company network and Abu Dhabi's SEHA system institutionalize SGLT2 inhibitor protocols for dual diabetes-heart failure management. These facilities capture the majority of cardiorenal indication prescribing.
- Clinics:Outpatient diabetes centers across Kuwait's Dasman Diabetes Institute and South Africa's public health clinics manage stable patients with tablet-based SGLT2 inhibitor continuation.
- Pharmacies:Community dispensing in Morocco and Algeria handles refill prescriptions for established patients with limited specialist follow-up.
- Homecare:Nurse-administered SGLT2 inhibitor programs in Israel's Clalit Health Services support elderly patients with mobility constraints.
Hospital procurement commands the volume concentration, though pharmacy channels are expanding most quickly as Gulf states liberalize chronic disease medication dispensing.
Indication:
Label expansion beyond glycemic control is restructuring reimbursement eligibility across national insurance frameworks.
- Type 2 Diabetes:The foundational indication covers broad patient populations in Egypt's Health Insurance Organization and Jordan's public sector formularies.
- Cardiovascular Disease:Heart failure with reduced ejection fraction approvals in Saudi Arabia's SFDA guidelines and UAE reimbursement lists now drive specialist prescribing.
- Chronic Kidney Disease:Renal-protective indications are gaining traction in South Africa's private medical aid schemes and Israel's community nephrology practices.
- Weight Management:Obesity-focused prescribing remains off-label across most Middle-East and Africa markets pending regulatory clarification.
Cardiovascular disease indications are expanding share fastest, while type 2 diabetes retains the largest eligible population base.
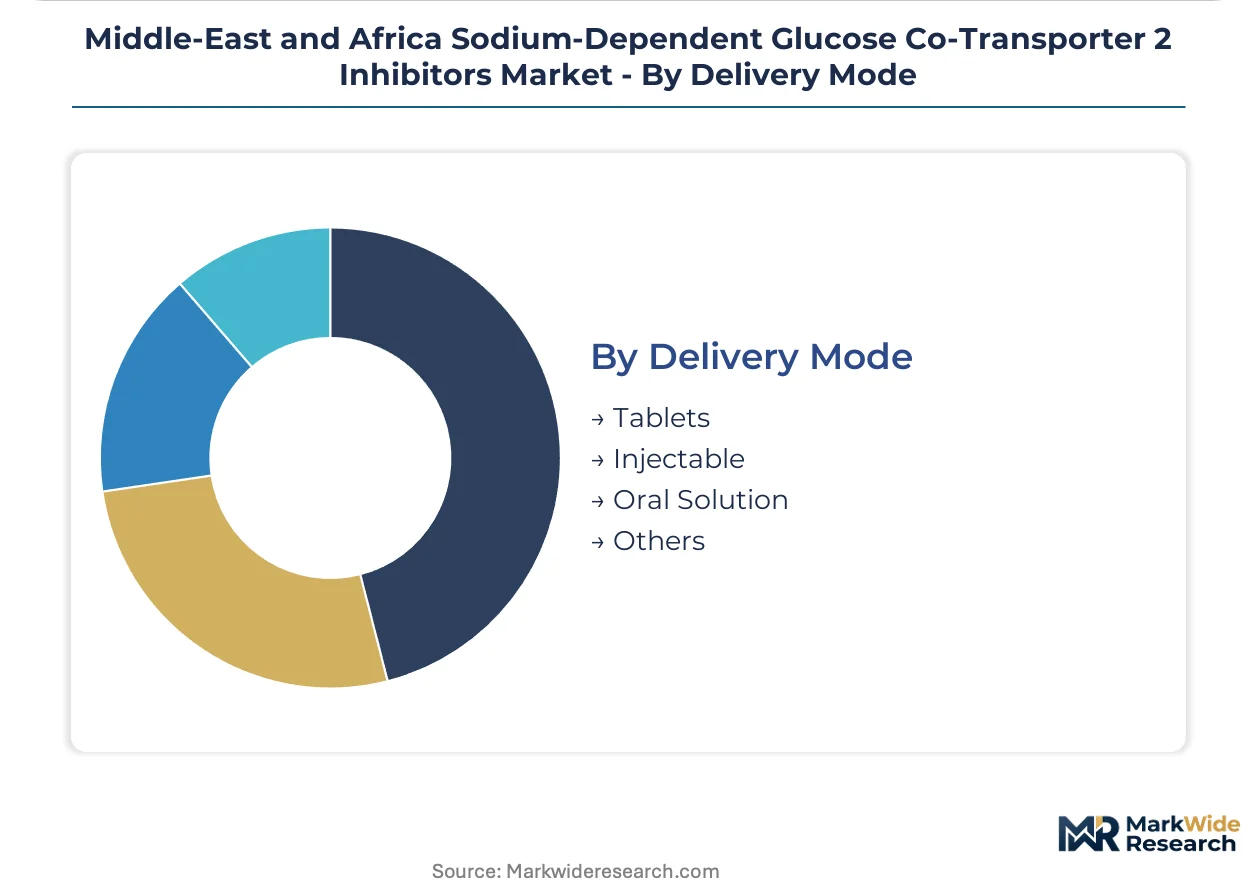
Delivery Mode:
Formulation choices reflect manufacturing scalability and cold-chain infrastructure limitations across the region.
- Tablets:Oral solid dosage forms dominate due to ambient storage stability and high-volume production economics. Saudi Arabia's local fill-finish partnerships and South African import channels prioritize tablet supply.
- Injectable:Hospital-administered formulations appear in ICU settings across Qatar's Hamad Medical Corporation for acute heart failure protocols.
- Oral Solution:Liquid formulations serve pediatric and geriatric populations in Lebanon's American University Hospital network where swallowing difficulties concentrate.
- Others:Novel delivery mechanisms remain investigational across Middle-East and Africa regulatory pathways.
Tablet formulations hold the installed base advantage, while oral solutions are gaining traction fastest in specialized geriatric and pediatric segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration pathways anchor Saudi Arabia's regional dominance, with cardiovascular-proven therapies securing accelerated formulary placement. Hospital procurement consolidation across Gulf states concentrates demand in Riyadh, Dubai, and Johannesburg clusters.
Saudi Arabia
King Faisal Specialist Hospital and National Guard Health Affairs drive empagliflozin and dapagliflozin prescribing for heart failure protocols. SFDA's streamlined cardiovascular outcome data requirements compress registration timelines for therapies with EMPA-REG and DAPA-HF evidence. The Riyadh cluster hosts the region's densest concentration of cardiometabolic units institutionalizing SGLT2 inhibitor protocols.
United Arab Emirates
Abu Dhabi's SEHA network and Dubai's private hospital chains separate cardiovascular and diabetes committee evaluations for SGLT2 inhibitor tenders. MOHAP procurement frameworks prioritize agents with chronic kidney disease indications in national insurance reimbursement lists. Dubai Healthcare City anchors specialist prescribing concentration for dual diabetes-heart failure management.
South Africa
Private medical aid schemes and Johannesburg cardiology practices prioritize renal-protective empagliflozin prescribing in diabetic populations. SAHPRA's bioequivalence study requirements delay generic entry and sustain originator market control. The Western Cape and Gauteng provinces concentrate specialist access, while Eastern Cape distribution infrastructure remains underdeveloped.
Egypt
Government tenders through the Health Insurance Organization cover broad type 2 diabetes populations with glycemic-focused SGLT2 inhibitor use. The national drug authority imposes localization mandates influencing multinational distribution strategies. Cairo and Alexandria clusters dominate procurement volume, with secondary city access limited by import dependency and currency volatility exposure.
Israel
Clalit Health Services operates nurse-administered SGLT2 inhibitor programs supporting elderly patients with mobility constraints. The Ministry of Health's pharmacokinetic study requirements for generic approvals sustain originator pricing power. Tel Aviv and Jerusalem medical centers concentrate cardiorenal indication prescribing, with community nephrology practices expanding chronic kidney disease label adoption.
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market Competitive Landscape
Capability concentration sits with cardiovascular outcome trial sponsors; scale advantage sits with hospital procurement consolidators. Saudi Arabia's National Unified Procurement Company and Abu Dhabi's SEHA network unbundle SGLT2 inhibitor purchasing from broad diabetes contracts, creating standalone tender categories. Three archetypes dominate: cardiovascular data originators, government tender partners, and generic pipeline builders. Strategic moves center on cardiorenal label expansion submissions and regional fill-finish localization partnerships.
Within the cardiovascular data originator tier, AstraZeneca and Boehringer Ingelheim occupy anchor positions. AstraZeneca leverages DAPA-HF program penetration across King Faisal Specialist Hospital and Dubai private chains. Boehringer Ingelheim sustains regional presence through Egyptian government tender relationships and Saudi National Guard Health Affairs partnerships. Eli Lilly and Company represents the GLP-1 receptor agonist combination vector, with fixed-dose development addressing Gulf state aging population polypharmacy burdens.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| AstraZeneca |
| Boehringer Ingelheim |
| Janssen Pharmaceuticals |
| Bristol-Myers Squibb |
| Merck & Co. |
| Johnson & Johnson Services |
| Glenmark Pharmaceuticals |
| Lexicon Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Import dependency on active pharmaceutical ingredients from India and China determines both the pricing tier spreads between originator and generic SGLT2 inhibitors and the supply chain shape across Middle-East and Africa markets. SFDA and SAHPRA bioequivalence requirements amplify this dependency by delaying local manufacturing scale-up and sustaining originator premium positioning.
Pricing Analysis
Price spreads between Saudi Arabia and Nigeria exceed threefold for equivalent dapagliflozin doses, reflecting divergent reimbursement frameworks and tender consolidation levels. Three-tier pricing structure across premium originator, licensed generic, and unbranded import levels stratifies the market, with cardiovascular outcome data commanding brand premiums in Gulf hospital chains. Pricing pressure stems from Egyptian government tender compression and currency volatility exposure in Nigerian private import channels. Public sector buyers in Cairo and Johannesburg exhibit highest price sensitivity, while Riyadh's National Unified Procurement Company prioritizes clinical data over unit cost.
Supply Chain Analysis
Upstream API manufacturing concentrates in India, China, and select European facilities, with intermediates for SGLT2 inhibitor synthesis drawing from specialized chemical producers in Gujarat and Zhejiang provinces. Key inputs include C-glucoside precursors, fluorinated aromatic intermediates, and high-purity solvents subject to pharmaceutical-grade certification requirements. Single-source vulnerability runs through concentrated API supply from individual Indian manufacturing sites serving multiple regional formulation facilities. Distribution runs through temperature-controlled logistics networks anchored in Jeddah, Dubai, and Johannesburg, with secondary city penetration limited by cold-chain infrastructure gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiorenal label expansion represents a high-growth disruption reshaping competitive positioning, with SFDA and SAHPRA cardiovascular outcome requirements creating regulatory moats that privilege trial-proven therapies over glycemic-only competitors.
For Market Incumbents: Build clinical data moats through regional subgroup enrollment in ongoing cardiorenal outcome trials. Secure hospital formulary lock-in via dedicated cardiometabolic unit partnerships at King Faisal Specialist Hospital and SEHA network facilities. Defend against generic erosion by accelerating fill-finish localization under Saudi Vision 2030 pharmaceutical incentives.
For New Entrants and Emerging Players: Build out white-space presence in Sub-Saharan diabetes centers where SGLT2 inhibitor penetration remains below Gulf state levels. Target Kenya and Ethiopia hospital procurement channels before cardiovascular outcome requirements harden into mandatory registration barriers. Enter through fixed-dose combination formulations addressing polypharmacy burdens in aging Gulf populations.
For Investors and Strategic Acquirers: The market sits at a label-expansion phase that favors cardiovascular data originators over glycemic-focused followers. Long-term viability hinges on cardiorenal indication breadth and hospital procurement consolidation capture. Prioritize acquisition targets with established SFDA registration and National Unified Procurement Company contract relationships. Watch SAHPRA generic bioequivalence guidance revisions as inflection signal for originator pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Enrollment | Regional patient representation in DAPA-HF and EMPA-REG protocols secures SFDA accelerated pathway access. |
| Hospital System Partnership | Direct procurement relationships with SEHA and National Guard Health Affairs institutionalize protocol-driven prescribing. |
| Localization Manufacturing Partnership | Saudi fill-finish operations under Vision 2030 incentives reduce import dependency and currency exposure. |
| Fixed-Dose Combination Development | SGLT2 inhibitor-metformin pairings address polypharmacy compliance in Gulf state aging populations. |
| Reimbursement Strategy Expansion | Chronic kidney disease indication submissions to MOHAP and SAHPRA broaden national insurance eligibility. |
Research Methodology
Operator-level perspectives from hospital formulary directors, cardiology department heads, pharmaceutical procurement managers, and regulatory affairs specialists anchored the qualitative base. These primary insights combined with secondary validation from SFDA registration databases, SAHPRA approval records, ClinicalTrials.gov cardiovascular outcome trial filings, and Gulf state hospital procurement disclosures. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated demand estimates across the analysis window.
Scenario-bracketing around regulatory approval timelines, reimbursement expansion trajectories, and generic entry assumptions structured the forecast framework. Segmentation dimensions modeled include product molecule, indication category, delivery formulation, end-user facility type, and country-specific regulatory cluster. CAGRs derived from prescription volume growth curves adjusted for cardiorenal label expansion pace and hospital procurement consolidation rates. Forecast inputs incorporated SFDA accelerated pathway utilization rates and SAHPRA bioequivalence study completion timelines.
Stress conditions across currency volatility exposure, API supply disruption scenarios, and tender pricing compression bands were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cardiovascular outcome data requirements and national insurance reimbursement evolution. Cross-checking against hospital procurement database trend lines and pharmaceutical import customs records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Respiratory Disease Vaccine Market