
 Global Acyclovir Market | 2026-2036
Global Acyclovir Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acyclovir Market Analysis
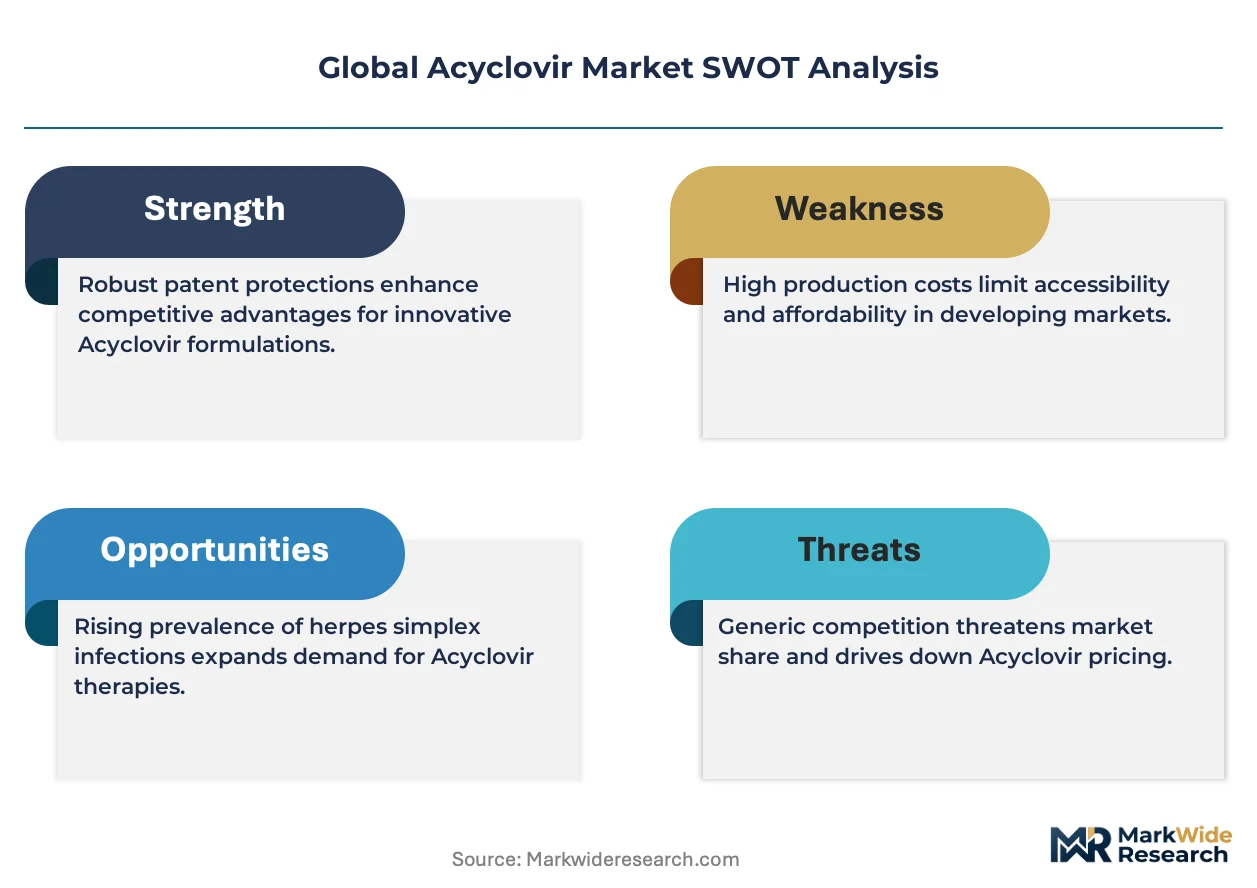
Pharmaceutical-grade USP specification acyclovir is collapsing toward commodity pricing as Indian and Chinese API manufacturers scale crystallization capacity. GlaxoSmithKline plc anchors brand residual value in developed markets through its original Zovirax franchise heritage. Cipla Inc. leverages vertical integration from API to finished formulation across African and Southeast Asian tender markets. Teva Pharmaceutical Industries Ltd. competes on cost in the crowded oral tablet segment.
Acyclovir is a synthetic purine nucleoside analogue with the molecular formula C8H11N5O3, manufactured through multi-step organic synthesis involving acetylation and cyclization reactions, functioning as a chain terminator during viral DNA polymerase elongation to treat herpesvirus infections. The oral tablet formulation dominates volume consumption in hospital and clinic settings where high-dose regimens for varicella zoster remain standard. Injectable acyclovir concentrates margin pools in ICU and immunocompromised patient segments where bioavailability demands override cost sensitivity. Topical creams and ointments occupy a mature niche with limited growth but stable pharmacy channel replenishment cycles.
FDA bioequivalence standards for generic acyclovir tablets shape US market access timelines, while India's CDSCO and BIS frameworks govern API export certification for domestic manufacturers. The WHO prequalification program and EMA's variation procedures for multisource antivirals create parallel compliance pathways that fragment registration strategies. Stakeholders must monitor whether FDA's emerging real-world evidence requirements for antiviral efficacy will tighten bioequivalence margins or sustain current generic substitution rates.
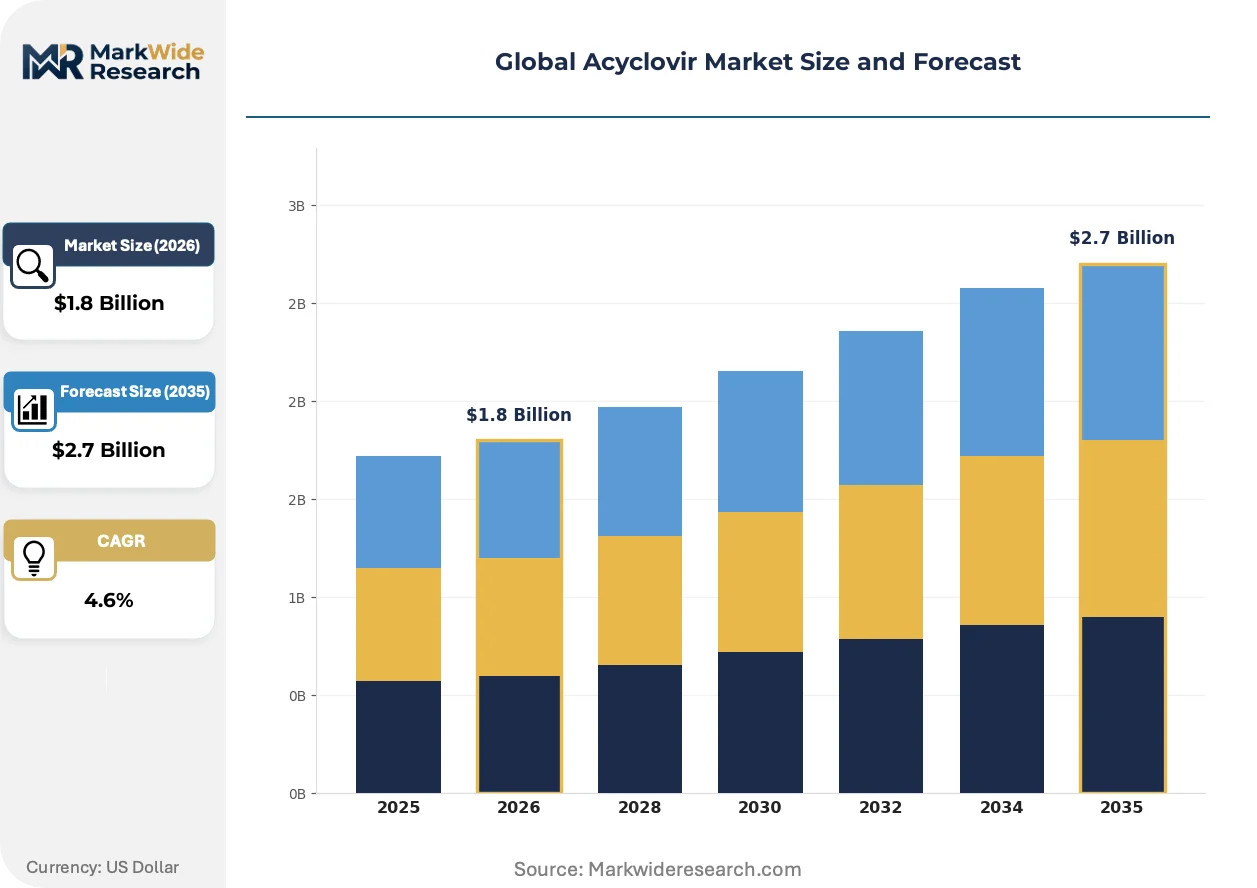
Market Dynamics
Indian API manufacturers have scaled crystallization capacity to capture pharmaceutical-grade acyclovir production, collapsing pricing toward commodity levels while WHO Essential Medicines List inclusion accelerates generic substitution mandates across public procurement systems.
Growth Catalysts
- WHO Essential Medicines List:Inclusion drives mandatory generic substitution policies in national health programs across Africa and Southeast Asia, expanding tender market access for multisource suppliers.
- Hospital-based HSV treatment protocols:High-dose intravenous regimens for immunocompromised patients in ICU settings sustain demand for injectable formulations where bioavailability requirements override cost sensitivity.
- Indian pharmaceutical manufacturing belt:Concentrated API production in Gujarat and Hyderabad clusters enables cost-competitive finished formulation exports to tender-dependent markets.
Market Restraints
- API supply concentration:Overreliance on Chinese and Indian acyclovir API manufacturers creates geopolitical and logistics vulnerability for European and North American formulators.
- Regulatory friction:FDA bioequivalence standards for generic acyclovir tablets impose lengthy ANDA approval timelines, delaying market entry for new suppliers.
- Substitution threat:Valacyclovir prodrug formulations offer improved oral bioavailability and reduced dosing frequency, displacing acyclovir in outpatient herpes zoster management.
Strategic Opportunities
- Brazilian public health expansion:ANVISA streamlined registration pathways for WHO-prequalified antivirals open tender access for generic acyclovir suppliers in Latin America's largest pharmaceutical market.
- Continuous manufacturing adoption:FDA's emerging real-world evidence framework for antiviral efficacy creates first-mover advantage for manufacturers investing in process analytical technology integration.
- Immunocompromised patient segments:Rising stem cell transplant volumes and oncology chemotherapy protocols expand addressable demand for prophylactic intravenous acyclovir in tertiary care centers.
Industry Challenges
- CDSCO export certification complexity:Indian API manufacturers face extended BIS specification alignment timelines for European Pharmacopoeia compliance, delaying shipment releases.
- EMA variation procedure fragmentation:Multisource antiviral registration across EU member states requires country-specific dossier adaptations, multiplying regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acyclovir Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical, Injectable, Oral, Ocular End User: Hospitals, Clinics, Homecare, Pharmacies Formulation: Creams, Tablets, Solutions, Ointments Distribution Channel: Direct Sales, Online, Retail, Wholesalers |
| Companies Covered | Aurobindo Pharma Limited, Cipla Inc., GlaxoSmithKline plc, Pfizer Inc., Fresenius Kabi AG, Teva Pharmaceutical Industries Ltd., Novartis AG, Zydus Cadila, Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acyclovir Market Emerging Trajectories
Process intensification and regulatory data modernization are restructuring how acyclovir API is manufactured, certified, and procured across divergent market tiers.
Continuous flow chemistry is decomposing traditional batch acyclovir synthesis by enabling real-time reaction monitoring and reduced solvent consumption. Mid-scale Indian API manufacturers are piloting microreactor installations to compress cycle times and improve yield consistency. This technology is decomposing the cost advantage held by legacy batch-reactor incumbents with sunk capital in conventional multi-step organic synthesis infrastructure.
EMA's variation procedures for multisource antivirals are tightening post-approval change management requirements for API manufacturing site transfers. European generic formulators must now submit enhanced stability data for crystallinity polymorph specifications. Suppliers targeting EU tender markets are responding by pre-positioning dedicated regulatory affairs teams in Brussels and Amsterdam to accelerate variation response cycles.
Hospital procurement consortia in Germany and France are consolidating antiviral purchasing through centralized tender platforms, compressing supplier negotiation cycles from annual to quarterly rhythms. Traditional wholesale distribution channels face margin compression as direct manufacturer-to-hospital contracts displace intermediary stocking arrangements. This pattern is most visible in German university hospital networks where GPOs now capture over half of injectable acyclovir volume.
Global Acyclovir Market Segmentation
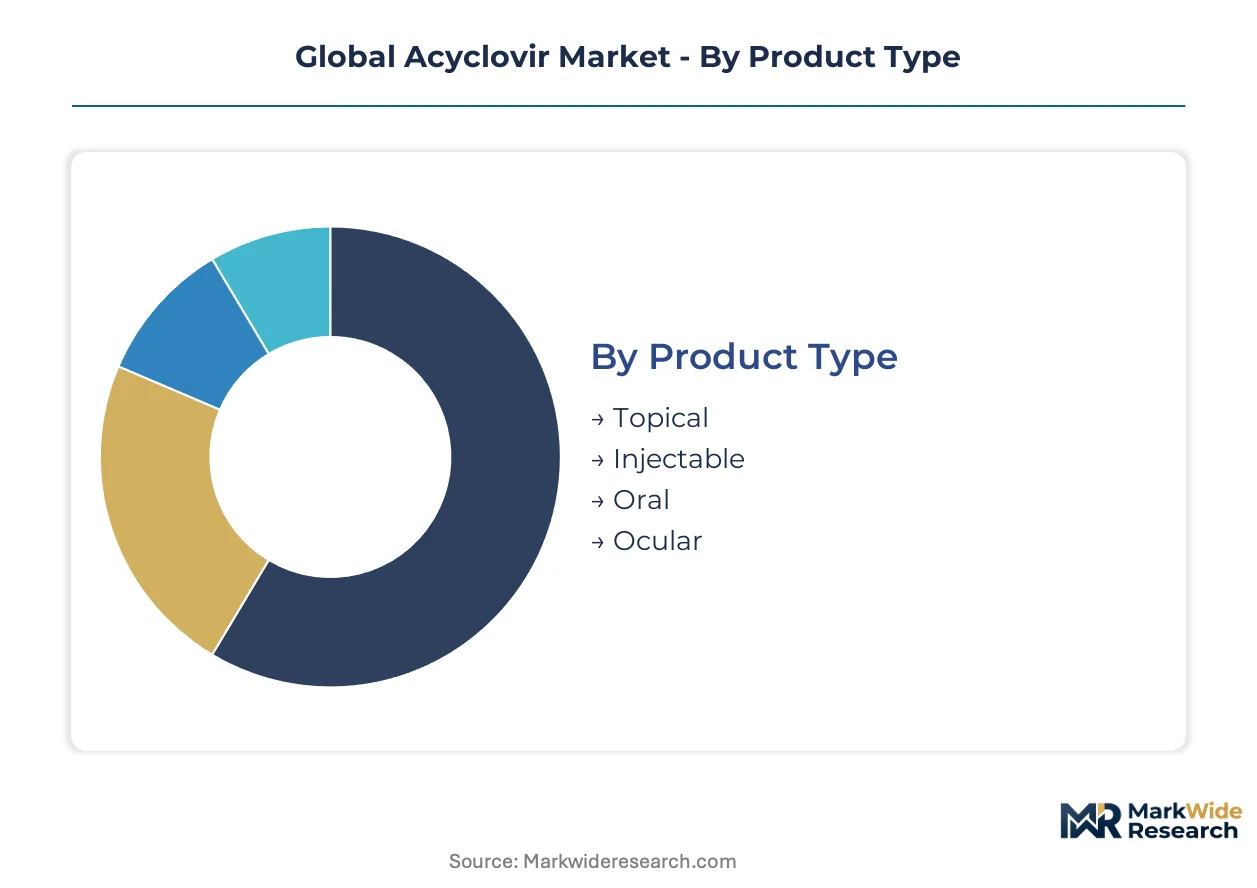
Acyclovir segmentation reveals divergent margin economics across administration routes and procurement channels. Injectable concentrates capture premium pricing in ICU settings where bioavailability demands override cost sensitivity, while oral tablets compete on commodity economics in high-volume tender markets.
Product Type:
Margin pools concentrate in parenteral formulations where manufacturing complexity and cold-chain requirements sustain pricing power, while topical and oral segments compete on scale economies.
- Injectable:Lyophilized powder for reconstitution requires aseptic manufacturing and terminal sterilization validation. Demand concentrates in tertiary care centers across Germany, France, and the United States where immunocompromised patient protocols mandate intravenous delivery for encephalitis and disseminated zoster.
- Oral:Compressed tablets and capsules dominate volume consumption through multi-source generic substitution policies. India's pharmaceutical manufacturing belt supplies cost-competitive finished formulations to African and Southeast Asian tender markets where WHO Essential Medicines List inclusion drives procurement mandates.
- Topical:Semisolid creams and ointments occupy mature pharmacy replenishment cycles with limited pipeline innovation.
- Ocular:Specialized ophthalmic preparations serve narrow herpetic keratitis indications with restricted formulary access.
Injectable holds installed capacity. Oral is rotating up the share rankings.
End User:
Procurement authority and reimbursement frameworks determine segment profitability, with institutional buyers extracting volume discounts unavailable to retail channels.
- Hospitals:Centralized purchasing consortia in German university networks and French public hospital systems consolidate antiviral procurement through quarterly tender platforms. GPOs now capture over half of injectable acyclovir volume, displacing traditional wholesale intermediaries.
- Clinics:Outpatient herpes zoster management in United States urgent care centers and Indian polyclinics drives oral tablet dispensing where valacyclovir prodrug substitution threatens acyclovir share.
- Homecare:Self-administered oral regimens for recurrent genital herpes suppression align with pharmacy benefit manager formularies in North American markets.
- Pharmacies:Community dispensing of topical formulations sustains stable replenishment cycles with limited generic price erosion.
Hospitals command procurement leverage. Clinics are expanding fastest as point-of-care diagnosis improves.
Formulation:
Physical form dictates manufacturing capital intensity and regulatory pathway complexity, with solutions requiring specialized containment infrastructure.
- Tablets:Immediate-release and sustained-release oral solid dosage forms dominate commercial volume. FDA bioequivalence standards for generic acyclovir tablets impose lengthy ANDA approval timelines, consolidating supply among established filers with validated dissolution profiles.
- Solutions:Intravenous infusion bags and oral suspensions serve pediatric and dysphagic patient populations where swallowing impairment precludes solid dosing. Manufacturing requires dedicated liquid filling lines and endotoxin-controlled water systems.
- Creams:Oil-in-water emulsions for cutaneous herpes labialis compete in over-the-counter and prescription channels with limited differentiation.
- Ointments:Hydrocarbon-based semisolids deliver occlusive therapy for localized lesions with slower absorption kinetics.
Tablets anchor production scale. Solutions are climbing fastest as home infusion expands.
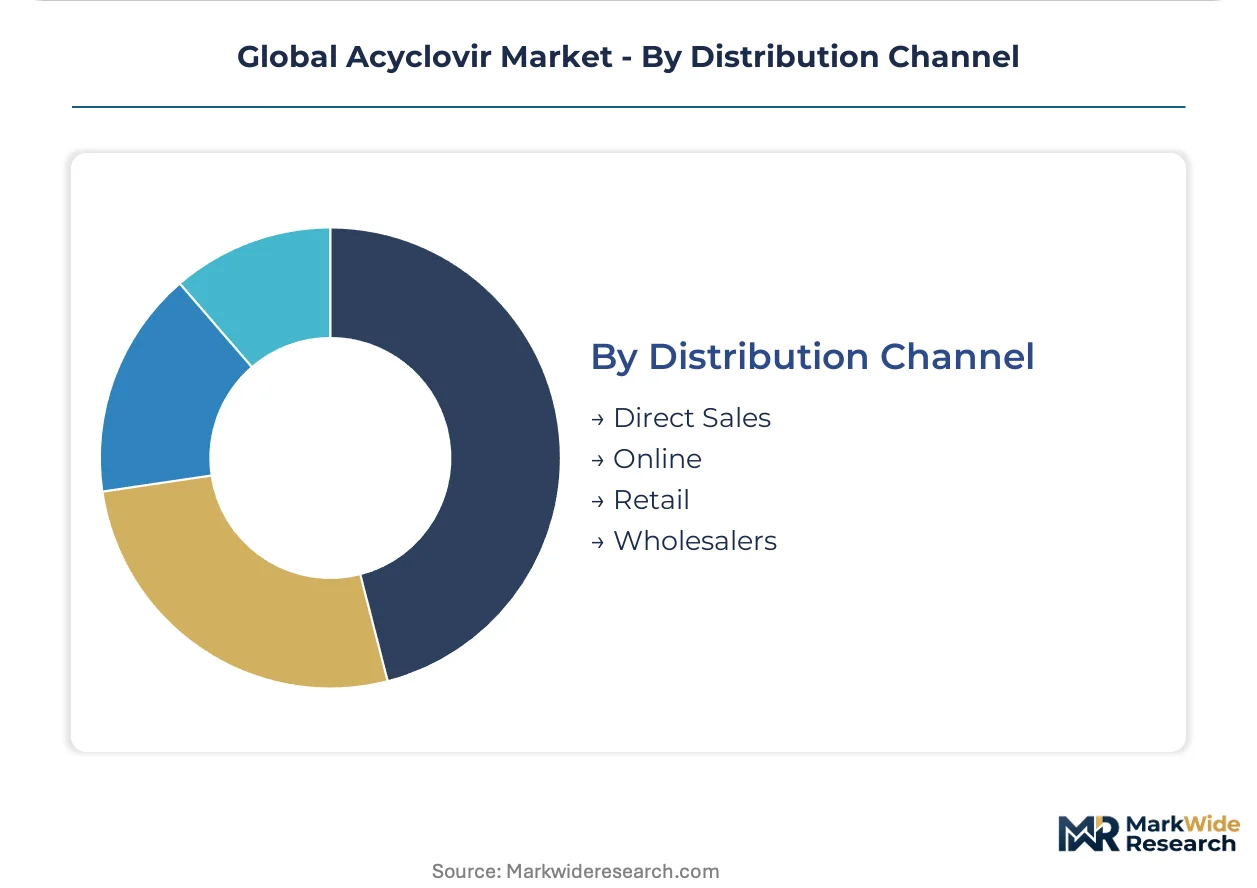
Distribution Channel:
Channel selection determines working capital requirements and price realization, with direct contracts bypassing distributor markups.
- Direct Sales:Manufacturer-to-hospital agreements in German and French procurement consortia compress negotiation cycles and displace intermediary stocking arrangements. Teva Pharmaceutical Industries and Cipla leverage dedicated institutional sales forces for tender participation.
- Wholesalers:Three-tier distribution through national and regional pharmaceutical wholesalers serves fragmented pharmacy and clinic demand across India's domestic market and Latin American territories.
- Retail:Community pharmacy stocking of topical and oral formulations sustains replenishment-driven revenue with limited forward commitment.
- Online:Telehealth-integrated prescription fulfillment and direct-to-consumer platforms expand in United States and United Kingdom markets where regulatory frameworks permit remote consultation for recurrent herpes management.
Direct sales capture margin. Online is gaining share fastest as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese API manufacturers control crystallization capacity for pharmaceutical-grade acyclovir, creating supply dependencies for European and North American formulators. Hospital procurement consortia in Germany and France now consolidate antiviral purchasing through quarterly tender platforms, compressing supplier margins.
United States
FDA bioequivalence standards for generic acyclovir tablets impose lengthy ANDA approval timelines, consolidating supply among established filers with validated dissolution profiles. The IRA prescription drug pricing provisions create uncertainty for branded residual value in outpatient herpes zoster management. New Jersey and Pennsylvania host injectable formulation facilities serving tertiary care centers where immunocompromised patient protocols mandate intravenous delivery.
Germany
University hospital networks capture over half of injectable acyclovir volume through GPO-negotiated direct contracts displacing wholesale intermediaries. EMA variation procedures for multisource antivirals tighten post-approval change management requirements for API manufacturing site transfers. The Rhine-Ruhr pharmaceutical cluster anchors formulation finishing for European tender markets with dedicated regulatory affairs teams in Brussels accelerating variation response cycles.
India
WHO Essential Medicines List inclusion drives mandatory generic substitution policies in national health programs across Africa and Southeast Asia, expanding tender market access for multisource suppliers. CDSCO export certification complexity creates extended BIS specification alignment timelines for European Pharmacopoeia compliance, delaying shipment releases. Gujarat and Hyderabad manufacturing belts enable cost-competitive finished formulation exports through vertical integration from API to tablet production.
Brazil
ANVISA streamlined registration pathways for WHO-prequalified antivirals open tender access for generic acyclovir suppliers in Latin America's largest pharmaceutical market. Public health expansion programs prioritize antiviral procurement for immunocompromised patient populations in São Paulo and Rio de Janeiro tertiary care centers. The São Paulo pharmaceutical corridor concentrates formulation finishing capacity serving Mercosur distribution networks.
China
NMPA oversight of acyclovir API export certification governs crystallization capacity expansion for pharmaceutical-grade specifications. Dual carbon goals pressure energy-intensive organic synthesis operations in Shandong and Jiangsu chemical parks, raising compliance costs for batch-reactor incumbents. The Yangtze River Delta API manufacturing cluster scales continuous flow chemistry pilot installations to compress cycle times and improve yield consistency.
Global Acyclovir Market Vendor Landscape
Concentration sits with Indian API-to-formulation integrators and legacy Western innovators defending brand residual value in developed markets. The vendor base stratifies across three tiers: vertically integrated API manufacturers capturing tender economics, multinational generics competing on cost in oral tablet segments, and original innovators anchoring premium positioning in injectable ICU applications. Strategic moves center on continuous manufacturing adoption for FDA real-world evidence frameworks and regulatory affairs pre-positioning for EMA variation acceleration.
Among Indian pharmaceutical specialists, Aurobindo Pharma Limited and Cipla Inc. exemplify API-to-formulation vertical integration archetypes, while GlaxoSmithKline plc occupies a position representing legacy brand heritage in developed market hospital segments. Teva Pharmaceutical Industries Ltd. sits within the scale-driven multinational generic tier competing on cost in crowded oral tablet segments. These three anchors illustrate divergent competitive positioning across tender-dependent emerging markets, premium injectable ICU applications, and commodity oral substitution economics.
| Leading Market Players |
|---|
| Aurobindo Pharma Limited |
| Cipla Inc. |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Fresenius Kabi AG |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Zydus Cadila |
| Mylan N.V. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Indian API manufacturers and European formulators lock in crystallization capacity access while capping price volatility for pharmaceutical-grade acyclovir. These arrangements tether procurement costs to raw material input indices, insulating buyers from spot-market swings in guanine derivative pricing.
Pricing Analysis
FDA bioequivalence standards dictate the pricing tier structure across oral tablet segments, separating validated ANDA filers from pending entrants. WHO prequalification status commands premium positioning in African and Southeast Asian tender markets where procurement mandates favor certified suppliers. Cost compression in the oral tablet segment is intensifying because Indian manufacturers are scaling crystallization capacity. Hospital procurement consortia in Germany and France exhibit the lowest price sensitivity, while community pharmacies in India's domestic market face the highest.
Supply Chain Analysis
Strategic stockpiling preferences dominate hospital procurement consortia, while just-in-time inventory management characterizes retail pharmacy channels. Crystallization capacity concentrates in India, China, and the United States, with Gujarat and Hyderabad clusters anchoring API production. Manufacturing draws from guanine derivatives, acetic anhydride, and specialized solvent systems as core inputs. Single-source vulnerability persists for European formulators dependent on Indian API shipments. Distribution runs through direct manufacturer-to-hospital contracts in consolidated European markets and three-tier wholesale networks in fragmented Latin American territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital procurement consortia as German and French GPOs consolidate antiviral purchasing through quarterly tender platforms, extracting volume discounts unavailable to fragmented retail channels.
For Market Incumbents: Secure backward integration into crystallization capacity to defend against API supply disruption risks from CDSCO export certification delays. Anchor hospital formulary positioning through dedicated regulatory affairs teams in Brussels, accelerating EMA variation response cycles against emerging continuous manufacturing adopters. For New Entrants and Emerging Players: Continuous manufacturing service gaps in FDA real-world evidence frameworks offer entry points for mid-scale API producers piloting microreactor installations. Brazilian ANVISA streamlined registration pathways represent the most penetrable geography. Target WHO prequalification status as the primary go-to-market credential for African tender access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among injectable formulation specialists serving immunocompromised patient protocols in tertiary care centers. Long-term viability hinges on regulatory data modernization capabilities and process analytical technology integration. Watch FDA emerging bioequivalence requirements for antiviral efficacy as the signal for margin compression or expansion in generic substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | FDA real-world evidence frameworks reward first-movers with accelerated ANDA pathways. |
| Backward Integration into API Production | Captive crystallization capacity insulates formulators from CDSCO certification delays. |
| WHO Prequalification Pursuit | Mandatory generic substitution policies in African tenders require this credential. |
| Regulatory Affairs Pre-positioning | Brussels-based teams compress EMA variation response cycles for EU market access. |
| Hospital GPO Direct Contracting | German university networks now capture over half of injectable acyclovir volume. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, hospital procurement managers, and API manufacturing executives, combined with secondary validation against FDA filings, EMA submissions, CDSCO export records, and WHO prequalification databases. Bottom-up volume estimates from crystallization capacity installations were triangulated against top-down tender market procurement data across African and Southeast Asian national health programs.
Across the analysis window, the forecasting framework modeled segmentation dimensions including administration route, procurement channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of crystallization capacity expansion and tender market penetration rates. Key inputs included hospital-based HSV treatment protocol adoption and immunocompromised patient population growth in tertiary care centers.
Underlying assumptions cover sustained WHO Essential Medicines List inclusion and stable API export certification timelines, with deviation risk concentrated in geopolitical disruption to Indian and Chinese manufacturing clusters. Revision becomes warranted when CDSCO BIS specification alignment timelines exceed thresholds that delay European Pharmacopoeia compliance shipments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Acetylspiramycin Market