
 Systemic Lupus Erythematous SLE Drugs Market | 2026-2036
Systemic Lupus Erythematous SLE Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Systemic Lupus Erythematous SLE Drugs Market Analytics
Biologics-grade manufacturing standards is bifurcating the competitive landscape between legacy small-molecule suppliers and cell-culture specialists. GlaxoSmithKline plc leverages its established rheumatology sales infrastructure to sustain physician access for its approved SLE therapy. F. Hoffmann-La Roche Ltd anchors its position through deep immunology R&D pipelines targeting interferon pathways. Aurinia Pharmaceuticals Inc. differentiates via nephrology-focused commercialization, occupying a narrow but high-need patient subset.
Systemic lupus erythematosus drugs encompass immunomodulatory and anti-inflammatory pharmaceutical agents formulated to suppress autoreactive B-cell proliferation, neutralize circulating immune complexes, and attenuate complement-mediated tissue damage in connective tissues and vital organs. These therapeutics function primarily to induce disease remission, prevent end-organ failure, and reduce corticosteroid burden in patients with heterogeneous autoimmune presentations. The biologics segment leads value generation due to premium pricing for targeted monoclonal antibodies, while immunosuppressants retain volume dominance as first-line induction therapy across cost-sensitive markets. Intravenous delivery commands the highest per-dose revenue in hospital settings, though subcutaneous formulations are gaining traction in homecare environments where patient convenience drives formulary preference.
The FDA, EMA, and WHO set divergent evidentiary standards for lupus trial endpoints, with the FDA emphasizing composite responder indices while EMA accepts organ-specific improvement measures. These regulatory frameworks directly shape Phase III trial design, determining which patient populations qualify for approval and subsequent reimbursement. Stakeholders must monitor how evolving biomarker-qualified surrogate endpoints reshape the competitive threshold for new molecular entities seeking accelerated pathways.

Market Dynamics
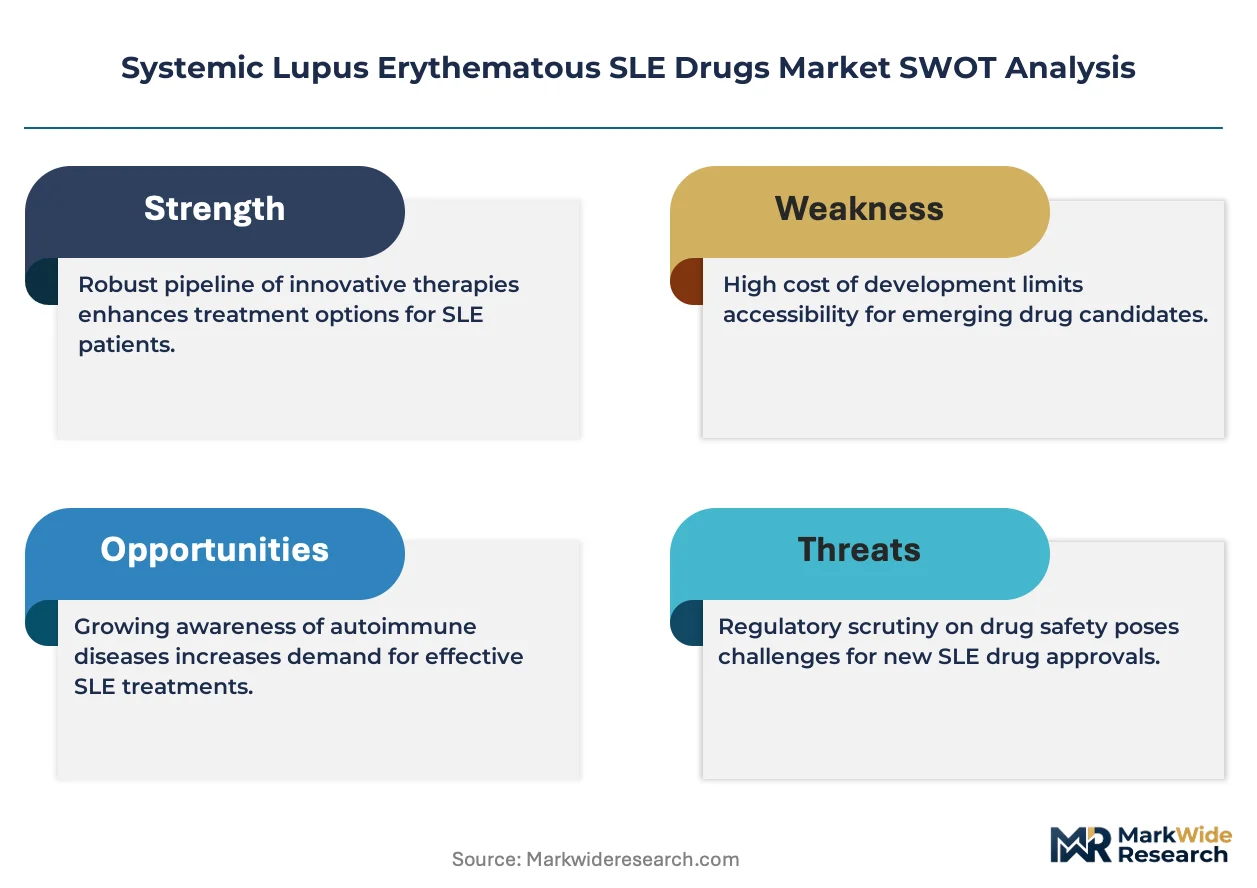
Accelerated FDA breakthrough designations for B-cell modulators and interferon pathway inhibitors are compressing Phase III timelines and reshaping how manufacturers prioritize pipeline assets against reimbursement benchmarks.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated approval pathway enables earlier market entry for novel biologics targeting refractory lupus nephritis, reducing development risk for sponsors.
- Biologic Infusion Capacity Expansion:Hospital-based rheumatology departments are building dedicated infusion centers to manage complex SLE patients requiring monoclonal antibody therapy.
- Type I Interferon Signature Stratification:Biomarker-driven patient selection improves trial responder rates and supports precision reimbursement negotiations with payers.
Market Restraints
- Plasma-Derived Raw Material Volatility:Biologics manufacturing depends on concentrated plasma supply chains with geographic concentration in the United States and Germany, creating input cost instability.
- EMA-FDA Endpoint Divergence:European regulators accept organ-specific improvement measures while FDA demands composite responder indices, forcing duplicate trial designs or delayed EU submissions.
- Corticosteroid Sparing Substitution:Generic immunosuppressants and long-standing corticosteroid regimens retain formulary preference in cost-sensitive markets, limiting biologic penetration.
Strategic Opportunities
- Subcutaneous Home Administration:Self-injection formulations bypass hospital infusion capacity constraints and capture patient convenience premiums in United States and Western European markets.
- India's Expanding Rheumatology Infrastructure:Underpenetrated diagnosis and treatment rates among Asia's largest SLE patient population create first-mover advantage for affordable biosimilar entrants.
- Complement Inhibition Convergence:Dual-targeting approaches combining B-cell depletion with terminal complement blockade open novel mechanism-of-action categories for nephrology-focused positioning.
Industry Challenges
- Cell-Culture Manufacturing Scale-Up:Biologics-grade capacity requires billion-dollar facility investments with multi-year construction timelines, constraining supply response to demand surges.
- Biomarker-Qualified Surrogate Endpoint Validation:Regulators demand extensive longitudinal data to accept novel endpoints, extending pre-submission dialogue and increasing clinical trial complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systemic Lupus Erythematous SLE Drugs Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Corticosteroids, Immunosuppressants, NSAIDs Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare, Research Laboratories Therapy Area: Autoimmune Disorders, Rheumatology, Dermatology, Nephrology |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, F. Hoffmann-La Roche Ltd, Aurinia Pharmaceuticals Inc., Bristol-Myers Squibb Company, Pfizer Inc., Sanofi S.A., Novartis AG, Biogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systemic Lupus Erythematous SLE Drugs Market Evolving Landscape
Targeted B-cell modulation and interferon pathway science are displacing broad immunosuppression as the therapeutic standard, while delivery innovation and diagnostic stratification reshape patient access models.
Subcutaneous belimumab and anifrolumab formulations are supplanting intravenous infusion as the preferred administration route in United States rheumatology practices. Community-based specialists and patient advocacy groups favor home-based injection for reduced clinic burden. This shift compresses hospital revenue per patient while expanding addressable prescriber pools beyond academic medical centers.
The FDA's 2023 updated guidance on lupus nephritis trial design emphasizes complete renal response endpoints and steroid-sparing metrics over partial improvement measures. Sponsors must now power studies for harder endpoints, increasing trial duration and patient enrollment requirements. Large pharmaceutical developers with existing rheumatology infrastructure absorb these costs more readily than emerging biotechnology firms.
Patient registries and real-world evidence platforms are restructuring how payers evaluate SLE therapy value. United States commercial insurers and Medicare Advantage plans increasingly condition preferred formulary placement on demonstrated corticosteroid reduction and hospitalization avoidance. Manufacturers must invest in longitudinal data infrastructure to defend access against therapeutic substitution pressures.
Systemic Lupus Erythematous SLE Drugs Market Segmentation
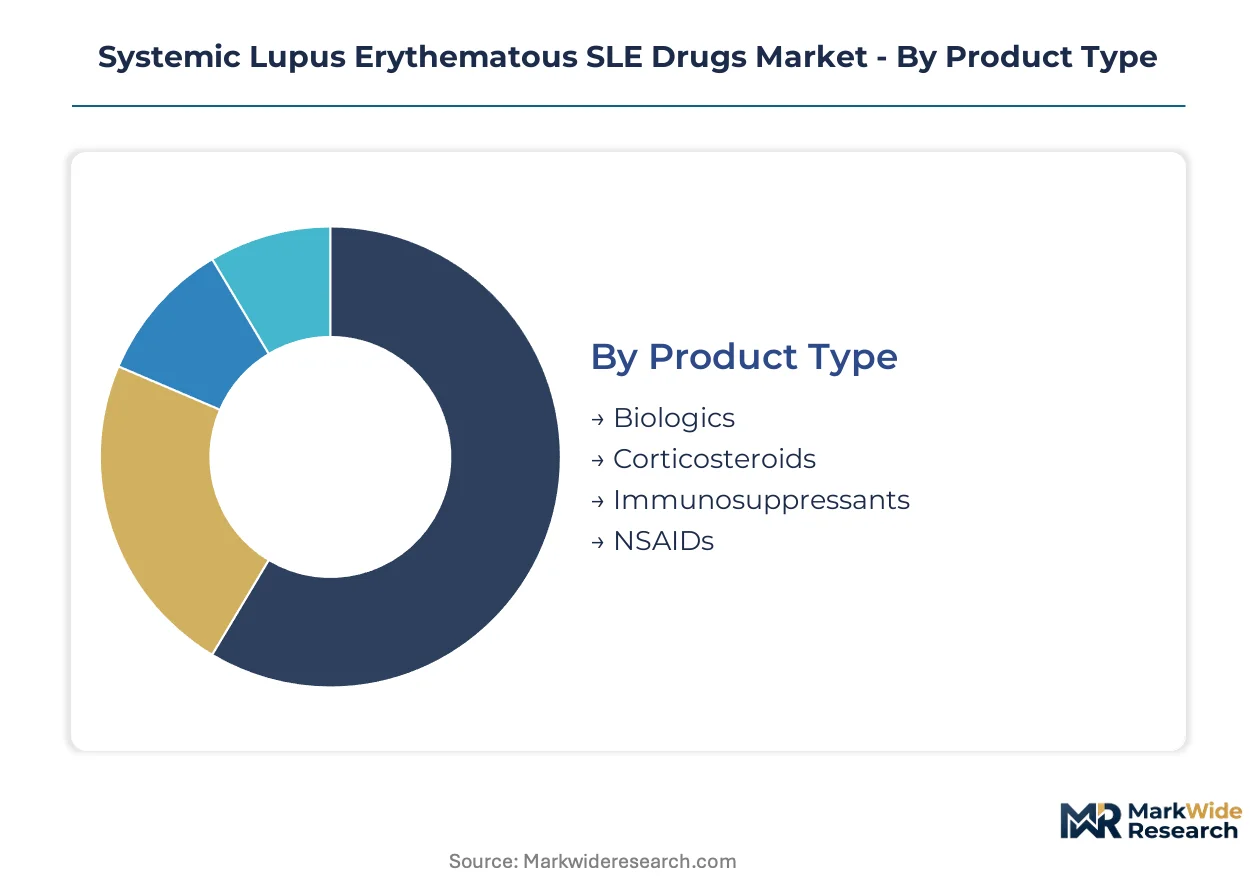
SLE drug segmentation reveals how therapeutic modality, administration route, and care setting intersect to determine pricing power and patient access. Manufacturers align pipeline investments with segments offering the strongest reimbursement leverage and lowest competitive density.
Product Type:
Domestic production concentrates in small-molecule corticosteroids and generic immunosuppressants, while biologics depend on imported active pharmaceutical ingredients and concentrated plasma derivatives from United States and German suppliers.
- Biologics:Monoclonal antibodies and fusion proteins manufactured via mammalian cell culture command premium pricing through targeted B-cell modulation and interferon pathway inhibition. United States rheumatology practices drive demand concentration as FDA breakthrough designations accelerate prescriber familiarity with novel mechanisms.
- Corticosteroids:Synthetic glucocorticoids including prednisone and methylprednisolone remain the induction backbone across cost-sensitive markets due to generic availability and rapid symptom suppression. Indian and Chinese manufacturers supply volume leadership, though tapering protocols now limit long-term revenue per patient.
- Immunosuppressants:Small-molecule agents such as mycophenolate mofetil and azathioprine bridge first-line and biologic-refractory populations.
- NSAIDs:Non-steroidal anti-inflammatory drugs address mild musculoskeletal manifestations without disease-modifying intent.
Corticosteroids command the established base. The steepest expansion runs through biologics.
Delivery Mode:
Cost tier stratification separates hospital-administered infusion therapies from self-administered options, with subcutaneous formulations capturing margin premiums through reduced healthcare utilization.
- Intravenous:Hospital-based infusion of monoclonal antibodies generates the highest per-dose revenue but requires dedicated rheumatology infrastructure and nursing supervision. Academic medical centers in the United States concentrate this segment's demand as they manage refractory lupus nephritis with complement inhibitors and B-cell depleting agents.
- Subcutaneous:Self-injection devices for belimumab and anifrolumab enable community rheumatologist prescribing and patient convenience. Western European markets favor this route for reducing clinic burden and enabling home-based chronic disease management.
- Oral:Tablet and capsule formulations dominate corticosteroid and immunosuppressant dispensing across all care settings.
- Topical:Localized preparations address cutaneous lupus manifestations with limited systemic exposure.
Oral administration retains volume leadership. Subcutaneous delivery is climbing the fastest as rheumatology practices decentralize beyond academic centers.
End User:
Patient acuity and reimbursement sophistication determine where each delivery mode concentrates, with homecare emerging as the contested frontier between hospital and outpatient clinic economics.
- Hospitals:Inpatient and infusion center settings manage acute lupus flares, nephritis induction, and biologic administration requiring monitoring. United States hospital systems with dedicated rheumatology departments capture the highest-value biologic patients through prior authorization control and specialty pharmacy integration.
- Homecare:Subcutaneous self-administration and home nursing visits for stable patients reduce institutional costs. Medicare Advantage plans in the United States increasingly direct stable SLE patients toward home-based management to avoid hospitalization penalties.
- Clinics:Outpatient rheumatology practices handle maintenance therapy and flare prevention.
- Research Laboratories:Academic and contract research organizations conduct biomarker validation and clinical trial operations.
Hospitals anchor the revenue base. Homecare is gaining share fastest as payers restructure site-of-care incentives.
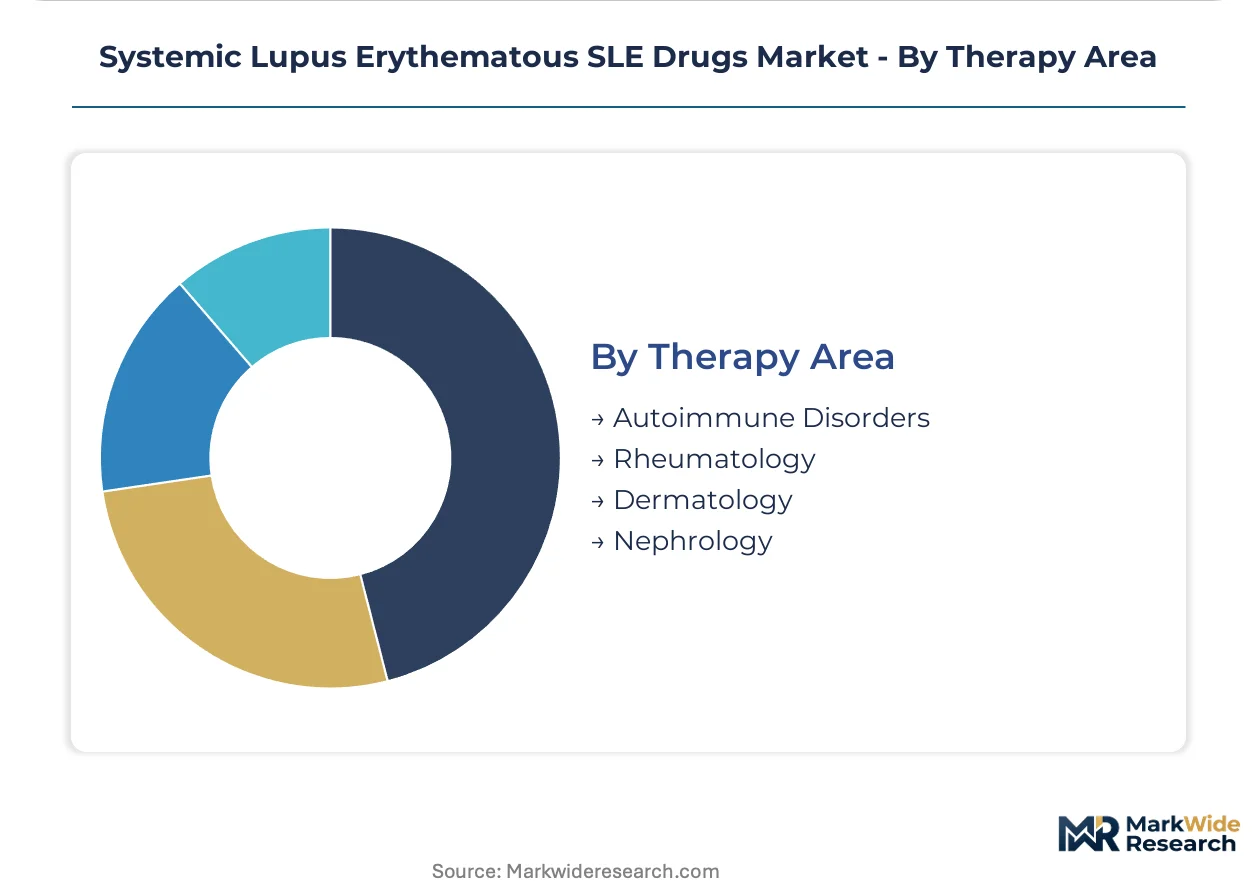
Therapy Area:
Organ-specific specialization creates divergent clinical trial endpoints and regulatory pathways, with nephrology commanding the most stringent evidence requirements and corresponding pricing authority.
- Nephrology:Lupus nephritis therapies face the highest evidentiary bar from FDA and EMA, requiring complete renal response endpoints and steroid-sparing validation. United States academic medical centers with transplant programs concentrate demand for complement inhibitors and novel B-cell modulators targeting refractory cases.
- Rheumatology:Systemic disease management spans musculoskeletal, serosal, and constitutional manifestations with composite responder indices as primary endpoints. European rheumatology practices emphasize organ-specific improvement measures accepted by EMA, enabling earlier access to emerging therapies.
- Autoimmune Disorders:Broad immunology franchises address SLE within portfolio approaches spanning multiple indications.
- Dermatology:Cutaneous lupus subsets receive targeted topical and systemic interventions.
Rheumatology holds the patient volume base. Nephrology presents the steepest expansion trajectory as complement inhibition redefines the refractory treatment paradigm.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics-grade manufacturing capacity clusters in the United States and Germany, concentrating high-value SLE therapy production within FDA and EMA regulatory orbits while India and China expand generic immunosuppressant supply.
United States
Hospital-based rheumatology departments in Boston and New York drive demand for monoclonal antibody infusions targeting refractory lupus nephritis. FDA breakthrough therapy designations for B-cell modulators compress development timelines and establish reimbursement benchmarks for subsequent entrants. The Research Triangle in North Carolina anchors clinical trial operations for interferon pathway inhibitors.
Germany
Academic medical centers in Munich and Heidelberg concentrate EMA-aligned lupus nephritis trials accepting organ-specific improvement measures. The country's plasma fractionation infrastructure supplies raw materials for biologics manufacturing across European markets. Berlin-based health technology assessment bodies influence pricing negotiations for subcutaneous formulations.
United Kingdom
London and Manchester rheumatology networks participate in multinational SLE patient registries generating real-world evidence for payer negotiations. NICE appraisals condition National Health Service access on demonstrated corticosteroid reduction metrics. The Oxford-Cambridge biotech corridor hosts early-stage complement inhibition research programs.
India
Maharashtra and Gujarat manufacturing hubs produce generic mycophenolate mofetil and corticosteroid formulations for cost-sensitive Asian and African markets. CDSCO regulatory pathways for biosimilar monoclonal antibodies are shortening as domestic rheumatology infrastructure expands in Delhi and Bangalore. Underpenetrated diagnosis rates among the country's SLE patient population attract first-mover positioning from affordable therapy developers.
Japan
PMDA consultations on biomarker-qualified surrogate endpoints are extending pre-submission dialogue for novel B-cell modulators seeking accelerated approval. Tokyo and Osaka academic medical centers concentrate demand for type I interferon signature stratification in clinical practice. The country's aging SLE demographic drives interest in home-based subcutaneous administration to reduce hospitalization burden.
Systemic Lupus Erythematous SLE Drugs Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing integrated rheumatology sales infrastructure and cell-culture manufacturing scale. The competitive structure tiers between legacy small-molecule suppliers and biologics specialists, with mid-cap nephrology-focused developers occupying narrow high-need subsets. Strategic moves center on subcutaneous formulation development to bypass hospital infusion constraints and biomarker-driven trial design to secure precision reimbursement. Geographic expansion into India's underpenetrated diagnosis pool and complement inhibition convergence represent parallel competitive vectors.
Within the diversified pharmaceutical tier, GlaxoSmithKline plc and F. Hoffmann-La Roche Ltd exemplify scale-driven positioning through established immunology franchises and deep interferon pathway R&D pipelines. Aurinia Pharmaceuticals Inc. occupies a specialist position focused on nephrology commercialization, representing the mid-cap archetype targeting high-need refractory patient subsets with novel mechanism-of-action approaches. These three entities collectively illustrate the competitive spectrum spanning broad systemic disease management to organ-specific therapeutic specialization.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| F. Hoffmann-La Roche Ltd |
| Aurinia Pharmaceuticals Inc. |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Sanofi S.A. |
| Novartis AG |
| Biogen Inc. |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day plasma-derived raw material lead times tether biologics pricing power to United States and German fractionation capacity, compressing margins for manufacturers without captive supply agreements or alternative sourcing routes. This inventory constraint stratifies the competitive landscape between integrated cell-culture specialists and small-molecule suppliers exposed to spot-market immunosuppressant volatility.
Pricing Analysis
FDA breakthrough therapy designation dictates the pricing tier structure across the Systemic Lupus Erythematous SLE Drugs Market, anchoring premium reimbursement for monoclonal antibodies against belimumab and anifrolumab benchmarks while generic corticosteroids compete on volume at economy levels. Price differentiation hinges on route of administration certification—intravenous hospital-administered therapies command facility fees and nursing premiums, whereas subcutaneous self-injection formulations capture convenience value in Medicare Advantage plans. Pricing pressure stems from corticosteroid-sparing protocols that accelerate biologic substitution timelines, eroding long-term immunosuppressant revenue per patient. Cost-sensitive markets in India and Southeast Asia exhibit highest price sensitivity to oral generic availability, while United States academic medical centers with dedicated rheumatology infrastructure demonstrate lowest sensitivity due to prior authorization control and specialty pharmacy integration.
Supply Chain Analysis
Plasma fractionation concentration in the United States and Germany creates a chokepoint that underwrites biologics manufacturing stability while exposing the Systemic Lupus Erythematous SLE Drugs Market to geographic supply disruption. Active pharmaceutical ingredient production for small-molecule immunosuppressants draws from Indian and Chinese chemical synthesis hubs, with mycophenolate mofetil and azathiopril intermediates sourced through multi-tier contractor networks. Single-source vulnerability concentrates in mammalian cell-culture capacity for monoclonal antibody production, where billion-dollar facility investments constrain supply response to demand surges. Distribution runs through hospital-based specialty pharmacies for intravenous infusion therapies, while subcutaneous formulations bypass institutional channels through mail-order and retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Systemic Lupus Erythematous SLE Drugs Market is recovering from cyclical compression in corticosteroid revenue as biologic penetration accelerates through FDA breakthrough designations and expanded nephrology indications.
For Market Incumbents: Secure cell-culture manufacturing capacity through backward integration into plasma fractionation or long-term offtake agreements with United States and German suppliers, insulating against raw material volatility that threatens margin stability. Reinforce rheumatology sales infrastructure with subcutaneous formulation training and homecare nursing partnerships to defend against emerging biosimilar entrants targeting Medicare Advantage channel substitution.
For New Entrants and Emerging Players: Anchor in India's underpenetrated diagnosis pool where CDSCO regulatory pathways for biosimilar monoclonal antibodies are shortening and domestic rheumatology infrastructure expansion in Delhi and Bangalore creates first-mover positioning. Target nephrology-focused commercialization with complement inhibition mechanisms, leveraging organ-specific improvement measures accepted by EMA to accelerate European market entry ahead of FDA complete renal response requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a precision immunology play because biomarker-qualified surrogate endpoint validation and interferon signature stratification are restructuring reimbursement negotiations and trial responder rates. Acquisition candidates with validated B-cell modulation platforms and existing nephrology relationships offer strongest positioning as complement inhibition convergence redefines refractory treatment paradigms. Monitor PMDA consultation outcomes in Japan for biomarker-driven accelerated approval precedents that signal regulatory pathway expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Belimumab and anifrolumab self-injection devices bypass hospital infusion capacity constraints and expand community rheumatologist prescribing pools. |
| Biomarker-Driven Trial Design | Type I interferon signature stratification improves responder rates and supports precision reimbursement negotiations with United States commercial insurers. |
| Plasma Supply Integration | Captive fractionation capacity or long-term offtake agreements insulate biologics manufacturers against United States and German raw material volatility. |
| Nephrology Commercialization Focus | Organ-specific positioning in lupus nephritis commands premium pricing through complete renal response endpoints required by FDA guidance. |
| India Market Entry | CDSCO biosimilar pathways and expanding rheumatology infrastructure in Maharashtra and Gujarat create first-mover advantage in Asia's largest SLE patient population. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and United States payer formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-verified segment-level estimates across treatment lines, administration routes, and regional regulatory clusters.
Across the analysis window, the analytical framework projected value and volume through disaggregated modeling of biologics versus small-molecule segments, intravenous versus subcutaneous delivery modes, and hospital versus homecare settings. CAGRs were derived from trend extrapolation of historical approval timelines, reimbursement expansion patterns, and plasma-derived manufacturing capacity additions. Forecast inputs incorporated FDA breakthrough therapy designation velocity, EMA organ-specific endpoint acceptance rates, and India's rheumatology infrastructure buildout trajectories.
Material uncertainties — regulatory endpoint revisions, plasma supply disruptions, and biosimilar launch timing — sit outside the modeled envelope and could materially alter trajectory assumptions. Practitioners should keep alternative scenarios live as FDA guidance evolution and CDSCO biosimilar pathway maturation reshape competitive entry dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Topical Acne Medication Market