
 Quinolones Market | 2026-2036
Quinolones Market Size, Share, and Industry Trends Forecast 2026-2036
Quinolones Market Outlook
Pharmacopoeia-grade API specifications are reorganizing procurement criteria across the quinolones supply base. Bayer AG leverages captive fermentation capacity to sustain European output of active pharmaceutical ingredients. Teva Pharmaceutical Industries Ltd. anchors its position through backward integration into key intermediate synthesis. Cipla Limited competes on cost-optimized norfloxacin and ciprofloxacin formulations for emerging markets.
Quinolones constitute a class of synthetic broad-spectrum antibacterial agents characterized by a bicyclic core structure with a fluorine atom at position 6 and a piperazine moiety at position 7, engineered to inhibit bacterial DNA gyrase and topoisomerase IV enzymes. These compounds serve as frontline therapies against Gram-negative pathogens in respiratory, urinary, and gastrointestinal infections where beta-lactam alternatives prove insufficient. Ciprofloxacin dominates prescription volumes across hospital formularies due to its established efficacy profile and generic availability. Levofloxacin captures premium positioning in respiratory infection protocols where atypical pathogen coverage commands higher reimbursement. Urinary tract infection applications represent the most mature segment with entrenched clinical guidelines limiting margin expansion.
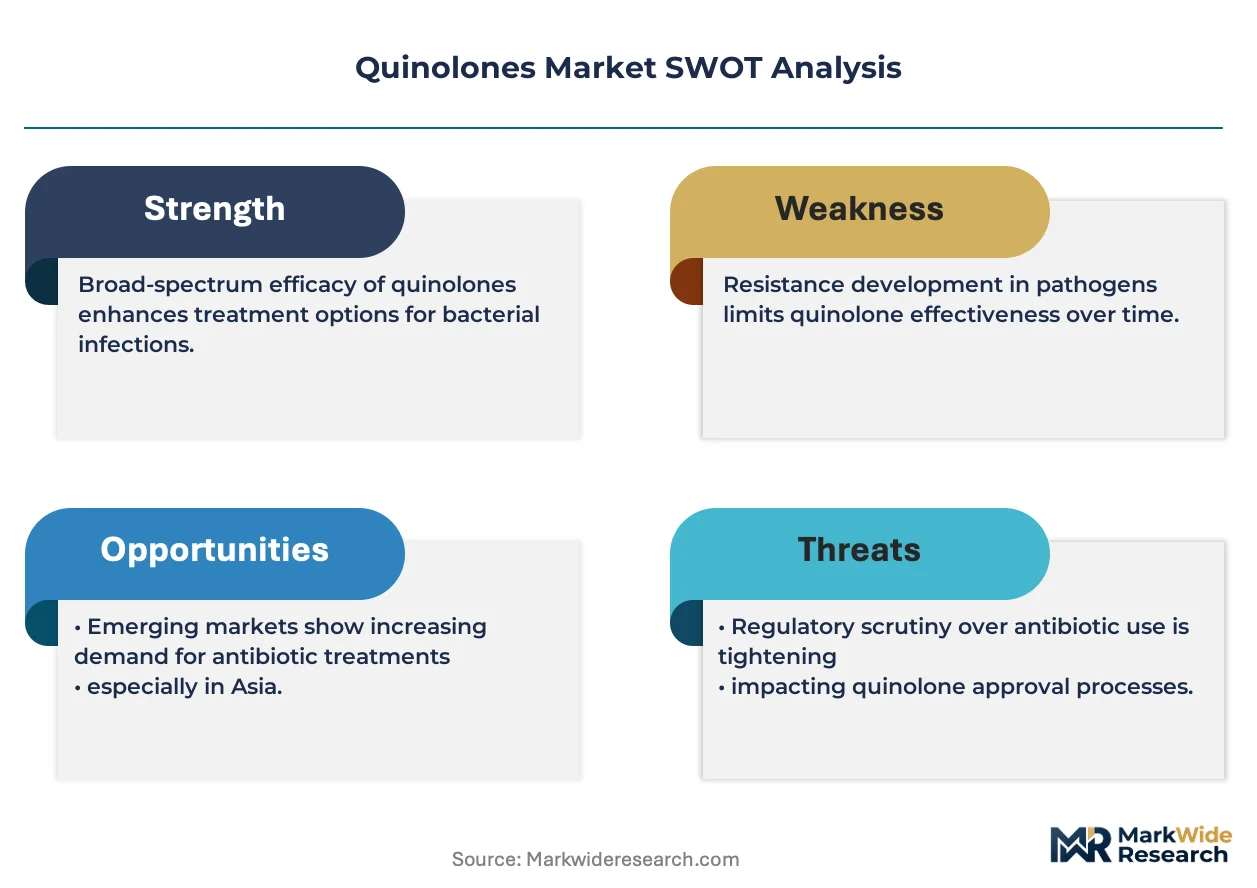
FDA black-box warnings on fluoroquinolone tendon rupture and neuropathy risks have constrained outpatient prescribing patterns in the United States. EMA pharmacovigilance assessments and REACH compliance requirements shape API import standards for European formulation manufacturers. CDSCO and BIS quality mandates in India are elevating documentation burdens for domestic exporters supplying regulated markets. Stakeholders must monitor evolving resistance surveillance data and regulatory label restrictions to anticipate shifts in first-line versus reserve-tier quinolone deployment.
Market Dynamics
Hospital procurement of broad-spectrum antibiotics is intensifying as drug-resistant infections climb, forcing formulary committees to reassess quinolone positioning against beta-lactam alternatives. FDA and EMA pharmacovigilance protocols are tightening resistance-tracking requirements for fluoroquinolone prescribers, reshaping prescriber behavior and reimbursement thresholds.
Growth Catalysts
- Pharmacovigilance mandates:FDA black-box warning protocols and EMA safety assessments are standardizing resistance surveillance, creating institutional demand for compliant quinolone sourcing.
- Generic manufacturing scale:India and China are expanding fermentation capacity for ciprofloxacin and levofloxacin APIs, lowering unit costs for emerging market procurement.
- Respiratory infection protocols:Hospital formulary expansion for atypical pathogen coverage is pulling levofloxacin into first-line positioning where macrolide resistance limits alternatives.
Market Restraints
- Fermentation input volatility:Precursor chemical costs for piperazine and fluorinated intermediates fluctuate with Chinese environmental enforcement cycles, compressing API margins.
- Supply concentration risk:European formulation manufacturers depend on Indian API exporters subject to CDSCO documentation delays and BIS quality mandate revisions.
- Tendon rupture liability:FDA black-box warnings on fluoroquinolone musculoskeletal risks constrain outpatient prescribing, shifting volume toward inpatient settings with lower reimbursement rates.
Strategic Opportunities
- Sub-Saharan Africa procurement:WHO prequalification pathways for norfloxacin and ciprofloxacin formulations are opening tender opportunities for manufacturers meeting international GMP standards.
- Dual-release formulation technology:Convergence of polymer matrix engineering with immediate-release quinolone cores is enabling extended-dose intervals that improve outpatient compliance.
- India PLI scheme incentives:Production-linked incentives for active pharmaceutical ingredient manufacturing are subsidizing domestic fermentation capacity expansion for export markets.
Industry Challenges
- Genotoxic impurity detection:N-nitrosamine testing protocols under ICH M7 guidelines require mass spectrometry capabilities that smaller API manufacturers lack, extending certification timelines.
- Legacy ERP integration:Serialization requirements for EU FMD compliance are forcing mid-tier formulation plants to reconfigure batch tracking systems against tight implementation deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quinolones Market |
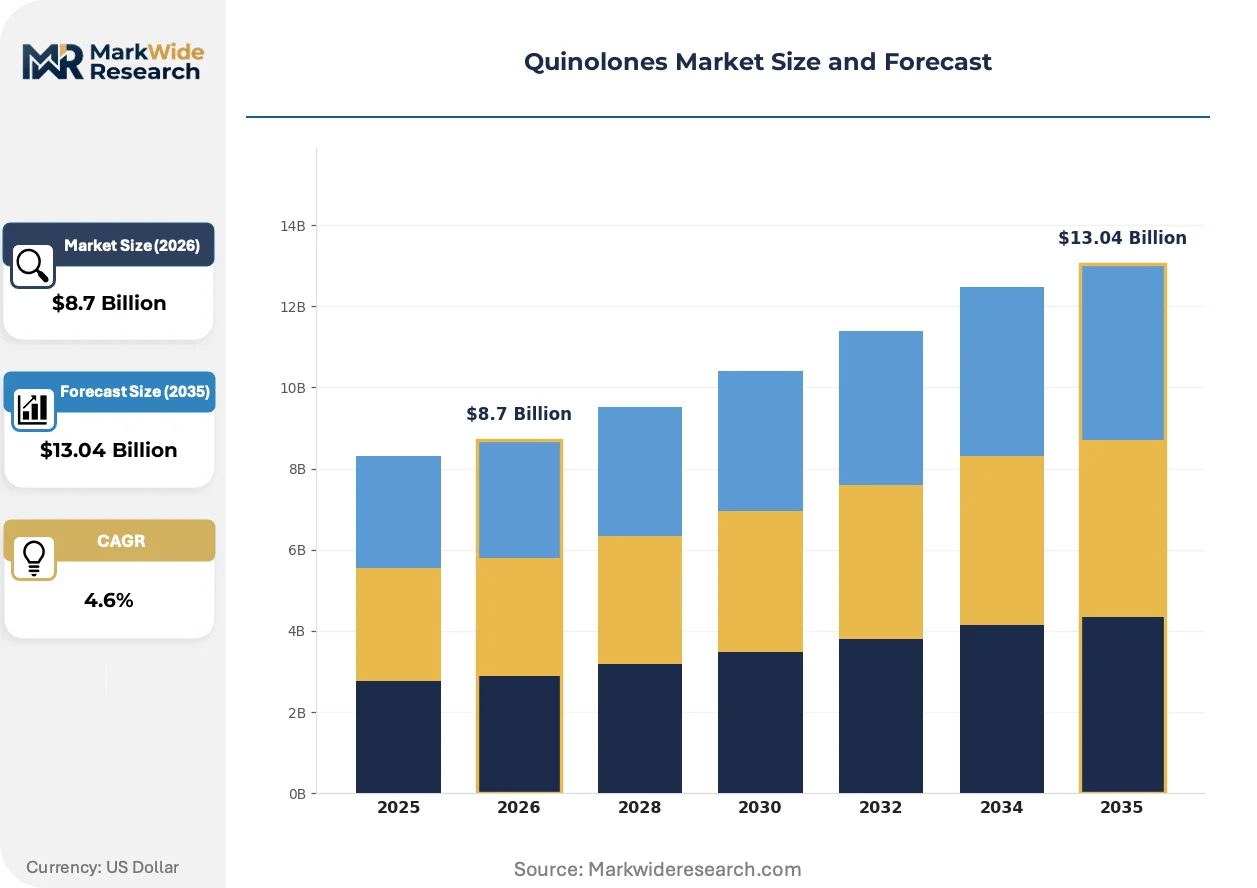
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
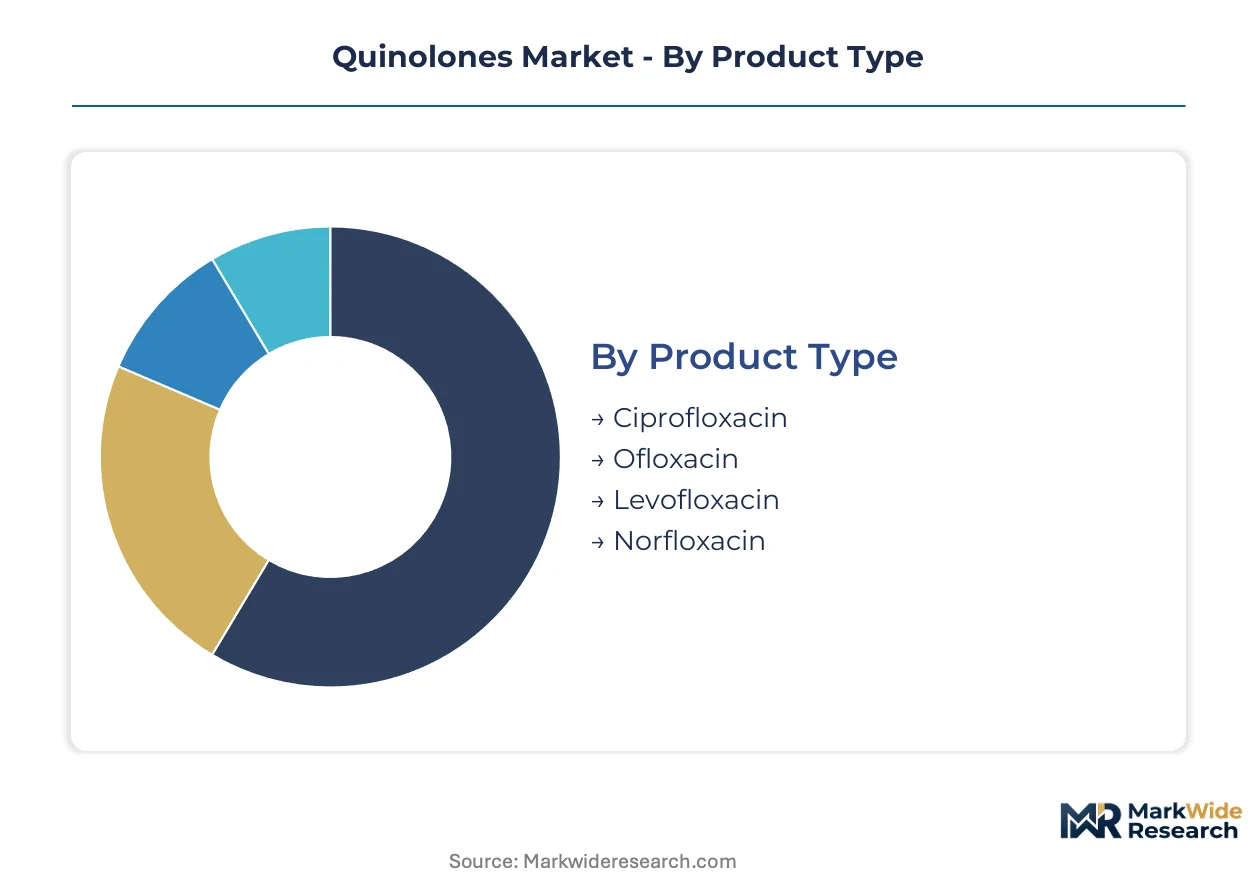
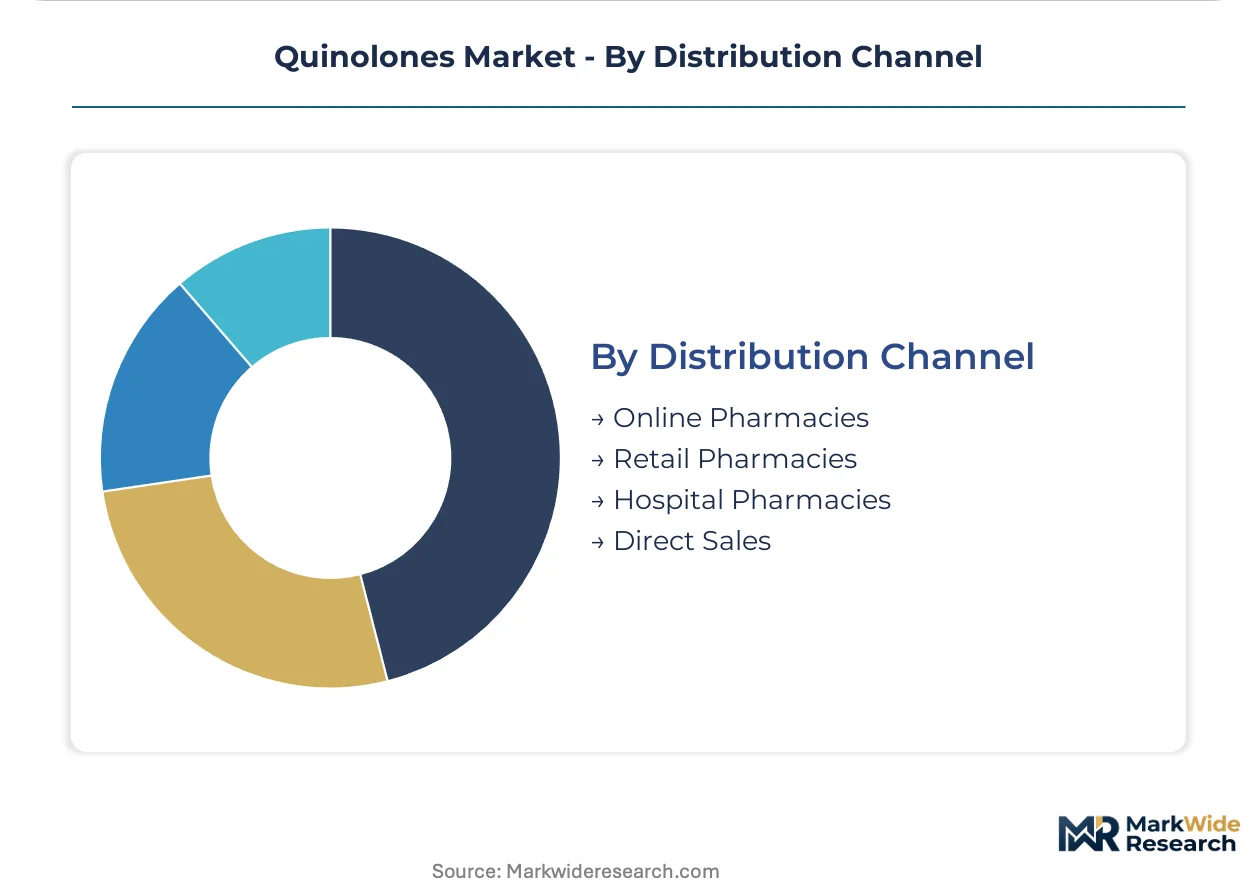
| Segmentation | Product Type: Ciprofloxacin, Ofloxacin, Levofloxacin, Norfloxacin Application: Infectious Diseases, Respiratory Infections, Urinary Tract Infections, Gastrointestinal Infections End User: Hospitals, Clinics, Pharmacies, Research Laboratories Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Bayer AG, Merck & Co., Inc., Pfizer Inc., Novartis AG, Sanofi, Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Bristol-Myers Squibb, Cipla Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quinolones Market Strategic Shifts
Continuous manufacturing techniques and real-time release testing are compressing quinolone production cycles, while regulatory pressure on resistance surveillance is accelerating digital integration across the supply base.
Continuous flow chemistry for quinolone API synthesis is supplanting traditional batch fermentation in select European manufacturing facilities. Bayer AG and specialized CDMOs are adopting microreactor platforms to reduce solvent volumes and improve yield consistency. This technology is enabling just-in-time API production that aligns with hospital formulary demand fluctuations.
EMA pharmacovigilance assessments and REACH compliance requirements are elevating documentation burdens for API import standards. European formulation manufacturers must now submit enhanced resistance surveillance data to maintain market authorization. Respiratory and urinary tract infection applications face the steepest compliance ramps, driving consolidation toward vertically integrated suppliers with dedicated regulatory affairs capacity.
Hospital procurement committees are consolidating antibiotic purchasing through centralized tender platforms, displacing traditional distributor networks in high-volume markets. Group purchasing organizations in the United States and national procurement agencies in India are aggregating demand to extract volume discounts from API suppliers. This concentration is most visible in tertiary hospital systems where formulary standardization across facility networks has compressed supplier rosters to three-to-five qualified vendors per molecule.
Quinolones Market Segmentation
Quinolone prescribing patterns fragment sharply across clinical settings and pathogen profiles, forcing manufacturers to align formulation specifications with distinct reimbursement and resistance surveillance requirements. Each segment carries unique regulatory documentation burdens that reshape supplier qualification criteria.
Product Type:
Substitution pressure from beta-lactam and macrolide alternatives varies dramatically across the quinolone class, with newer agents facing tighter formulary scrutiny than legacy compounds.
- Ciprofloxacin:First-generation fluoroquinolone with established Gram-negative coverage dominates hospital formularies through generic availability and WHO Essential Medicines List positioning. Indian API manufacturers supply bulk volumes to African and Southeast Asian procurement tenders where cost thresholds override newer-agent efficacy advantages.
- Levofloxacin:Enhanced respiratory pathogen coverage including atypical organisms commands premium positioning in pneumonia protocols where macrolide resistance has eliminated standard alternatives. Japanese and South Korean hospital systems favor this agent for community-acquired respiratory infections despite EMA tendon rupture warnings.
- Ofloxacin:Racemic mixture with intermediate potency serves cost-sensitive markets in Latin America and the Middle East where regulatory pathways for newer enantiopure agents remain underdeveloped.
- Norfloxacin:Restricted urinary tract penetration and inferior pharmacokinetics limit this agent to niche prophylaxis applications in recurrent cystitis protocols across select European markets.
Ciprofloxacin retains volume leadership; levofloxacin holds the steepest expansion curve.
Application:
Clinical guideline revisions are redrawing segment boundaries as resistance surveillance data forces pathogen-specific protocol updates.
- Respiratory Infections:Atypical pathogen coverage requirements in hospital-acquired pneumonia protocols are pulling levofloxacin into first-line positioning. EMA pharmacovigilance assessments for this application impose enhanced tendon rupture documentation that smaller formulation suppliers cannot satisfy.
- Urinary Tract Infections:Entrenched clinical guidelines and extensive generic substitution have compressed margins in this mature segment. Indian and Chinese manufacturers compete primarily on API cost and CDSCO export certification speed.
- Infectious Diseases:Broad-spectrum empiric therapy for sepsis and undifferentiated fever drives hospital procurement concentration. FDA black-box warnings on fluoroquinolone neuropathy risks have shifted prescribing toward inpatient monitoring settings.
- Gastrointestinal Infections:Traveler's diarrhea and enteric fever applications face displacement by azithromycin in regions where quinolone resistance in Salmonella and Campylobacter has crossed clinical thresholds.
Urinary tract infection applications anchor revenue stability; respiratory infection protocols are gaining share fastest.
End User:
Procurement authority concentration determines pricing leverage, with centralized hospital systems extracting steeper discounts than fragmented retail channels.
- Hospitals:Tertiary care systems aggregate antibiotic demand through group purchasing organizations in the United States and national procurement agencies in India. Formulary standardization across facility networks has compressed supplier rosters to qualified vendors with dedicated regulatory affairs capacity.
- Clinics:Outpatient prescribing faces FDA black-box warning constraints on fluoroquinolone musculoskeletal risks, shifting volume toward alternative agents. Reimbursement differentials between oral and intravenous formulations reshape prescriber behavior.
- Pharmacies:Retail dispensing operates under tighter margin pressure in markets with direct-to-consumer generic substitution policies.
- Research Laboratories:Reference standard and analytical reagent demand supports specialized API manufacturers with pharmacopoeia certification capabilities.
Hospitals command procurement volume dominance; clinics face the sharpest prescribing constraint acceleration.
Distribution Channel:
Cold-chain requirements and serialization mandates are segmenting supplier capabilities across channel types.
- Hospital Pharmacies:Direct contracting with API-integrated formulation manufacturers bypasses traditional distributor markups. EU FMD serialization requirements force mid-tier plants to reconfigure batch tracking systems.
- Retail Pharmacies:Generic substitution policies and pharmacist-level therapeutic interchange authority concentrate demand on lowest-cost qualified suppliers.
- Online Pharmacies:Cross-border dispensing regulations vary sharply by jurisdiction, with CDSCO and BIS quality mandates blocking Indian exports to certain markets.
- Direct Sales:Institutional tenders for government stockpiles and NGO procurement require WHO prequalification pathways that only vertically integrated manufacturers can navigate efficiently.
Hospital pharmacies concentrate procurement authority; online channels face regulatory friction escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit extreme price elasticity, driving procurement toward lowest-cost generic APIs, while German and Swiss hospital systems absorb premium pricing for pharmacovigilance-assured supply chains.
United States
Hospital formulary committees concentrate antibiotic purchasing through group purchasing organizations, extracting volume discounts from qualified suppliers. FDA black-box warnings on fluoroquinolone tendon rupture risks constrain outpatient prescribing, shifting demand toward inpatient monitoring settings. The Boston-Cambridge pharmaceutical corridor anchors clinical trial activity for next-generation formulations.
India
Domestic infectious disease burdens and WHO prequalification pathways for African export tenders sustain fermentation capacity expansion. CDSCO documentation requirements and BIS quality mandates elevate certification burdens for API exporters supplying regulated markets. The Hyderabad-Visakhapatnam corridor concentrates generic manufacturing for ciprofloxacin and levofloxacin active pharmaceutical ingredients.
China
Environmental enforcement cycles in fluorinated intermediate production create input cost volatility for piperazine derivatives. NMPA quality standards and dual carbon goals reshape fermentation plant compliance investments. The Zhejiang-Jiangsu chemical manufacturing belt supplies bulk quinolone precursors to European formulation manufacturers.
Germany
EMA pharmacovigilance assessments and REACH compliance requirements impose documentation thresholds that filter smaller API suppliers from procurement rosters. Hospital procurement agencies aggregate demand through centralized tender platforms, compressing qualified vendor lists. The Rhine-Main pharmaceutical cluster sustains captive fermentation capacity for high-specification active pharmaceutical ingredients.
Brazil
ANVISA regulatory pathways for generic fluoroquinolone formulations attract Indian API exporters seeking Latin American market access. Public hospital procurement through national tender systems concentrates demand on cost-optimized suppliers. The São Paulo pharmaceutical manufacturing hub handles formulation and packaging for regional distribution.
Quinolones Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with European innovators commanding pharmacovigilance-assured premiums while Asian manufacturers compete on fermentation scale. The vendor base stratifies across three tiers: research-driven originators with captive API capacity, vertically integrated generic majors with regulatory affairs depth, and commodity API suppliers competing on CDSCO certification speed. Bayer AG exemplifies the first archetype through European fermentation infrastructure. Teva Pharmaceutical Industries Ltd. and Cipla Limited anchor the second tier. Strategic moves concentrate on backward integration into key intermediate synthesis and dual-release formulation technology licensing.
Among European-origin research pharmaceutical companies, Bayer AG occupies a position exemplifying captive fermentation capacity for pharmacopoeia-grade active pharmaceutical ingredients. Teva Pharmaceutical Industries Ltd. represents the vertically integrated generic archetype, with regulatory affairs infrastructure spanning multiple jurisdictions. Cipla Limited sits within the cost-optimized formulation tier, competing on norfloxacin and ciprofloxacin supply for emerging market procurement tenders. These three anchors illustrate the competitive structure: technology differentiation, regulatory depth, and manufacturing scale operate as distinct positioning vectors rather than cumulative advantages.
| Leading Market Players |
|---|
| Bayer AG |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Novartis AG |
| Sanofi |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb |
| Cipla Limited |
| Others |
Value Chain & Pricing Dynamics
Chinese environmental enforcement-driven substitution of batch fermentation with continuous flow chemistry simultaneously shifts active pharmaceutical ingredient production geography toward European microreactor facilities and compresses pricing economics for legacy piperazine derivative suppliers. This dual restructuring concentrates premium-tier pharmacopoeia-grade supply in Rhine-Main corridor captive operations while Indian exporters absorb margin erosion from CDSCO documentation burdens.
Pricing Analysis
After-sales revenue from resistance surveillance compliance services and pharmacovigilance documentation packages drives lifetime value differentiation among API suppliers. Pricing stratifies across pharmacopoeia certification tiers, with FDA-EMA dual-compliant manufacturers commanding substantial premiums over CDSCO-only certified competitors. Cost compression in generic ciprofloxacin API tiers is intensifying because Indian fermentation scale expansion outpaces formulary demand growth. Hospital procurement committees exhibit the sharpest price sensitivity through centralized tender aggregation, while research laboratories demonstrate the least due to analytical reagent purity requirements.
Supply Chain Analysis
Container availability constraints on India-Europe pharmaceutical trade lanes elevate inbound logistics costs for piperazine and fluorinated intermediate shipments. Geographic supply concentration centers on India, China, and Germany, with the Hyderabad-Visakhapatnam corridor and Zhejiang-Jiangsu belt feeding European formulation manufacturers. Raw material dependencies rest on piperazine derivatives, fluorinated aromatics, and fermentation feedstock inputs. Single-source vulnerability from CDSCO documentation delays creates procurement risk for European buyers. Distribution runs through hospital pharmacy direct contracting and centralized national tender platforms, displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing disruption and EMA pharmacovigilance tightening create a high-growth inflection for compliant quinolone suppliers, with digital resistance surveillance integration determining competitive survival.
For Market Incumbents: Fortify market position through backward integration into key intermediate synthesis and captive fermentation capacity expansion in European regulatory jurisdictions. Generic API margin compression from Indian scale expansion threatens legacy revenue streams; pharmacopoeia-grade certification investments and dedicated regulatory affairs teams provide defensive moats against CDSCO-certified challengers. For New Entrants and Emerging Players: Compliance-as-a-service gaps in genotoxic impurity testing and N-nitrosamine mass spectrometry capabilities offer white-space entry points. Sub-Saharan Africa WHO prequalification pathways for norfloxacin and ciprofloxacin formulations represent the most penetrable geography, with tender aggregation creating volume concentration for qualified entrants. Partner with established Indian API manufacturers for CDSCO export certification speed rather than building captive fermentation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated generic majors with multi-jurisdictional regulatory depth. Long-term viability over the next decade hinges on continuous manufacturing technology adoption and pharmacovigilance infrastructure investment. Watch EMA label restriction expansions on tendon rupture documentation as the critical inflection signal for first-line versus reserve-tier quinolone deployment shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Bayer AG microreactor adoption reduces solvent volumes and aligns output with hospital formulary demand fluctuations. |
| Backward Integration into Piperazine Intermediates | Teva Pharmaceutical Industries secures supply chain control over fluorinated precursor costs amid Chinese environmental enforcement cycles. |
| WHO Prequalification Pathway Navigation | Cipla Limited unlocks African tender opportunities through international GMP standard compliance and CDSCO export certification. |
| Dual-Release Formulation Technology Licensing | Polymer matrix engineering convergence enables extended-dose intervals that improve outpatient compliance in respiratory protocols. |
| Pharmacovigilance Infrastructure Investment | Dedicated regulatory affairs capacity satisfies EMA enhanced resistance surveillance data submissions for levofloxacin positioning. |
Study Parameters
Desk research of FDA pharmacovigilance databases, EMA safety assessment archives, and CDSCO export certification records preceded structured interviews with hospital formulary directors, API procurement managers, regulatory affairs leads, and fermentation plant engineers. Secondary validation drew from WHO Essential Medicines List positioning data, REACH compliance documentation, and Indian PLI scheme disclosure filings. Bottom-up API production capacity estimates triangulated against top-down hospital antibiotic consumption surveys.
Variance decomposition across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume-weighting of hospital procurement concentration trends and generic substitution elasticity patterns. Forecast inputs incorporated fermentation capacity expansion timelines in India and China alongside EMA pharmacovigilance assessment frequency revisions.
Forecasts assume regulatory continuity in FDA black-box warning protocols, EMA REACH compliance requirements, and CDSCO-BIS quality mandates; material policy shifts would require re-modeling. Resistance surveillance data publication lags and environmental enforcement cycle unpredictability in Chinese fluorinated intermediate production represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Mexico Dimenhydrinate Market