
 Middle East and Africa Continuous Glucose Monitoring Market | 2026-2036
Middle East and Africa Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Continuous Glucose Monitoring Market Foresight
Hospital procurement consolidation across Gulf Cooperation Council health systems is expanding as centralized purchasing authorities aggregate CGM volumes for multi-site diabetes centers. Abbott Laboratories leverages its FreeStyle Libre manufacturing scale to anchor distribution across UAE and Saudi Arabia hospital networks. Medtronic competes through its Guardian sensor platform, sustaining R&D intensity in real-time algorithm development. Dexcom differentiates via its G7 platform's interoperability with insulin pump ecosystems, positioning for integrated closed-loop adoption.
Continuous glucose monitoring comprises wearable sensor systems that measure interstitial glucose levels via enzymatic electrochemical reaction, transmitting data to receivers or smartphones for real-time glycemic trend visualization. The primary purpose is enabling proactive diabetes management through automated alerts and pattern recognition, reducing hypoglycemic episodes and HbA1c variability. Interstitial glucose sensors dominate product type value pools due to recurring consumable replacement cycles, while real-time CGM technology leads technology segmentation through its predictive alert capabilities and integration with automated insulin delivery. Flash glucose monitoring occupies the fastest-expanding position among technology categories, driven by lower cost per test and reduced calibration requirements expanding access in price-sensitive African markets.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority shape device registration pathways, with SFDA's medical device marketing authorization requirements accelerating quality standard convergence with European MDR frameworks. The UAE's Ministry of Health and Prevention implements procurement specifications favoring connected CGM platforms with cloud-based data sharing for remote patient monitoring. Stakeholders must monitor reimbursement policy evolution across national health insurance schemes, as coverage determinations for sensor-based glucose monitoring will dictate addressable patient populations and pricing flexibility across the region's heterogeneous payer structures.
Market Dynamics
Centralized hospital procurement across Gulf health systems is consolidating purchasing power, compressing vendor margins while expanding sensor-based diabetes management into previously unreachable patient populations across the region.
Growth Catalysts
- SFDA Marketing Authorization Alignment:Saudi Arabia's medical device registration pathway is converging with European MDR frameworks, accelerating approval timelines for imported CGM systems and reducing regulatory fragmentation across Gulf markets.
- Ministry of Health Sensor Programs:Saudi Arabia's national diabetes management initiatives are embedding continuous glucose monitoring into standard care protocols, creating institutional demand pull through government-funded health system procurement.
- Interstitial Sensor Technology:Enzymatic electrochemical reaction platforms are achieving extended wear durations, reducing per-test costs and expanding addressable patient pools in price-sensitive African markets.
Market Restraints
- Consumable Cost Structure:Recurring sensor replacement cycles impose sustained out-of-pocket burdens on patients in markets lacking comprehensive reimbursement coverage, limiting penetration among uninsured populations.
- Distribution Concentration Risk:Medical device supply chains for the region route through limited UAE-based logistics hubs, creating vulnerability to port congestion and customs processing delays.
- Flash-to-RTGM Substitution Pressure:Lower-cost flash glucose monitoring systems are capturing price-sensitive segments, compressing real-time CGM pricing power in South African and Nigerian outpatient markets.
Strategic Opportunities
- Nigerian Outpatient Expansion:Private diabetes clinics in Lagos and Abuja represent underpenetrated demand for factory-calibrated sensors requiring minimal patient training.
- Cloud-Connected Platform Mandates:UAE Ministry of Health and Prevention procurement specifications favoring remote patient monitoring integration are creating preferential market access for data-sharing-enabled devices.
- Insulin Pump Convergence:Closed-loop automated insulin delivery systems are absorbing interoperable CGM sensors, positioning integrated platform vendors for premium positioning in Saudi hospital networks.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Gulf health systems face shortages of specialists capable of maintaining calibration-free sensor systems and troubleshooting receiver-smartphone connectivity failures.
- SFDA-to-SAHPRA Registration Divergence:Separate marketing authorization requirements across Saudi Arabia and South Africa force redundant clinical documentation and extended certification timelines for vendors targeting both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Continuous Glucose Monitoring Market |
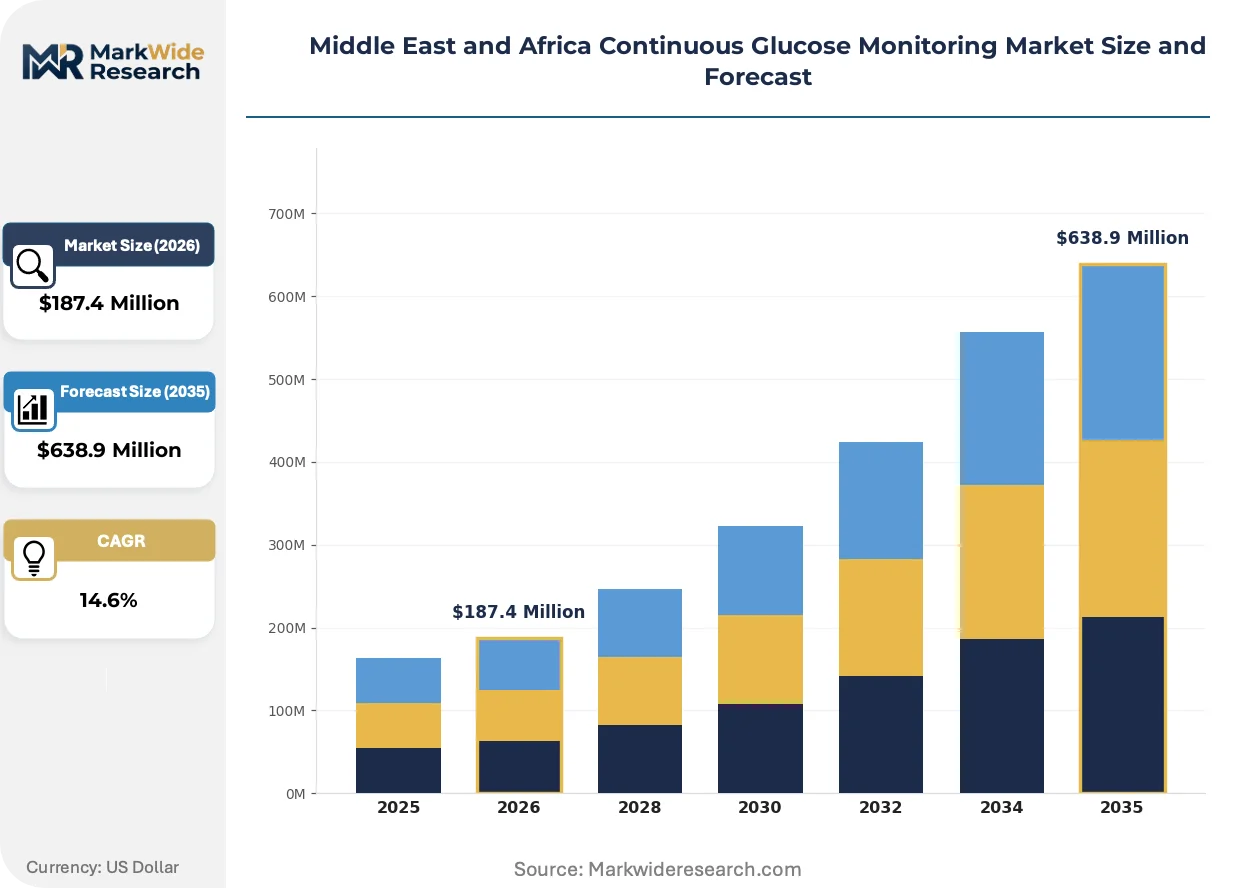
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interstitial Glucose Sensors, Transmitters, Display Devices, Application Software End User: Hospitals, Homecare Settings, Clinics, Healthcare Providers Technology: Real-Time CGM, Flash Glucose Monitoring, Professional CGM, Wearable Technologies Distribution Channel: Retail Pharmacies, Online Stores, Direct Sales, Diabetes Care Centers |
| Companies Covered | Senseonics Holdings, Roche Diabetes Care, Medtronic, Insulet Corporation, Ypsomed, Abbott Laboratories, GlySens Incorporated, Novo Nordisk, Dexcom, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Continuous Glucose Monitoring Market Shifts & Advancements
Sensor miniaturization and algorithmic predictive capability are converging to transform diabetes management from reactive glucose testing into proactive glycemic intervention across Middle East and African care settings.
Factory-calibrated flash glucose monitoring is absorbing patient populations previously excluded from sensor-based care due to calibration burden and cost sensitivity. Community health programs in Kenya and Ethiopia are deploying these systems for type 2 diabetes screening. The technology is absorbing market share from traditional fingerstick monitoring in price-constrained segments.
SAHPRA's updated glucose monitoring procurement standards are mandating enhanced accuracy specifications for publicly tendered devices. South African public hospital networks are disqualifying legacy systems failing updated performance thresholds. Private clinic chains are responding by accelerating technology refresh cycles to maintain eligibility for national health laboratory service contracts.
Hospital buying committees are consolidating multi-site CGM procurement under centralized Gulf Cooperation Council purchasing authorities. Individual diabetes center purchasing autonomy is contracting as health system administrators aggregate volumes for price negotiation. Saudi Arabia's Ministry of Health programs exhibit the most advanced consolidation, with single-source awards covering dozens of facilities.
Middle East and Africa Continuous Glucose Monitoring Market Segmentation
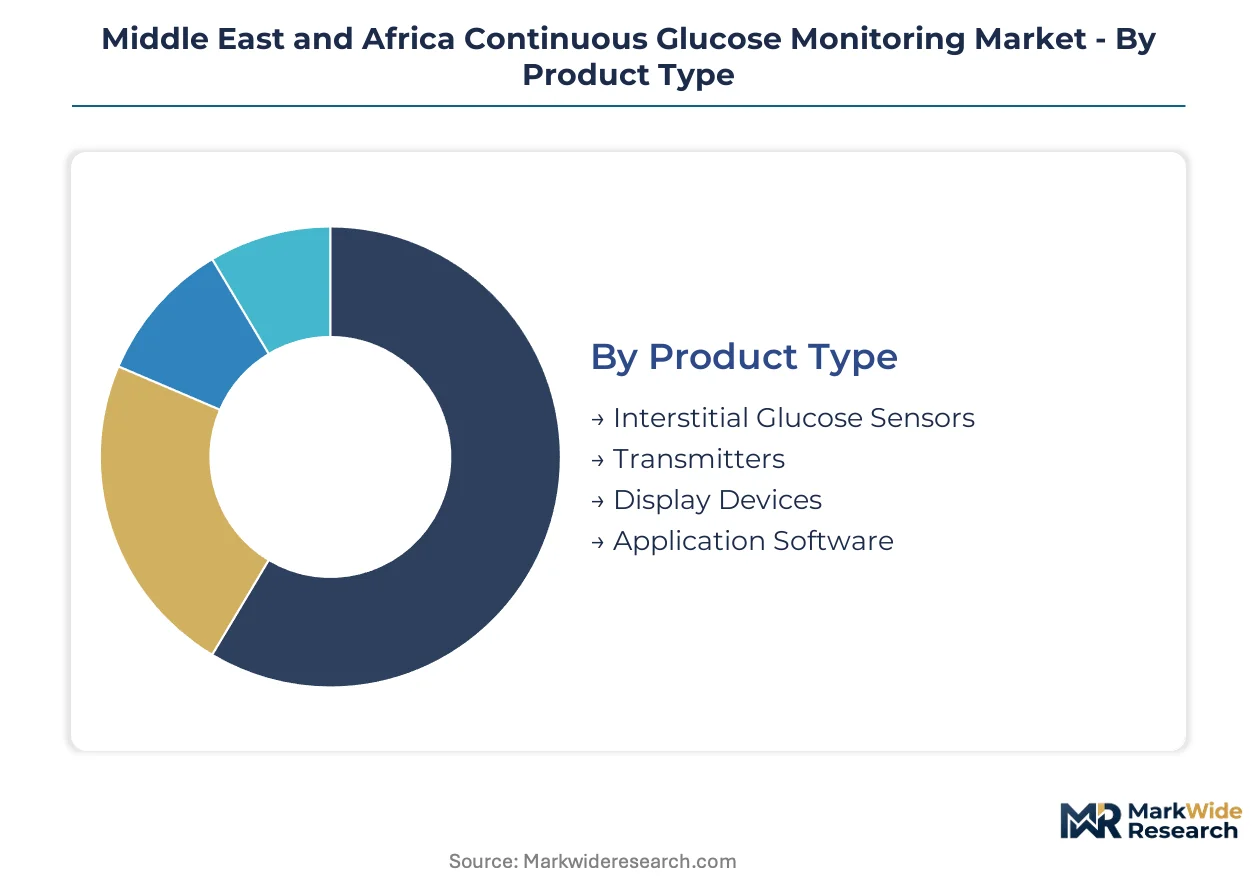
CGM market segmentation reveals divergent capital requirements across hardware and software layers, with sensor manufacturing demanding specialized cleanroom infrastructure while digital platforms scale through cloud architecture. Understanding these investment profiles enables stakeholders to align resource allocation with margin structures across Middle East and African healthcare systems.
Product Type:
Interstitial glucose sensors command the steepest upfront capital commitment, requiring precision electrochemical manufacturing lines and biocompatible material certification pathways.
- Interstitial Glucose Sensors:Enzymatic electrochemical reaction platforms measure glucose through subcutaneous filaments with factory-calibrated chemistry. Saudi Arabia's Ministry of Health diabetes programs are consolidating multi-hospital procurement for these consumables, driving volume aggregation that favors scaled manufacturers.
- Transmitters:Bluetooth-enabled relay devices bridge sensor-receiver communication with embedded firmware for signal processing. UAE hospital networks specify extended battery life and water resistance for Gulf climate conditions, narrowing qualified supplier pools.
- Display Devices:Dedicated receivers and smartphone-integrated readers provide glycemic trend visualization.
- Application Software:Cloud-based analytics platforms enable remote patient monitoring and pattern recognition.
Interstitial glucose sensors absorb the bulk of installed capacity; application software is expanding most quickly.
End User:
Hospital procurement patterns concentrate purchasing power through centralized Gulf Cooperation Council health authorities, reshaping vendor access requirements.
- Hospitals:Multi-site diabetes centers under Saudi Arabia's Ministry of Health programs embed CGM into standard care protocols. Centralized tendering aggregates volumes across dozens of facilities, compressing unit economics while expanding institutional penetration.
- Homecare Settings:Self-monitoring patients in South Africa and Nigeria drive outpatient demand for factory-calibrated systems requiring minimal training. SAHPRA procurement standard updates are disqualifying legacy devices from public reimbursement eligibility.
- Clinics:Private diabetes centers in Lagos and Abuja represent underpenetrated demand for simplified sensor deployment.
- Healthcare Providers:Physician practices and community health programs integrate CGM data into treatment workflows.
Hospitals dominate current procurement volume; homecare settings are climbing the fastest as reimbursement frameworks mature.
Technology:
Real-time algorithm development demands sustained R&D intensity, creating capability barriers that differentiate platform vendors.
- Real-Time CGM:Predictive alert systems with automated hypoglycemia detection transmit continuous data streams to receivers or smartphones. Saudi hospital networks prioritize interoperability with insulin pump ecosystems for closed-loop adoption.
- Flash Glucose Monitoring:Factory-calibrated sensors eliminate calibration burden through on-body scanning. Community health programs in Kenya and Ethiopia deploy these systems for type 2 diabetes screening, absorbing patient populations excluded by cost sensitivity.
- Professional CGM:Clinic-based diagnostic systems support short-term metabolic profiling.
- Wearable Technologies:Sensor-integrated form factors beyond traditional adhesive patches.
Real-time CGM holds the largest installed base; flash glucose monitoring is gaining share fastest in price-constrained African markets.
Distribution Channel:
Channel selection determines regulatory compliance burden and patient training requirements across heterogeneous Middle East and African healthcare infrastructure.
- Retail Pharmacies:Over-the-counter sensor availability expands access in South African and Nigerian urban centers. SAHPRA updated standards mandate accuracy verification for pharmacy-stocked devices, raising quality barriers.
- Online Stores:Direct-to-patient platforms bypass traditional supply chain concentration through UAE logistics hubs. Customs processing delays and temperature-controlled shipping requirements create operational complexity for sensor fulfillment.
- Direct Sales:Vendor field teams support hospital procurement committees with clinical evidence packages.
- Diabetes Care Centers:Specialized facilities bundle sensor provision with patient education and remote monitoring services.
Retail pharmacies handle the greatest transaction volume; online stores are expanding most quickly as digital health infrastructure penetrates Gulf markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia where Ministry of Health diabetes management programs are scaling sensor-based care across hospital networks. South Africa and the UAE anchor procurement innovation through updated regulatory standards and connected platform mandates.
Saudi Arabia
Ministry of Health sensor programs embed continuous glucose monitoring into standard care protocols across multi-site diabetes centers. SFDA marketing authorization alignment with European MDR frameworks accelerates approval timelines for imported CGM systems. Riyadh anchors centralized tendering that aggregates volumes across dozens of facilities, compressing unit economics while expanding institutional penetration.
United Arab Emirates
UAE Ministry of Health and Prevention procurement specifications favor connected CGM platforms with cloud-based data sharing for remote patient monitoring. MOHAP mandates are creating preferential market access for data-sharing-enabled devices. Dubai hospital networks specify extended battery life and water resistance for Gulf climate conditions, narrowing qualified supplier pools.
South Africa
National Health Laboratory Service updated glucose monitoring procurement standards mandate enhanced accuracy specifications for publicly tendered devices. SAHPRA's revised requirements are disqualifying legacy systems from public reimbursement eligibility. Private clinic chains in Johannesburg and Cape Town accelerate technology refresh cycles to maintain eligibility for national contracts.
Nigeria
Private diabetes clinics in Lagos and Abuja represent underpenetrated demand for factory-calibrated sensors requiring minimal patient training. Outpatient expansion targets type 2 diabetes populations previously excluded by cost sensitivity and calibration burden. Lagos anchors distribution reach into West African markets through retail pharmacy networks.
Kenya
Community health programs deploy flash glucose monitoring systems for type 2 diabetes screening in rural and peri-urban populations. Factory-calibrated sensors absorb patient populations excluded by real-time CGM cost barriers. Nairobi anchors East African distribution corridors for temperature-controlled sensor logistics.
Middle East and Africa Continuous Glucose Monitoring Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue interoperability specialization and regional manufacturing partnerships. The vendor base stratifies across multinational device manufacturers with Gulf distribution scale, mid-tier sensor specialists targeting price-sensitive African markets, and insulin pump ecosystem integrators positioning for closed-loop convergence. Dominant competitive moves include hospital procurement committee engagement with clinical evidence packages and cloud platform partnerships satisfying UAE remote monitoring mandates.
Within the multinational tier, Abbott Laboratories, Medtronic, and Dexcom exemplify divergent positioning strategies. Abbott represents manufacturing scale advantages anchored across UAE and Saudi Arabia hospital networks. Medtronic occupies a position emphasizing sustained R&D intensity in real-time algorithm development. Dexcom exemplifies interoperability-focused positioning via platform convergence with insulin pump ecosystems.
| Leading Market Players |
|---|
| Senseonics Holdings |
| Roche Diabetes Care |
| Medtronic |
| Insulet Corporation |
| Ypsomed |
| Abbott Laboratories |
| GlySens Incorporated |
| Novo Nordisk |
| Dexcom |
| Others |
Supply & Pricing Matrix
Enzymatic electrochemical sensor membrane costs cascade through Gulf procurement tiers, compressing margins on factory-calibrated flash systems while sustaining premium positioning for real-time CGM platforms with insulin pump interoperability. Saudi Arabia's Ministry of Health volume aggregation and South Africa's SAHPRA accuracy mandates reshape how vendors stratify pricing across hospital, retail pharmacy, and direct-to-patient channels.
Pricing Analysis
Volume aggregation in Saudi hospital networks compresses per-unit margins while expanding total addressable patient pools through government-funded procurement. Three-tier pricing structure across premium, standard, and economy levels reflects calibration burden, wear duration, and cloud connectivity bundling. Pricing pressure stems from flash glucose monitoring substitution in Nigerian and Kenyan outpatient markets. Uninsured self-monitoring patients in price-sensitive African markets exhibit highest price sensitivity; Saudi hospital procurement committees with centralized tendering authority demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Dubai and Johannesburg anchor hub-and-spoke patterns for temperature-controlled sensor logistics across Gulf and sub-Saharan markets. Manufacturing concentration rests on Ireland, Malaysia, and the United States for electrochemical sensor production. Supply chains draw from platinum-group catalysts, biocompatible adhesives, and Bluetooth-enabled transmitter chipsets. Single-source vulnerability concentrates in UAE port clearance and customs processing for Gulf-bound shipments. Distribution runs through hospital procurement committees, retail pharmacy networks, and emerging direct-to-patient online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
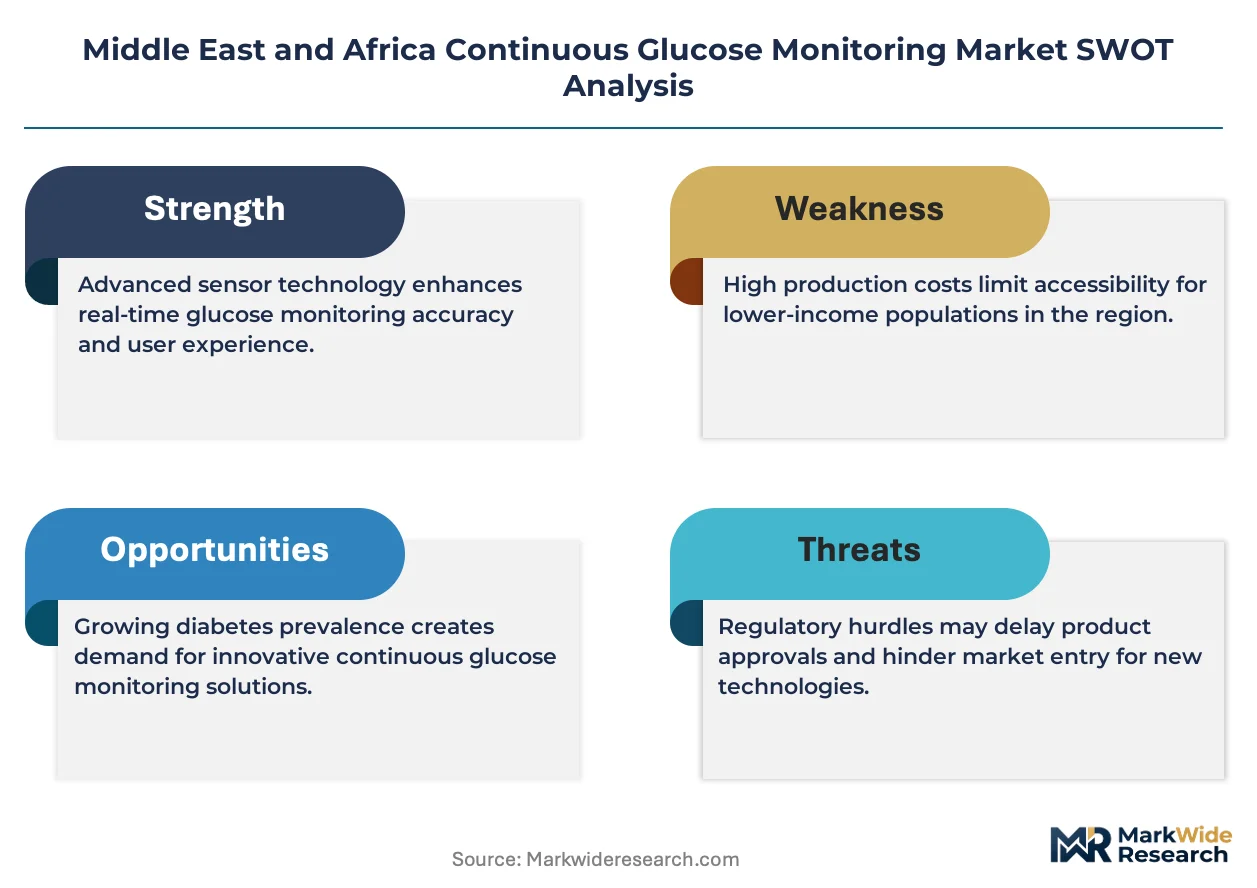
SFDA marketing authorization alignment with European MDR frameworks erects a compliance moat that favors established players with regulatory affairs infrastructure and clinical documentation capabilities. This cost-of-compliance barrier filters out undercapitalized entrants lacking Gulf health system procurement committee relationships.
For Market Incumbents: Cement hospital procurement committee lock-in through multi-year sensor supply agreements covering Saudi Ministry of Health diabetes center networks. Deepen cloud platform partnerships satisfying UAE MOHAP remote monitoring mandates to defend against flash glucose monitoring substitution in outpatient segments. Flash-to-RTGM substitution pressure in South African and Nigerian markets demands accelerated factory-calibrated sensor cost reduction through manufacturing scale. For New Entrants and Emerging Players: Begin with private diabetes clinics in Lagos and Abuja where factory-calibrated flash systems face minimal incumbent saturation and limited calibration-free alternatives. Target community health programs in Kenya and Ethiopia deploying screening-focused glucose monitoring for type 2 diabetes populations previously excluded by real-time CGM cost barriers. Partner with East African temperature-controlled logistics specialists to bypass UAE hub concentration risk. For Investors and Strategic Acquirers: The window for entry favors sensor-integrated insulin pump ecosystem specialists positioning for closed-loop convergence in Saudi hospital networks. Long-term viability hinges on interoperability certification with automated insulin delivery platforms and Gulf health system GPO contract eligibility. Watch SAHPRA procurement standard enforcement velocity as inflection indicator for South African public reimbursement access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Marketing Authorization Pathway | Accelerates Gulf market entry for MDR-aligned device portfolios. |
| Hospital System Partnership | Secures multi-site volume aggregation under Saudi Ministry of Health programs. |
| Cloud Platform Integration | Satisfies UAE MOHAP remote patient monitoring procurement specifications. |
| Insulin Pump Ecosystem Convergence | Positions for premium closed-loop adoption in Saudi hospital networks. |
| Reimbursement Strategy | Shapes addressable patient populations across heterogeneous national health insurance schemes. |
Research Methodology
SFDA medical device registration databases, SAHPRA procurement tender records, and Gulf Cooperation Council health system expenditure reports formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with hospital procurement managers, biomedical engineering directors, diabetes center clinicians, and GPO contracts specialists combined with secondary validation through regulatory filings and customs trade data. Bottom-up patient population modeling and top-down health system expenditure triangulation anchored volume and value estimates across the analysis window.
Bottom-up modeling segmented installed base by technology type, end-user setting, and distribution channel while top-down validation cross-checked against national health insurance reimbursement data. Segmentation dimensions included real-time versus flash glucose monitoring technology, hospital versus homecare versus clinic end-use, and retail pharmacy versus online versus direct sales channel structure. CAGRs derived from patient population growth trajectories, reimbursement policy evolution assumptions, and sensor replacement cycle economics across the projection horizon. Forecast inputs incorporated SFDA approval timeline acceleration effects and SAHPRA accuracy standard displacement of legacy devices.
Underlying measurement precision varies by segment; Saudi hospital procurement volume and UAE connected platform mandates carry tighter precision than Nigerian private clinic demand and Kenyan community health program deployment. Forecasts reflect documented assumptions regarding reimbursement expansion velocity and regulatory alignment timelines. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that biomedical engineering talent scarcity and distribution hub concentration risk could materially revise adoption trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Diabetes Monitors Market