
 Global Atherosclerosis Drugs Market | 2026-2036
Global Atherosclerosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Atherosclerosis Drugs Market Foresight
FDA's Inflation Reduction Act drug pricing provisions are pivoting the cost-of-entry calculus for manufacturers seeking Medicare formulary placement. Pfizer leverages its manufacturing scale to sustain competitive positioning in the statin segment across North American markets. AstraZeneca anchors its portfolio through specialty hospital channels with a focus on integrated cardiovascular care protocols. Amgen differentiates via upstream control over biologic production capacity for PCSK9 inhibitor supply security.
Atherosclerosis drugs comprise pharmaceutical agents that modulate lipid metabolism, inhibit vascular inflammation, or prevent thrombotic events through mechanisms targeting HMG-CoA reductase, PCSK9 receptors, or cholesterol absorption pathways in the intestinal lumen. These therapies serve the primary commercial purpose of reducing myocardial infarction, stroke, and revascularization incidence in patients with established atherosclerotic cardiovascular disease. The statin category occupies the largest revenue pool given decades of clinical validation and generic availability, while PCSK9 inhibitors represent the fastest-expanding segment driven by subcutaneous delivery innovation and residual risk reduction protocols. Coronary artery disease dominates therapy area allocation, though peripheral artery disease is gaining specialist attention as interventional cardiology extends into limb salvage indications.
The FDA, EMA, and Japan's PMDA collectively govern approval standards, with each regulator demanding distinct cardiovascular outcomes trial designs that shape development timelines and label expansions. REACH and RoHS compliance requirements in Europe further constrain excipient sourcing and packaging specifications for manufacturers distributing across multiple jurisdictions. Stakeholders must monitor how CMS negotiation timelines interact with pipeline asset prioritization decisions.
Market Dynamics
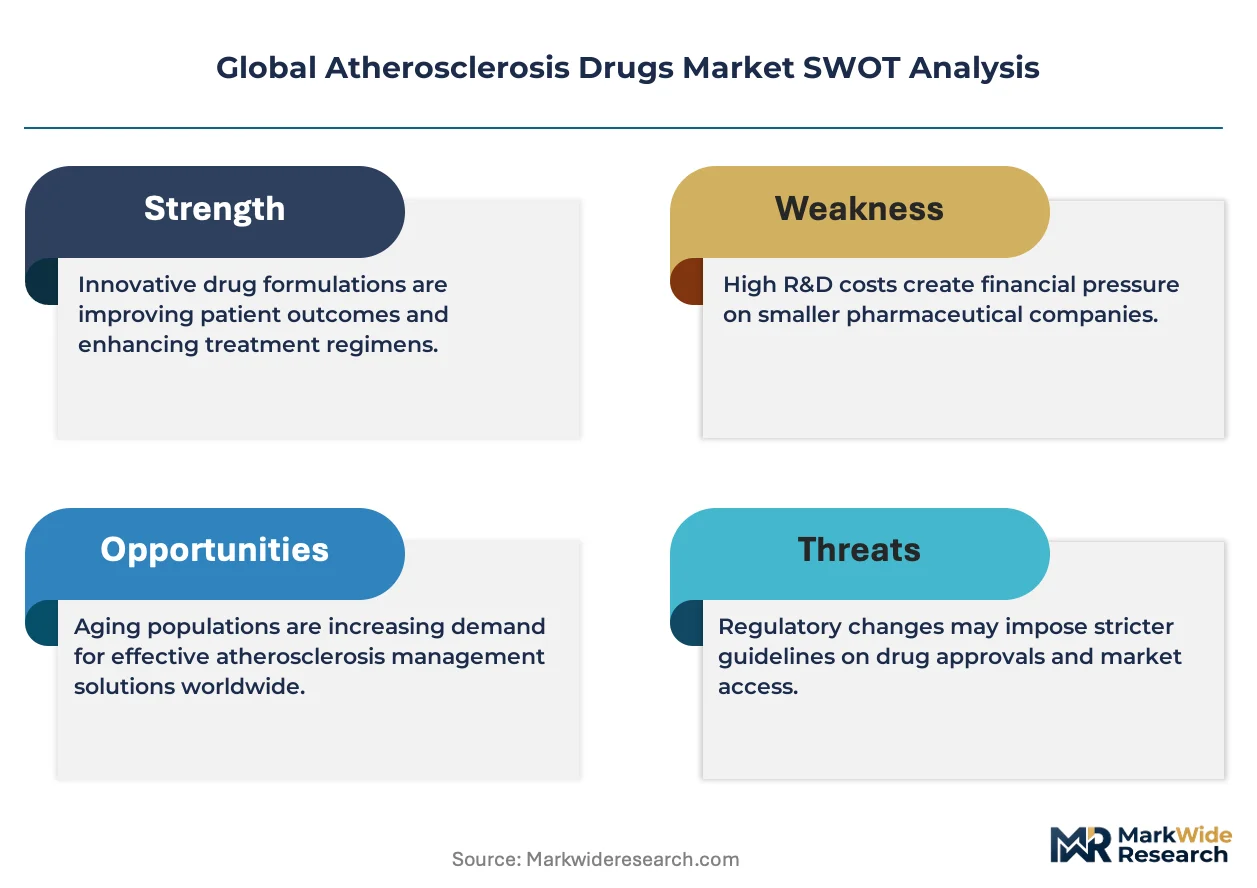
The FDA's accelerated approval pathways for cardiovascular therapies are compressing development timelines while forcing sponsors to design adaptive cardiovascular outcomes trials that satisfy simultaneous EMA and PMDA scrutiny. This regulatory convergence is redrawing competitive entry costs across lipid-lowering and anti-inflammatory drug classes.
Growth Catalysts
- Preventive Cardiology Infrastructure:The United States, Germany, and Japan are deepening hospital-based screening protocols for coronary artery disease, creating pull-through demand for combination lipid therapies in asymptomatic high-risk cohorts.
- Inflation Reduction Act Provisions:Medicare price negotiation timelines are accelerating formulary access decisions, rewarding manufacturers that front-load cardiovascular outcomes data to secure preferential placement.
- Subcutaneous Delivery Innovation:Autoinjector platforms for PCSK9 inhibitors are expanding patient self-administration and reducing clinical burden in cardiology clinics managing polypharmacy regimens.
Market Restraints
- API Supply Concentration:HMG-CoA reductase inhibitor active pharmaceutical ingredients concentrate among Chinese and Indian contract manufacturers, exposing statin supply chains to geopolitical friction and customs delays.
- REACH Compliance Burden:European excipient sourcing requirements under REACH and RoHS constrain formulation flexibility, forcing reformulation investments for multi-jurisdictional product registrations.
- Generic Erosion Intensity:Patent cliffs for atorvastatin and rosuvastatin have collapsed price floors in developed markets, compressing margin recovery windows for novel mechanism assets.
Strategic Opportunities
- Residual Risk Protocols:Cardiology practices in Japan are adopting intensive LDL-C targeting below 20 mg/dL, opening indication expansion for add-on therapies in statin-intolerant populations.
- Peripheral Artery Disease Indications:Interventional cardiology's extension into limb salvage creates new reimbursement pathways for anti-thrombotic and anti-inflammatory agents beyond coronary applications.
- Integrated Care Contracts:German sickness funds are piloting episode-based reimbursement for myocardial infarction prevention, rewarding pharmaceutical partners that bundle diagnostics with therapeutic protocols.
Industry Challenges
- Biostatistics Talent Scarcity:Adaptive trial design expertise for cardiovascular outcomes studies concentrates among a limited pool of specialized contract research organizations, extending study start-up timelines.
- Legacy System Integration:Real-world evidence collection requires connecting electronic health record architectures across hospital networks with disparate data standards, complicating post-market surveillance commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Atherosclerosis Drugs Market |
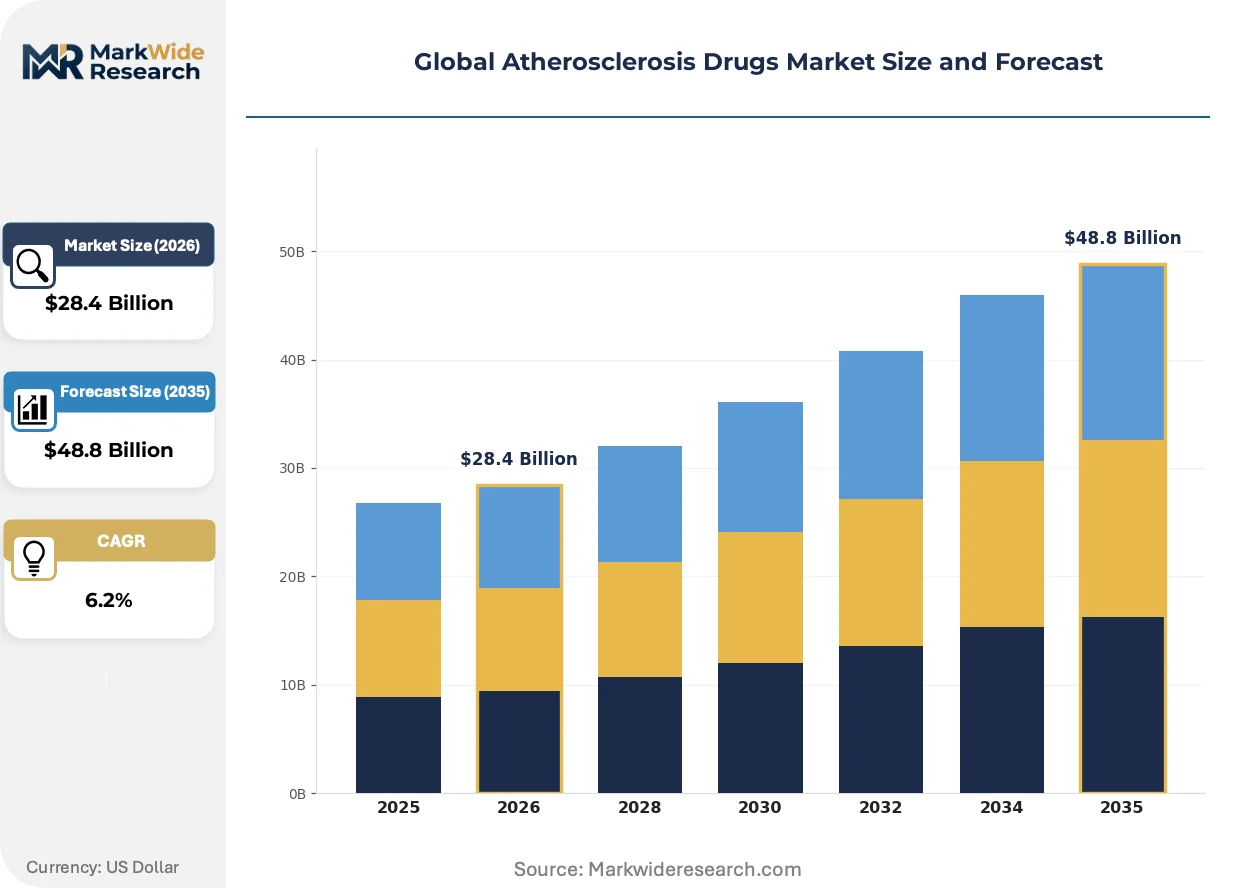
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $48.8 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, PCSK9 Inhibitors, Fibrates, Niacin, Cholesterol Absorption Inhibitors Therapy Area: Coronary Artery Disease, Peripheral Artery Disease, Carotid Artery Disease, Chronic Kidney Disease End User: Cardiology Clinics, Specialty Hospitals, Diagnostic Centers, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Pfizer, AstraZeneca, Amgen, Novartis, Sanofi, Merck & Co., Bayer, Regeneron Pharmaceuticals, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Atherosclerosis Drugs Market Shifts & Advancements
Delivery technology convergence with outcomes-based contracting is reshaping how atherosclerosis therapies penetrate cardiology practices. These shifts are compressing traditional sales models while elevating data integration capabilities.
RNA-interference agents targeting hepatic PCSK9 expression are expanding into quarterly dosing regimens that displace biweekly injection schedules. Large integrated delivery networks in the United States are prioritizing these assets for patient adherence programs. The technology is expanding into populations with established cardiovascular disease who previously failed oral statin therapy.
Europe's Medical Device Regulation and In Vitro Diagnostic Regulation are forcing cardiovascular drug-device combination products through consolidated technical documentation pathways. Manufacturers must now synchronize pharmaceutical quality systems with device risk management files. The EMA's parallel scientific advice process is most affected, with sponsors restructuring development teams to manage dual competency requirements.
Hospital procurement committees are consolidating vendor relationships for cardiovascular therapeutic categories, replacing fragmented physician-driven purchasing with centralized pharmacy and therapeutics oversight. Specialty distributors are losing shelf space to direct manufacturer agreements with health system formularies. This concentration is most visible in German university hospital networks, where integrated care contracts bundle lipid management across inpatient and ambulatory settings.
Global Atherosclerosis Drugs Market Segmentation
Segmentation in atherosclerosis therapeutics reveals how regulatory pathways, clinical settings, and supply chain configurations fragment commercial opportunity. Each dimension carries distinct margin profiles and compliance burdens that reshape manufacturer resource allocation.
Product Type:
FDA, EMA, and PMDA each impose cardiovascular outcomes trial requirements that segment development timelines and label expansions differently across mechanism classes.
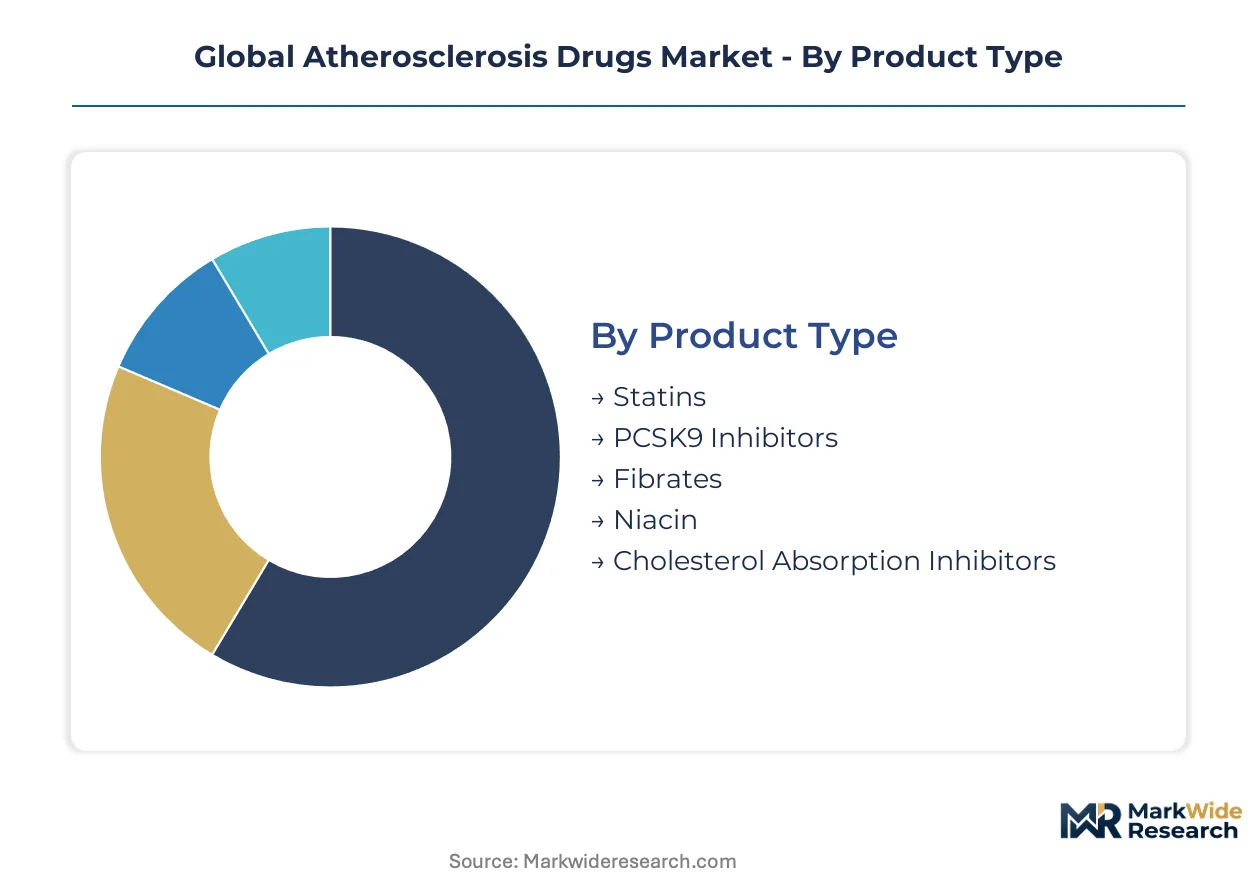
- Statins:HMG-CoA reductase inhibitors with decades of generic erosion have collapsed price floors in developed markets. Demand concentrates in cardiology clinics across the United States and Germany where residual risk protocols still mandate high-intensity LDL-C reduction.
- PCSK9 Inhibitors:Subcutaneous biologics and RNA-interference agents targeting hepatic PCSK9 expression enable quarterly dosing that displaces biweekly schedules. Japanese hospital networks prioritize these for intensive LDL-C targeting below 20 mg/dL in statin-intolerant populations.
- Fibrates:PPAR-alpha agonists for mixed dyslipidemia face reimbursement compression in European markets.
- Niacin:Vitamin B3 derivatives have retreated to niche applications following outcome trial disappointments.
- Cholesterol Absorption Inhibitors:Ezetimibe-class agents persist as combination therapy staples in Medicare formularies.
Statins sit at the top of the volume ranking, with PCSK9 inhibitors climbing the fastest.
Therapy Area:
Clinical trial infrastructure and interventional cardiology penetration determine which indications attract development investment versus generic substitution.
- Coronary Artery Disease:Myocardial infarction prevention commands the largest reimbursement pool. German sickness funds pilot episode-based contracts that bundle diagnostics with therapeutic protocols across hospital networks.
- Peripheral Artery Disease:Limb salvage indications are gaining specialist attention as interventional cardiology extends beyond coronary anatomy. United States academic medical centers are building dedicated peripheral vascular programs.
- Carotid Artery Disease:Stroke prevention protocols concentrate in Japanese preventive cardiology infrastructure.
- Chronic Kidney Disease:Dyslipidemia management in renal impairment remains underpenetrated due to outcome data gaps.
Coronary artery disease dominates current allocation, while peripheral artery disease shows the steepest expansion trajectory.
End User:
Procurement centralization is redrawing account management strategies across institutional settings.
- Cardiology Clinics:Outpatient settings managing polypharmacy regimens favor autoinjector platforms that reduce clinical burden. United States integrated delivery networks consolidate vendor relationships through pharmacy and therapeutics committees.
- Specialty Hospitals:German university hospital networks bundle lipid management across inpatient and ambulatory settings through integrated care contracts.
- Diagnostic Centers:Screening protocols in Japan create pull-through demand for combination therapies in asymptomatic cohorts.
- Research Institutes:Adaptive cardiovascular outcomes trials concentrate among specialized contract research organizations with biostatistics expertise.
Cardiology clinics anchor volume concentration, with specialty hospitals expanding share through episode-based reimbursement pilots.
Distribution Channel:
Channel economics reflect formulary control consolidation and self-administration trends.
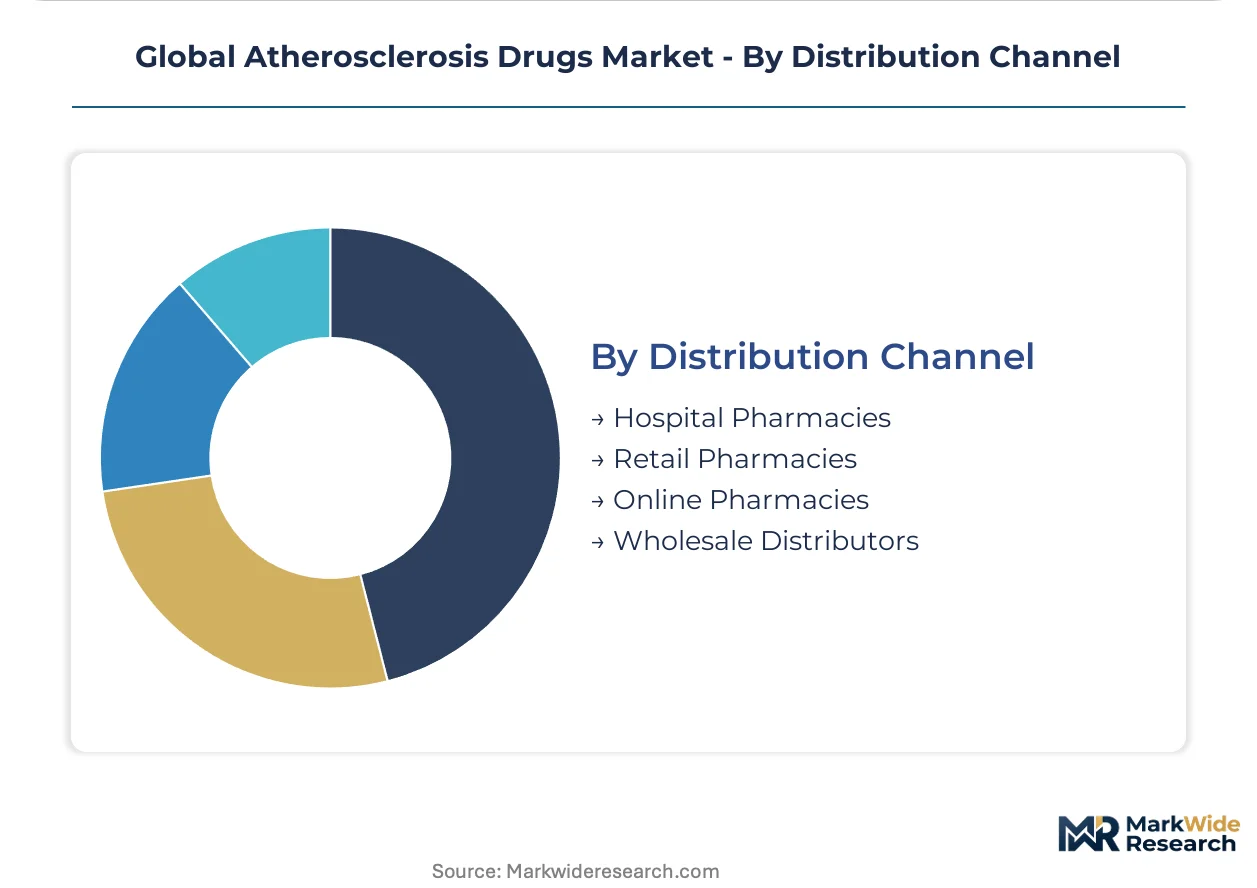
- Hospital Pharmacies:Centralized procurement in German and Japanese health systems captures high-value biologics. Direct manufacturer agreements displace specialty distributors.
- Retail Pharmacies:Generic statin volume concentrates in United States retail chains facing Medicare price negotiation timelines.
- Online Pharmacies:Patient adherence programs for PCSK9 autoinjectors are testing digital refill platforms.
- Wholesale Distributors:API supply concentration among Chinese and Indian contract manufacturers exposes statin distribution to customs friction.
Hospital pharmacies lead value capture, with retail pharmacies defending volume position through generic substitution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular outcomes trial specialists cluster in Boston, Basel, and Tokyo, anchoring regional development capacity. These talent concentrations shape where sponsors locate cardiovascular research infrastructure. Geographic variation in regulatory stringency and reimbursement design fragments commercial entry costs.
United States
Integrated delivery networks in Cleveland and Houston consolidate formulary control through pharmacy and therapeutics committees. The FDA's accelerated approval pathways compress development timelines while mandating confirmatory cardiovascular outcomes studies. Massachusetts hosts the densest concentration of adaptive trial design expertise, with CROs specializing in biostatistics for lipid-lowering agents.
Germany
Sickness funds in Bavaria and North Rhine-Westphalia pilot episode-based reimbursement for myocardial infarction prevention. REACH compliance requirements constrain excipient sourcing for multi-jurisdictional product registrations. The Frankfurt-Rhine-Main corridor anchors pharmaceutical quality system integration with medical device risk management under EMA parallel scientific advice.
Japan
Preventive cardiology infrastructure in Tokyo and Osaka deepens hospital-based screening protocols for asymptomatic high-risk cohorts. PMDA cardiovascular outcomes trial designs demand distinct endpoints from FDA and EMA standards. The Kansai region concentrates specialist expertise in intensive LDL-C targeting below 20 mg/dL for statin-intolerant populations.
United Kingdom
NHS England's specialized commissioning frameworks concentrate high-cost biologic access in London and Manchester academic medical centers. The MHRA's post-Brexit recognition agreements with FDA and EMA reshape parallel submission strategies. The Cambridge-Oxford-London triangle anchors RNA-interference therapeutic development for quarterly PCSK9 dosing regimens.
Switzerland
Swissmedic's streamlined review procedures attract sponsors seeking rapid European market entry for novel lipid-lowering mechanisms. Basel and Zurich host concentrated pharmaceutical manufacturing quality assurance expertise. The country's bilateral agreements with EU regulatory frameworks enable simplified distribution logistics into German and French hospital networks.
Global Atherosclerosis Drugs Market Competitive Landscape
The competitive structure tilts toward large-cap incumbents with cardiovascular franchise depth. Pfizer, AstraZeneca, and Amgen anchor the top tier through manufacturing scale, specialty hospital channel control, and biologic production capacity respectively. Mid-tier players compete through indication expansion in peripheral artery disease and residual risk protocols. Dominant competitive moves include strategic partnerships for autoinjector platform access and geographic licensing to secure PMDA and EMA parallel approvals.
Within the scale-driven archetype, Pfizer leverages North American manufacturing infrastructure to defend statin segment positioning. AstraZeneca and Amgen occupy distinct strategic positions: the former anchors integrated cardiovascular care protocols through specialty hospital channels, while the latter exemplifies upstream control over biologic production capacity for supply security in PCSK9 inhibitor manufacturing. Novartis and Sanofi sit within the innovation-tier, representing RNA-interference and monoclonal antibody platform specialists respectively.
| Leading Market Players |
|---|
| Pfizer |
| AstraZeneca |
| Amgen |
| Novartis |
| Sanofi |
| Merck & Co. |
| Bayer |
| Regeneron Pharmaceuticals |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Captive production of HMG-CoA reductase inhibitor APIs anchors margin structures for statin manufacturers while exposing them to customs friction at key ports. This integration choice concentrates pricing power among vertically integrated incumbents but leaves reformulation-dependent players vulnerable to REACH-driven excipient cost spikes.
Pricing Analysis
Bundled episode-based reimbursement in German sickness funds contrasts with unbundled per-unit pricing in United States retail channels. Three-tier pricing structure across premium biologics, standard branded agents, and economy generics reflects FDA certification tier and manufacturing scale. Cost compression in the generic statin tier intensifies because Medicare price negotiation timelines accelerate formulary access decisions. Hospital procurement committees show lowest price sensitivity due to integrated care contract bundling, while retail pharmacy chains face highest sensitivity from generic substitution economics.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's dual carbon goals are reshaping API sourcing patterns for contract manufacturers. Active pharmaceutical ingredient production concentrates in China, India, and select European hubs. Finished formulation depends on biologics manufacturing capacity in Switzerland, Singapore, and Puerto Rico. Single-source vulnerability in HMG-CoA reductase inhibitor intermediates exposes statin supply chains to geopolitical friction. Distribution runs through hospital pharmacy central procurement in German and Japanese health systems, with direct manufacturer agreements displacing specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atherosclerosis drugs market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations with established cardiovascular disease. Preventive cardiology infrastructure investments in the United States, Germany, and Japan sustain pull-through demand regardless of macroeconomic cycles.
For Market Incumbents: Deepen upstream control over PCSK9 biologic production capacity to defend against emerging RNA-interference platform specialists. Secure preferred formulary placement by front-loading cardiovascular outcomes data ahead of CMS negotiation timelines. Expand manufacturing footprint in Switzerland to exploit Swissmedic's streamlined review procedures for rapid European market entry.
For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for value-based pricing models that displace traditional per-unit reimbursement. Target peripheral artery disease indications where interventional cardiology extension creates new reimbursement pathways with limited incumbent presence. Pursue autoinjector platform partnerships with large integrated delivery networks to bypass fragmented physician-driven purchasing.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier cardiovascular specialists because hospital procurement consolidation favors scaled formulary vendors over fragmented niche players. Focus acquisition screening on firms with adaptive trial design capabilities and PMDA parallel approval experience. Watch Japanese intensive LDL-C targeting protocols below 20 mg/dL as the signal for residual risk protocol expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Adaptive cardiovascular outcomes designs satisfy simultaneous FDA, EMA, and PMDA scrutiny requirements. |
| Manufacturing Scale-Up | Biologic production capacity expansion in Singapore secures PCSK9 inhibitor supply security for Japanese hospital networks. |
| Regulatory Approval Pathway | Swissmedic streamlined review attracts sponsors seeking rapid European entry for novel lipid-lowering mechanisms. |
| Strategic Partnership | Autoinjector platform access agreements reduce clinical burden in United States cardiology clinics managing polypharmacy. |
| Pipeline Diversification | RNA-interference agents targeting hepatic PCSK9 expression enable quarterly dosing regimens displacing biweekly schedules. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and regulatory timing uncertainties. Primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed pipeline prioritization assumptions. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Historical reference periods spanning pre-pandemic baseline through post-acceleration normalization established trendline anchors across the projection horizon. Segmentation modeling incorporated treatment line, dosage form, administration route, patient population, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to each segment with cross-validation against clinician adoption curve research. Forecast inputs included PMDA cardiovascular outcomes trial timelines and German sickness fund episode-based reimbursement pilot expansion rates.
Revisions become necessary when FDA accelerated approval pathway requirements shift, Medicare negotiation timelines compress, or API supply concentration triggers customs disruptions. Forecasts reflect documented assumptions about regulatory convergence and procurement centralization trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Botulinum Toxin Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Calcium Channel Blocker Market