
 Global Epilepsy Drug Market | 2026-2036
Global Epilepsy Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Global Epilepsy Drug Market Analysis
Pediatric neurology is recalibrating the end-use mix for epilepsy therapeutics as specialist centers expand their formularies beyond first-line generics. UCB Inc. dominates the biologics segment for refractory cases through its established neurology franchise. Pfizer Inc. leverages its global manufacturing scale to sustain supply of established antiepileptic molecules across emerging markets. Novartis AG differentiates through its orphan drug portfolio targeting rare epilepsy syndromes.
Epilepsy drugs comprise anticonvulsant pharmaceutical agents formulated as small molecules, biologics, or combination therapies that modulate neuronal excitability through sodium channel blockade, GABA enhancement, or glutamate inhibition to prevent seizure propagation. These agents serve the primary commercial purpose of chronic disease management across outpatient, inpatient, and homecare settings. Brand formulations and orphan drugs command concentrated margin pools due to patent protection and limited competition, while generic oral tablets anchor volume across retail pharmacy channels. The intravenous administration route supports acute seizure management in hospital settings where reimbursement rates favor parenteral delivery.
FDA orphan drug designations and EMA centralized marketing authorizations shape product development priorities and market access timelines for manufacturers. Japan's PMDA accelerates review pathways for pediatric epilepsy indications, creating differentiated entry points for novel mechanisms. Stakeholders must monitor how reimbursement negotiations in Germany's G-BA framework and India's CDSCO manufacturing standards reshape competitive positioning between originator and generic portfolios.
Market Dynamics
Orphan drug designation pathways from the FDA and EMA are compressing development timelines for novel antiepileptic mechanisms, forcing established manufacturers to accelerate biologics pipelines while defending small-molecule franchises against generic erosion.
Growth Catalysts
- PMDA Pediatric Review Pathways:Japan's accelerated timelines for childhood epilepsy indications are pulling novel mechanism submissions toward Tokyo filing strategies.
- Refractory Case Biologics:Specialist epilepsy centers in the United States are expanding formulary access for monoclonal antibody therapies targeting drug-resistant patient populations.
- EMA Centralized Authorizations:The centralized marketing authorization procedure is enabling simultaneous market entry across Germany, France, and Italy for rare syndrome therapies.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of sodium channel modulators depends on concentrated intermediate suppliers in Zhejiang province, exposing formulation networks to single-source disruption.
- G-BA Reimbursement Negotiations:Germany's Federal Joint Committee is extending price arbitration timelines for orphan-designated antiepileptics, delaying commercial launch revenue recognition.
- Generic Substitution Mandates:Automatic substitution laws in multiple US states are compressing brand prescription duration for established anticonvulsants.
Strategic Opportunities
- Homecare Infusion Services:Parenteral antiepileptic administration is migrating from hospital neurology wards to specialized home infusion networks in suburban United States markets.
- CDSCO Manufacturing Partnerships:India's central drug regulator is harmonizing active pharmaceutical ingredient standards with ICH guidelines, enabling contract manufacturing for export-oriented biologics.
- Digital Therapeutic Adjuncts:FDA-cleared seizure detection algorithms are creating bundled reimbursement opportunities for pharmaceutical-device combination protocols.
Industry Challenges
- Pediatric Trial Recruitment:Rare epilepsy syndrome trials face enrollment bottlenecks due to dispersed patient geography and competing academic center protocols.
- Biologics Cold Chain Integrity:Temperature-controlled distribution for monoclonal antibody therapies requires validated logistics partnerships that exceed small-molecule infrastructure standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Epilepsy Drug Market |
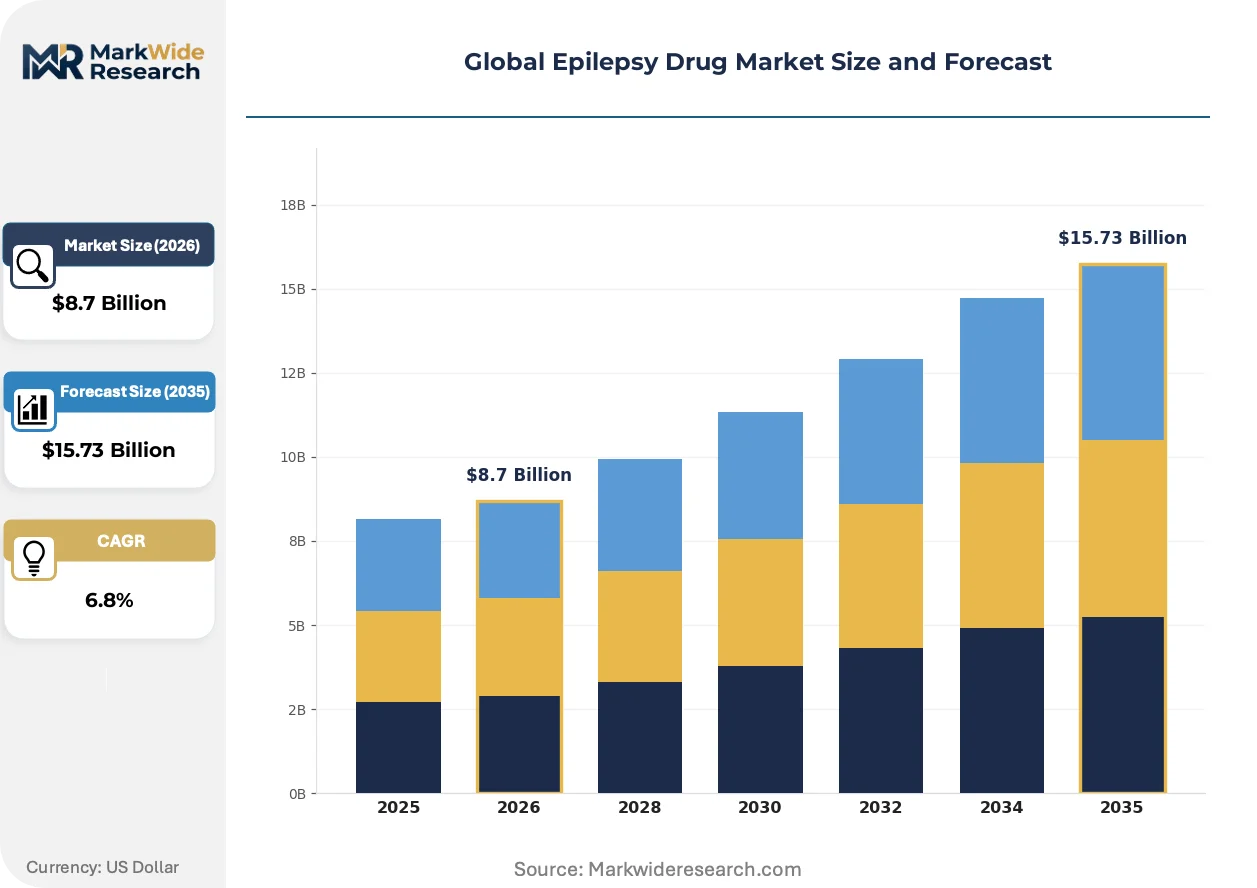
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Generic, Brand, Combination Therapy, Orphan Drugs Administration Route: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Distribution Channel: Retail Pharmacies, E-commerce, Hospital Pharmacies, Wholesalers |
| Companies Covered | UCB Inc., Pfizer Inc., Novartis AG, GlaxoSmithKline plc, Eisai Co., Ltd., H. Lundbeck A/S, Abbott Laboratories, Sanofi, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Epilepsy Drug Market Emerging Trajectories
Gene therapy vectors and precision dosing platforms are displacing one-size-fits-all anticonvulsant protocols, while real-world evidence requirements are reshaping post-market study obligations across regulatory jurisdictions.
Antisense oligonucleotide therapies targeting SCN1A and other monogenic epilepsy variants are modularizing the clinical development pathway. Biopharmaceutical developers are adopting platform manufacturing approaches that separate payload synthesis from delivery vehicle production. This architecture is compressing timeline risk for subsequent rare syndrome indications by enabling regulatory cross-referencing of toxicology and manufacturing data.
REACH registration requirements for novel chemical entities are extending pre-market environmental fate assessments for small-molecule antiepileptics. The European Chemicals Agency is requiring aquatic toxicity data for metabolites that previously escaped scrutiny. Formulation scientists are responding by prioritizing biodegradable prodrug structures in early discovery portfolios to preempt authorization delays.
Specialist epilepsy centers are consolidating purchasing decisions through centralized pharmacy and therapeutics committees. Academic medical centers in the United States are displacing individual prescriber autonomy with protocol-driven formulary adherence. This concentration is compressing brand access for newer entrants while entrenching established relationships with incumbent manufacturers.
Global Epilepsy Drug Market Segmentation
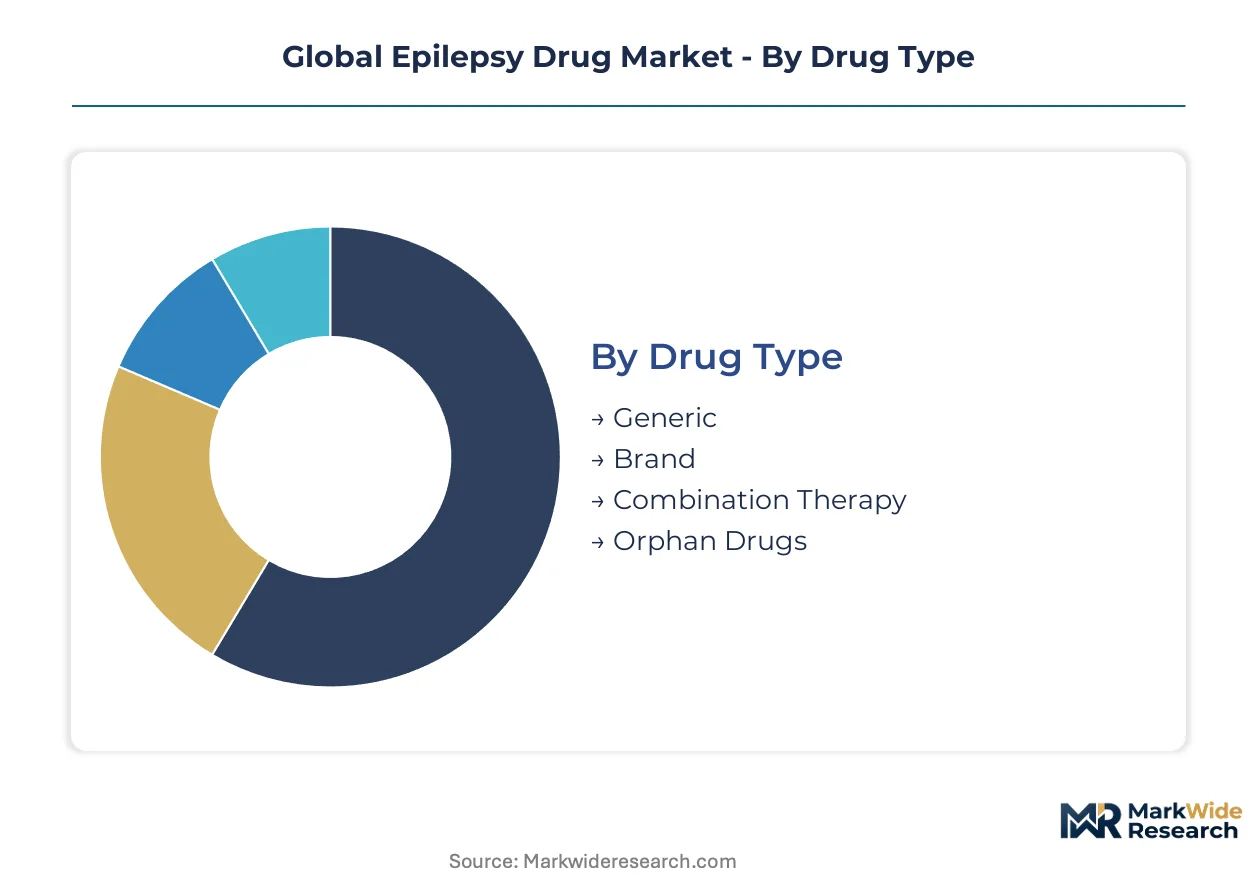
Epilepsy drug segmentation reveals how reimbursement pathways and patient acuity reshape commercial strategy across formulation types and care settings. Manufacturers must align portfolio investments with where prescribing authority and purchasing decisions actually concentrate.
Drug Type:
Cost tier and patent status differentiate buyers through reimbursement pressure and clinical positioning.
- Generic:Small-molecule anticonvulsants with expired patent protection anchor volume across retail pharmacy channels. Medicaid formularies and automatic substitution laws in multiple US states compress brand duration, forcing manufacturers to defend through manufacturing reliability and authorized generic strategies.
- Brand:Patent-protected formulations command concentrated margin pools through specialist prescriber relationships and prior authorization requirements. Germany's G-BA framework and Japan's NHI price listings shape access timelines for novel small molecules.
- Combination Therapy:Fixed-dose and adjunctive regimens target polytherapy-resistant patients through simplified adherence profiles.
- Orphan Drugs:FDA and EMA designations for rare epilepsy syndromes enable premium pricing with limited competition.
Generic formulations lead volumes today; orphan drugs are gaining share fastest.
Administration Route:
Patient acuity and care setting dictate route selection through reimbursement and logistics requirements.
- Oral:Tablets and capsules dominate chronic outpatient management through pharmacy benefit coverage. Germany's retail pharmacy substitution rules and US Medicare Part D tier structures shape competitive dynamics for immediate versus extended-release formulations.
- Intravenous:Parenteral delivery supports acute seizure management in hospital neurology wards and emergency departments where DRG reimbursement favors inpatient administration. Temperature-controlled distribution requirements exceed oral infrastructure standards.
- Subcutaneous:Self-administered biologics for refractory cases enable home-based chronic therapy.
- Transdermal:Patch formulations address adherence challenges in pediatric and geriatric populations.
Oral administration leads volumes today; subcutaneous biologics are expanding most quickly.
End User:
Purchasing authority and patient complexity segment buyers across institutional and ambulatory settings.
- Hospitals:Academic medical centers and specialist epilepsy centers consolidate formulary decisions through pharmacy and therapeutics committees. US children's hospitals and German university hospitals drive adoption of novel mechanisms through protocol-driven care pathways.
- Clinics:Pediatric neurology and epilepsy specialist practices prescribe based on academic center referral patterns and prior authorization requirements.
- Homecare:Infusion nursing services and family caregivers administer parenteral therapies outside institutional settings.
- Rehabilitation Centers:Post-acute facilities manage seizure recurrence risk in brain injury recovery populations.
Hospitals lead volumes today; homecare services are climbing the fastest.
Distribution Channel:
Supply chain configuration and patient access requirements differentiate channel economics.
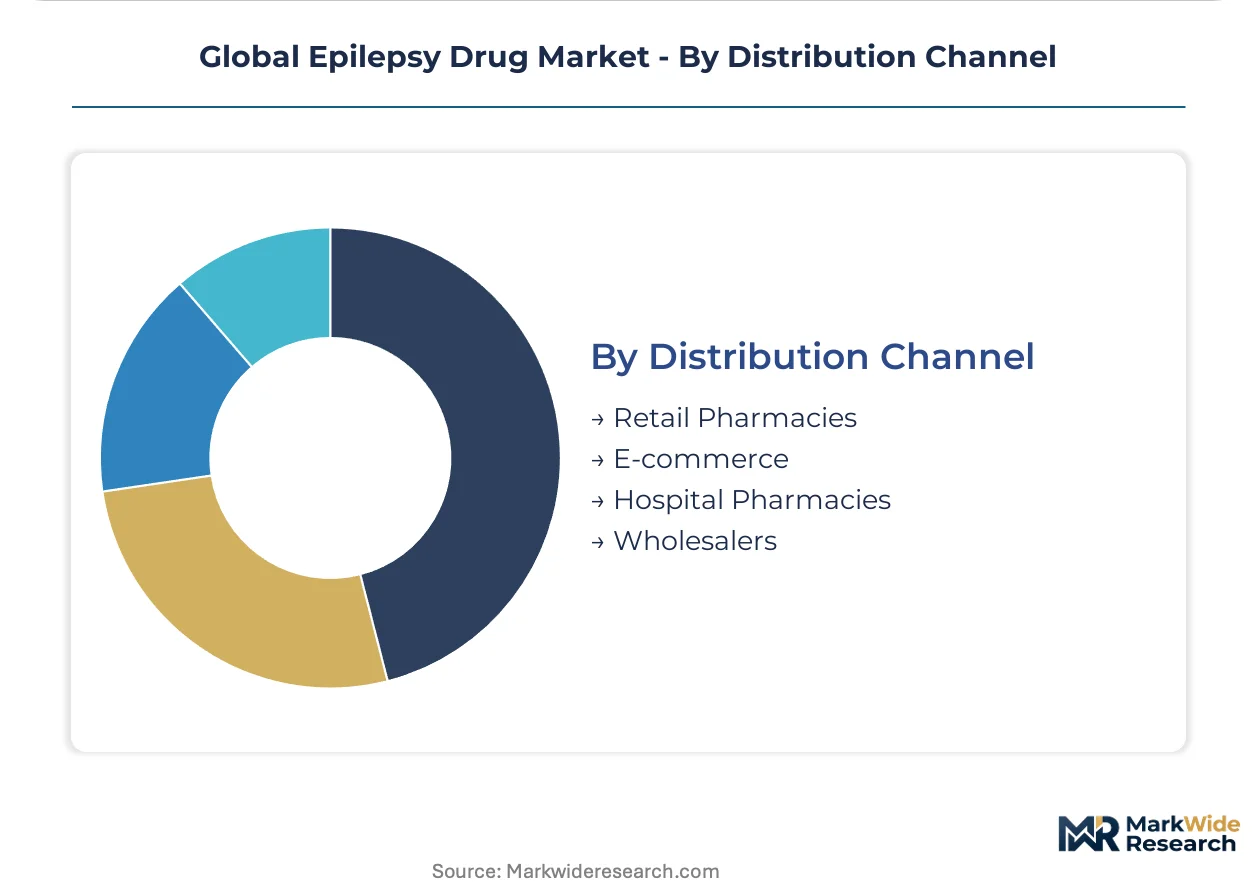
- Retail Pharmacies:Community pharmacy networks dispense oral generics and brand maintenance therapies. India's CDSCO manufacturing standards and US state board regulations shape sourcing for export-oriented and domestic supply chains.
- E-commerce:Direct-to-patient platforms and specialty pharmacy portals enable orphan drug delivery with cold chain validation.
- Hospital Pharmacies:Inpatient formularies control acute parenteral access through centralized purchasing agreements.
- Wholesalers:Three-tier distribution networks aggregate demand across fragmented retail and institutional accounts.
Retail pharmacies lead volumes today; e-commerce platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's specialist epilepsy centers anchor North American demand for biologic therapies, while regulatory pathways in Japan and Germany reshape competitive entry timelines for novel mechanisms.
United States
Academic medical centers in Boston and Philadelphia drive orphan drug adoption through protocol-driven formulary committees. FDA breakthrough therapy designations compress review timelines for rare syndrome indications. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing for parenteral antiepileptic formulations.
Germany
University hospitals in Munich and Heidelberg consolidate purchasing decisions for refractory case therapies through centralized pharmacy committees. The G-BA's early benefit assessment framework extends price arbitration timelines for novel antiepileptics. The Rhine-Main biotech corridor near Frankfurt hosts specialized cold chain logistics for monoclonal antibody distribution.
Japan
Pediatric neurology clinics in Tokyo and Osaka accelerate novel mechanism adoption through PMDA's sakigake designation pathway. The regulator's pediatric review timelines pull submission strategies toward Tokyo filings. The Kansai region's pharmaceutical manufacturing base supplies extended-release formulations across Asia-Pacific markets.
India
Specialist epilepsy centers in Mumbai and Delhi expand access to imported biologics while domestic manufacturers scale generic anticonvulsant production. CDSCO's harmonization with ICH guidelines enables contract manufacturing partnerships for export-oriented active pharmaceutical ingredients. The Hyderabad-Visakhapatnam corridor concentrates synthesis capacity for sodium channel modulator intermediates.
United Kingdom
NHS specialist commissioning hubs in London and Manchester gate access to high-cost orphan therapies through technology appraisal processes. NICE's highly specialized technologies program creates dedicated funding pathways for rare epilepsy syndromes. The Cambridge-London biotech cluster advances antisense oligonucleotide platforms for monogenic variants.
Global Epilepsy Drug Market Vendor Landscape
Portfolio diversification dominates the current landscape as established neurology franchises defend against generic erosion. The market structures around three tiers: integrated pharmaceutical conglomerates with global manufacturing scale, mid-cap biotech specialists focused on orphan mechanisms, and regional generic manufacturers competing on cost. Strategic archetypes include the neurology-focused biologic developer, the diversified small-molecule incumbent, and the emerging market generic anchor. M&A activity concentrates on gene therapy platform acquisitions, while capacity expansion targets parenteral formulation capacity for homecare migration.
Within the integrated pharmaceutical tier, UCB Inc. and Pfizer Inc. exemplify divergent strategic postures. The Brussels-based biopharmaceutical company anchors the neurology-focused archetype through its established epilepsy franchise. The New York-based conglomerate occupies the diversified incumbent position, leveraging manufacturing scale across emerging markets. Novartis AG represents the orphan drug specialist vector, with its Basel headquarters signaling European regulatory sophistication for rare syndrome therapies.
| Leading Market Players |
|---|
| UCB Inc. |
| Pfizer Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Eisai Co., Ltd. |
| H. Lundbeck A/S |
| Abbott Laboratories |
| Sanofi |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient spot prices for sodium channel modulator intermediates cascade through formulation networks into three-tier pricing structures across premium orphan biologics, patent-protected brand small molecules, and commoditized generic tablets. Zhejiang province supply disruptions transmit directly into US Medicaid formulary tier placements and German G-BA arbitration timelines, compressing margin pools at the generic anchor while insulating biologic premiums through cold chain scarcity.
Pricing Analysis
Input-cost pass-through from concentrated intermediate suppliers in eastern China drives pricing stratification across premium orphan biologics, patent-protected brand formulations, and economy generic tablets. Quality grade differentiation separates FDA breakthrough-designated therapies from standard-of-care small molecules, while volume scale discounts anchor retail pharmacy procurement for chronic outpatient management. Pricing pressure stems from automatic substitution mandates in multiple US states, eroding brand prescription duration. Medicaid formularies exhibit highest price sensitivity; specialist epilepsy centers demonstrate lowest sensitivity due to protocol-driven formulary adherence.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Tokyo, and Research Triangle Park coordinate hub-and-spoke patterns for temperature-sensitive monoclonal antibody therapies. Manufacturing concentration centers on India for generic API synthesis, Switzerland for biologics fill-finish, and Japan for extended-release formulation technology. Raw material dependencies include Zhejiang-sourced sodium channel intermediates, Swiss bioreactor media, and German chromatography resins. Single-source vulnerability in Chinese intermediate suppliers exposes formulation networks to geopolitical disruption. Distribution runs through specialized cold chain logistics partnerships exceeding small-molecule infrastructure standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in epilepsy therapeutics rests on biologics cold chain premiumization and generic manufacturing automation cost-downs, with orphan drug pricing power insulating against formulary compression.
For Market Incumbents: Hedge generic erosion through authorized generic strategies and backward integration into Indian API manufacturing. Defend biologic franchises by deepening specialist epilepsy center relationships through protocol-driven care pathway sponsorship. Prioritize cold chain capacity expansion in the Rhine-Main corridor to secure monoclonal antibody distribution exclusivity against emerging entrants. For New Entrants and Emerging Players: Antisense oligonucleotide platform technologies offer a technology-first wedge into Dravet syndrome and other SCN1A-driven indications with limited incumbent penetration. Target pediatric neurology clinics in Japan through PMDA sakigake pathway submissions, where accelerated review timelines compress competitive entry gaps. Pursue bundled reimbursement with FDA-cleared seizure detection algorithms to differentiate from standalone pharmaceutical offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with gene therapy platform developers targeting monogenic epilepsy variants, where clinical validation creates irreversible competitive moats. Long-term viability favors biopharmaceutical developers with modular manufacturing architectures enabling regulatory cross-referencing across rare syndrome indications. Watch for inflection in homecare infusion network coverage expansion as signal of parenteral therapy migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA and EMA designations compress development timelines while enabling premium pricing for rare syndrome therapies. |
| Cold Chain Logistics Partnership | Validated temperature-controlled distribution secures monoclonal antibody access to specialist epilepsy centers. |
| Platform Manufacturing Scale-Up | Modular payload-delivery separation compresses timeline risk for subsequent rare syndrome indications. |
| Digital Therapeutic Bundling | FDA-cleared seizure detection algorithms create reimbursement opportunities for pharmaceutical-device combinations. |
| Pediatric Trial Network Expansion | Academic medical center partnerships address enrollment bottlenecks in dispersed rare syndrome populations. |
Methodological Framework
Direct dialogue with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists grounded qualitative insights in operational reality across the value chain. Secondary validation drew from FDA orphan drug designations, EMA centralized marketing authorizations, ClinicalTrials.gov enrollment data, and German G-BA benefit assessment documents. Bottom-up prescription volume modeling and top-down epidemiological incidence estimates triangulated market sizing across the analysis window.
Segmented outputs across drug type, administration route, end user, and distribution channel dimensions enabled granular scenario testing throughout the projection horizon. CAGRs derived from patent cliff timing, generic entry assumptions, and biologics adoption curve modeling in refractory patient populations. Forecast inputs incorporated PMDA pediatric review pathway acceleration rates and CDSCO manufacturing standard harmonization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy clinical trial readouts and biosimilar entry timelines in monoclonal antibody categories. Outputs reflect documented assumptions around reimbursement negotiation durations and regulatory approval velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Global Plasma Derived Therapy Market