
 Photophobia Drug Market | 2026-2036
Photophobia Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Photophobia Drug Market Analysis
Market Context
Specialized neuro-ophthalmology training programs are reorganizing how photophobia therapeutics reach patients through advanced diagnostic protocols. Pfizer Inc leverages its established neurology infrastructure to sustain distribution across hospital networks. Sun Pharmaceutical Industries Ltd anchors its position through cost-competitive generic formulations. Novartis AG differentiates via targeted R&D investments in migraine-related light sensitivity pathways.
Technical and Segment Structure
Photophobia drugs comprise pharmaceutical agents that modulate photosensitive neural pathways, including triptan-class compounds, NSAID formulations, and specialized ophthalmic preparations designed to reduce light-induced pain transmission. Prescription drugs dominate current revenue pools, while over-the-counter medications capture expanding self-directed patient segments. Home care settings represent the fastest-growing end-user channel as remote monitoring technologies enable outpatient photophobia management, though hospitals retain the highest-margin acute-care applications.
Regulatory Environment
FDA oversight governs novel photophobia drug approvals through neurology and ophthalmology divisions, while EMA's centralized procedure shapes European market access for light-sensitivity therapeutics. The FDA's breakthrough therapy designation for migraine drugs directly accelerates photophobia indication expansions. Stakeholders must monitor evolving pharmacovigilance requirements for ophthalmic delivery modes as regulatory scrutiny intensifies on localized side-effect profiles.
Market Dynamics
FDA breakthrough therapy designations for migraine therapeutics are accelerating photophobia indication expansions, compressing clinical trial timelines and reshaping how pharmaceutical firms allocate neurology R&D budgets toward light-sensitivity pathways.
Growth Catalysts
- Specialized headache centers:United States-based tertiary care facilities are standardizing photophobia screening protocols, driving prescription volumes for targeted therapeutics through integrated neuro-ophthalmology departments.
- EMA centralized procedure:Streamlined European market access for light-sensitivity drugs reduces regulatory duplication, enabling faster cross-border distribution of novel ophthalmic preparations.
- Remote monitoring platforms:Telehealth-enabled photophobia management is extending treatment reach into rural and underserved patient populations previously excluded from specialized care.
Market Restraints
- Active pharmaceutical ingredient concentration:Manufacturing of triptan-class compounds concentrates among Indian and Chinese contract manufacturers, creating supply vulnerability from single-source dependencies.
- Specialized formulation costs:Ophthalmic delivery modes require sterile manufacturing capabilities that inflate production costs relative to oral dosage forms, compressing margins for generic entrants.
- Reimbursement heterogeneity:Medicaid formulary restrictions in multiple US states limit access to newer photobia therapeutics, fragmenting addressable patient pools.
Strategic Opportunities
- Pediatric migraine protocols:Underpenetrated treatment guidelines for adolescent photobia present expansion potential as the American Academy of Neurology revises pediatric headache management standards.
- Home care channel development:Direct-to-patient distribution models bypass traditional hospital pharmacy gatekeepers, capturing margin from acute-care diversion.
- Biomarker-guided prescribing:Convergence of genetic screening and photophobia phenotyping enables precision medicine approaches that command premium positioning.
Industry Challenges
- Neuro-ophthalmology specialist scarcity:Fellowship-trained clinicians capable of differential photobia diagnosis remain concentrated in major metropolitan academic centers, constraining diagnostic throughput.
- Pharmacovigilance infrastructure:Post-market surveillance requirements for localized ophthalmic side effects demand specialized adverse event reporting systems that smaller manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photophobia Drug Market |
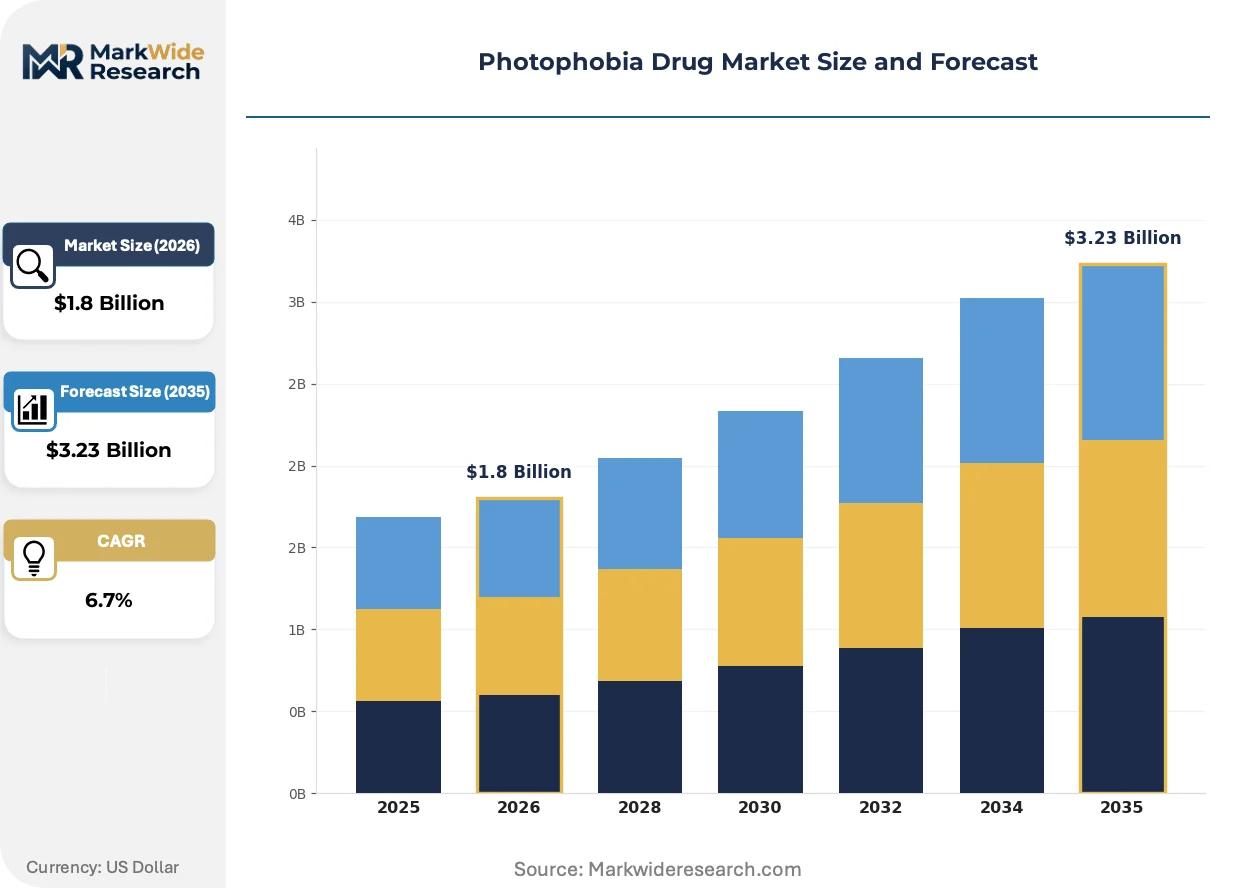
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Eye Drops, Topical Treatments Application: Chronic Pain Management, Migraine Relief, Eye Disorders, Post-Surgical Care End User: Clinics, Hospitals, Home Care Settings, Rehabilitation Centers Delivery Mode: Oral, Injectable, Transdermal, Ophthalmic |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Pfizer Inc, GlaxoSmithKline plc, Allergan, Novartis AG, Merck & Co, Johnson & Johnson, AbbVie Inc, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photophobia Drug Market Emerging Trajectories
Novel delivery mechanisms and diagnostic biomarkers are restructuring competitive positioning in photophobia therapeutics, with technology convergence between neurology and ophthalmology creating new product categories.
Intranasal triptan formulations are supplanting oral administration routes for acute photobia episodes, with emergency departments and urgent care networks adopting these delivery modes to bypass gastrointestinal absorption variability. The structural consequence is compression of time-to-therapeutic-effect metrics that now define formulary placement decisions.
EMA's expanded pharmacovigilance requirements under the Medical Device Regulation are mandating real-world evidence collection for combination drug-device photobia products. Manufacturers must now integrate post-market surveillance into product lifecycle planning, with ophthalmic delivery systems facing heightened scrutiny on localized adverse event profiles.
Self-directed patient research is fragmenting traditional physician-centric prescription pathways, with online migraine communities and direct-to-consumer genetic testing services reshaping how individuals identify and seek treatment for light sensitivity. This behavioral shift is most pronounced in United States metropolitan markets where healthcare consumerism intersects with high-speed telehealth infrastructure.
Photophobia Drug Market Segmentation
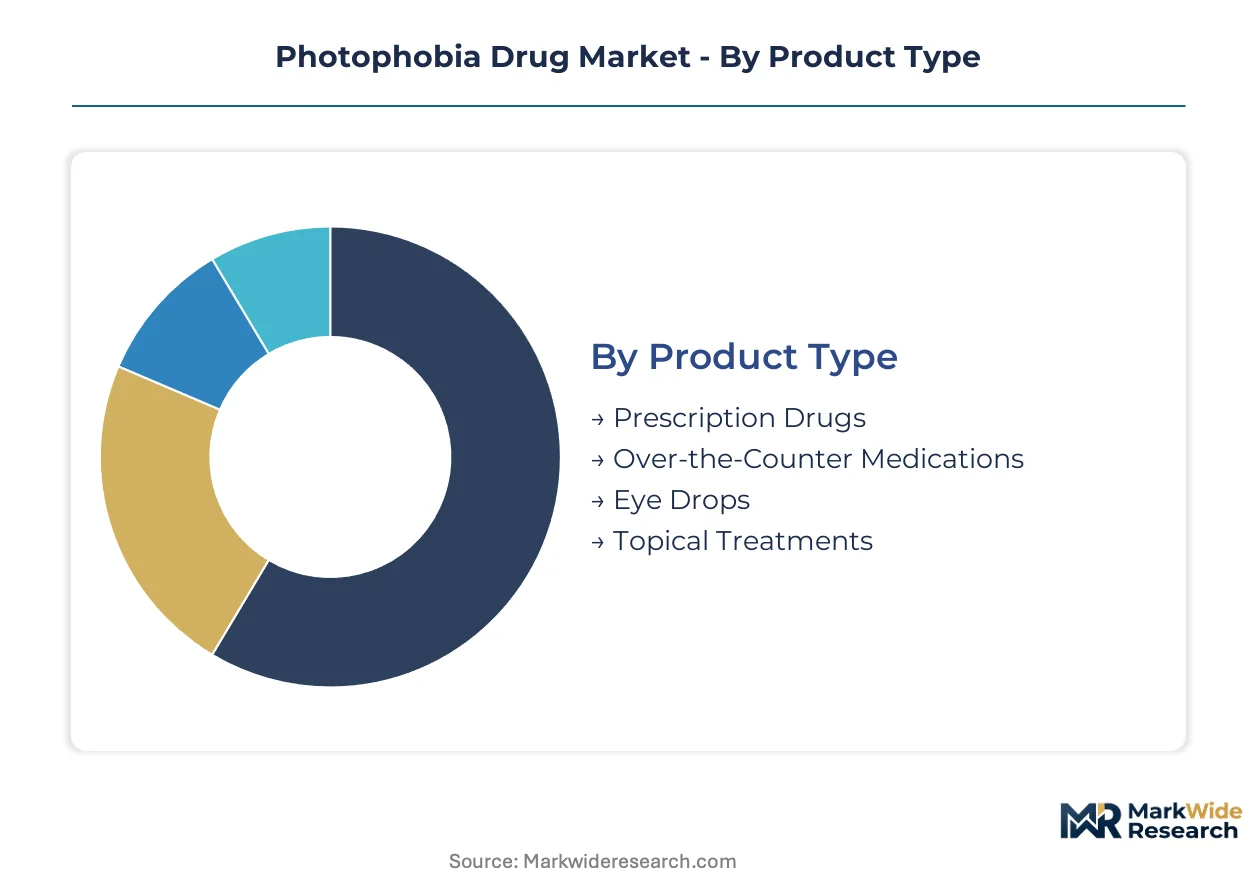
Photophobia drug segmentation reveals distinct channel economics where prescription flows through hospital networks while over-the-counter products leverage retail pharmacy and direct-to-patient routes. Understanding these pathway divergences shapes portfolio allocation and margin capture strategies for manufacturers.
Product Type:
Hospital pharmacies and retail chains split volume differently across these categories, with prescription drugs requiring specialist gatekeeping while self-directed purchases bypass clinical oversight.
- Prescription Drugs:Triptan-class compounds and specialized neurology formulations dominate hospital formularies. United States tertiary headache centers drive volume through neuro-ophthalmology protocols that mandate physician-controlled dispensing.
- Over-the-Counter Medications:NSAID-based light-sensitivity remedies reach patients through pharmacy retail and e-commerce channels. Self-directed migraine management in metropolitan markets accelerates uptake without specialist referral.
- Eye Drops:Ophthalmic preparations target acute photic pain through sterile formulations requiring specialized manufacturing.
- Topical Treatments:Transdermal and localized applications serve niche patient populations with compound medication needs.
By volume, Prescription Drugs leads. By growth pace, Over-the-Counter Medications is climbing the fastest as patient self-education fragments traditional prescribing pathways.
Application:
Cost tiers stratify sharply across these use cases, with chronic conditions commanding premium pricing while acute episodic treatment faces generic substitution pressure.
- Migraine Relief:Acute and prophylactic protocols for light-sensitive headache disorders absorb the largest share of neurology R&D investment. FDA breakthrough therapy designations for novel mechanisms reshape competitive positioning in this indication.
- Chronic Pain Management:Long-term photophobia associated with neuropathic conditions requires sustained therapeutic exposure. Reimbursement complexity in United States Medicaid programs constrains access to newer agents.
- Eye Disorders:Corneal and retinal pathologies with photic sensitivity components drive ophthalmology clinic prescribing.
- Post-Surgical Care:Cataract and refractive surgery recovery protocols generate time-limited demand for light-protection therapeutics.
Migraine Relief captures the highest absolute revenue. Post-Surgical Care shows the steepest expansion trajectory as refractive surgery volumes rise.
End User:
Customer type determines margin structure, with acute-care facilities accepting premium pricing while home settings demand cost efficiency and convenience.
- Hospitals:Tertiary care centers with dedicated headache units generate the highest-margin transactions through integrated neuro-ophthalmology departments. United States academic medical centers concentrate specialized diagnostic capacity.
- Home Care Settings:Remote monitoring platforms and telehealth-enabled management extend treatment reach beyond traditional clinical boundaries. Rural patient populations previously excluded from specialized care now access photophobia protocols.
- Clinics:Ophthalmology and neurology outpatient facilities serve as the primary diagnostic and prescribing gateway.
- Rehabilitation Centers:Post-acute facilities address photophobia in traumatic brain injury and stroke recovery populations.
Hospitals dominate value capture. Home Care Settings is gaining share fastest as technology-enabled distribution models mature.
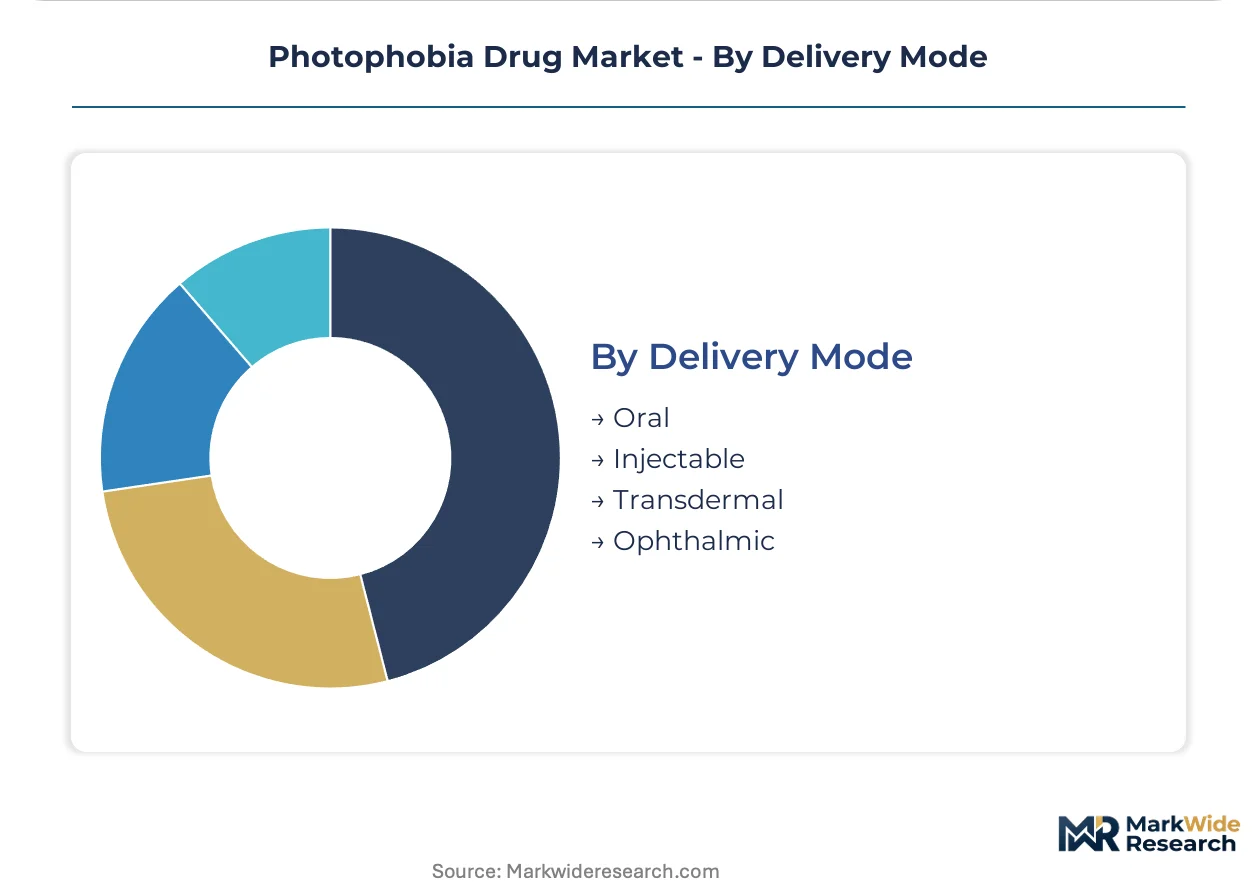
Delivery Mode:
Supply concentration varies by manufacturing complexity, with sterile ophthalmic production limiting generic competition compared to oral dosage commoditization.
- Oral:Standard tablet and capsule formulations face intense generic competition from Indian and Chinese contract manufacturers. Cost-competitive production enables broad formulary access.
- Ophthalmic:Sterile eye drop and ointment preparations require specialized manufacturing capabilities that inflate production costs. EMA pharmacovigilance requirements under Medical Device Regulation intensify post-market surveillance obligations.
- Injectable:Parenteral formulations serve acute emergency department and urgent care settings.
- Transdermal:Patch-based delivery offers sustained release for chronic photophobia management.
Oral delivery dominates prescription volume. Ophthalmic modes command the highest price per dose.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients access photophobia therapeutics predominantly through specialized headache centers and neuro-ophthalmology departments, while German and Japanese markets emphasize outpatient clinic protocols with tighter formulary controls.
United States
Specialized headache centers in Boston, New York, and Chicago drive prescription volumes through integrated neuro-ophthalmology screening protocols. FDA breakthrough therapy designations for migraine drugs accelerate photophobia indication expansions, compressing clinical trial timelines. The Mayo Clinic Rochester and Cleveland Clinic anchor diagnostic capacity, training fellowship clinicians who diffuse protocols to regional hospitals.
Germany
Outpatient neurology clinics in Munich and Berlin standardize photophobia management through statutory health insurance reimbursement frameworks. EMA centralized procedures under the German national competent authority (BfArM) streamline market access for novel therapeutics. The Rhine-Main cluster around Frankfurt concentrates pharmaceutical R&D investment in migraine-related light sensitivity pathways.
Japan
PMDA regulatory pathways prioritize real-world evidence collection for ophthalmic delivery modes, shaping post-market surveillance requirements. Tokyo and Osaka academic medical centers concentrate neuro-ophthalmology specialists trained in differential photobia diagnosis. The Kanto region's aging demographic drives demand for chronic pain management protocols incorporating light-sensitivity therapeutics.
India
Cost-competitive generic manufacturing in Gujarat and Maharashtra supplies triptan-class compounds to contract-dependent markets. CDSCO oversight governs domestic photophobia drug approvals, with state-level pharmacy councils regulating distribution. Hyderabad's active pharmaceutical ingredient cluster anchors production of NSAID formulations for export markets.
United Kingdom
NICE technology appraisals determine NHS formulary placement for photobia therapeutics, creating access barriers for newer agents. London's National Hospital for Neurology and Neurosurgery trains specialists who staff regional headache centers. The Oxford-Cambridge corridor concentrates biotech R&D targeting biomarker-guided prescribing for migraine-related light sensitivity.
Photophobia Drug Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital formulary placement through neurology infrastructure and the lower tier competing on cost in retail channels. Pfizer Inc and Novartis AG anchor the integrated segment through established distribution networks across tertiary care facilities. Sun Pharmaceutical Industries Ltd exemplifies the cost-competitive archetype, leveraging Indian manufacturing scale for generic triptan supply. Strategic moves concentrate on M&A for pipeline assets and capacity expansion in sterile ophthalmic manufacturing.
Within the integrated pharmaceutical tier, Pfizer Inc and Novartis AG occupy positions defined by neurology-focused R&D infrastructure and hospital network penetration. Sun Pharmaceutical Industries Ltd represents the specialist generic archetype, with Mumbai-based manufacturing operations supplying cost-competitive formulations to price-sensitive markets. These three companies collectively illustrate the market's structural division between premium branded therapeutics and commoditized oral dosage forms.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Pfizer Inc |
| GlaxoSmithKline plc |
| Allergan |
| Novartis AG |
| Merck & Co |
| Johnson & Johnson |
| AbbVie Inc |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Sterile manufacturing scale economies in Gujarat and Maharashtra anchor global cost floors for ophthalmic preparations, concentrating production capacity among Indian contract manufacturers while compressing margins for generic oral dosage entrants unable to match unit economics. This concentration pattern simultaneously elevates pricing power for specialized sterile formulators and erodes returns in commoditized tablet segments where Chinese API suppliers compete on volume.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital formulary procurement, with United States tertiary headache centers locking in triptan-class supply through multi-year purchasing commitments. Price differentiation separates FDA-breakthrough-designated migraine therapeutics from standard NSAID formulations, with certification tier and after-sales clinical support bundling commanding premium positioning. Cost compression in oral generic segments intensifies as Indian manufacturers expand capacity, while ophthalmic modes maintain pricing resilience due to sterile production barriers. Medicaid formulary restrictions in multiple United States states render this segment most price-sensitive, whereas integrated delivery networks with captive pharmacy operations exhibit lowest sensitivity.
Supply Chain Analysis
Inventory lead times for triptan-class active pharmaceutical ingredients stretch across 12-16 week procurement cycles, tethering finished dose manufacturers to Indian and Chinese API production schedules. Supply concentration centers on India, China, and the United States for critical inputs including sumatriptan base compounds, sterile filtration equipment, and specialized ophthalmic packaging. Single-source vulnerability pervades the API tier where Gujarat-based manufacturers supply multiple branded and generic finished dose facilities. Distribution runs through hospital pharmacy networks for prescription therapeutics, while retail chains and direct-to-patient platforms capture over-the-counter volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photophobia drug market exhibits cyclical recovery characteristics as FDA breakthrough therapy designations for migraine therapeutics compress development timelines and restock pipeline valuations. Prescription volume expansion through specialized headache centers provides the cyclical driver justifying strategic positioning.
For Market Incumbents: Fortify hospital formulary placement through expanded neuro-ophthalmology specialist training partnerships, defending against emerging telehealth-enabled competitors. Deepen backward integration into sterile ophthalmic manufacturing capacity in India to capture margin from API-to-finished-dose control. The priority lever rests on securing long-term purchasing agreements with United States academic medical centers before generic substitution intensifies. For New Entrants and Emerging Players: Lead with pediatric migraine protocols as the most penetrable application segment, exploiting underdeveloped treatment guidelines and pending American Academy of Neurology standard revisions. Target home care settings through direct-to-patient distribution models that bypass established hospital pharmacy gatekeepers. The optimal go-to-market angle combines remote monitoring platform partnerships with genetic screening service integrations for biomarker-guided prescribing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterile ophthalmic manufacturing specialists with established EMA pharmacovigilance infrastructure and Medical Device Regulation compliance capabilities. Long-term viability across the five-to-ten year window hinges on convergence between neurology and ophthalmology diagnostic protocols. The acquisition target archetype comprises mid-scale Indian manufacturers with FDA-inspected sterile facilities. The signal to watch is PMDA real-world evidence requirement expansion for combination drug-device products.| Strategic Initiative | Industry Significance |
|---|---|
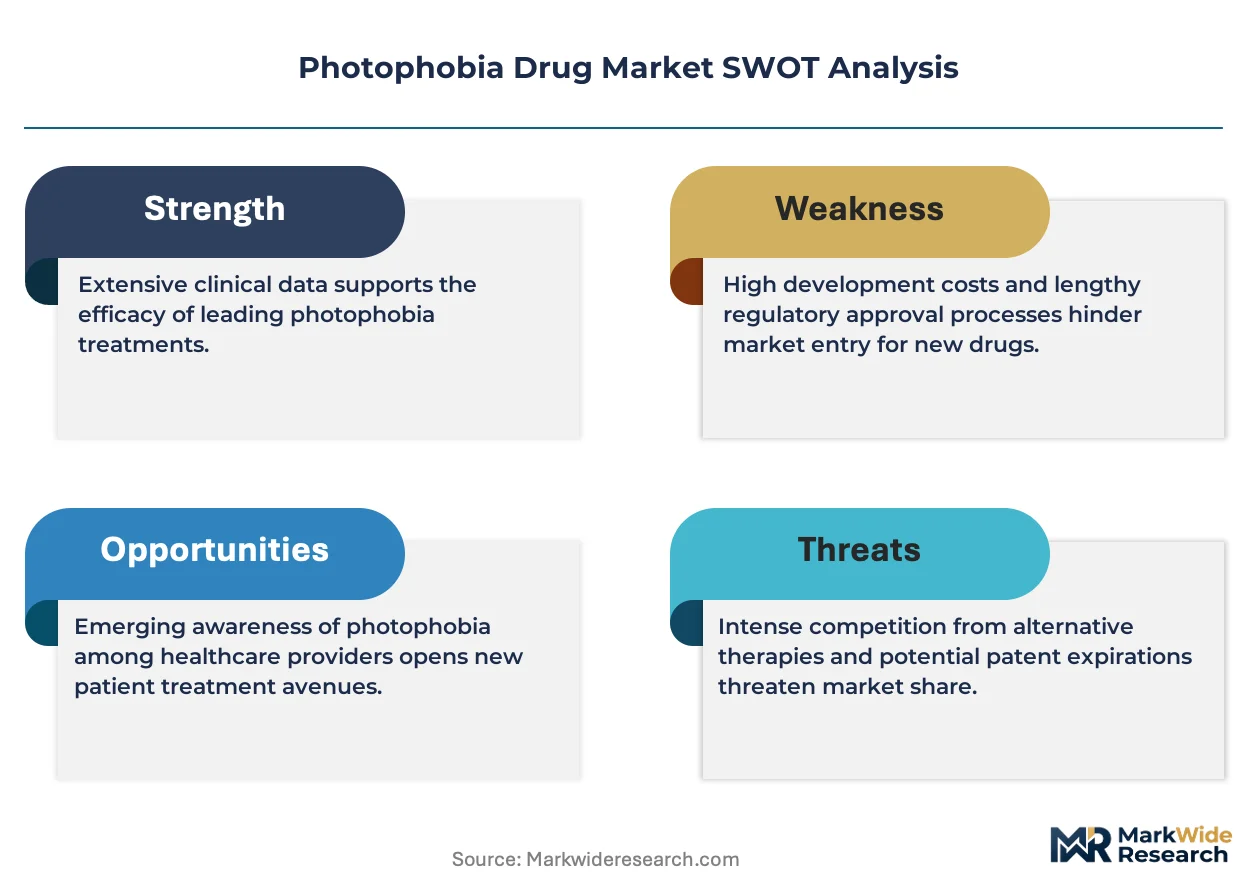
| Clinical Trial Advancement | FDA breakthrough therapy designation compresses photophobia indication timelines for migraine therapeutics. |
| Manufacturing Scale-Up | Sterile ophthalmic capacity expansion in Gujarat captures margin from API concentration. |
| Regulatory Approval Pathway | EMA centralized procedure streamlines cross-border distribution for novel light-sensitivity preparations. |
| Pipeline Diversification | Pediatric migraine protocol development addresses underpenetrated adolescent photobia treatment guidelines. |
| Licensing Agreement | Remote monitoring platform partnerships extend reach into rural patient populations. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this study. Primary interviews across these stakeholder categories combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across regulatory approval scenarios and API supply disruption assumptions. The analytical framework segmented the market by product type, application, end user, and delivery mode across the projection horizon, with dosage form and regional regulatory cluster as additional modeling dimensions. CAGRs derived from patient volume epidemiology and pricing trajectory assumptions, incorporating real-world evidence adoption curves for biomarker-guided prescribing.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough therapy designations or EMA pharmacovigilance stability would require recalibration. Forecasts reflect documented assumptions regarding migraine therapeutic approval timelines and sterile manufacturing capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Estonia Pharmaceutical Market