
 Penicillin Market | 2026-2036
Penicillin Market Size, Share, and Industry Trends Forecast 2026-2036
Penicillin Market Analysis
Injectable-grade penicillin G sodium is bifurcating the market into hospital-critical and outpatient-oral tiers. Pfizer Inc. leverages its sterile injectable infrastructure to dominate institutional procurement in North America. Aurobindo Pharma Limited anchors global API supply through backward integration into fermentation capacity at its Telangana facilities. Teva Pharmaceutical Industries Ltd. competes on cost in the oral generic segment across European tenders.
Penicillin denotes a group of beta-lactam antibiotics derived from Penicillium fungi, typically formulated as sodium or potassium salts with potency standardized in international units per milligram, and manufactured via submerged fermentation followed by solvent extraction and crystallization. The therapy area dimension shows bacterial endocarditis protocols commanding premium pricing due to narrow therapeutic alternatives, while rheumatic fever prophylaxis in developing markets sustains volume demand for benzathine penicillin. Delivery mode analysis reveals intravenous formulations capturing margin pools in ICU settings, whereas oral amoxicillin derivatives occupy commoditized retail pharmacy channels.
FDA batch release requirements and EMA good manufacturing practice inspections shape market access for non-US and non-European manufacturers seeking export approvals. India's CDSCO aligns with WHO prequalification standards to facilitate generic penicillin shipments to African procurement programs. China's NMPA enforces revised impurity profiling rules that filter substandard API entrants. Stakeholders must monitor evolving antimicrobial resistance surveillance data and corresponding formulary restrictions that determine which penicillin derivatives retain preferred status.
Market Dynamics
Antimicrobial stewardship programs are tightening hospital prescribing protocols, forcing manufacturers to differentiate between narrow-spectrum premium formulations and commoditized broad-spectrum alternatives. This regulatory pressure is reshaping production economics across fermentation-based supply chains.
Growth Catalysts
- Injectable protocol expansion:Hospital-critical care units are standardizing intravenous penicillin G sodium for bacterial endocarditis prophylaxis, creating dedicated procurement streams for sterile-grade manufacturing.
- EMA GMP alignment:European manufacturing practice inspections are filtering substandard entrants, rewarding facilities with certified sterile infrastructure and accelerating consolidation among qualified suppliers.
- Fermentation capacity clustering:India's API manufacturing belt is capturing backward integration economics through captive solvent extraction and crystallization capabilities at Telangana and Gujarat production hubs.
Market Restraints
- Raw material volatility:Corn steep liquor and lactose feedstock prices fluctuate with agricultural commodity cycles, compressing margins for fermentation-dependent producers without long-term supply contracts.
- Single-region API dependence:China's dominance in penicillin G potassium intermediate supply creates concentration risk for European and North American formulation facilities.
- Generic substitution pressure:Oral amoxicillin derivatives face unlimited therapeutic substitution in retail pharmacy channels, eroding pricing power for legacy penicillin formulations.
Strategic Opportunities
- African procurement program access:WHO prequalification pathways enable generic benzathine penicillin shipments to national malaria and rheumatic fever programs in Nigeria, Ethiopia, and Tanzania.
- Continuous manufacturing adoption:Integration of process analytical technology with traditional batch fermentation is reducing batch failure rates and shortening FDA review timelines for supplemental applications.
- CDSCO-WHO harmonization:India's alignment with international reference standards is accelerating export approvals for manufacturers serving UNICEF and Global Fund tender programs.
Industry Challenges
- Sterile manufacturing workforce scarcity:Qualified aseptic processing technicians and fermentation microbiologists command premium wages, constraining capacity expansion at mid-scale facilities.
- Legacy equipment retrofit costs:FDA's updated guidance on closed-system transfer devices requires capital-intensive isolator upgrades for existing fill-finish lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penicillin Market |
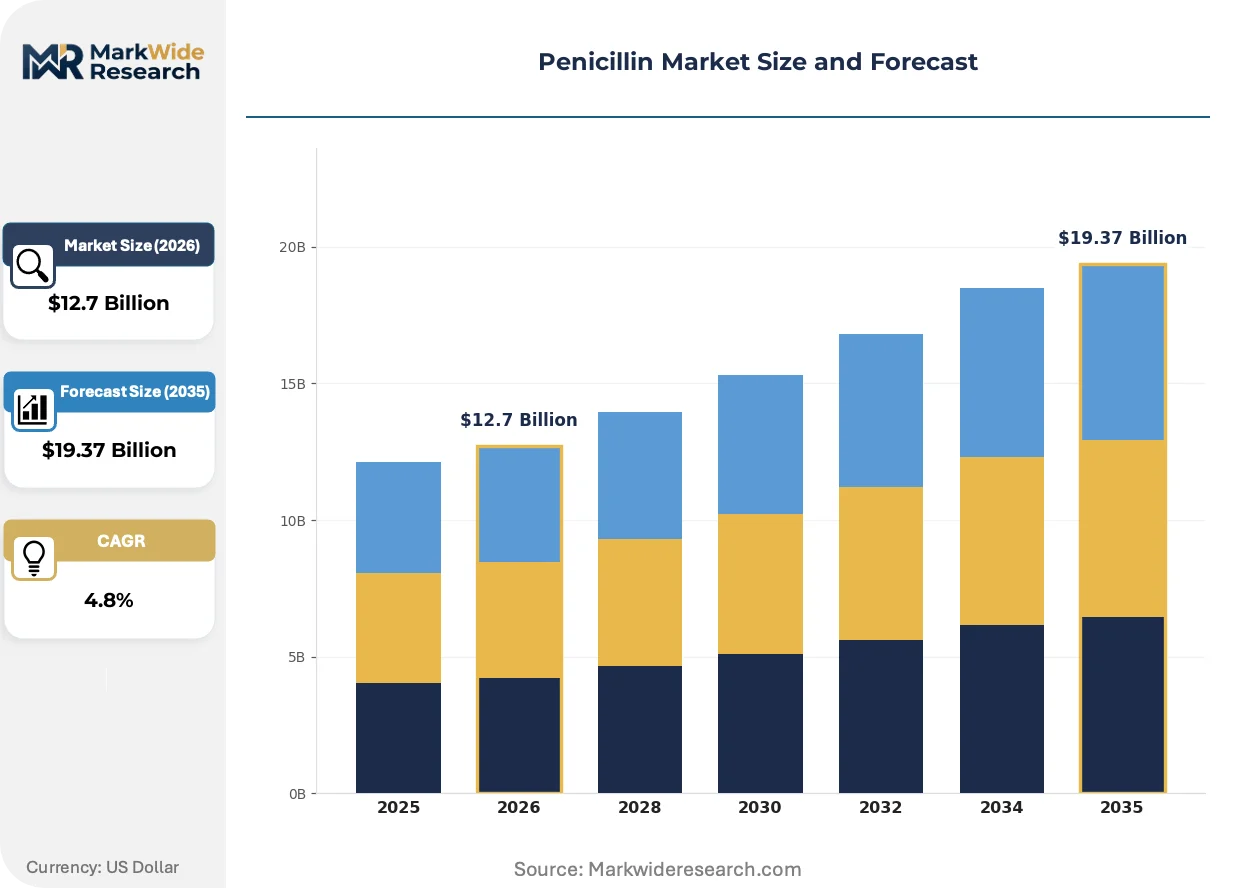
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $19.37 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzathine Penicillin, Procaine Penicillin, Potassium Penicillin, Benzyl Penicillin Therapy Area: Infections, Syphilis, Bacterial Endocarditis, Rheumatic Fever Delivery Mode: Injectable, Oral, Topical, Intravenous End User: Hospitals, Clinics, Pharmacies, Home Care |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Novartis AG, Aurobindo Pharma Limited, Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Sun Pharmaceutical Industries Ltd., Cipla Limited, Sandoz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penicillin Market Emerging Trajectories
Process intensification and regulatory harmonization are converging to redefine competitive advantage in penicillin manufacturing. Technology adoption now separates premium sterile suppliers from commodity oral producers.
Continuous bioprocessing technology is bifurcating the manufacturing landscape between high-throughput perfusion systems and traditional fed-batch fermentation. Contract development and manufacturing organizations in Switzerland and Singapore are adopting perfusion-based cell retention for enhanced penicillin G titers. This technology is bifurcating margin pools toward facilities capable of real-time quality release and away from conventional batch-reliant plants facing extended FDA inspection timelines.
REACH authorization requirements for solvent recovery systems are compelling European manufacturers to implement closed-loop extraction processes for penicillin G potassium crystallization. The ECHA's updated restriction proposals on N-methyl-2-pyrrolidone usage are forcing reformulation of downstream purification protocols. Injectable-grade producers in Italy and Germany are responding by qualifying alternative solvent systems ahead of 2027 sunset dates.
Hospital formulary committees are consolidating antibacterial purchasing through antimicrobial stewardship-driven therapeutic substitution protocols. Group purchasing organizations in the United States are replacing individual hospital contracts with regional bundled agreements covering beta-lactam classes. This concentration is most visible in academic medical centers across California, Texas, and New York, where pharmacy and therapeutics committees now mandate narrow-spectrum preference hierarchies.
Penicillin Market Segmentation
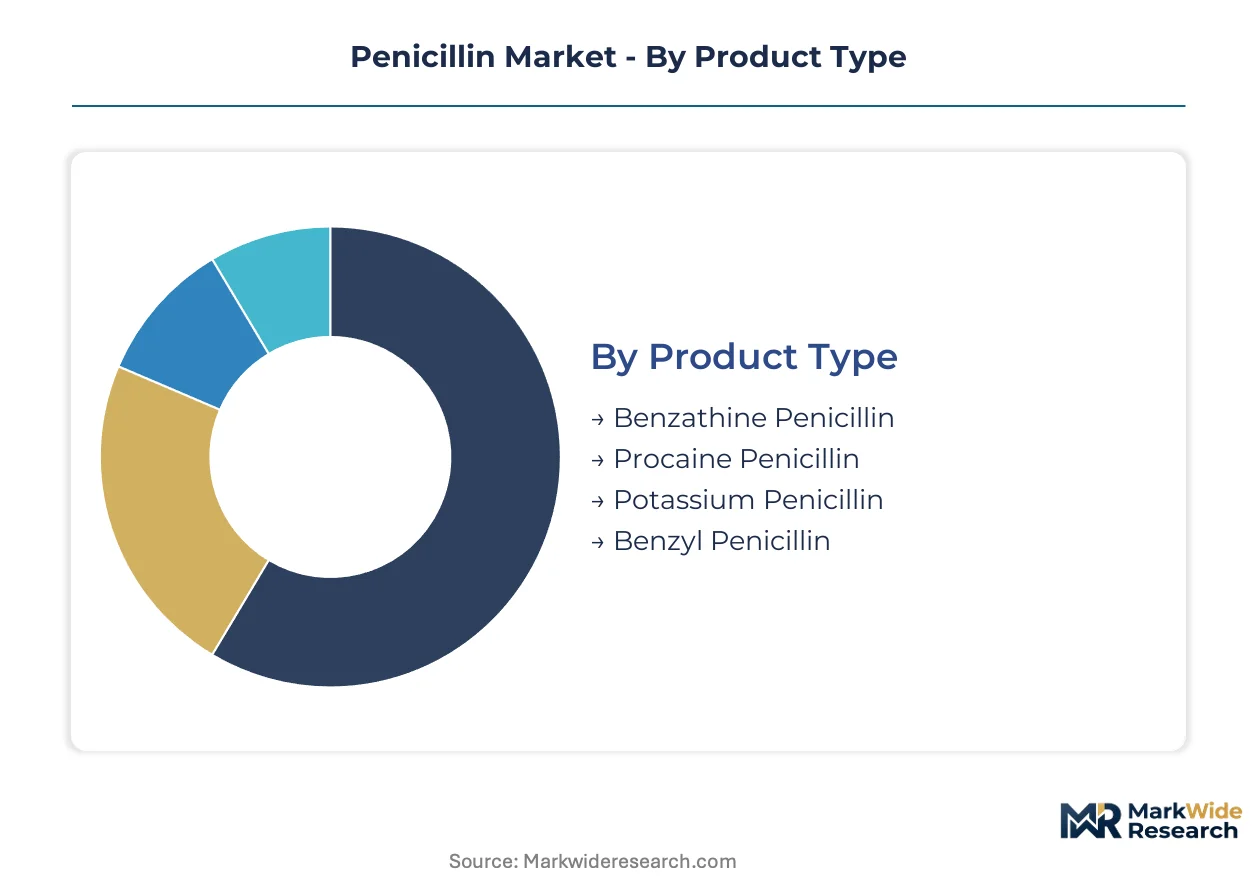
Penicillin market segmentation reveals how formulation chemistry, clinical application, and care setting interact to create distinct competitive arenas. Each dimension carries different regulatory burdens, margin profiles, and geographic demand patterns that manufacturers must navigate strategically.
Product Type:
Benzathine penicillin and procaine penicillin formulations dominate export procurement for tropical disease programs, while potassium and benzyl variants serve hospital-critical markets in North America and Europe.
- Benzathine Penicillin:Long-acting intramuscular formulation with delayed absorption kinetics enabling single-dose rheumatic fever prophylaxis. Demand concentrates in Nigeria, Ethiopia, and Tanzania through WHO-prequalified procurement channels serving national elimination programs.
- Procaine Penicillin:Repository formulation combining immediate and sustained release through procaine salt complexation. Brazilian ANVISA and Indian CDSCO registrations drive volume for secondary syphilis treatment in public health systems.
- Potassium Penicillin:Rapidly absorbed oral and injectable salt used in community-acquired pneumonia protocols.
- Benzyl Penicillin:Narrow-spectrum beta-lactam reserved for streptococcal pharyngitis and susceptible organism coverage.
Benzathine penicillin holds the largest share; momentum sits with potassium penicillin.
Therapy Area:
Application-driven segmentation separates premium-priced hospital-critical indications from high-volume public health campaigns, with reimbursement and procurement mechanisms diverging sharply across these use cases.
- Infections:Community and nosocomial bacterial infections requiring empiric beta-lactam therapy. Respiratory and soft tissue applications in European outpatient settings sustain oral amoxicillin-clavulanate demand.
- Syphilis:CDC and WHO first-line therapy designation for all disease stages preserves procurement priority despite macrolide alternatives. US sexually transmitted infection clinics and prenatal screening programs anchor institutional purchasing.
- Bacterial Endocarditis:High-stakes prophylaxis and treatment protocols commanding sterile injectable premiums. Cardiac surgery units at Cleveland Clinic, Mayo Clinic, and Texas Heart Institute standardize penicillin G sodium for susceptible organism coverage.
- Rheumatic Fever:Secondary prophylaxis programs in India, Brazil, and Egypt drive benzathine penicillin volume through national health ministry tenders.
Infections holds the largest share; bacterial endocarditis climbs fastest on stewardship-driven narrow-spectrum preference.
Delivery Mode:
Route of administration determines manufacturing complexity, with sterile parenteral forms requiring isolator infrastructure and oral solids competing on cost in commoditized channels.
- Injectable:Intramuscular and subcutaneous repository formulations for prolonged antibiotic exposure. Telangana and Gujarat manufacturing clusters supply pre-filled syringe presentations to UNICEF and Global Fund programs.
- Oral:Immediate and modified-release tablets and capsules for outpatient therapy. European pharmacy substitution rules and US 180-day exclusivity periods shape generic amoxicillin economics.
- Topical:Dermatological preparations for localized bacterial infections.
- Intravenous:Sterile penicillin G sodium for critical care and surgical prophylaxis. FDA batch release requirements and EMA Annex 1 compliance filter supplier participation in hospital GPO contracts.
Injectable holds the largest share; intravenous gains fastest on ICU protocol standardization.
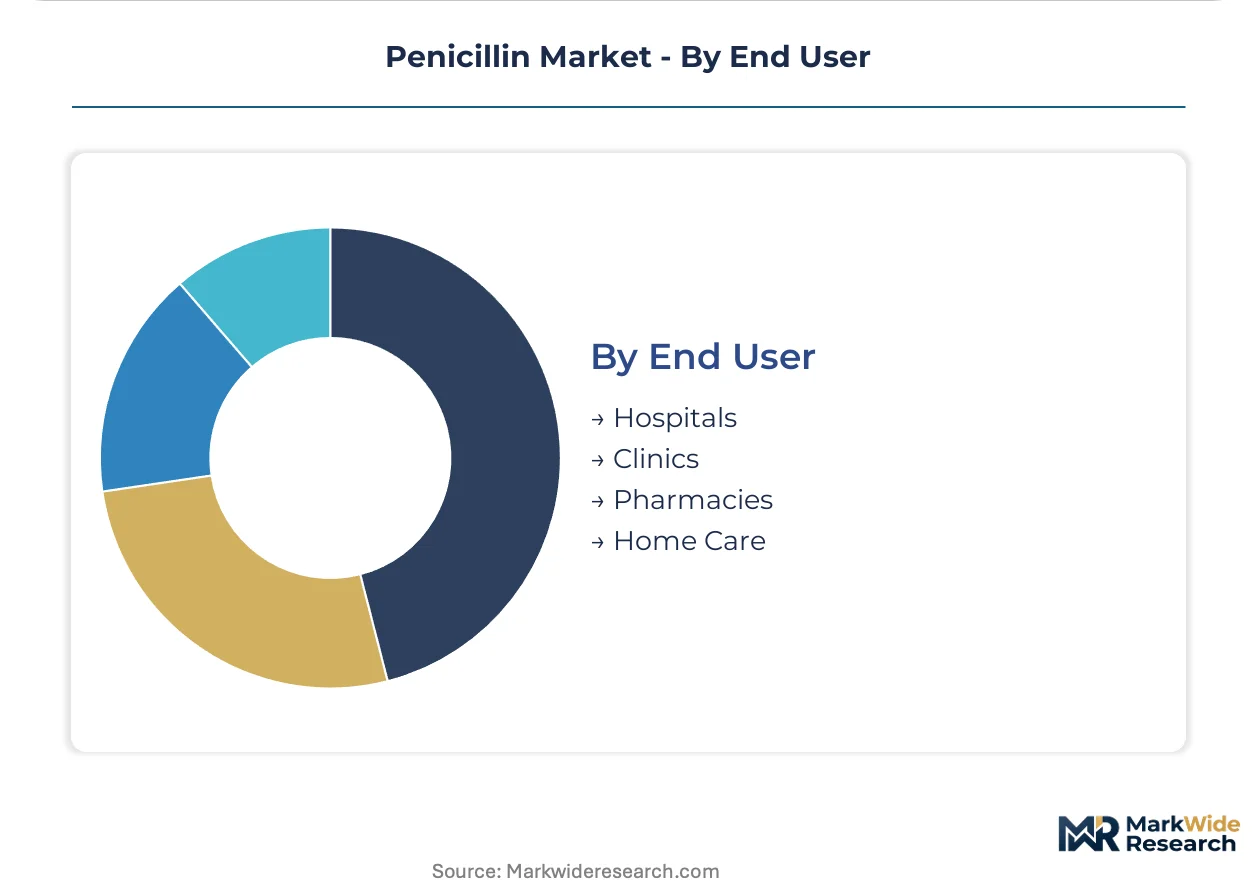
End User:
Customer type segmentation maps to reimbursement and procurement concentration, with institutional buyers consolidating volume and retail channels fragmenting across pharmacy networks.
- Hospitals:Academic medical centers and community hospitals with antimicrobial stewardship committees. California, Texas, and New York health systems bundle beta-lactam purchasing through regional GPO agreements.
- Clinics:Outpatient facilities and urgent care centers prescribing empiric therapy. Federally qualified health centers in the US and primary care networks in the UK's NHS drive oral penicillin volume.
- Pharmacies:Community and mail-order dispensaries with generic substitution autonomy. German apotheken and US chain retailers compete on amoxicillin-clavulanate pricing.
- Home Care:Infusion services and self-administration programs for long-term prophylaxis.
Hospitals hold the largest share; home care expands quickest on infusion therapy migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Penicillin trade flows reveal a pronounced export-import asymmetry, with API manufacturing concentrated in South Asian fermentation clusters while finished formulation demand concentrates in North American and European hospital systems. This geographic split shapes regulatory alignment priorities and shapes capital deployment patterns across the value chain.
United States
Hospital procurement of sterile injectable penicillin G sodium dominates demand, driven by antimicrobial stewardship protocols at Cleveland Clinic and Mayo Clinic cardiac surgery units. FDA batch release requirements and 503B compounding regulations filter supplier participation in group purchasing organization contracts. New Jersey and North Carolina formulation facilities rely heavily on imported API from Indian and Chinese sources.
India
Generic API manufacturing anchors global supply, with Telangana and Gujarat fermentation clusters producing benzathine penicillin for WHO prequalified export programs. CDSCO alignment with international reference standards accelerates shipments to African procurement channels. Sun Pharmaceutical and Aurobindo Pharma maintain captive solvent extraction capacity at Hyderabad-area facilities.
China
Penicillin G potassium intermediate production dominates upstream supply, creating concentration risk for European and North American formulation facilities. NMPA enforcement of revised impurity profiling rules filters substandard API entrants. Shandong and Hebei province fermentation plants supply bulk intermediates under tightened environmental compliance protocols.
Germany
EMA GMP inspections and REACH authorization requirements for solvent recovery systems shape manufacturing economics for sterile-grade producers. Bavaria and Baden-Württemberg facilities qualify alternative purification solvents ahead of N-methyl-2-pyrrolidone sunset dates. German academic medical centers bundle beta-lactam purchasing through regional hospital alliances.
Brazil
ANVISA registrations drive volume for procaine penicillin in public health systems treating secondary syphilis. São Paulo and Rio de Janeiro state health ministries anchor national tender programs for repository formulations. Brazilian demand for benzathine penicillin in rheumatic fever prophylaxis supports import flows from Indian API manufacturers.
Penicillin Market Vendor Landscape
Concentration sits with sterile injectable specialists and backward-integrated API manufacturers, creating a tiered structure where fermentation capacity and regulatory certification separate premium from commodity positioning. The competitive arena fragments across three strategic archetypes: multinational pharmaceutical corporations with sterile infrastructure, Indian generic API producers with captive fermentation, and European contract manufacturers with EMA-certified isolator lines. Capacity expansion and regulatory harmonization represent the dominant competitive moves, with players investing in continuous manufacturing adoption and WHO prequalification pathways.
Within the multinational tier, Pfizer Inc. and GlaxoSmithKline plc occupy positions defined by institutional procurement relationships and sterile manufacturing heritage. Among Indian generic specialists, Aurobindo Pharma Limited and Sun Pharmaceutical Industries Ltd. exemplify backward-integrated fermentation economics. Teva Pharmaceutical Industries Ltd. sits within the scale-driven oral generic segment competing on European tender participation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Aurobindo Pharma Limited |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Limited |
| Sandoz |
| Others |
Supply Flow & Price Mechanics
Corn steep liquor substitution for synthetic nitrogen sources in fermentation media is simultaneously shifting procurement geography toward Midwest US agricultural belts and compressing API pricing economics for manufacturers without long-term feedstock contracts. This input pivot rewards Indian facilities with captive corn processing partnerships while eroding margins for European producers dependent on imported lactose derivatives.
Pricing Analysis
Hospital procurement managers anchor three-tier pricing structure across premium, standard, and economy levels in the penicillin market. Price differentiation centers on FDA batch release certification and EMA Annex 1 compliance grade, with sterile injectable G sodium commanding substantial premiums over oral amoxicillin derivatives. Cost compression in the oral generic tier is intensifying because unlimited therapeutic substitution rules in European pharmacy channels erode brand pricing power. Retail pharmacy buyers exhibit highest price sensitivity, while cardiac surgery units at Cleveland Clinic and Mayo Clinic demonstrate lowest sensitivity due to protocol-locked formulary requirements.
Supply Chain Analysis
Inventory buffers at Telangana fermentation hubs currently extend lead times for benzathine penicillin shipments to African procurement programs. Geographic supply concentration centers on India, China, and Germany for distinct value chain stages. Raw material flows draw from corn steep liquor processors in the US Midwest, lactose refiners in New Zealand, and solvent suppliers in Rotterdam. Single-source vulnerability in penicillin G potassium intermediate production creates concentration risk for North American formulation facilities. Distribution runs through WHO-prequalified channels for tropical disease programs and regional hospital GPO contracts for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The penicillin market is entering a cyclical recovery phase as antimicrobial stewardship programs restore narrow-spectrum antibiotic preference hierarchies after years of broad-spectrum dominance. Agricultural commodity cycles in fermentation feedstock markets reinforce this cyclical pattern.
For Market Incumbents: Shield sterile manufacturing margins through isolator line upgrades ahead of FDA's updated closed-system transfer device guidance. Backward integration into Telangana fermentation capacity provides defensive moats against API price volatility. EMA GMP certification investments filter substandard competitors from European hospital procurement channels. For New Entrants and Emerging Players: CDSCO-WHO harmonization fast-track pathways enable generic benzathine penicillin access to Nigerian and Ethiopian national elimination programs. Rheumatic fever prophylaxis tenders in Brazil and Egypt represent the most penetrable volume segment. Target UNICEF and Global Fund procurement channels with pre-filled syringe presentations as the primary go-to-market angle. For Investors and Strategic Acquirers: REACH authorization deadlines for N-methyl-2-pyrrolidone replacement reshape the acquisition landscape toward European facilities with qualified alternative solvent systems. Five-to-ten year viability favors backward-integrated API manufacturers with captive fermentation and crystallization infrastructure. Acquisition target archetype: mid-scale Indian generic producers with CDSCO export approvals and Telangana manufacturing presence. Monitor ECHA restriction proposal implementation timelines as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Process analytical technology integration at Swiss CDMOs reduces FDA supplemental application review timelines. |
| Backward Integration into Fermentation | Hyderabad-area captive solvent extraction capacity insulates Aurobindo and Sun Pharma from API price volatility. |
| WHO Prequalification Pathway | CDSCO-aligned manufacturers accelerate shipments to Global Fund and UNICEF tender programs in Nigeria and Tanzania. |
| Isolator Infrastructure Upgrade | EMA-certified facilities in Bavaria qualify alternative purification solvents ahead of N-methyl-2-pyrrolidone sunset dates. |
| Regional GPO Contract Consolidation | California and Texas health system bundling concentrates beta-lactam purchasing power among qualified sterile suppliers. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with fermentation microbiologists, hospital pharmacy directors, antimicrobial stewardship committee chairs, and API procurement managers; and secondary validation through FDA 483 inspection observations, EMA GMP certificates, WHO prequalification listings, and Indian CDSCO export approval records. Bottom-up volume modeling triangulated against top-down pharmaceutical trade flow data.
Across the analysis window, forecasts segment by product type (benzathine, procaine, potassium, benzyl salts), therapy area (infections, syphilis, bacterial endocarditis, rheumatic fever), delivery mode (injectable, oral, topical, intravenous), and end user (hospitals, clinics, pharmacies, home care). CAGRs derive from regression analysis of historical formulation shipment data and antimicrobial resistance surveillance trends. Forecast inputs incorporate EMA inspection frequency patterns and agricultural commodity price indices for corn steep liquor and lactose feedstocks.
Decision-makers should treat outputs as directional under assumptions of sustained antimicrobial stewardship program enforcement and stable WHO procurement funding; material deviation would warrant model refresh. Revision becomes warranted when REACH authorization implementation timelines or FDA isolator guidance enforcement intensity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Blood Coagulants Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market