
 Europe Smart Meter Data Management Market | 2026-2036
Europe Smart Meter Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Meter Data Management Market Analytics
Platform licensing revenue is reshaping competitive economics in Europe's smart meter data management sector. Landis+Gyr leverages its deep utility relationships across Central Europe to sustain recurring software income. Siemens AG anchors large-scale deployment capability through integrated AMI consulting and hardware bundles.
Europe smart meter data management encompasses software platforms, communication infrastructure, and analytics tools that aggregate, validate, and process interval consumption data from advanced metering infrastructure, typically handling 15-minute to hourly read frequencies across millions of endpoints. These systems enable automated billing, grid balancing, and demand response orchestration for electric, gas, and water utilities. The application dimension shows data analytics and demand response solutions outpacing legacy billing modules as utilities prioritize grid optimization over revenue collection. Cellular and PLC technology segments dominate connectivity architecture, though Zigbee retains share in dense urban deployments where mesh networking reduces infrastructure cost.
The EU Green Deal, F-Gas Regulation, and national implementations of the Clean Energy Package collectively mandate granular consumption visibility and interoperability standards that force utilities toward certified data management platforms. EMA guidelines on energy data privacy and GDPR compliance add compliance layers that favor established vendors with proven security architectures. Stakeholders must monitor how the EU AI Act applies to automated demand response algorithms and predictive load forecasting models as regulatory scrutiny intensifies.
Market Dynamics
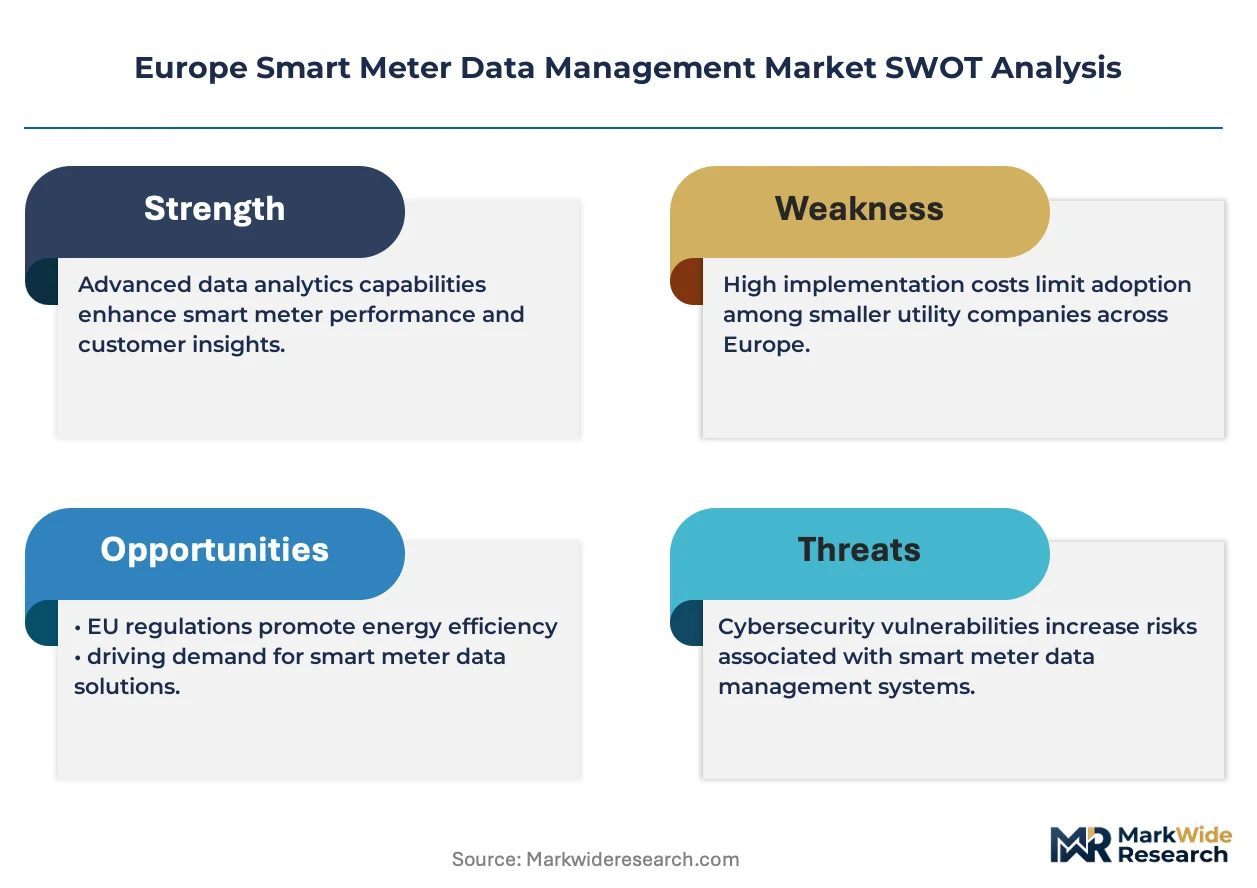
Platform licensing economics are compressing vendor margins while the EU AI Act and GDPR compliance layers force utilities toward certified data management architectures with proven security frameworks.
Growth Catalysts
- Clean Energy Package mandates:National implementations across EU member states require granular consumption visibility and interoperability standards that drive certified platform procurement.
- Grid balancing applications:Distribution system operators deploy demand response orchestration tools to manage distributed energy resource integration and voltage stability.
- France and Germany:These markets anchor rollout momentum with binding smart meter installation targets and utility-scale AMI deployment programs.
Market Restraints
- Cellular module supply concentration:Dependence on narrow semiconductor foundry capacity for LTE-M and NB-IoT chipsets creates procurement bottlenecks.
- F-Gas Regulation friction:Stringent reporting requirements for SF6-insulated switchgear delay substation automation timelines and data infrastructure deployment.
- Legacy billing system substitution:Mature on-premise revenue management platforms resist displacement despite cloud-native platform advantages.
Strategic Opportunities
- Poland and Romania:These member states present underpenetrated addressable markets with nascent smart meter rollout programs and limited incumbent platform saturation.
- AI-driven load forecasting:Machine learning convergence with interval data streams enables predictive grid operations and automated demand response optimization.
- CSRD disclosure requirements:Corporate sustainability reporting mandates create enterprise demand for granular energy consumption data and carbon accounting integration.
Industry Challenges
- Cybersecurity certification timelines:Common Criteria and IEC 62443 evaluation processes extend product qualification cycles by twelve to eighteen months.
- AMI-MDMS integration complexity:Head-end system fragmentation across multiple communication protocols complicates unified data aggregation architecture deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Meter Data Management Market |
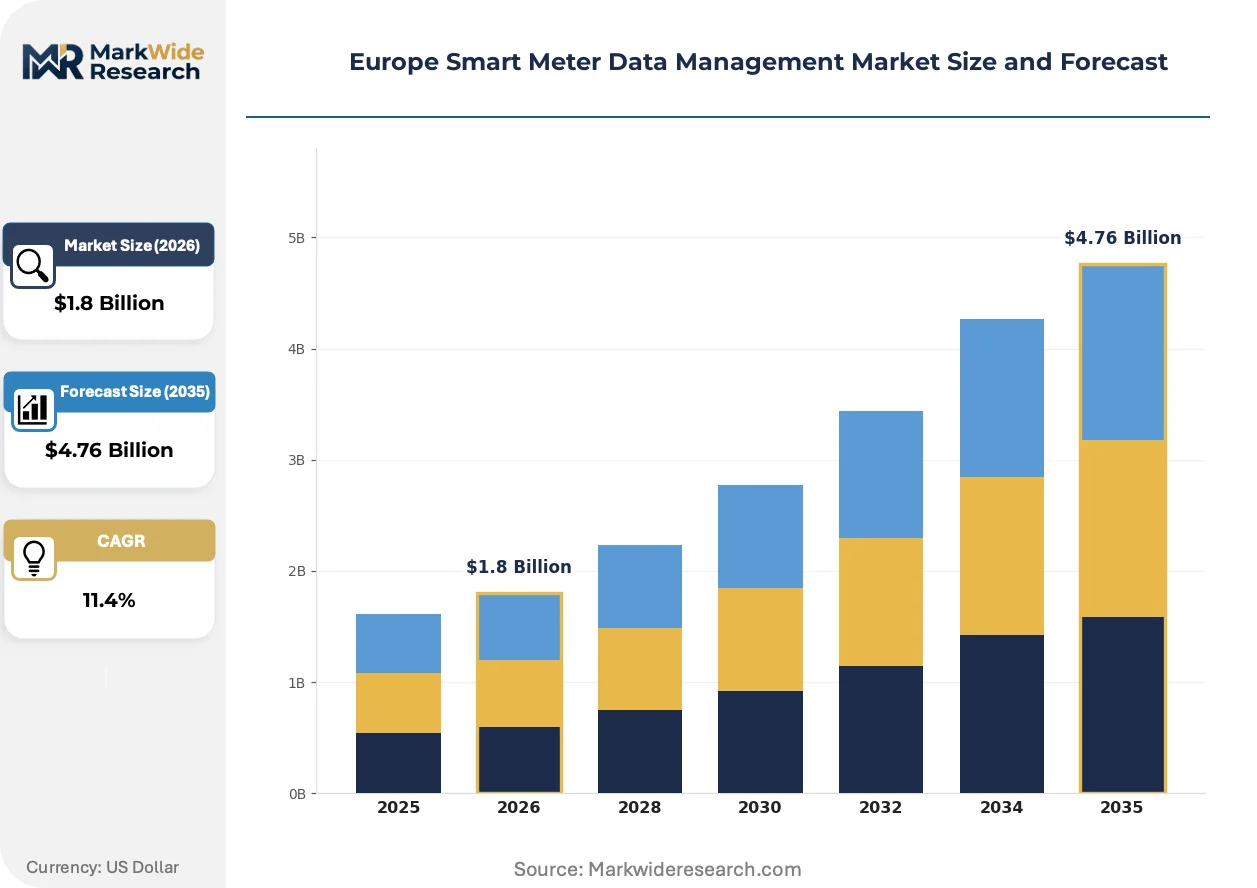
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless, Zigbee, Cellular, PLC End User: Utilities, Manufacturers, Retailers, Service Providers Application: Billing, Monitoring, Data Analytics, Demand Response Service Type: Installation, Maintenance, Consulting, Support |
| Companies Covered | Landis+Gyr, Itron, Oracle Corporation, Siemens AG, ABB Group, Schneider Electric, Honeywell International, Kamstrup, Eaton Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Meter Data Management Market Evolving Landscape
Edge computing architectures and real-time analytics engines are compressing decision latency in grid operations. Vendors race to embed intelligence closer to metering endpoints.
Cloud-native meter data management platforms are digitizing utility operational technology stacks. Nordic distribution system operators migrate fastest, replacing decade-old on-premise installations with software-as-a-service architectures. This shift is digitizing procurement models and collapsing traditional five-year enterprise sales cycles.
The EU AI Act risk classification framework imposes algorithmic transparency requirements on automated demand response systems. Energy retailers deploying predictive load forecasting must document training data provenance and model drift monitoring protocols. German utilities face the steepest compliance burden given their concentration of AI-enabled grid balancing applications.
Aggregated energy service company models are capturing commercial and industrial customer relationships that utilities historically owned. Third-party platform providers now intermediate between meter data repositories and end-user analytics, unbundling the utility's monopoly on consumption insights. This channel restructuring is most advanced in the Netherlands and Denmark where market liberalization enabled competitive metering service unbundling.
Europe Smart Meter Data Management Market Segmentation
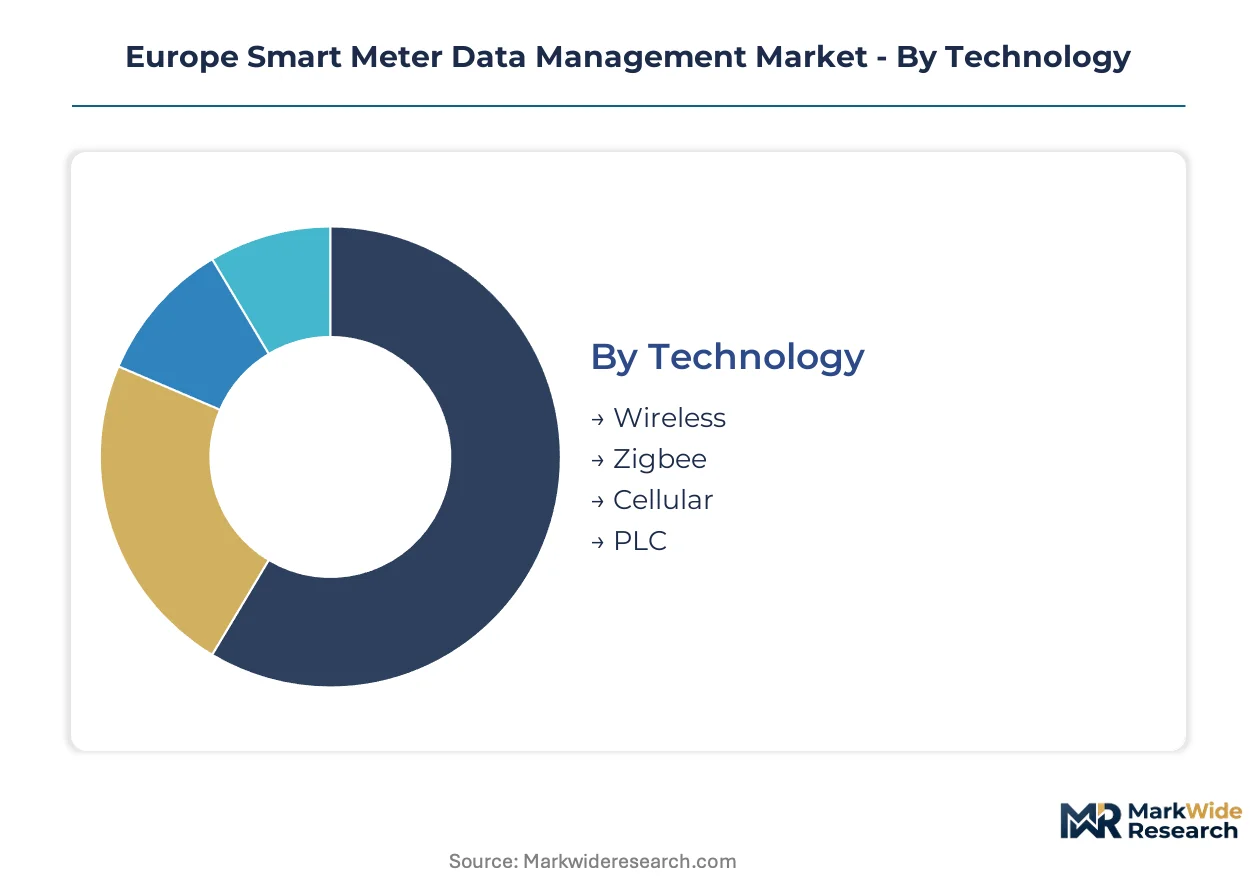
Smart meter data management platforms must align with distinct connectivity architectures, operational workflows, and compliance requirements across European utilities. Segmentation reveals where procurement budgets concentrate and which technology choices determine platform scalability.
Technology:
Use-case spectrum spans dense urban mesh networks through rural cellular deployments, with each architecture imposing different data aggregation latency and infrastructure cost profiles.
- Cellular:LTE-M and NB-IoT modules provide wide-area coverage with minimal gateway infrastructure. German distribution system operators favor this architecture for rural AMI rollouts where PLC signal attenuation limits reliability.
- PLC:Power line communication leverages existing grid infrastructure for data transmission. French utilities deploy PLC-Broadband across urban density zones where meter concentration justifies dedicated network investment.
- Wireless:Proprietary RF mesh protocols enable neighborhood-area network formation without cellular subscription overhead. Nordic operators pilot these in islanded microgrid configurations.
- Zigbee:IEEE 802.15.4-based mesh networking reduces per-endpoint connectivity cost in high-rise residential clusters. Dutch metering service providers deploy Zigbee where building density exceeds 150 units per hectare.
The dominant share belongs to Cellular, while PLC is closing the gap fastest.
End User:
Customer type determines platform procurement authority and integration complexity, from regulated grid operators through competitive retail intermediaries.
- Utilities:Vertically integrated distribution system operators hold primary procurement authority for AMI-MDMS platforms. E.ON and Enel manage multi-million endpoint deployments with fifteen-minute read frequencies.
- Service Providers:Competitive metering service companies unbundle data management from utility ownership. Netherlands-based operators capture commercial customer analytics relationships previously held by incumbents.
- Retailers:Energy retailers purchase interval data access for dynamic tariff product development. British suppliers leverage consumption patterns to design time-of-use offerings under Ofgem market rules.
- Manufacturers:Industrial facility operators deploy private meter data systems for carbon accounting compliance. German automotive suppliers integrate CSRD-mandated energy disclosure into enterprise resource planning platforms.
Utilities command the largest procurement volumes, though Service Providers are expanding most quickly.
Application:
Functional priority determines platform module investment, with grid optimization applications displacing legacy revenue management.
- Data Analytics:Machine learning pipelines process interval consumption for predictive load forecasting. Danish system operators apply these models to manage offshore wind intermittency.
- Demand Response:Automated orchestration platforms curtail distributed energy resources during network constraints. Italian utilities deploy these under ARERA regulatory frameworks for capacity market participation.
- Monitoring:Real-time voltage and power quality telemetry enables distribution automation. Spanish distributors prioritize this functionality for rural network visibility.
- Billing:Automated meter-to-cash workflows remain necessary but receive reduced platform investment. Polish utilities maintain these modules while deferring advanced analytics upgrades.
Data Analytics holds the leading position, with Demand Response climbing fastest.
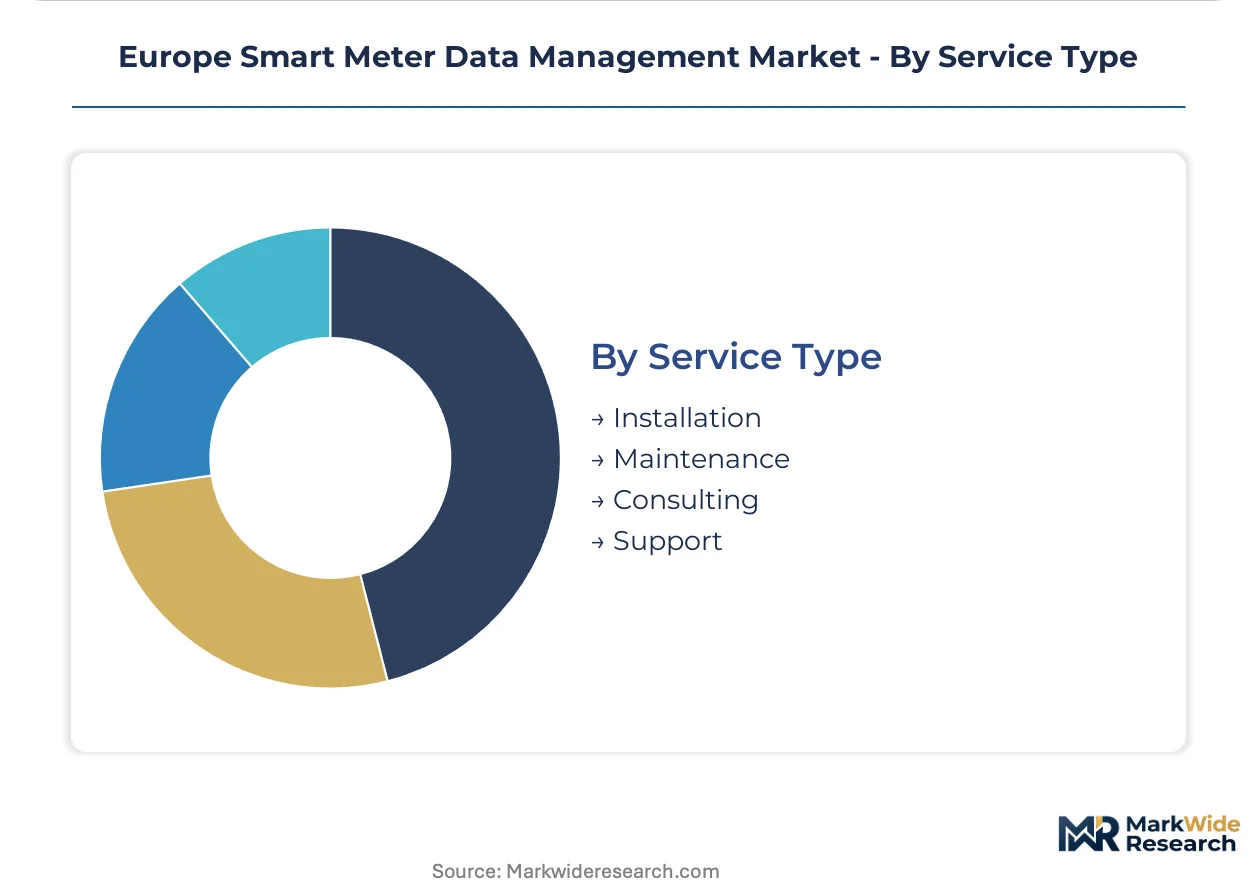
Service Type:
Margin structure varies across deployment lifecycle phases, from capital-intensive installation through recurring support revenue.
- Consulting:System integration and AMI architecture design services capture value during procurement decision windows. Siemens and Capgemini compete for framework contracts with French distribution network operators.
- Installation:Field deployment of communication modules and meter replacement programs. Romanian rollout programs drive demand for certified technician networks.
- Maintenance:Firmware updates, communication diagnostics, and endpoint replacement under service level agreements. Nordic operators outsource these functions to specialized metering service companies.
- Support:Help desk operations and data quality assurance for utility operational staff. Cloud-native platform vendors bundle these services into subscription pricing.
Consulting generates the highest margin concentration, while Support is scaling fastest through SaaS bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform vendors concentrate engineering resources where AMI deployment velocity outpaces regulatory compliance timelines. Germany, France, and the Nordic states absorb disproportionate solution development capacity due to binding rollout mandates and utility procurement scale.
Germany
Distribution system operators in Bavaria and North Rhine-Westphalia deploy cellular-connected AMI at fifteen-minute intervals under the Messstellenbetriebsgesetz framework. The Federal Network Agency enforces interoperability standards through BSI certification requirements. E.ON and EnBW anchor procurement volumes in Stuttgart and Mannheim, where grid balancing applications prioritize real-time data analytics.
France
Linky smart meter saturation exceeds 35 million endpoints, creating sustained demand for MDMS platform upgrades and cybersecurity hardening. The Commission de régulation de l'énergie mandates data portability under the Clean Energy Package national implementation. Grid operators in Île-de-France and Auvergne-Rhône-Alpes concentrate predictive load forecasting investments to manage nuclear fleet intermittency.
Netherlands
Liberalized metering service markets enable competitive unbundling of data management from utility ownership. The Autoriteit Consument en Markt oversees time-of-use tariff frameworks that require granular consumption visibility. Rotterdam and Amsterdam host third-party platform providers intermediating between meter repositories and commercial customer analytics.
Poland
Nascent smart meter programs in Masovian and Silesian Voivodeships present underpenetrated procurement opportunities with limited incumbent platform saturation. The Energy Regulatory Office implements EU Green Deal targets through binding 2025-2030 installation schedules. Warsaw-based utilities pilot AMI architectures while legacy billing systems resist full displacement.
Sweden
Nordic distribution system operators migrate fastest to cloud-native MDMS platforms, replacing decade-old on-premise installations. The Swedish Energy Markets Inspectorate enforces GDPR-compliant data handling through sector-specific guidelines. Stockholm and Gothenburg utilities embed edge computing architectures to compress grid operation decision latency.
Europe Smart Meter Data Management Market Competitive Landscape
Integrated AMI consultancies and specialized metering platform developers split the market along deployment scale and service bundling vectors. Siemens AG anchors large-scale deployment capability through hardware-software integration, while Landis+Gyr leverages deep utility relationships to sustain recurring software income. Competitive moves concentrate on cloud-native platform migration and cybersecurity certification acceleration.
Among European-headquartered conglomerates, Siemens AG and ABB Group exemplify the integrated infrastructure archetype, bundling AMI consulting with hardware deployment. Landis+Gyr and Kamstrup occupy positions within the specialized metering tier, where deep utility relationships and proven security architectures favor platform licensing economics. These named entities represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron |
| Oracle Corporation |
| Siemens AG |
| ABB Group |
| Schneider Electric |
| Honeywell International |
| Kamstrup |
| Eaton Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in cellular module foundries across Southeast Asia is compressing component pricing while simultaneously eroding supplier willingness to extend payment terms to European AMI vendors. This utilization dynamic forces platform developers toward longer-term service contracts to lock in recurring revenue streams and offset hardware margin deterioration.
Pricing Analysis
After-sales support and firmware maintenance contracts now generate the dominant lifetime value in meter data management economics. Subscription-based SaaS pricing stratifies across enterprise, mid-market, and entry-tier deployment scales, with certification under BSI and Common Criteria standards commanding substantial premiums over uncertified alternatives. Cost compression in hardware provisioning is intensifying because semiconductor foundry overcapacity has collapsed module spot pricing. Municipal utilities in Eastern Europe exhibit the highest price sensitivity due to constrained capital budgets, while Nordic distribution system operators prioritize security architecture over cost minimization.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit European vendor access to leading-edge LTE-M and NB-IoT chip fabrication capacity. Supply concentration centers on Taiwan, South Korea, and mainland China for cellular communication modules, with Germany and France hosting final assembly and software integration stages. The ecosystem draws from silicon wafers, RF front-end components, and cryptographic security elements as critical inputs. Single-source vulnerability in narrowband chipset supply creates structural exposure to geopolitical disruption. Distribution runs through authorized systems integrators and direct utility procurement frameworks rather than open channel markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is restructuring competitive advantage around interoperability certification and ecosystem orchestration rather than standalone product performance. The EU Green Deal's mandate for granular consumption visibility and cross-border data portability is forcing vendors toward collaborative standard-setting.
For Market Incumbents: Insulate recurring revenue streams by deepening vertical integration into edge computing hardware and accelerating Common Criteria certification timelines ahead of EU AI Act enforcement. Cloud-native platform substitution from specialized SaaS entrants threatens incumbent consulting-heavy business models. Priority investment in firmware-over-the-air update infrastructure locks in long-term maintenance contracts and raises switching costs for utility customers. For New Entrants and Emerging Players: Pursue white-space penetration in Polish and Romanian distribution system operators where incumbent platform saturation remains limited and national rollout mandates create procurement urgency. Nascent smart meter programs in these markets present the most penetrable geography for unbundled data analytics offerings. A channel partnership strategy with established metering service companies accelerates credibility and bypasses lengthy utility direct sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software layers while edge hardware deployment demands rising physical infrastructure investment. Long-term viability in this sector hinges on recurring platform revenue rather than project-based consulting, favoring acquisition targets with established SaaS subscription bases. The signal to watch is utility procurement shift from perpetual licensing to consumption-based metering, which would accelerate margin compression for legacy vendors and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Acceleration | Common Criteria and IEC 62443 compliance under EU AI Act timelines differentiates vendor eligibility for German and French utility tenders. |
| Cloud-Native Platform Migration | SaaS architectures collapse Nordic utility procurement cycles from five-year enterprise sales to annual recurring subscriptions. |
| Edge Computing Hardware Integration | Embedded intelligence at metering endpoints compresses grid operation decision latency for Swedish distribution system operators. |
| Interoperability Standard Alignment | Clean Energy Package mandates for cross-border data portability favor vendors with proven multi-protocol AMI-MDMS integration. |
| AI-Driven Load Forecasting Development | Machine learning convergence with interval data streams enables predictive grid operations under ARERA and Ofgem regulatory frameworks. |
Research Methodology
Operator-level perspectives from utility planning officers, AMI program directors, metering service company executives, and grid operations engineers anchored the qualitative base for this analysis. Primary field engagement combined structured interviews with distribution system operators across Germany, France, the Netherlands, Poland, and Sweden with secondary validation against regulatory filings from the Federal Network Agency, Commission de régulation de l'énergie, and Swedish Energy Markets Inspectorate. Bottom-up endpoint deployment tracking and top-down platform revenue estimation were triangulated against EU Green Deal implementation schedules and national Clean Energy Package transposition timelines.
Scenario-bracketing around cellular module supply constraints, F-Gas Regulation compliance timelines, and EU AI Act enforcement intensity bounded the forecast range across the analysis window. Segmentation modeling incorporated connectivity architecture, end-user procurement authority, application functional priority, and service type margin structure as core dimensions. CAGRs were derived from utility capital expenditure trajectories, smart meter installation mandates, and platform licensing revenue migration patterns. Forecast inputs included BSI certification pipeline velocity, Nordic cloud migration adoption curves, and Polish-Romanian rollout acceleration signals.
Sensitivities concentrate around semiconductor foundry capacity allocation shifts, EU AI Act risk classification finalization for automated demand response, and cybersecurity certification backlog duration. Forecasts reflect documented assumptions regarding regulatory enforcement timing and utility procurement cycle normalization. Material shifts in export-control regimes affecting cellular chipset supply, or accelerated EU Green Deal target revision, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Solar Meter Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Power Monitoring System Market
Smart Meters
Europe Smart Meters Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
US Water Meter Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Power Quality Meter Market
Smart Meters
Europe Water Meter Market