
 Residential Water Submetering Market | 2026-2036
Residential Water Submetering Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Water Submetering Market Insights
EPA WaterSense certification requirements for multi-family properties is consolidating procurement standards across the United States. Neptune Technology Group leverages its vertical manufacturing footprint to dominate municipal utility contracts. Badger Meter sustains R&D intensity in ultrasonic flow measurement for residential pipe sizes. Kamstrup competes through integrated radio-frequency modules that eliminate separate communication infrastructure.
Residential water submetering encompasses the installation of individual consumption measurement devices downstream from a master utility meter, typically employing volumetric positive displacement, ultrasonic time-of-flight, or electromagnetic sensing principles with flow ranges from 0.25 to 20 gallons per minute and accuracy classes meeting AWWA C700-C715 standards. Its primary purpose enables equitable cost allocation among tenants, leak detection, and conservation behavior modification through direct usage feedback. Smart meters with embedded IoT connectivity represent the fastest-expanding technology segment as utilities prioritize remote read capabilities and real-time anomaly detection, while mechanical meters retain cost advantages in legacy retrofit installations where electrical power availability constrains device selection. Wireless technology deployments are displacing wired AMR systems in new construction segments where builders pre-integrate communication backbones.
FCC Part 15 regulations govern radio-frequency emissions from wireless meter transmitters, while EPA WaterSense specifications establish performance benchmarks for flow accuracy and leak detection sensitivity that shape product development roadmaps. State-level public utility commissions in California, Texas, and Florida enforce submetering billing transparency rules that determine market access requirements for service providers. Stakeholders must monitor evolving cybersecurity frameworks for IoT-enabled water infrastructure as NIST guidelines extend to critical utility networks.
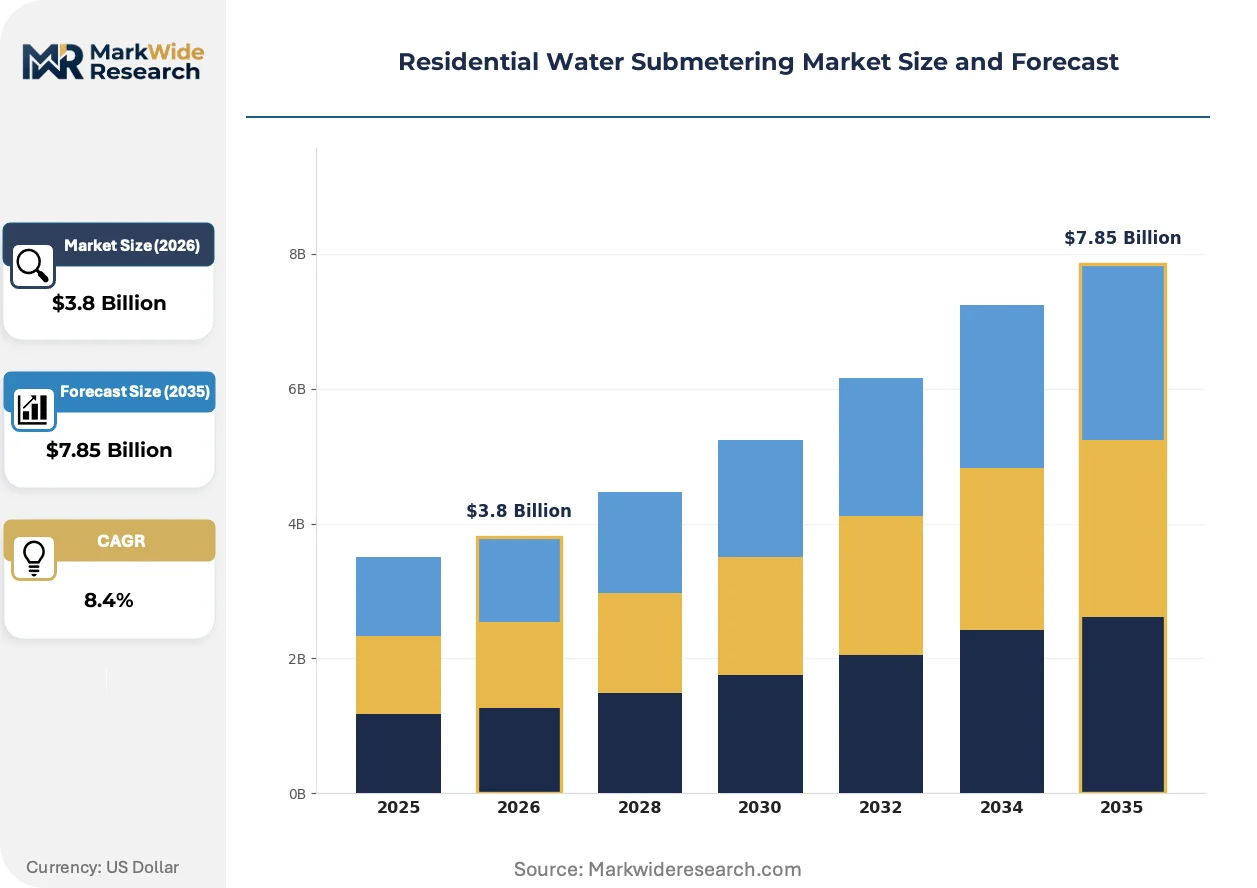
Market Dynamics
The transition from mechanical to connected metering infrastructure is compressing installation timelines while elevating cybersecurity compliance burdens for utilities and property managers.
Growth Catalysts
- LoRaWAN protocol adoption:Municipal utilities in California, Texas, and Florida mandate wireless connectivity for new multi-tenant constructions, eliminating manual read costs.
- AWWA C715 ultrasonic standards:Updated accuracy requirements for low-flow detection drive replacement cycles in aging mechanical meter bases.
- Drought-response building codes:Unit-level consumption tracking provisions in state-level conservation statutes create procurement pull-through in residential construction.
Market Restraints
- Semiconductor supply concentration:RF module fabrication depends on concentrated Asian foundry capacity, creating lead time volatility for smart meter OEMs.
- Copper and brass input costs:Mechanical meter housings remain exposed to base metal price swings that compress margin on legacy product lines.
- FCC Part 15 certification timelines:Radio-frequency equipment authorization processes extend product launch windows by 8-14 months.
Strategic Opportunities
- Retrofit installation services:Aging housing stock in the Northeast and Midwest presents untapped addressable base for AMR-to-AMI upgrades.
- Leak detection analytics:Machine learning integration with flow signature databases enables subscription revenue models for property management platforms.
- EPA WaterSense certification expansion:Proposed multi-family performance specifications would create preferential procurement status for certified devices.
Industry Challenges
- RF engineering talent scarcity:Embedded systems expertise for sub-GHz mesh networks commands premium compensation in utility technology sectors.
- Legacy AMR integration complexity:Drive-by read systems require protocol bridging hardware that extends deployment timelines and elevates commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Water Submetering Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Meters, Ultrasonic Meters, Smart Meters, Digital Meters Technology: Wired Technology, Wireless Technology, IoT Technology, Analog Technology Installation: Retrofit Installation, New Construction, In-building Installation, Standalone Installation End User: Property Managers, Homeowners, Utilities, Residential Complexes |
| Companies Covered | Sensus, Neptune Technology Group, SageWater, RealPage, Submeter Solutions, Submtr, Kamstrup, Metron Farnier, Badger Meter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Water Submetering Market Trends and Innovations
Connected infrastructure investment is redirecting R&D expenditure toward edge computing capabilities and interoperable data standards that transcend proprietary utility architectures.
Ultrasonic time-of-flight sensing is modularizing around standardized transducer assemblies and replaceable battery packs that extend field service intervals beyond 15 years. Multi-family developers in sunbelt states specify these units for new construction, compressing mechanical meter procurement into legacy retrofit niches. The technology is modularizing installation workflows through plug-and-play communication modules that swap between cellular, mesh, and fixed-network protocols without meter replacement.
EPA WaterSense specifications for multi-family leak detection sensitivity are tightening flow-rate thresholds that reshape product development roadmaps. Manufacturers must demonstrate sub-gallon-per-hour detection capability to maintain certification eligibility. California and Texas public utility commissions reference these benchmarks in submetering billing rulemakings, forcing service providers to upgrade device fleets or exit regulated markets.
Property managers increasingly bundle water consumption data with energy management dashboards, consolidating vendor relationships around integrated building automation platforms. Traditional meter-to-cash service providers face disintermediation as software platforms absorb billing functions. This consolidation is most visible in Class A multifamily assets across Florida and Arizona, where institutional ownership demands unified utility expense recovery systems.
Residential Water Submetering Market Segmentation
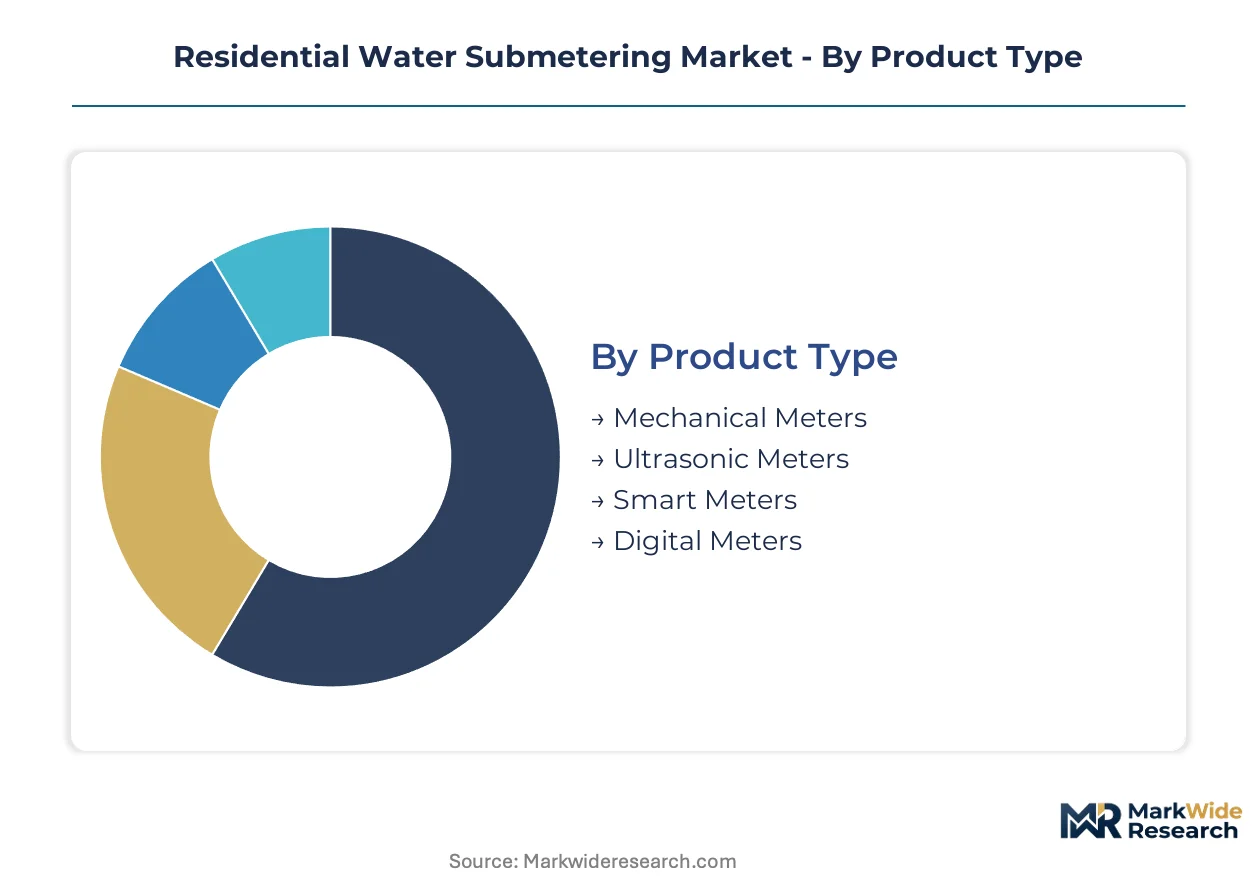
Residential water submetering procurement varies sharply by building vintage, connectivity requirements, and billing complexity. Segmentation reveals where mechanical legacy systems persist versus where smart infrastructure commands premium positioning.
Product Type:
Standardization dominates at the low end with commodity mechanical units, while ultrasonic and smart variants offer customization through protocol selection and analytics integration.
- Mechanical Meters:Positive displacement mechanisms with brass or polymer bodies dominate retrofit budgets where electrical access is limited. Demand concentrates in Midwest and Northeast legacy housing stock where utilities prioritize lowest first-cost procurement over connectivity.
- Ultrasonic Meters:Time-of-flight sensing eliminates moving parts and achieves AWWA C715 accuracy classes for low-flow leak detection. California and Texas multi-family developers specify these for new construction as drought codes tighten unit-level accountability requirements.
- Smart Meters:Embedded LoRaWAN or cellular modules enable remote reads and anomaly alerts.
- Digital Meters:LCD-display units bridge mechanical reliability with electronic registration.
Most installed capacity flows through Mechanical Meters. Expansion is steepest in Smart Meters.
Technology:
Cost tiers separate legacy analog systems from wireless and IoT platforms that carry higher hardware costs but eliminate manual read labor.
- Wired Technology:AMR systems with fixed network cabling persist in campus-style residential complexes where conduit installation is feasible during major renovations. Northeast property managers favor these for reliability against RF interference in dense urban construction.
- Wireless Technology:Sub-GHz mesh and star-topology networks displace drive-by reads as Florida and Arizona utilities mandate remote accessibility. FCC Part 15 certification requirements extend procurement cycles but reduce ongoing operational expenditure.
- IoT Technology:Cloud-connected meters with edge analytics support real-time leak detection and consumption benchmarking.
- Analog Technology:Mechanical dials with no electronic components serve off-grid or extreme-budget installations.
Wireless Technology carries the largest current deployment volume. IoT Technology is gaining share fastest among new multi-family developments.
Installation:
Application context distinguishes greenfield pre-integration from retrofit complexity where existing plumbing constraints dictate approach.
- Retrofit Installation:Copper pipe cutting and meter setter replacement in occupied units demands coordination with tenant schedules. Texas and California service providers specialize in rapid-turnover methodologies that minimize water shutoff duration.
- New Construction:Pre-installed meter boxes with integrated communication backbones allow plug-and-drop deployment. Sunbelt state builders specify these configurations to meet submetering mandates before certificate of occupancy issuance.
- In-building Installation:Central utility rooms or riser closets accommodate multiple meters with shared communication gateways.
- Standalone Installation:Single-point meters for detached accessory dwelling units or garden apartments.
New Construction captures the majority of smart meter volume. Retrofit Installation presents the steepest expansion trajectory as aging housing stock faces efficiency upgrade requirements.
End User:
Customer type determines procurement sophistication, from institutional property managers with unified platforms to individual homeowners prioritizing device cost.
- Property Managers:Institutional multifamily operators across Florida and Arizona demand integrated billing platforms that consolidate water with energy and HVAC data. These buyers negotiate enterprise pricing for AMI deployments across entire portfolios.
- Utilities:Municipal water departments in California and Texas drive standardization through master meter downstream submetering mandates that reduce apparent water losses.
- Homeowners:Individual unit owners in condominium associations or single-family rentals select basic mechanical or digital units.
- Residential Complexes:Homeowner associations and cooperative boards manage collective procurement for common-area and unit-level metering.
Property Managers represent the largest addressable base by contract value. Utilities are expanding most quickly as regulatory mandates proliferate across drought-affected states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential water submetering originated in the United States during the 1970s energy crisis, when California and Texas first mandated unit-level metering in multi-family housing to drive conservation. The technology spread to Canada and Australia through drought-response building codes, then to European markets facing water scarcity and regulatory pressure for consumption transparency.
United States
California, Texas, and Florida dominate procurement volume through drought-driven conservation statutes. The EPA WaterSense program establishes multi-family performance benchmarks that shape product certification requirements. Dallas-Fort Worth and Houston metro areas concentrate retrofit installation activity as municipal utilities expand submetering mandates to reduce apparent water losses.
Canada
Ontario and British Columbia lead deployment through provincial building codes requiring individual unit metering in new multi-family construction. Natural Resources Canada efficiency standards influence meter specification for federally funded housing projects. Toronto and Vancouver metropolitan areas drive smart meter adoption as utilities prioritize remote read capabilities across aging housing stock.
Australia
New South Wales and Victoria enforce submetering provisions through state-level water efficiency labeling schemes. The country's national water regulator mandates consumption transparency in strata-titled apartment buildings. Sydney and Melbourne property managers increasingly specify LoRaWAN-connected meters to integrate water data with building automation platforms.
Germany
Baden-Württemberg and Bavaria concentrate precision manufacturing of ultrasonic flow sensors for export markets. The country's national metrology institute enforces MID certification requirements that exceed AWWA accuracy standards. Stuttgart and Munich industrial clusters supply transducer assemblies to North American meter OEMs seeking European component sourcing.
United Kingdom
England's water retail market opening created demand for submetering in multi-tenant commercial-residential mixed-use developments. Ofwat regulatory frameworks mandate consumption data accessibility for tenant billing transparency. London and Southeast England property developers specify smart meters to meet building regulation conservation targets.
Residential Water Submetering Market Competitive Landscape
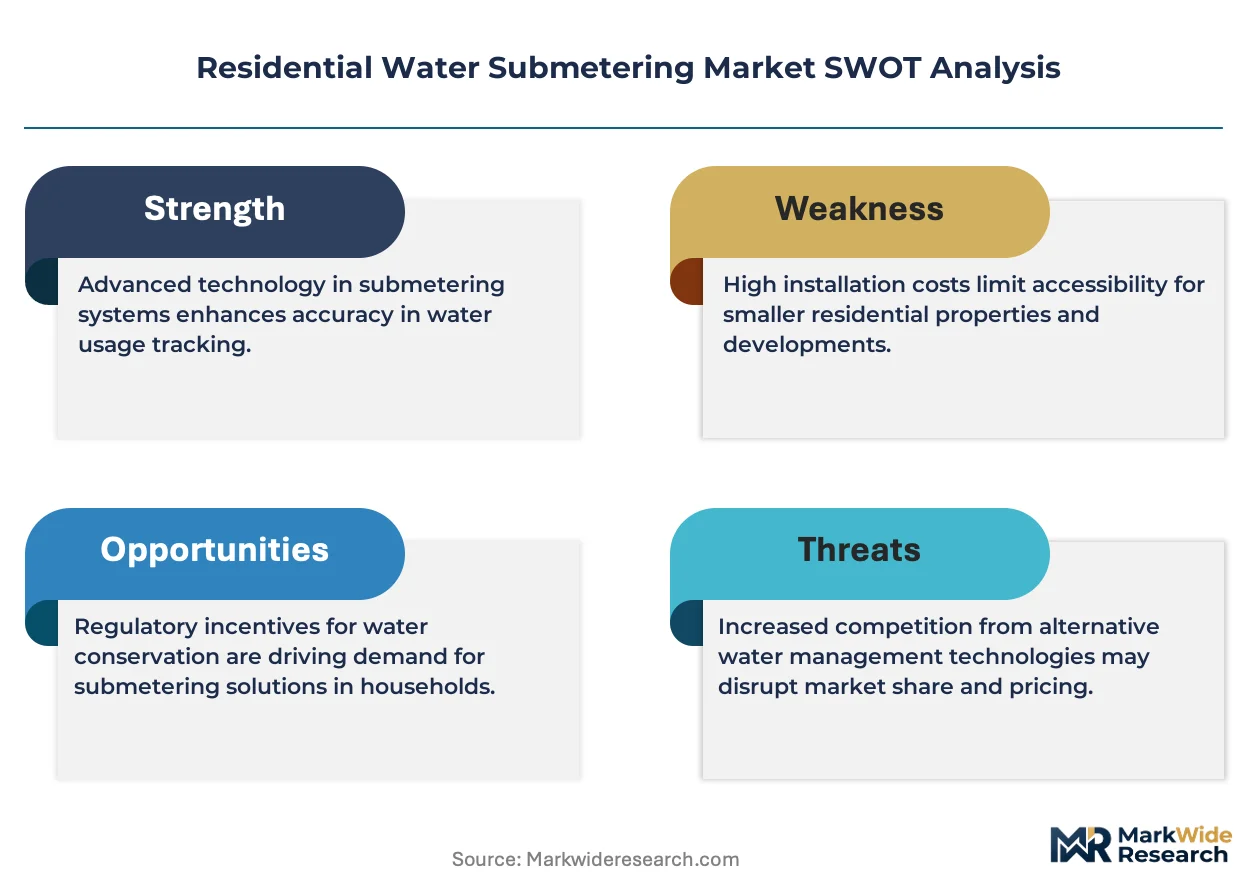
Premium-margin players sit above commodity-margin players across technology sophistication and certification breadth, with ultrasonic and smart meter specialists commanding pricing power against mechanical legacy suppliers. The vendor base organizes into three tiers: integrated utility-scale providers, regional installation service specialists, and component-focused technology licensors. Consolidation pressure intensifies as software platforms absorb billing functions and property managers demand unified utility management systems. Dominant competitive moves include vertical integration into RF module manufacturing and strategic partnerships with building automation platform providers.
Among North American utility-scale providers, Neptune Technology Group and Badger Meter exemplify the integrated manufacturing archetype, while Kamstrup represents European precision engineering positioning in ultrasonic sensing technology. These three companies anchor distinct competitive vectors: Neptune dominates municipal contract procurement through vertical manufacturing control, Badger sustains R&D intensity in flow measurement accuracy, and Kamstrup competes through embedded radio-frequency integration that eliminates separate communication infrastructure deployment.
| Leading Market Players |
|---|
| Sensus |
| Neptune Technology Group |
| SageWater |
| RealPage |
| Submeter Solutions |
| Submtr |
| Kamstrup |
| Metron Farnier |
| Badger Meter |
| Others |
Pricing and Supply Chain Analysis
LoRaWAN module standardization is compressing smart meter hardware costs while concentrating RF semiconductor sourcing among Taiwanese and South Korean foundries. This technology transition simultaneously elevates procurement leverage for volume buyers and exposes smaller OEMs to allocation risk during capacity crunches.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA WaterSense-certified ultrasonic units from basic mechanical meters and entry-level digital displays. Price differentiation rests on certification grade and after-sales service bundling, with property management platforms commanding enterprise discounts unavailable to individual homeowners. Cost compression in mechanical tiers is intensifying because brass and copper input volatility erodes margin on legacy product lines. Homeowners in condominium associations exhibit highest price sensitivity, while institutional multifamily operators in Florida and Arizona prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from California and Texas municipal utilities mandate qualified secondary suppliers for RF modules and ultrasonic transducer assemblies, forcing OEMs to maintain relationships with both Taiwanese and German component vendors. Manufacturing draws from China for mechanical meter housings, Mexico for final assembly serving North American demand, and Germany for precision flow sensors. Copper, brass, and lithium battery cell dependencies create commodity price exposure. Single-source vulnerability concentrates in sub-GHz radio chip fabrication. Distribution runs through utility-scale distributors, regional installation service providers, and direct OEM contracts to property management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as drought-driven conservation mandates in California, Texas, and Florida create durable procurement pull-through across housing vintages.
For Market Incumbents: Anticipate disintermediation from building automation platforms by deepening software integration partnerships and securing exclusive data-sharing agreements with institutional property managers. Backward integration into captive RF module production mitigates semiconductor allocation risk from concentrated Asian foundries. Prioritize EPA WaterSense certification maintenance as state-level billing rulemakings tighten device eligibility thresholds. For New Entrants and Emerging Players: Regional installation service specialists in the Northeast and Midwest present underserved buyer archetypes with aging AMR infrastructure requiring AMI upgrades. White-space targets include leak detection analytics subscriptions for mid-market multifamily assets and rapid-turnover retrofit methodologies minimizing tenant disruption. A go-to-market angle bundling hardware with cloud-based billing software bypasses traditional meter-to-cash service provider relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among component-focused technology licensors lacking integrated installation capabilities or platform software. Long-term viability favors assets with EPA WaterSense certification breadth and established utility procurement relationships. The signal to watch is consolidation of billing functions into property management software platforms, which would accelerate margin compression for pure-play meter-to-cash providers.| Strategic Initiative | Industry Significance |
|---|---|
| EPA WaterSense Certification Expansion | Secures preferential procurement status in California and Texas municipal mandates. |
| LoRaWAN Protocol Integration | Eliminates separate communication infrastructure deployment for Florida utilities. |
| Leak Detection Analytics Platform | Enables subscription revenue models targeting Arizona institutional property managers. |
| Retrofit Installation Service Scaling | Captures aging housing stock upgrade cycles across Northeast and Midwest markets. |
| Building Automation Partnership | Prevents disintermediation by consolidating water data with energy and HVAC dashboards. |
Research Methodology
Bottom-up property manager and utility procurement modeling reconciled against top-down meter OEM production tracking forms the analytical core of this study. Primary interviews with municipal utility planning officers, multifamily property management executives, submetering installation contractors, and RF module procurement leads combined with secondary validation from EPA WaterSense certification databases, FCC Part 15 equipment authorization filings, state public utility commission rulemakings, and AWWA technical standards documentation. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices map unit shipments by product type, technology tier, installation context, and end-user category across the projection horizon. Segmentation dimensions modeled include meter mechanism, connectivity protocol, building vintage, and regional regulatory cluster. CAGRs derive from regression analysis of historical procurement patterns against conservation mandate implementation timelines. Industry-specific forecast inputs incorporate drought severity indices and multi-family housing construction permit data.
Underlying measurement precision varies by segment; smart meter and ultrasonic categories carry tighter precision than mechanical legacy estimates due to more transparent OEM reporting. Forecasts reflect assumptions about continued LoRaWAN protocol adoption and sustained municipal mandate expansion. Deviation in semiconductor supply availability or federal preemption of state-level submetering regulations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
United States Smart Meter Market
Smart Meters
North America Gas Meter Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Digital Gas Meter Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
US Smart Meter Data Management Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
US Water Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Smart Meters Market
Smart Meters
South and Central America Smart Metering Market