
 Asia Pacific Smart Meter Market | 2026-2036
Asia Pacific Smart Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Smart Meter Market Outlook
Pay-as-you-go leasing for advanced metering infrastructure is fragmenting competitive access across Asia Pacific, allowing mid-sized utilities to deploy AMI without capital-intensive balance sheet commitments. Wasion Group leverages its manufacturing scale to dominate domestic Chinese deployments while extending module exports across Southeast Asia. EDMI Limited anchors its position through specialized RF Mesh competency in Australian and New Zealand utility tenders. Honeywell International competes by integrating cloud-based analytics platforms with its hardware installations.
Asia Pacific smart meters comprise electronic measurement devices with embedded communication modules, typically operating at 50-60 Hz with accuracy classes of 0.2S to 2.0S, designed to capture consumption data at 15-minute intervals or shorter for automated billing and grid optimization. Electric Meters occupy the largest value share given utility-scale renewable integration mandates across the region, while AMI deployments are displacing legacy AMR systems as two-way communication becomes standard for demand response programs. Water Meters represent the fastest-growing product category where non-revenue water reduction targets in cities from Bangalore to Manila drive sensorization of distribution networks.
China's GB standards and MIIT certification requirements shape product design specifications for any manufacturer seeking market access, while India's CEA technical standards for smart grid interoperability create compliance barriers that favor pre-qualified vendors. METI's subsidy frameworks in Japan accelerate residential AMI replacement cycles beyond normal depreciation schedules. Stakeholders must monitor how evolving cybersecurity mandates across these regulatory regimes reshape firmware architecture requirements and supplier qualification timelines.
Market Dynamics
AMI infrastructure leasing is fragmenting competitive access across Asia Pacific, allowing mid-sized utilities to deploy advanced metering without capital-intensive balance sheet commitments. This financial innovation is compressing vendor concentration while accelerating replacement cycles beyond traditional depreciation schedules.
Growth Catalysts
- India's PLI scheme for AMI:Production-linked incentives for advanced metering infrastructure are lowering procurement costs for state distribution companies and accelerating domestic manufacturing scale.
- China's dual carbon goals:National carbon neutrality targets are mandating grid digitization to integrate utility-scale renewable generation and enable real-time demand response.
- Non-revenue water reduction mandates:Cities from Bangalore to Manila are sensorizing distribution networks, creating pull for smart water meters with embedded pressure and flow analytics.
Market Restraints
- Semiconductor supply concentration:Communication module chipsets concentrate in Taiwan and South Korea foundries, exposing AMI deployments to geopolitical supply disruption risks.
- GB standards compliance costs:China's MIIT certification requirements impose firmware architecture redesigns that extend supplier qualification timelines by 8-14 months.
- RF spectrum allocation friction:Unlicensed sub-GHz band congestion in dense urban deployments limits mesh network scalability in Japanese and Australian metropolitan zones.
Strategic Opportunities
- Vietnam's rural electrification gap:Provincial power utilities outside Hanoi and Ho Chi Minh City remain underpenetrated by AMI, creating first-mover advantage for prepaid metering solutions.
- Cybersecurity mandate convergence:Evolving firmware security requirements across China's GB standards, India's CEA interoperability rules, and Japan's METI frameworks favor vendors with certified secure element integration.
- Edge analytics module attachment:On-device machine learning for anomaly detection is hybridizing with traditional metrology, opening premium pricing tiers for predictive maintenance capabilities.
Industry Challenges
- Interoperability certification backlog:India's CEA technical standards for smart grid interoperability create pre-qualification bottlenecks that delay vendor onboarding by 12-18 months.
- Legacy AMR system stranding:Utilities with substantial drive-by meter reading infrastructure face stranded asset risk during AMI transition, complicating capital allocation decisions.
- RF engineering talent scarcity:Specialized mesh network design expertise concentrates in Australia and Japan, limiting deployment quality in Southeast Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Smart Meter Market |
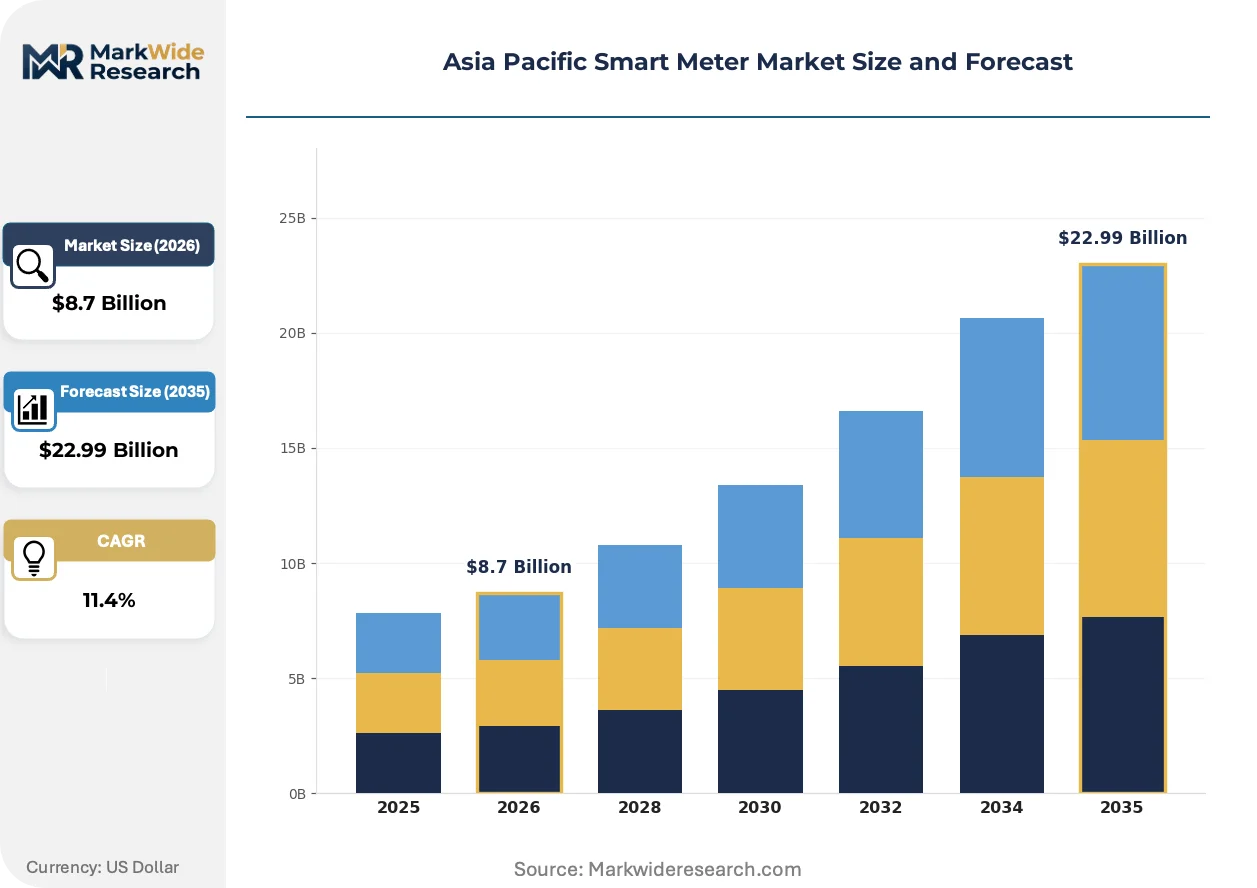
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meters, Water Meters, Gas Meters, Heat Meters Deployment: On-Premises, Cloud-Based, Hybrid, Standalone End User: Utilities, Residential, Commercial, Industrial Technology: AMR, AMI, PLC, RF Mesh |
| Companies Covered | Landis+Gyr, Honeywell International, EDMI Limited, Schneider Electric, Wasion Group, Holley Technology Ltd, Badger Meter, Suntront Tech Co., Ltd, Itron, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Smart Meter Market Strategic Shifts
Communication architecture decisions are becoming the primary competitive differentiator as utilities prioritize cyber-resilient, low-latency data pathways over hardware cost minimization. Vendors are repositioning around integrated platform offerings rather than standalone meter supply.
Dual-band RF-PLC communication modules are hybridizing across Asia Pacific deployments, combining radio frequency mesh redundancy with powerline carrier reliability for underground and dense urban environments. Australian utilities are adopting these hybrid architectures fastest to address topographical coverage gaps. The technology is compressing single-technology vendor margins while rewarding integrated platform providers.
Japan's METI subsidy frameworks are accelerating residential AMI replacement cycles beyond normal depreciation schedules, creating artificial demand compression through 2027. The policy is forcing utilities to front-load capital expenditure while suppliers scramble to secure component allocation. Residential segment procurement is responding with consolidated vendor panels to ensure delivery certainty.
Pay-as-you-go leasing structures are displacing traditional capital purchase models for mid-sized utilities in Indonesia and the Philippines. Equipment financiers are capturing margin previously retained by meter manufacturers, fragmenting value chain control. This shift is most visible in municipal water utilities where non-revenue water targets create urgent procurement pressure without matching budget authority.
Asia Pacific Smart Meter Market Segmentation
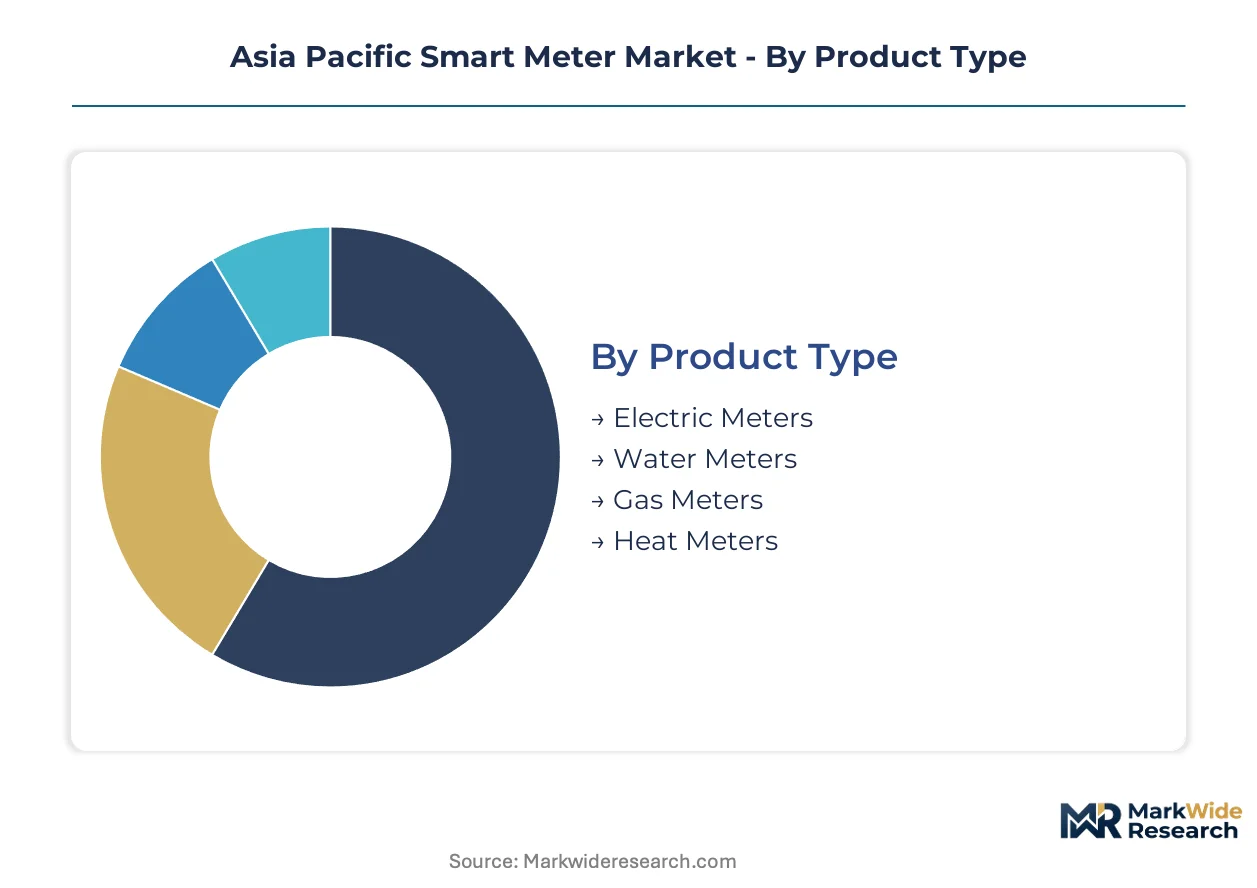
Segmentation in the Asia Pacific smart meter market reveals how procurement priorities diverge across utility infrastructure maturity and regulatory pressure points. Product type and technology choices cascade into deployment architecture decisions that reshape vendor competitive dynamics.
Product Type:
Mature electric metering programs in China and Japan contrast with emerging water sensorization across Southeast Asian cities, creating divergent growth trajectories across product categories.
- Electric Meters:These units integrate bidirectional communication modules for real-time grid balancing and renewable integration. Demand concentrates in China's state grid expansion and India's rural electrification programs where distribution digitization mandates are accelerating replacement cycles. Electric meters retain volume leadership; water meters hold the steepest expansion curve.
- Water Meters:Embedded pressure and flow analytics enable non-revenue water reduction in distribution networks. Cities from Bangalore to Manila are driving sensorization as municipal utilities face leakage reduction targets without matching capital budgets.
- Gas Meters:Ultrasonic and diaphragm smart variants with tamper-detection firmware serve urban utility consolidation in Japan and South Korea.
- Heat Meters:District heating network digitization in northern China and South Korea drives seasonal demand for thermal energy measurement with remote readout capability.
Electric meters dominate procurement volumes through state-mandated grid modernization; water meters are expanding most quickly through municipal non-revenue water programs.
Deployment:
Cost tier differentiation separates capital-intensive on-premises installations from operational-expense cloud models that lower barriers for mid-sized utilities.
- On-Premises:Utility-owned data centers with localized SCADA integration serve security-sensitive state grids in China requiring sovereign data containment.
- Cloud-Based:Third-party hosted analytics platforms reduce upfront infrastructure investment. Philippine and Indonesian municipal utilities are adopting these models fastest where budget constraints limit capital deployment.
- Hybrid:Edge-gateway architectures with cloud failover balance latency requirements against cost optimization for Australian and Japanese utilities with mixed urban-rural coverage.
- Standalone:Prepaid metering units without network backhaul serve Vietnam's rural electrification gaps and remote Indonesian archipelago communities.
Cloud-based deployments are gaining share fastest among budget-constrained municipal utilities; on-premises architectures retain dominance in sovereign-data-sensitive state grids.
End User:
Customer type segmentation tracks procurement authority concentration versus fragmentation across utility ownership structures.
- Utilities:State-owned distribution companies in China and India command centralized procurement at scale with standardized technical specifications and pre-qualified vendor panels.
- Residential:Japan's METI subsidy frameworks are compressing residential AMI replacement cycles beyond normal depreciation schedules through artificial demand front-loading.
- Commercial:Demand response program enrollment drives meter specification toward real-time pricing capability in South Korea and Australian deregulated markets.
- Industrial:High-voltage connection monitoring with power quality analytics serves manufacturing clusters in Vietnam and Thailand seeking grid reliability guarantees.
Utility procurement retains volume concentration through state-mandated rollouts; residential replacement cycles are compressing fastest through subsidy-driven acceleration.
Technology:
Supply concentration for communication chipsets shapes technology adoption feasibility across different deployment environments.
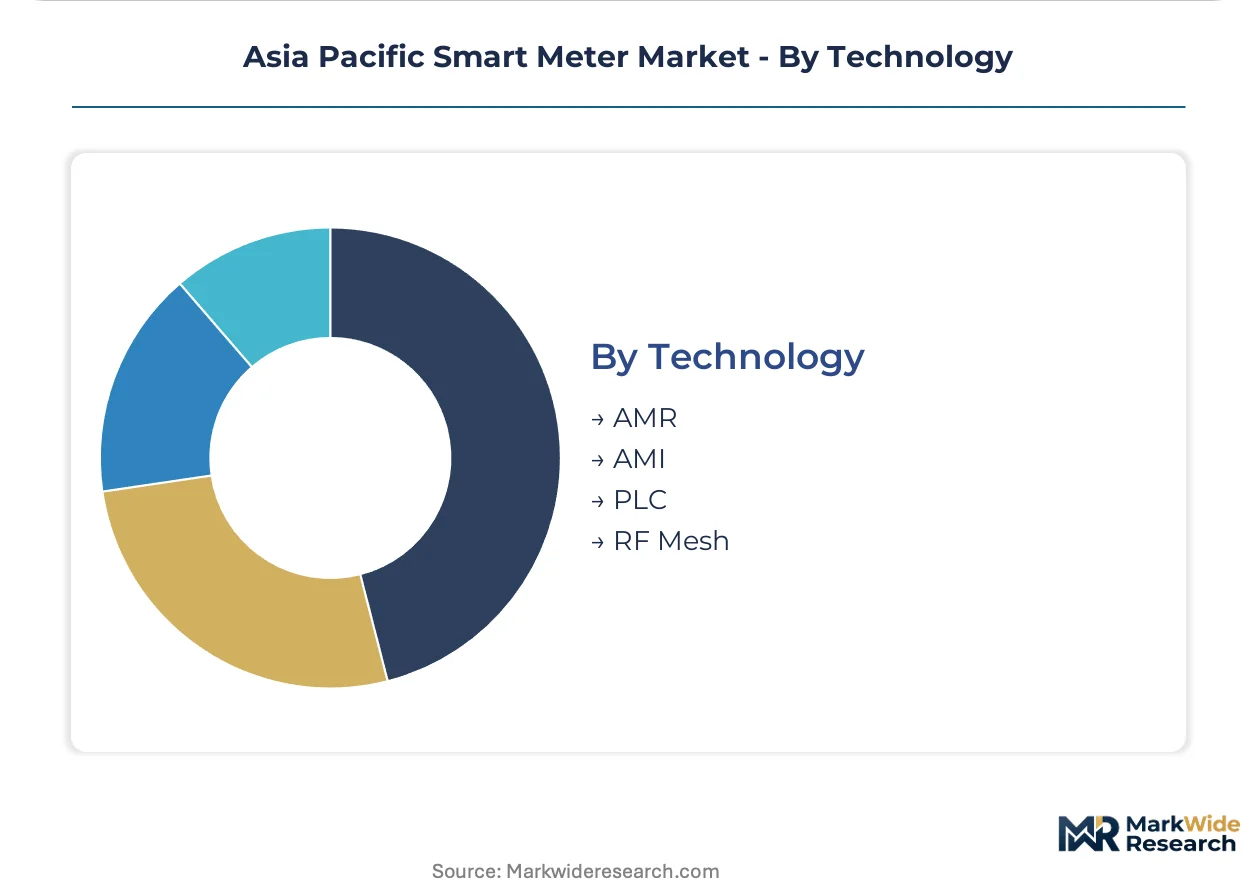
- AMR:Drive-by meter reading systems face stranded asset risk as utilities transition to two-way communication, though legacy infrastructure persists in early-adopter Japanese markets.
- AMI:Two-way advanced metering infrastructure with 15-minute interval data capture is displacing legacy systems across China, India, and Australia's grid modernization programs.
- PLC:Powerline carrier communication provides underground and dense-urban reliability where RF propagation faces interference from building density.
- RF Mesh:Sub-GHz radio frequency mesh networks serve Australian topographical coverage gaps and New Zealand rural distribution, though spectrum congestion limits scalability in dense Japanese metropolitan zones.
AMI is displacing legacy AMR most rapidly through mandate-driven replacement; RF mesh retains specialized application in geographically challenging deployments despite spectrum constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for advanced metering infrastructure is accelerating procurement timelines across state distribution companies. China's dual carbon goals mandate grid digitization to integrate renewable generation. Japan's METI subsidy frameworks compress residential AMI replacement cycles beyond normal depreciation schedules.
China
State Grid Corporation drives centralized procurement at scale for distribution network digitization. MIIT certification requirements and GB standards impose firmware architecture redesigns that extend supplier qualification timelines. Manufacturing clusters in Shenzhen and Hangzhou concentrate module production for domestic deployment and Southeast Asian export.
India
State distribution companies under the PLI scheme are lowering procurement costs and accelerating domestic manufacturing scale. CEA technical standards for smart grid interoperability create pre-qualification bottlenecks that delay vendor onboarding. Deployment concentrates in Maharashtra, Gujarat, and Karnataka where rural electrification programs advance fastest.
Japan
METI subsidy frameworks are front-loading residential AMI capital expenditure through artificial demand compression until 2027. Utilities consolidate vendor panels to ensure delivery certainty amid component allocation constraints. Tokyo Electric Power and Kansai Electric Power drive metropolitan deployment while Tohoku utilities address rural coverage gaps.
Australia
Deregulated market structures prioritize demand response program enrollment with real-time pricing capability. RF mesh networks address topographical coverage gaps in rural distribution zones. Deployment clusters in New South Wales and Victoria adopt hybrid RF-PLC architectures fastest to manage dense urban interference.
Vietnam
Provincial power utilities outside Hanoi and Ho Chi Minh City remain underpenetrated by AMI infrastructure. Prepaid metering solutions target rural electrification gaps without network backhaul requirements. Municipal water utilities in Da Nang and Can Tho sensorize distribution networks under non-revenue water reduction mandates.
Asia Pacific Smart Meter Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform providers while fragmenting at the module component tier. Scale-driven manufacturers with captive semiconductor sourcing dominate domestic procurement in China. Three archetypes define competitive positioning: vertically integrated conglomerates with cloud analytics capabilities, specialized RF mesh competency firms, and manufacturing-scale exporters. Dominant competitive moves include strategic partnerships with equipment financiers for leasing structures and geographic expansion through module exports to Southeast Asian utilities.
Among Asia-Pacific-based manufacturers, Wasion Group and Holley Technology Ltd exemplify scale-driven production archetypes serving domestic Chinese deployments and regional export markets. EDMI Limited occupies a specialized position representing RF mesh competency in Australian and New Zealand utility tenders. Honeywell International anchors the integrated platform provider tier, combining hardware installations with cloud-based analytics capabilities.
| Leading Market Players |
|---|
| Landis+Gyr |
| Honeywell International |
| EDMI Limited |
| Schneider Electric |
| Wasion Group |
| Holley Technology Ltd |
| Badger Meter |
| Suntront Tech Co., Ltd |
| Itron |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shenzhen and Hangzhou manufacturing clusters is compressing module margins while forcing suppliers toward firmware customization services to defend pricing power. This utilization dynamic creates divergent cost structures between commodity meter hardware and certified AMI platforms.
Pricing Analysis
Certification level under China's MIIT framework and India's CEA interoperability standards creates the primary spread between premium and standard tiers. Three-tier pricing structure across certified AMI platforms, pre-qualified standard units, and uncertified economy modules dominates procurement. Pricing pressure stems from leasing model adoption in Indonesia and the Philippines, where equipment financiers capture margin previously retained by manufacturers. State-owned utilities in China and India exhibit lowest price sensitivity due to sovereign-backed procurement; municipal water utilities in Southeast Asia show highest sensitivity given budget constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing and South Korean foundries for communication module chipsets, supplemented by domestic Chinese EMS providers for final assembly. Geographic supply concentration centers on China for meter housings and metrology components, Taiwan and South Korea for RF and PLC chipsets, and Japan for precision sensors. Raw material dependencies include rare earth elements for magnetic components, lithium for battery-backed units, and copper for connectivity infrastructure. Single-source vulnerability in Taiwan and South Korean semiconductor foundries exposes AMI deployments to geopolitical disruption. Distribution runs through direct utility procurement channels in China and India, with integrator-mediated sales dominating Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific smart meter market is approaching a platform-economics inflection where interoperability certification becomes the primary moat. China's GB standards and India's CEA rules are converging toward mutual recognition frameworks that will reshape vendor consolidation trajectories.
For Market Incumbents: Insulate installed base value by embedding edge analytics modules that hybridize with traditional metrology, creating switching costs through predictive maintenance data accumulation. Accelerate backward integration into secure element manufacturing to reduce exposure to Taiwan and South Korean foundry concentration. Prioritize certification pre-qualification under India's CEA technical standards to lock out emerging competitors facing 12-18 month onboarding delays.
For New Entrants and Emerging Players: Vietnam's provincial power utilities outside Hanoi and Ho Chi Minh City offer first-mover positioning for prepaid metering solutions without network backhaul requirements. Municipal water utilities in Philippine cities under non-revenue water mandates present parallel entry points given urgent procurement pressure without matching capital budgets. Partner with equipment financiers to offer pay-as-you-go leasing structures that bypass incumbent capital purchase relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform providers combining hardware installations with cloud-based analytics subscriptions. Long-term viability favors vendors with certified secure element integration and pre-qualified status across multiple national regulatory regimes. Acquisition target archetype: specialized RF mesh competency firms with established utility relationships in Australia and New Zealand. Monitor India's PLI scheme disbursement velocity as inflection indicator for domestic manufacturing scale acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Integration | MIIT and CEA cybersecurity mandates favor vendors with certified firmware architecture capabilities. |
| Leasing Structure Partnerships | Equipment financiers capture margin from traditional manufacturers in Indonesian and Philippine municipal markets. |
| Hybrid RF-PLC Module Development | Australian utilities adopt dual-band architectures fastest to address topographical coverage gaps. |
| Edge Analytics Attachment | On-device machine learning for anomaly detection opens premium pricing tiers for predictive maintenance. |
| CEA Pre-Qualification Investment | India's interoperability certification backlog creates 12-18 month defensive moats for pre-approved vendors. |
Study Parameters
Desk research of regulatory filings from China's MIIT, India's CEA, and Japan's METI preceded structured interviews with utility planning officers, AMI procurement leads, and smart grid engineering directors. Secondary validation drew from State Grid Corporation tender databases, SEC filings of listed meter manufacturers, and customs trade records for module exports. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts from national electrification programs.
The analytical framework held carbon neutrality policy commitment intensity fixed while varying subsidy disbursement timing and semiconductor supply availability across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user category, and communication technology. CAGRs derived from logistic diffusion curves fitted to AMI penetration rates by country, with inputs from distribution network digitization budget allocations and renewable integration mandates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated conglomerates or state-backed domestic manufacturers would shift outcomes. Semiconductor supply disruption, regulatory certification delays, or subsidy program suspension represent specific revision risks. Quarterly review of component allocation constraints and CEA pre-qualification pipeline velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Power Metering Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Solar Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
Power Monitoring System Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Water Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
US Water Meter Market