
 Digital Gas Meter Market | 2026-2036
Digital Gas Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Gas Meter Market Insights
Modular smart meter bundling with AMI communication modules is pivoting buyer choice away from standalone mechanical units. Honeywell International Inc. leverages its sensing technology heritage to anchor premium ultrasonic portfolios. Kamstrup A/S dominates European utility tenders through vertically integrated production of radio-frequency endpoints. Itron Inc. competes on software stack depth, extending cloud analytics capabilities that differentiate its platform from hardware-only rivals.
A digital gas meter is an electronic flow measurement instrument that quantifies natural gas or hydrogen consumption using sensors such as ultrasonic transducers or capacitive elements, typically achieving accuracy classes of 1.0 or 1.5 under ISO 4064 standards, and transmits data via wired or wireless protocols for billing and grid optimization. Smart meters within the product type category lead volume deployment as utilities pursue remote disconnect and leak detection functionality, while diaphragm technology retains cost advantages in residential retrofits where pipework constraints limit ultrasonic adoption. Ultrasonic technology represents the fastest-growing technology segment, displacing traditional mechanical designs in commercial and industrial applications where turndown ratio and low-flow sensitivity determine measurement integrity.
The Federal Energy Regulatory Commission in the United States and the EU F-Gas Regulation jointly shape product standards, with FERC Order 2222 enabling distributed resource aggregation that requires sub-hourly meter data while REACH compliance constrains material selection for sensor housings. Germany's KBA and France's ANSM do not regulate gas meters directly, but national metrology institutes across EU member states enforce MID certification for market access. Stakeholders must monitor hydrogen blending mandates from regulators in Germany, Japan, and South Korea, as these will force recalibration of ultrasonic algorithms and compatibility certification for existing meter fleets.
Market Dynamics
AMI infrastructure rollouts across Germany, Japan, and the United States are compressing replacement cycles for mechanical meters, forcing utilities to rebalance capital allocation between hardware procurement and cloud analytics integration.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-carbon grid infrastructure accelerate ultrasonic meter adoption in utility tenders across France, Italy, and Spain.
- Remote disconnect functionality:Smart meter bundles with leak detection sensors reduce field service costs for municipal gas distributors in Japan.
- Hydrogen blending pilots:South Korea's KGS certification requirements for H2-compatible meters open retrofit opportunities in industrial clusters near Ulsan.
Market Restraints
- MEMS sensor supply concentration:Taiwanese foundry capacity constraints create 14-18 week lead times for ultrasonic transducer arrays.
- Mechanical meter residual value:Decades-long depreciation schedules in regulated US utilities delay AMI authorization in rate cases.
- Copper and lithium price volatility:Battery-backed communication modules face input cost swings that compress OEM margins on residential endpoints.
Strategic Opportunities
- India's AMR mandate under CEA:City gas distribution licensees in Mumbai and Delhi must deploy digital meters by 2027, creating tender volume.
- Edge-AI convergence:On-device anomaly detection algorithms reduce cloud data costs for utilities managing millions of endpoints.
- Pay-as-you-go residential models:Prepaid metering via mobile wallets penetrates informal settlements in South African metros.
Industry Challenges
- MID certification timelines:German PTB and French LNE testing queues extend 8-12 months for new ultrasonic firmware releases.
- Legacy SCADA integration:Protocol translation between DLMS/COSEM meters and 1990s-era DMS platforms requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Gas Meter Market |
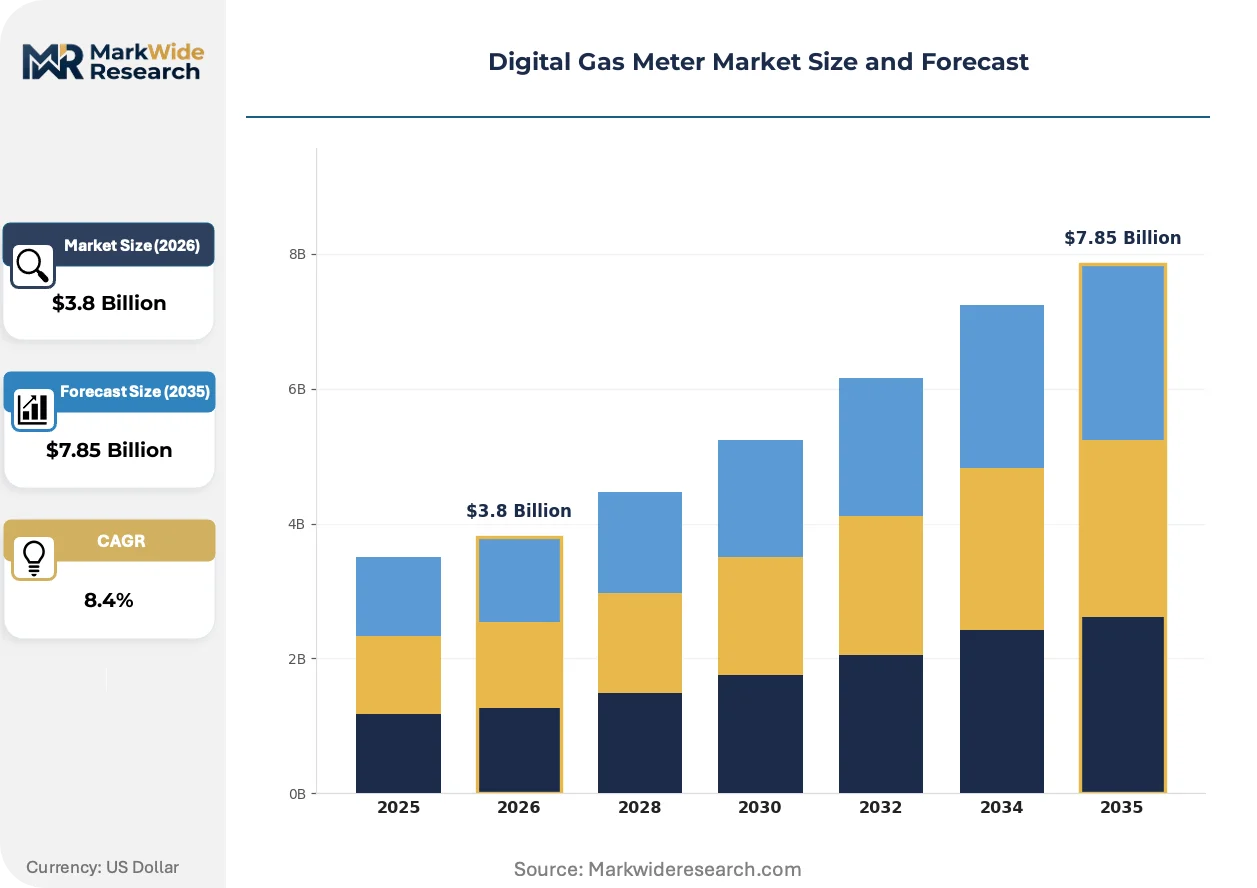
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Meters, Commercial Meters, Industrial Meters, Smart Meters Technology: Ultrasonic, Diaphragm, Capacitive, Electromagnetic Installation Type: Indoor Installation, Outdoor Installation, Wall-Mounted, Portable End User: Utilities, Gas Companies, Industrial Facilities, Household Consumers |
| Companies Covered | Diehl Stiftung & Co. KG, Sensus, Honeywell International Inc., Kamstrup A/S, Waltero, Itron Inc., Landis+Gyr, Emerson Electric Co., Apator SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Gas Meter Market Trends and Innovations
Measurement architectures are fragmenting as distributed energy resources force bidirectional data flows and real-time grid balancing algorithms.
Ultrasonic flow sensing with time-of-flight calculation is decentralizing custody transfer verification away from centralized laboratory calibration. Large industrial offtakers in the US Gulf Coast petrochemical corridor now deploy in-situ diagnostic arrays that self-validate against ISO 17025 traceability chains. This shift compresses third-party metrology service revenue while expanding firmware subscription attach rates.
REACH compliance for sensor housings is forcing material substitutions from ABS to glass-filled PBT in EU-bound product lines. ECHA substance restriction updates every 24 months trigger BOM revisions that strain supplier qualification programs. German meter OEMs now maintain dual material stacks to hedge against SVHC list expansion.
Buyer committees now specify API-accessible meter data as a standard procurement term, unbundling hardware from software licensing. European municipal utilities in the Netherlands and Denmark lead this shift, replacing perpetual licenses with consumption-indexed SaaS agreements. This restructures vendor cash flows from upfront recognition to recurring revenue streams.
Digital Gas Meter Market Segmentation
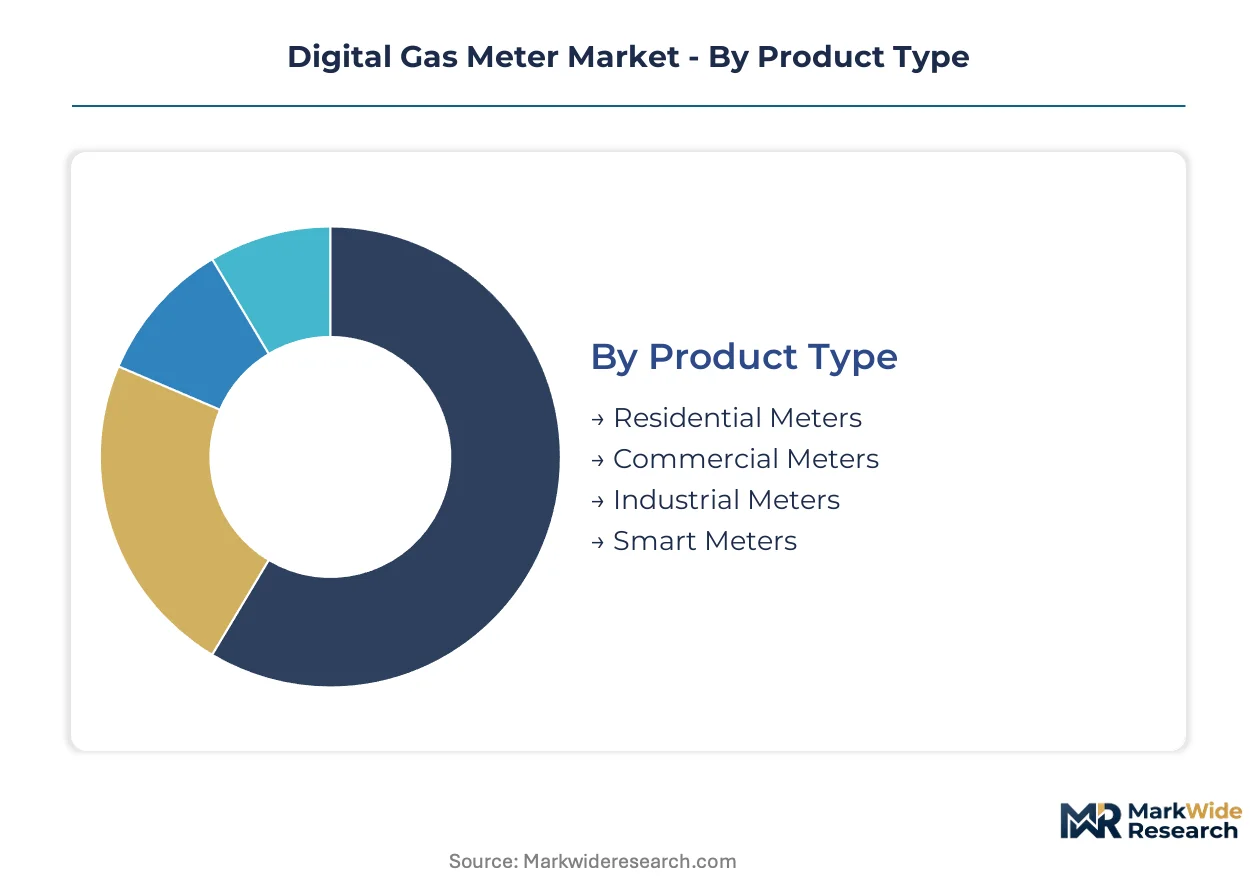
Segmentation in the digital gas meter market determines procurement specifications, certification pathways, and margin structures. Buyers prioritize different performance thresholds across residential, commercial, and industrial deployments, while technology choices lock in maintenance regimes and data architectures for decades.
Product Type:
Supply concentration in residential endpoints dominates OEM production scheduling, with foundry capacity prioritizing high-volume diaphragm and ultrasonic variants.
- Residential Meters:Compact flow measurement devices designed for low-pressure natural gas service, typically rated at G4 or G6 capacity. Municipal utilities in Germany and Japan deploy these in mass replacement programs where AMI integration mandates remote read capability. FERC Order 2222 compliance in the United States accelerates sub-hourly data requirements.
- Smart Meters:Integrated measurement and communication endpoints enabling remote disconnect, leak detection, and prepaid billing. City gas distributors in South Korea and the Netherlands specify these for new housing developments where edge analytics reduce cloud infrastructure costs.
- Commercial Meters:Mid-capacity units serving small businesses and multi-tenant buildings with higher turndown ratios than residential variants.
- Industrial Meters:High-pressure, high-accuracy custody transfer devices for petrochemical and power generation offtakers.
Residential meters absorb the bulk of installed capacity; smart meters are expanding most quickly.
Technology:
Cost tier differentiation separates premium ultrasonic platforms from legacy mechanical designs, with material selection driving REACH compliance costs in EU-bound product lines.
- Ultrasonic:Time-of-flight flow measurement using piezoelectric transducer pairs, achieving accuracy class 1.0 under ISO 4064. Industrial facilities along the US Gulf Coast and in Ulsan, South Korea specify these for hydrogen blending compatibility where algorithm recalibration supports variable gas composition.
- Diaphragm:Positive displacement measurement via oscillating chambers, retaining cost advantages in residential retrofits where pipework constraints prevent ultrasonic retrofit. Indian city gas distribution licensees under CEA mandate deploy these in cost-sensitive Mumbai and Delhi tenders.
- Capacitive:Dielectric sensing for specialized low-flow applications in laboratory and medical gas distribution.
- Electromagnetic:Faraday's law-based measurement for wet gas and impurity-laden industrial streams.
Diaphragm technology retains the largest installed base; ultrasonic platforms are climbing the fastest.
Installation Type:
Application environment dictates housing specifications, with outdoor variants requiring IP67 ratings and extended temperature ranges that add 15-20% to BOM costs.
- Outdoor Installation:Weather-hardened enclosures with battery-backed communication modules for pit or pole mounting. Japanese gas utilities specify these for earthquake resilience in Tokyo and Osaka metropolitan areas.
- Indoor Installation:Standard housings for utility room or basement placement in European multi-family housing.
- Wall-Mounted:Compact form factors for space-constrained retrofits in older UK housing stock.
- Portable:Temporary measurement for construction site fuel accounting and emergency response.
Outdoor installation commands the highest unit economics; wall-mounted variants are gaining share fastest in dense European housing.
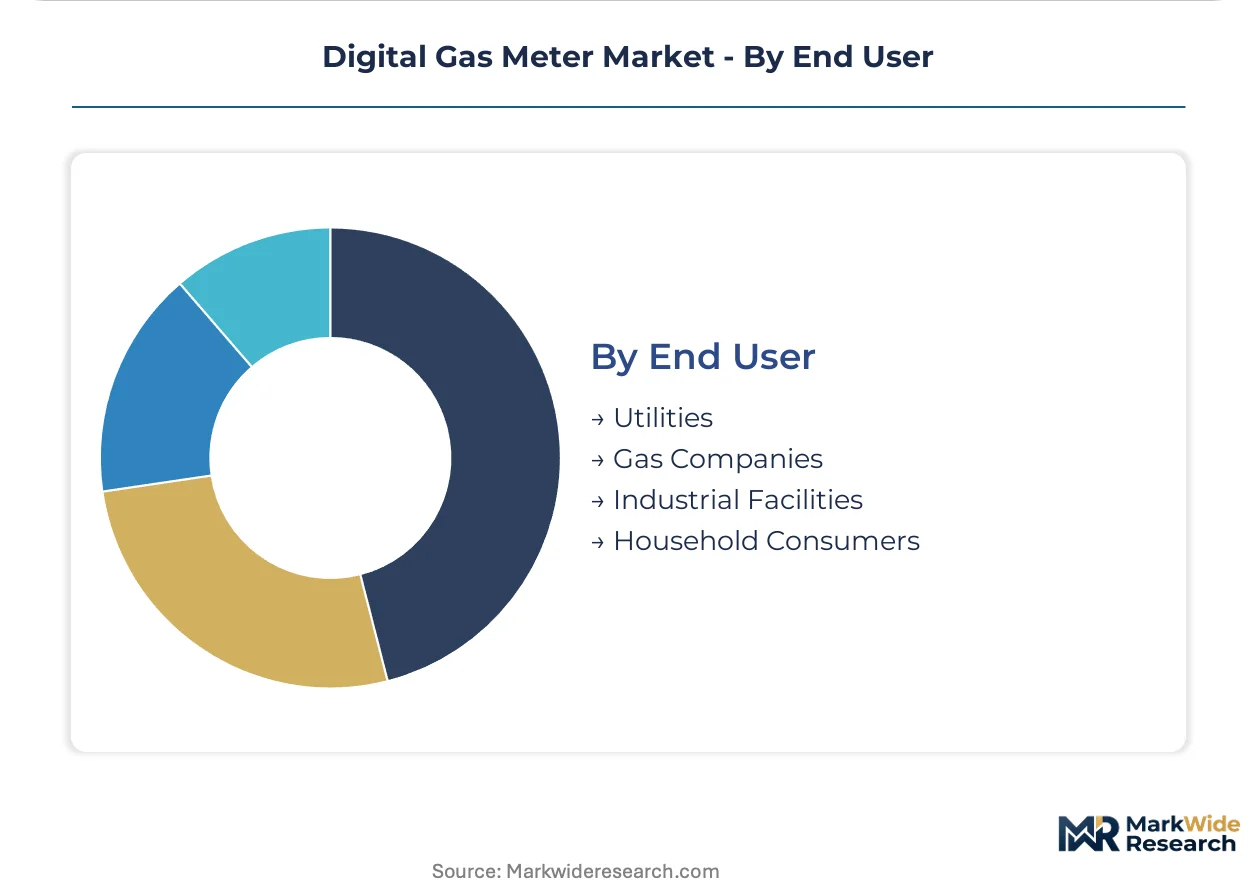
End User:
Customer type determines procurement authority, with utilities consolidating purchasing through framework agreements while industrial facilities negotiate directly for custody transfer specifications.
- Utilities:Regulated entities procuring AMI-compatible endpoints through multi-year tenders, prioritizing interoperability with existing SCADA and billing systems. German municipal utilities lead unbundling of hardware from SaaS licensing.
- Industrial Facilities:Large offtakers in petrochemical corridors requiring in-situ diagnostic arrays with ISO 17025 traceability. These buyers compress third-party metrology spend while subscribing to firmware validation services.
- Gas Companies:Integrated energy retailers with bundled service offerings spanning measurement through billing.
- Household Consumers:Individual purchasers in prepaid metering markets, particularly South African informal settlements where mobile wallet integration enables pay-as-you-go models.
Utilities dominate procurement volume; industrial facilities are driving the steepest expansion trajectory for premium ultrasonic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for clean energy manufacturing in South Korea, Germany, and the United States concentrate ultrasonic meter production capacity near hydrogen blending pilot sites.
United States
FERC Order 2222 mandates sub-hourly interval data from distributed resource aggregators. The EPA's methane emissions rules tighten measurement accuracy requirements for midstream operators. Gulf Coast petrochemical clusters near Houston deploy in-situ diagnostic arrays that self-validate custody transfer without third-party laboratory recalibration.
Germany
The EU Green Deal accelerates AMI replacement timelines for municipal utilities in North Rhine-Westphalia. Germany's national metrology institute PTB enforces MID certification queues extending 8-12 months for new ultrasonic firmware. Industrial hydrogen clusters in the Ruhr region demand recalibrated algorithms for variable gas composition metering.
Japan
METI's decarbonization roadmap funds smart meter deployment with earthquake-resilient outdoor housings. The country's gas safety regulations mandate remote leak detection functionality for Tokyo and Osaka metropolitan utilities. City gas distributors specify battery-backed communication modules for pit-mounted installations in dense urban corridors.
South Korea
KGS certification requirements for hydrogen-compatible meters open retrofit opportunities near Ulsan industrial complexes. The government's hydrogen economy roadmap drives procurement standards for H2-blended natural gas measurement. Manufacturing zones in the Southeast region concentrate transducer assembly capacity for export markets.
India
CEA mandates under the city gas distribution program require digital meter deployment by 2027 for Mumbai and Delhi licensees. The country's petroleum regulator frames technical specifications for AMR integration in cost-sensitive tenders. Distribution networks in Gujarat and Maharashtra prioritize diaphragm technology for residential retrofits with pipework constraints.
Digital Gas Meter Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The market exhibits moderate consolidation with tiered pricing stratification between premium ultrasonic platforms and economy diaphragm variants. Three archetypes dominate: sensing technology heritage players, vertically integrated European utility suppliers, and software-centric platform providers. Competitive moves center on AMI communication module bundling and cloud analytics licensing unbundling from hardware sales.
Among diversified technology conglomerates, Honeywell International Inc. and Emerson Electric Co. occupy positions anchored by industrial automation portfolios. Kamstrup A/S exemplifies the European pure-play archetype with vertically controlled production of radio-frequency endpoints. Itron Inc. sits within the software-differentiated tier where cloud analytics capabilities separate platform providers from hardware-only competitors.
| Leading Market Players |
|---|
| Diehl Stiftung & Co. KG |
| Sensus |
| Honeywell International Inc. |
| Kamstrup A/S |
| Waltero |
| Itron Inc. |
| Landis+Gyr |
| Emerson Electric Co. |
| Apator SA |
| Others |
Pricing and Supply Chain Analysis
Ultrasonic transducer manufacturing migration from mechanical assembly to semiconductor-style wafer processing simultaneously compresses per-unit sensor costs and concentrates foundry dependence among Taiwanese and South Korean producers. This dual shift amplifies pricing power for OEMs with captive transducer supply while exposing diaphragm meter specialists to margin pressure from input cost volatility.
Pricing Analysis
Lead-time premiums now dominate contract negotiations, with utilities paying 12-18% markups for ultrasonic meter delivery under 20 weeks versus standard 35-week schedules. Pricing stratifies across premium, standard, and economy tiers based on MID certification grade and AMI communication module integration depth. Cost compression in residential endpoints is intensifying because Indian CEA-mandated tenders prioritize lowest-unit-cost diaphragm variants. Municipal utilities in Germany and Japan exhibit lowest price sensitivity due to decarbonization-linked procurement budgets, while South African prepaid metering distributors face acute margin constraints.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific manufacturing hubs to European utility depots now exceeds 8% of landed meter value, reshaping regional sourcing strategies. Production concentrates in Germany, Taiwan, and South Korea for ultrasonic transducer arrays; China and India for diaphragm meter castings. Raw material dependencies center on piezoelectric ceramics, glass-filled PBT for REACH-compliant housings, and lithium primary cells for battery-backed communication modules. Single-source vulnerability from Taiwanese MEMS foundry concentration threatens 14-18 week lead time extensions. Distribution runs through utility framework agreements and city gas distribution licensee tenders, with aftermarket service parts flowing via OEM-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital gas meter market sits in a technology-transition phase where ultrasonic platforms displace mechanical designs across utility-scale deployments. This shift demands strategic repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: Deepen backward integration into transducer wafer processing to offset Taiwanese foundry bottlenecks and defend margin position against emerging Asian OEMs. Prioritize MID certification pre-approval for hydrogen-blending firmware releases before German PTB and French LNE queues extend further. Secure multi-year AMI communication module supply agreements with semiconductor partners to lock in volume allocation. For New Entrants and Emerging Players: Municipal utility SaaS partnerships in the Netherlands and Denmark offer lowest competitive density for software-differentiated market entry. Target India's city gas distribution licensees under CEA mandate for diaphragm meter volume, where incumbent relationships remain unconsolidated. Pursue white-label ultrasonic assembly for European OEMs seeking to diversify supply beyond vertically integrated specialists. For Investors and Strategic Acquirers: Re-rating potential sits with software-centric meter platform providers given unbundling of hardware from recurring SaaS revenue streams. Five-to-ten year viability favors firms with dual-stack material qualification for REACH compliance and hydrogen-ready firmware architectures. Watch German hydrogen blending mandate implementation timelines as the signal for ultrasonic algorithm recalibration demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AMI Communication Module Bundling | Utilities in Japan and Germany now specify integrated radio-frequency endpoints as standard procurement terms. |
| Hydrogen Compatibility Certification | KGS certification in South Korea and PTB testing in Germany create first-mover advantages for H2-blend metering. |
| Edge-AI Firmware Development | On-device leak detection algorithms reduce cloud infrastructure costs for municipal utilities managing dense endpoint networks. |
| REACH Dual-Material Stack Maintenance | German OEMs hedge against ECHA SVHC list expansion by qualifying glass-filled PBT alongside ABS housings. |
| Pay-as-you-Go Platform Integration | Mobile wallet interoperability penetrates South African informal settlements where traditional billing infrastructure is absent. |
Research Methodology
Multi-period observation of AMI deployment timelines, hydrogen blending pilot progress, and MEMS foundry capacity utilization anchored the trend analysis, supplemented by interviews with utility planning officers, city gas distribution procurement leads, ultrasonic transducer R&D directors, and AMI platform integration specialists. Secondary validation drew from FERC Order 2222 filings, EU F-Gas Regulation implementation reports, ECHA substance restriction updates, and CEA city gas distribution licensing records. Bottom-up unit economics modeling triangulated against top-down utility capital expenditure projections.
Input-output matrices mapped transducer production capacity, raw material cost indices, and regulatory certification queues to deployment volume forecasts across the projection horizon. Segmentation dimensions modeled include product type, technology tier, installation environment, and end-user procurement authority, with hydrogen-readiness certification status as an industry-specific overlay. CAGRs were derived from regression analysis of historical replacement cycles against policy-mandated acceleration factors, incorporating utility rate case approval timelines and foundry capacity expansion announcements.
Caveats apply where Taiwanese semiconductor export restrictions, ECHA SVHC list expansion, or FERC distributed resource aggregation rule revisions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
United States Smart Meter Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
North America Smart Meters Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Water Meter Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Europe Water Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Residential Smart Water Metering Market