
 Europe Smart Meters Market | 2026-2036
Europe Smart Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Meters Market Foresight
Advanced Metering Infrastructure specification upgrades are unwinding legacy AMR deployments across European utilities. Landis+Gyr leverages its Swiss manufacturing base to dominate high-precision electric meter supply for Central European grids. Siemens sustains technology leadership through integrated grid-edge software paired with German-engineered hardware platforms. Kamstrup anchors Nordic markets with specialized ultrasonic water metering systems designed for cold-climate accuracy.
Europe smart meters are electronic devices that measure utility consumption in real time, communicate via RF mesh or cellular networks, and support remote disconnect functions with measurement accuracy typically within 0.2-2.0% depending on meter class. Their primary purpose is to enable dynamic pricing, detect outages instantly, and balance distributed energy resources across modernized distribution networks. Electric meters lead product type deployment as renewable integration strains legacy grid infrastructure, while AMI technology captures the fastest growth trajectory due to its two-way communication and demand-response capabilities. Wireless connectivity is displacing wired alternatives in retrofit-heavy markets where trenching costs prove prohibitive.
The EU Green Deal and F-Gas Regulation shape product standards by mandating energy efficiency disclosures and restricting fluorinated gases in meter manufacturing processes. ECHA REACH compliance governs material composition for circuit boards and housings, while CE marking remains mandatory for market access across all member states. National regulators including Germany's BNetzA and France's CRE enforce binding rollout quotas that lock in replacement demand regardless of wholesale energy price volatility. Stakeholders must monitor the divergence between cloud and hybrid deployment architectures as cybersecurity requirements harden under the EU Cybersecurity Act.
Market Dynamics
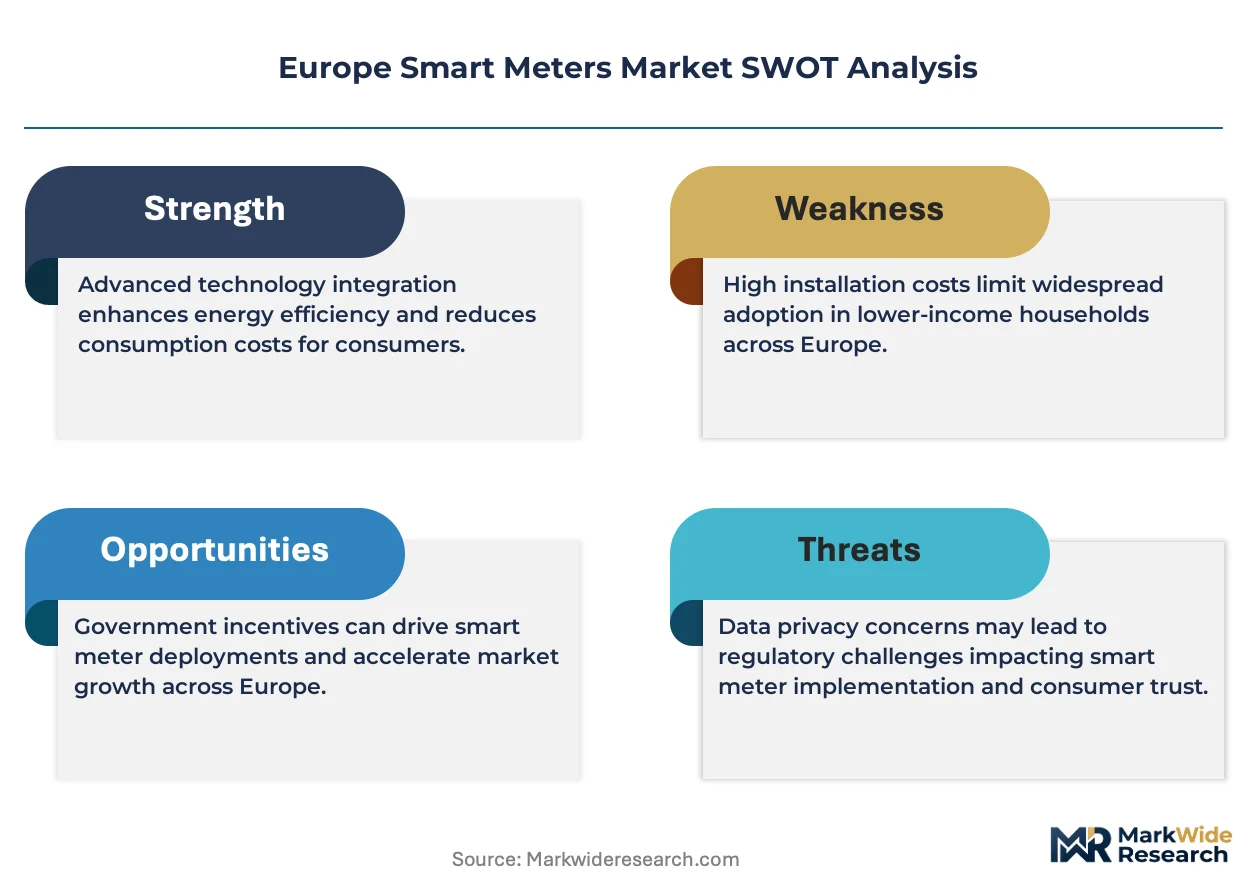
EU Green Deal mandates are forcing a wholesale replacement of legacy metering infrastructure across member states, with binding national rollout quotas locking in demand regardless of energy price volatility. This regulatory pressure is compressing deployment timelines and reshaping supplier competition.
Growth Catalysts
- AMI Technology Mandates:Germany's BNetzA and France's CRE enforce binding smart meter installation quotas that guarantee replacement demand through 2035. Utilities must comply regardless of wholesale electricity price fluctuations.
- Distributed Energy Integration:Solar and wind proliferation strains legacy grid infrastructure, requiring two-way communication capabilities that only AMI systems provide. Grid operators in Italy and Spain prioritize meters with demand-response functionality.
- RF Mesh Networks:Wireless connectivity eliminates trenching costs in dense urban retrofit environments. Central European utilities favor cellular-backhauled mesh architectures for last-mile coverage.
Market Restraints
- Semiconductor Supply Concentration:Metering-grade microcontrollers and RF transceivers depend on concentrated Asian foundry capacity. European utilities face extended lead times for AMI communication modules.
- REACH Compliance Burden:ECHA restrictions on circuit board materials and housing compounds force costly redesigns. Smaller meter manufacturers struggle with substance testing and documentation requirements.
- Copper Price Volatility:Current transformer cores and wiring harnesses expose meter producers to commodity swings. Procurement teams hedge forward positions to stabilize production costs.
Strategic Opportunities
- Poland and Eastern Europe:Smart metering penetration lags Western European averages by 8-12 percentage points. National regulators are finalizing rollout frameworks that will unlock mass deployment contracts.
- Hybrid Cloud Architectures:Utilities seek edge-computing meters that process data locally while transmitting aggregates to central systems. This convergence addresses GDPR data localization requirements.
- Ultrasonic Water Metering:Cold-climate accuracy specifications in Nordic markets favor solid-state measurement over mechanical alternatives. Kamstrup's Danish engineering base positions suppliers for specification wins.
Industry Challenges
- Cybersecurity Certification Delays:The EU Cybersecurity Act mandates Common Criteria evaluation for network-connected meters. Testing backlogs at notified bodies extend product launch timelines by 6-9 months.
- Legacy System Integration:Head-end software from 1990s-era AMR deployments lacks API compatibility with modern AMI platforms. Utilities must run parallel systems during multi-year transition periods.
- Field Engineer Shortage:Specialized technicians for meter installation and commissioning are scarce in rural France and southern Italy. Training programs cannot scale to meet deployment targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Meters Market |
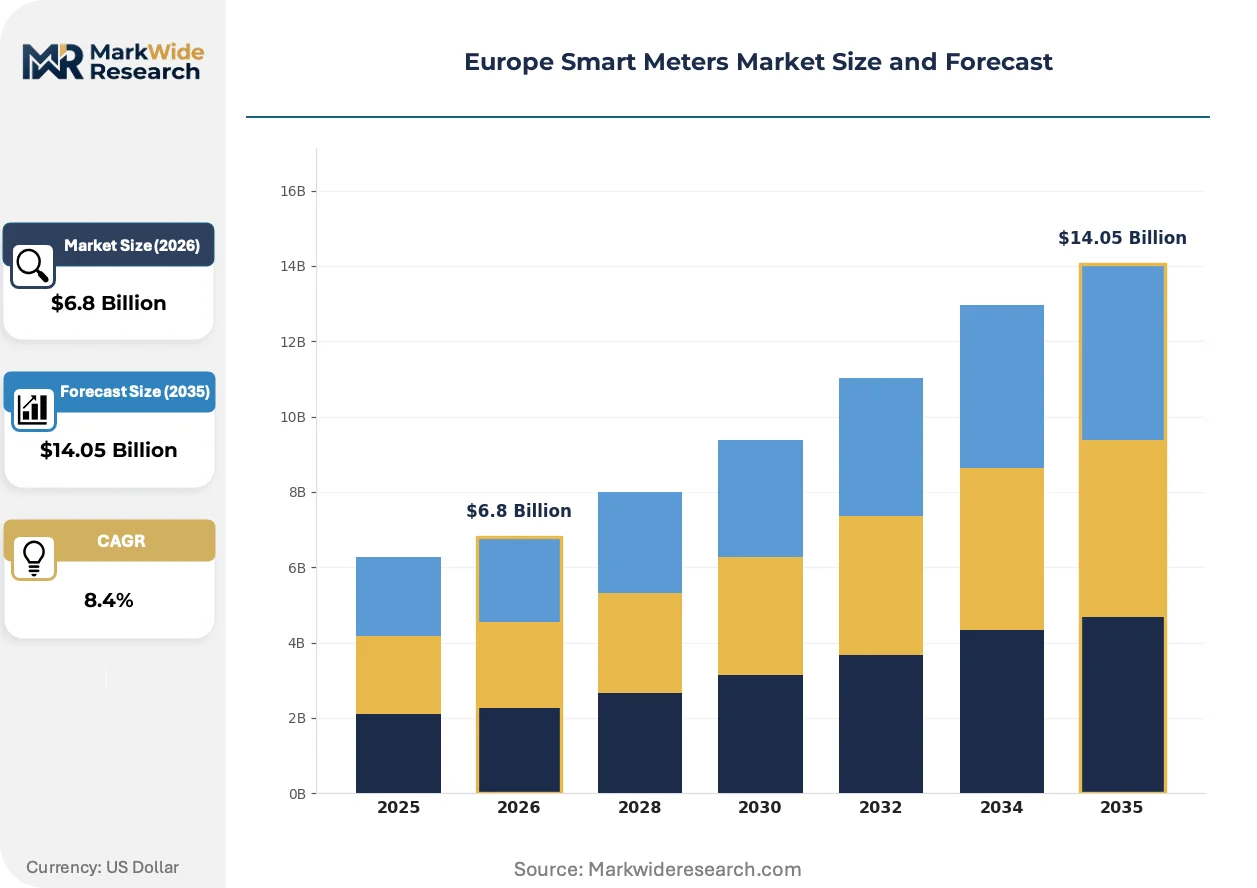
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meter, Gas Meter, Water Meter, Multi-Utility Meter Technology: AMR, AMI, Wireless, Wired End User: Residential, Commercial, Industrial, Utilities Deployment: On-Premise, Cloud, Hybrid, Remote |
| Companies Covered | Xylem, Siemens, Landis+Gyr, Sagemcom, Schneider Electric, Itron Inc., Honeywell International, Diehl Metering, Kamstrup, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Meters Market Shifts & Advancements
Three forces are reshaping European smart meter competition: component miniaturization enabling new form factors, cybersecurity hardening under EU regulation, and procurement model evolution favoring integrated solution providers over hardware-only vendors.
Ultrasonic sensing technology is miniaturizing measurement modules to sub-50mm footprints while maintaining 0.2% accuracy class. Nordic water utilities are adopting these compact sensors for retrofit installations in meter pits with severe space constraints. The technology is miniaturizing mechanical component counts, reducing failure rates and extending calibration intervals beyond fifteen years.
The EU Cybersecurity Act and accompanying EN 303 645 standards mandate cryptographic hardware modules for all network-connected meters. Manufacturers must redesign communication stacks to support post-quantum encryption algorithms by 2028. Italian and Spanish utilities are prioritizing pre-certified platforms to accelerate procurement timelines.
Utility procurement teams now bundle meter hardware with long-term software subscriptions and managed services. Traditional equipment vendors face margin compression as integrated platform providers capture recurring revenue streams. This shift is most pronounced in Germany, where municipal utilities favor ten-year total-cost-of-ownership contracts over capital purchase models.
Europe Smart Meters Market Segmentation
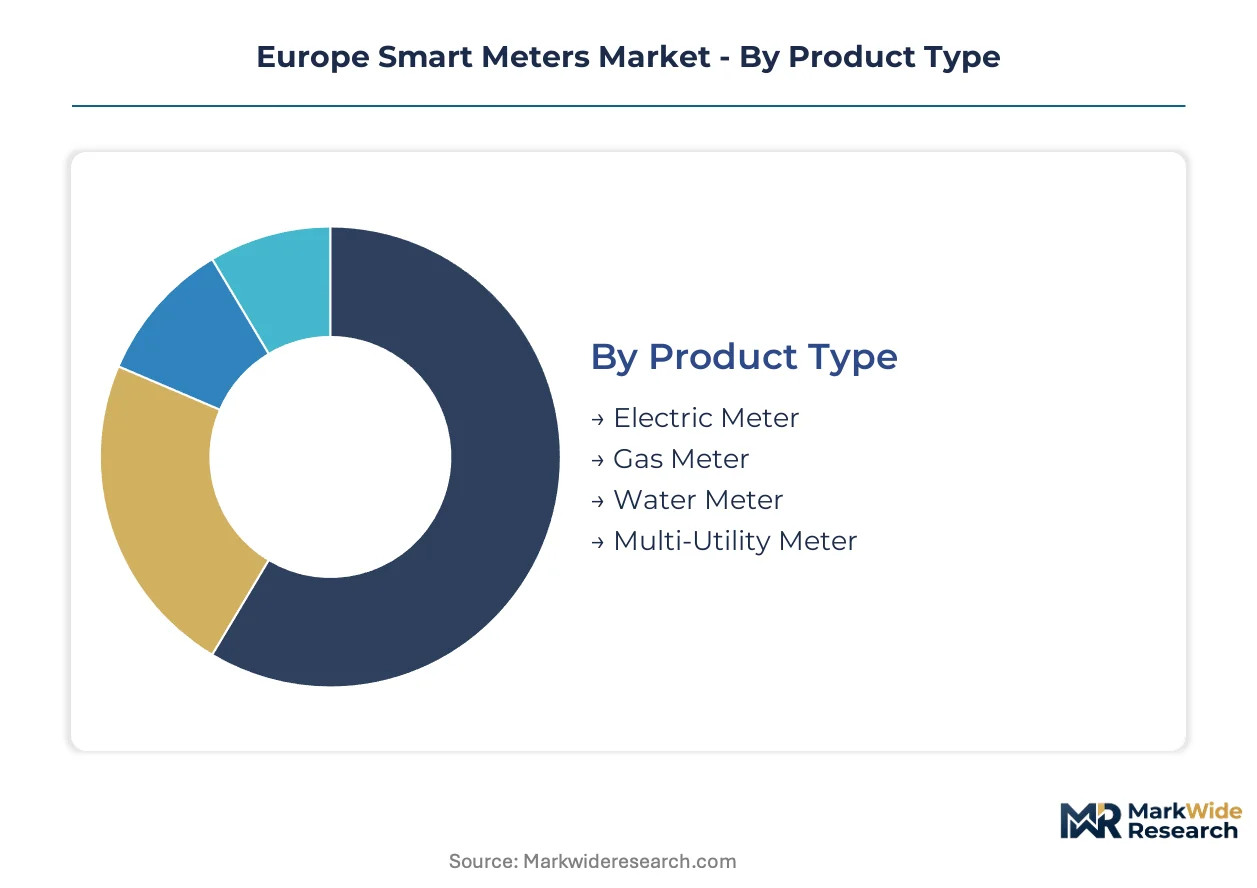
Smart meter segmentation in Europe reflects divergent regulatory timelines, infrastructure maturity, and utility procurement strategies across member states. Category boundaries are blurring as multi-utility meters and hybrid deployments gain traction in retrofit-heavy markets.
Product Type:
Substitution pressure concentrates in mechanical gas and water meters, where ultrasonic and solid-state technologies displace legacy diaphragm and turbine designs. Electric meters face less direct substitution but compete against integrated energy management platforms.
- Electric Meter:These devices measure alternating current consumption with accuracy classes ranging from 0.2S to 2.0, communicating via RF mesh or cellular modules. Demand concentrates in Germany and France where BNetzA and CRE enforce binding installation quotas for distributed solar integration. Grid operators prioritize bidirectional measurement capabilities for prosumer net metering.
- Water Meter:Ultrasonic and electromagnetic technologies eliminate moving parts, extending calibration intervals beyond fifteen years in Nordic cold-climate specifications. Danish and Swedish utilities lead specification upgrades for pit-mounted retrofits where space constraints favor miniaturized sensors.
- Gas Meter:Diaphragm meters dominate installed base but ultrasonic flow measurement captures new-build contracts for hydrogen-blend readiness. Italian utilities specify thermal mass flow sensors for compressed natural gas measurement accuracy.
- Multi-Utility Meter:Single-device consolidation of electric, gas, and water measurement reduces installation labor costs. Polish and Romanian regulators evaluate unified metering frameworks for mass rollout efficiency.
Electric meters anchor the volume base while water meters gain share at the steepest rate as ultrasonic technology penetrates cold-climate retrofit specifications.
Technology:
Cost tier differentiation separates capital-intensive AMI platforms from legacy AMR upgrade paths, with wireless architectures commanding premium pricing over wired alternatives in dense urban environments.
- AMI:Advanced Metering Infrastructure enables two-way communication, remote disconnect, and demand-response coordination through IP-based networks. Spain and Italy prioritize AMI for distributed energy resource balancing as solar penetration strains distribution feeders. Grid-edge computing capabilities process consumption data locally before cloud transmission.
- AMR:Automated Meter Reading provides one-way consumption data via drive-by or fixed-network RF collection. Eastern European utilities deploy AMR as an intermediate upgrade where full AMI capital budgets remain unapproved.
- Wireless:RF mesh and cellular architectures eliminate trenching costs in historic city centers. Central European utilities favor mesh networks with cellular backhaul for last-mile coverage reliability.
- Wired:Power-line communication and Ethernet deployments persist in new construction and industrial campuses. German industrial parks specify wired meters for electromagnetic immunity in heavy manufacturing environments.
Wireless deployments dominate retrofit economics while AMI platforms expand most quickly under Green Deal-mandated rollout schedules.
End User:
Application requirements diverge sharply across customer classes, with industrial meters demanding highest accuracy certification and utilities requiring fleet-scale management platforms.
- Residential:Single-phase meters with 60A-100A capacity serve apartment dwellings and detached homes. French and Italian mass rollout programs target residential premises first for demand-response enrollment scale.
- Commercial:Three-phase meters with sub-metering capabilities track consumption by tenant or department. German retail chains and office parks specify MID-certified meters for tenant billing accuracy.
- Industrial:0.2S accuracy class meters with harmonic distortion measurement support power quality monitoring. Spanish automotive and chemical plants prioritize meters with IEC 61850 substation integration.
- Utilities:Grid operators deploy meters as network sensors for outage detection and voltage monitoring. Distribution system operators in the Netherlands and Belgium specify meters with synchronized phasor measurement capabilities.
Residential installations constitute the volume foundation while utility-grade deployments capture the steepest value expansion as grid operators instrument distribution networks.
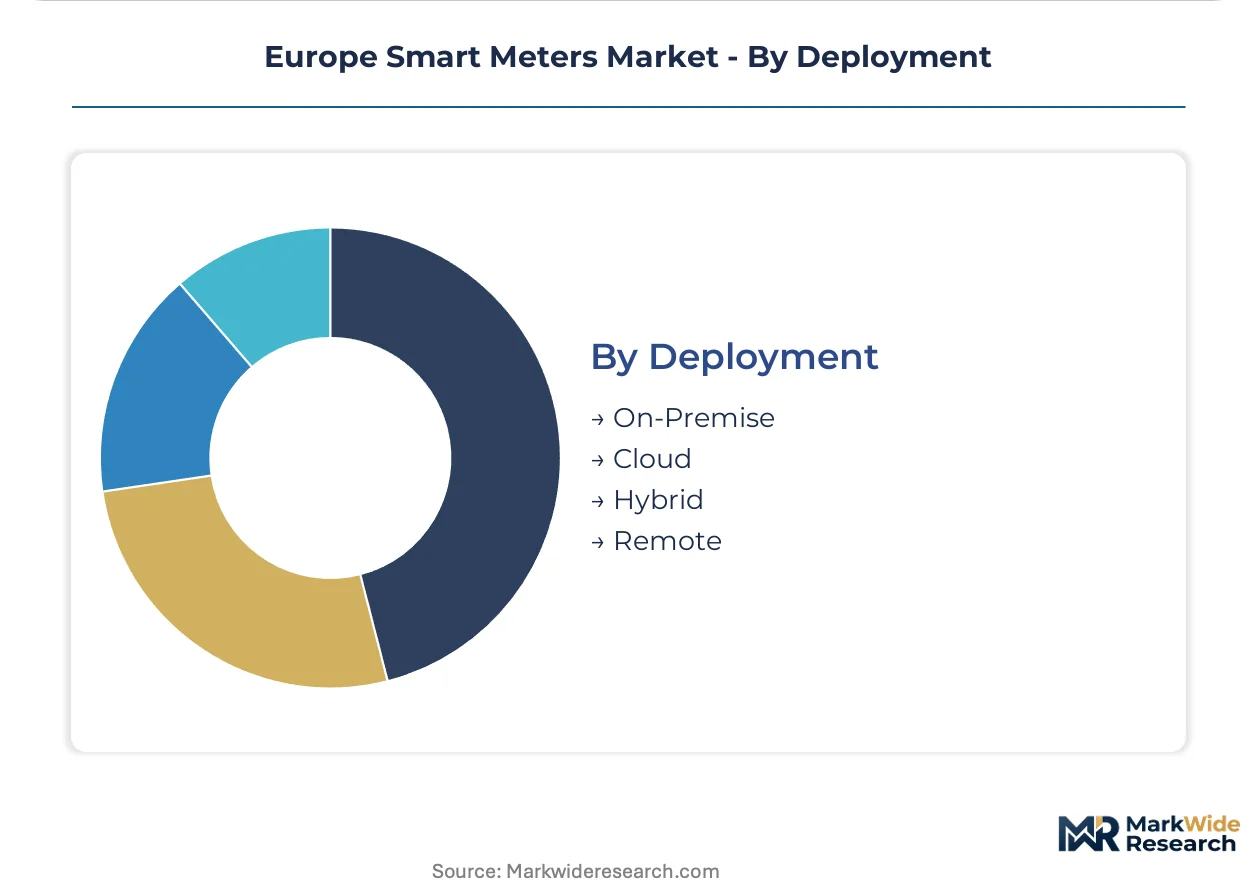
Deployment:
Customer type preferences split across IT maturity levels, with municipal utilities favoring on-premise control and multi-national operators accepting cloud economics.
- On-Premise:Head-end software and meter data management systems operate within utility-owned data centers. German municipal utilities insist on local infrastructure for GDPR data sovereignty compliance.
- Cloud:SaaS meter data platforms reduce capital expenditure and accelerate deployment timelines. British and Nordic utilities lead cloud adoption for multi-tenant scalability.
- Hybrid:Edge-computing meters process time-critical functions locally while transmitting aggregates to central cloud systems. French distribution operators pilot hybrid architectures for GDPR-compliant data localization.
- Remote:Fully managed service models outsource installation, maintenance, and data analytics to meter providers. Italian utilities contract ten-year managed service agreements to accelerate AMI rollout velocity.
On-premise systems retain share in privacy-sensitive segments while hybrid architectures climb fastest as cybersecurity requirements harden under the EU Cybersecurity Act.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows within Europe smart meters tilt toward intra-regional trade, with Swiss and German engineering bases supplying precision hardware to French and Italian utilities executing mass rollout programs. Component sourcing from Asian foundries creates dependency, yet final assembly and software integration concentrate in Central European industrial clusters.
Germany
BNetzA mandates require 80% smart meter coverage by 2030, driving demand for bidirectional electric meters that integrate distributed solar assets. The EU Green Deal's energy efficiency directives accelerate replacement timelines for legacy AMR infrastructure. Bavarian industrial zones host manufacturing facilities supplying AMI communication modules to municipal utilities across the Rhine-Ruhr metropolitan region.
France
CRE enforcement of Linky smart meter deployment targets 35 million installations, prioritizing RF mesh networks with cellular backhaul for rural coverage. The EU Cybersecurity Act mandates cryptographic certification for all network-connected devices entering the French grid. The Île-de-France region concentrates software development for head-end systems managing Paris metropolitan demand-response programs.
Italy
Enel's Telegestore platform expansion requires second-generation meters with enhanced grid-edge computing for voltage monitoring on solar-heavy distribution feeders. National regulators align with EU F-Gas Regulation restrictions on meter manufacturing materials. Lombardy-based system integrators deploy hybrid cloud architectures for GDPR-compliant data localization in Milan industrial corridors.
Spain
Iberdrola and Endesa prioritize AMI deployments for distributed energy resource balancing as photovoltaic penetration strains Mediterranean grid infrastructure. The EU REACH compliance framework governs substance restrictions for circuit boards in Spanish-manufactured meters. Catalan technology clusters develop ultrasonic sensing modules for water metering retrofits in Barcelona's dense urban core.
Poland
National regulators finalize smart metering frameworks that lag Western European penetration by approximately ten percentage points, unlocking mass deployment contracts for 2025-2030. CE marking requirements align Polish product standards with EU single market access rules. The Silesian industrial basin attracts component assembly investments serving Eastern European retrofit markets.
Europe Smart Meters Market Competitive Landscape
Concentration sits with integrated platform providers that bundle hardware, software subscriptions, and managed services under long-term contracts. The supplier base organizes into three tiers: multinational conglomerates with grid-edge software capabilities, specialized metering manufacturers with regional manufacturing footprints, and component suppliers focused on communication modules and sensing elements. Competitive dynamics favor vertical consolidation through strategic partnerships between meter producers and cloud infrastructure providers, alongside geographic expansion into underpenetrated Eastern European markets.
Among Swiss and German engineering specialists, Landis+Gyr and Siemens occupy positions exemplifying the integrated platform archetype, combining precision hardware manufacturing with software-defined grid management capabilities. Kamstrup represents the climate-specialized tier, with Danish engineering heritage positioning it for Nordic water metering specifications requiring cold-climate accuracy. These three anchors illustrate how regional manufacturing proximity to end-use utilities shapes procurement decisions under EU localization preferences.
| Leading Market Players |
|---|
| Xylem |
| Siemens |
| Landis+Gyr |
| Sagemcom |
| Schneider Electric |
| Itron Inc. |
| Honeywell International |
| Diehl Metering |
| Kamstrup |
| Others |
Supply & Pricing Matrix
Ultrasonic sensing modules displacing mechanical measurement assemblies are redrawing component sourcing maps toward Nordic engineering clusters while compressing unit economics for precision meter classes. This substitution simultaneously elevates material costs for piezoelectric ceramics and specialized ASICs while reducing downstream calibration service revenue as solid-state designs extend maintenance intervals.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Europe Smart Meters Market. Premium tiers command certification-grade positioning through EU Cybersecurity Act pre-qualification and MID accuracy class 0.2S, while standard segments compete on volume scale and economy tiers serve Eastern European retrofit budgets. Pricing pressure stems from municipal utilities consolidating procurement into ten-year total-cost-of-ownership contracts that compress hardware margins in favor of recurring software subscriptions. Residential segment buyers exhibit highest price sensitivity due to standardized specifications, whereas utility-grade deployments show lowest sensitivity given grid-sensor instrumentation requirements.
Supply Chain Analysis
Extended lead times for metering-grade microcontrollers and RF transceivers signal inventory strain concentrated in Taiwanese and South Korean foundry capacity. European meter manufacturers draw from German precision component clusters for current transformer cores, Swiss RF module assembly, and Chinese PCB substrate supply. Single-source vulnerability sits with concentrated Asian semiconductor fabrication for AMI communication chipsets. Distribution runs through direct utility procurement channels and systems integrator partnerships, bypassing traditional wholesale electrical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of field engineers certified for EU Cybersecurity Act meter commissioning is constraining deployment velocity and inflating service premiums across France and Italy. This capability gap favors suppliers with captive installation workforces over hardware-only vendors.
For Market Incumbents: Secure backward integration into AMI communication module production to offset semiconductor supply concentration and stabilize delivery timelines. Lock in ten-year managed service contracts with Italian and Spanish distribution operators before certification backlogs ease. Defend against integrated platform competitors by bundling edge-computing firmware subscriptions with hardware procurement. For New Entrants and Emerging Players: Post-installation analytics and predictive maintenance services represent an underserved layer where incumbents under-serve municipal utilities lacking internal data science capabilities. Target Polish and Romanian mass rollout programs where regulatory frameworks are finalizing and incumbent relationships remain unconsolidated. Enter through ultrasonic water metering specialization for Nordic cold-climate specifications where Danish engineering heritage creates procurement preference. For Investors and Strategic Acquirers: The market sits at a regulatory-mandate acceleration phase that favors vertically integrated platform providers over component specialists. Long-term viability across the next decade rests on recurring software revenue attachment rates rather than hardware shipment volumes. Monitor EU Cybersecurity Act certification backlogs at notified bodies as the inflection signal—clearing delays indicate imminent procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AMI Communication Module Backward Integration | Captive semiconductor supply hedges Taiwanese foundry concentration risk for German meter producers. |
| Managed Service Contract Structuring | Ten-year subscription bundling locks Italian utilities into recurring revenue streams beyond hardware margins. |
| Ultrasonic Water Metering Specialization | Solid-state accuracy certification opens Nordic retrofit specifications against mechanical incumbent base. |
| Hybrid Cloud Architecture Development | Edge-computing meter design addresses French GDPR data localization requirements for distribution operators. |
| Cybersecurity Pre-Certification Investment | Early Common Criteria evaluation accelerates procurement timelines with Spanish grid operators. |
Research Methodology
The analysis maps electric, water, gas, and multi-utility meter sub-sectors, each validated through utility procurement directors, AMI systems integrators, and meter manufacturer product strategists. Primary fieldwork combined with secondary validation against EU regulatory filings, national rollout progress reports from BNetzA and CRE, and ECHA REACH substance restriction databases. Bottom-up installation forecasts triangulated against top-down Green Deal mandate targets across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology tier, deployment architecture, and end-user class. CAGRs derived from regulatory-mandated installation quotas, replacement cycle assumptions, and technology substitution curves. Forecast inputs incorporated semiconductor lead time trajectories and utility capital expenditure survey data.
Underlying assumptions cover binding national rollout quotas, EU Cybersecurity Act enforcement timelines, and foundry capacity normalization, with deviation risk concentrated in regulatory deadline extensions or trade restriction escalations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Utility Solutions Market
Smart Meters
Smart Water Metering Market
Smart Meters
Power Metering Market
Smart Meters
North America Smart Meters Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Home Energy Monitor Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Watt Meter Market
Smart Meters
North America Gas Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Smart Gas Metering Market