
 Global Energy and Power Quality Meters Market | 2026-2036
Global Energy and Power Quality Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy and Power Quality Meters Market Intelligence
A shift from single-source to multi-source procurement for advanced metering hardware is rebalancing competitive dynamics among utilities and large industrial consumers. Schneider Electric leverages its extensive distribution network and broad portfolio to secure large-scale contracts. Siemens differentiates its offerings by integrating power quality meters with its comprehensive industrial automation and digitalization platforms. ABB specializes in high-precision meters tailored for demanding sectors like renewable energy integration and data centers.
Energy and power quality meters are electronic devices designed to measure and record electricity consumption and diagnose disturbances in an electrical system. These instruments monitor parameters like voltage sags, swells, harmonics, and flicker, often with sampling rates exceeding 256 samples per cycle. While three-phase meters dominate industrial and utility end-user segments, the smart technology segment represents the fastest-growing category. Within applications, power quality analysis is gaining share over basic energy monitoring due to grid complexity.
Grid interconnection standards, such as IEEE 1547 in the United States and EN 50160 in Europe, mandate specific power quality monitoring capabilities. Energy efficiency directives like the EU Green Deal and China's dual carbon goals promote sub-metering in commercial and industrial facilities. Vendor selection increasingly depends on the ability to provide software and analytics that translate raw meter data into actionable grid management insights.
Market Dynamics
The imperative for grid stability amid rising distributed energy resource integration and the non-negotiable uptime requirements of data centers are the central forces driving the market for advanced energy and power quality meters.
Growth Catalysts
- Smart Grid Modernization:The proliferation of smart grid infrastructure, guided by standards like IEEE 1547 in the US, necessitates advanced metering to manage bidirectional energy flows from distributed energy resources.
- Decarbonization Policies:Germany's Energiewende and China's dual carbon goals compel industrial users to install meters for monitoring energy efficiency, driving demand in manufacturing.
- Mission-Critical Uptime:Data centers and hospitals require precise power quality monitoring to ensure operational continuity, creating a specific demand vector for high-sampling-rate meters.
Market Restraints
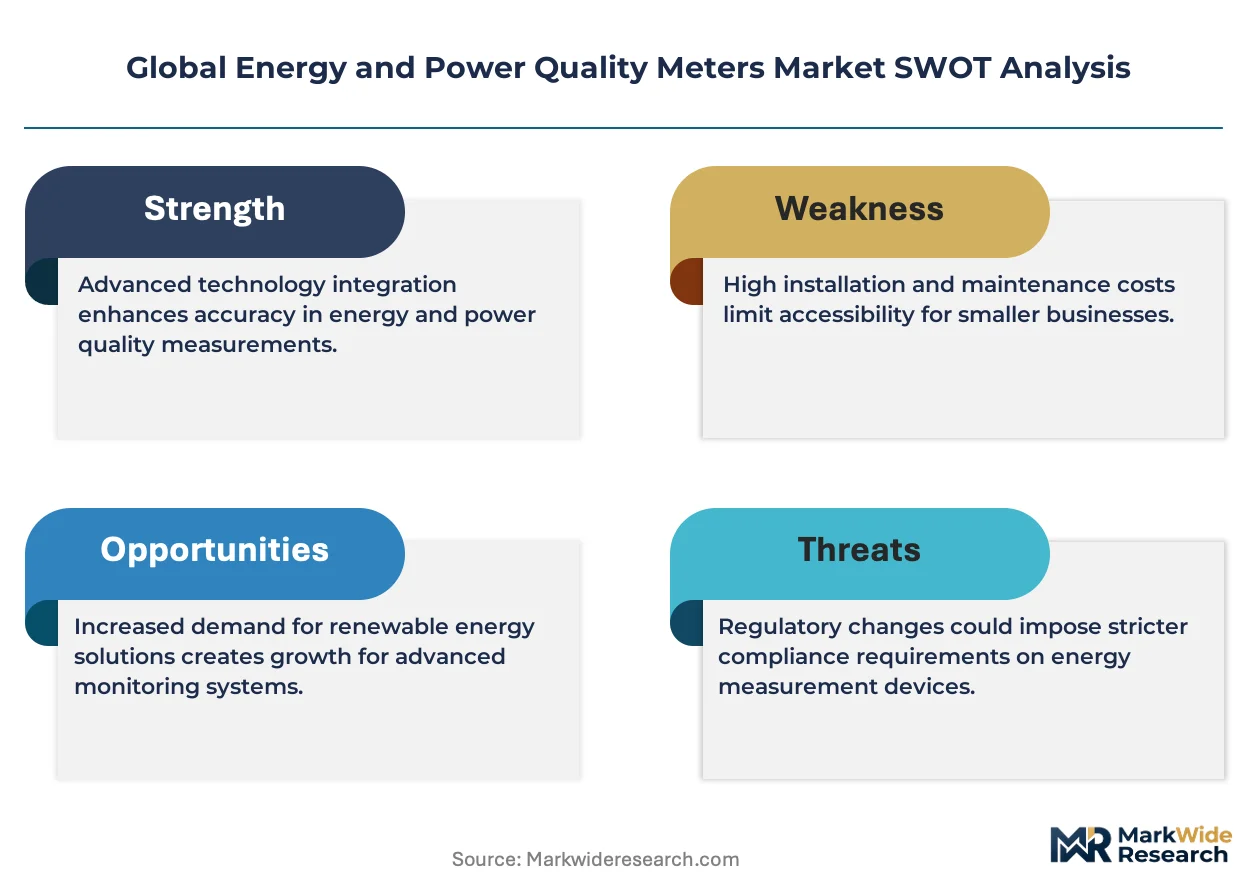
- High Initial Cost:The significant capital expenditure for deploying advanced three-phase meters and software presents a barrier for smaller industrial facilities and commercial buildings without clear ROI mandates.
- Legacy System Interoperability:Integrating new IP-based meters with older, proprietary utility SCADA systems and billing platforms creates significant technical friction, delaying deployment schedules.
- Specialized Component Bottlenecks:The supply of high-precision analog-to-digital converters, concentrated among a few semiconductor firms, creates vulnerability to supply chain disruptions and price volatility.
Strategic Opportunities
- Analytics-as-a-Service:Developing cloud-based software that translates raw meter data into actionable insights for predictive maintenance and grid management offers a significant value-add over hardware sales.
- Sub-metering for ESG Reporting:Growing requirements for granular energy data for corporate reporting, driven by regulations like the EU's CSRD, opens new applications in commercial real estate.
- Grid Modernization in Southeast Asia:Upgrading electrical grids in industrializing nations like Vietnam and Indonesia presents a large, underpenetrated market for scalable and cost-effective metering solutions.
Industry Challenges
- Cybersecurity of Networked Devices:Securing vast networks of internet-connected meters from cyberattacks is a critical operational challenge for utilities, requiring constant investment in advanced threat detection.
- Analytics Skill Gap:A shortage of power systems engineers with data science skills hinders the ability of end-users to fully leverage complex datasets from modern meters.
- Interoperability with Legacy Systems:Ensuring seamless integration between new meters and existing energy management information systems remains a persistent and costly challenge for facility managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy and Power Quality Meters Market |
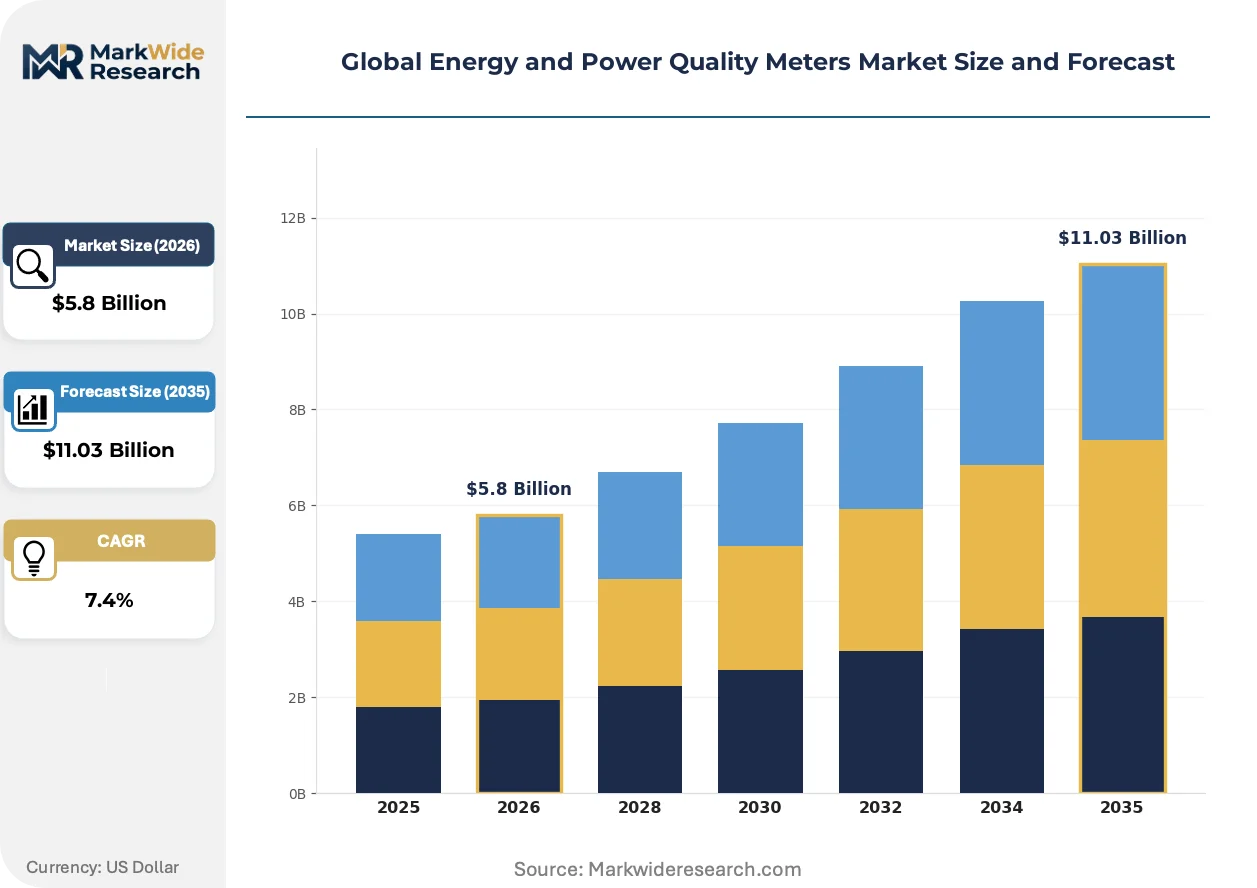
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Meters, Three-Phase Meters, Portable Meters, Permanent Meters Technology: Electromechanical, Electronic, Smart, Digital, Solid State Application: Energy Monitoring, Load Management, Power Quality Analysis, Demand Response, Power Factor Correction End User: Utilities, Renewable Generators, Manufacturing Plants, Commercial Facilities, Data Centers |
| Companies Covered | Schneider Electric, Siemens, ABB, Eaton, GE Vernova, Emerson Electric, Fluke Corporation, Honeywell International, Accuenergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy and Power Quality Meters Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from hardware-centric sales to data-driven services. This transition places a premium on software, analytics, and the ability to integrate meter data into broader operational intelligence platforms.
Edge computing capabilities are being integrated directly into advanced meters. These onboard processors analyze power quality data locally, identifying events like sags or harmonics in real-time. Utilities and data center operators adopt this to reduce network latency, and this capability is rewriting the value proposition from simple measurement to real-time grid control.
China's dual carbon goals are mandating stringent energy efficiency monitoring across heavy industry and large commercial facilities. This policy stimulates investment in sub-metering and power quality analyzers to track performance and comply with emissions targets. Industrial zones in Jiangsu and Guangdong are seeing the most significant uptake to meet these directives.
A move toward subscription-based Metering-as-a-Service models alters traditional procurement cycles. This opex-friendly approach allows customers to access advanced metering and analytics without a large upfront capital investment. This trend is most visible in competitive electricity markets across Europe and North America where facility managers seek flexible solutions.
Global Energy and Power Quality Meters Market Segmentation
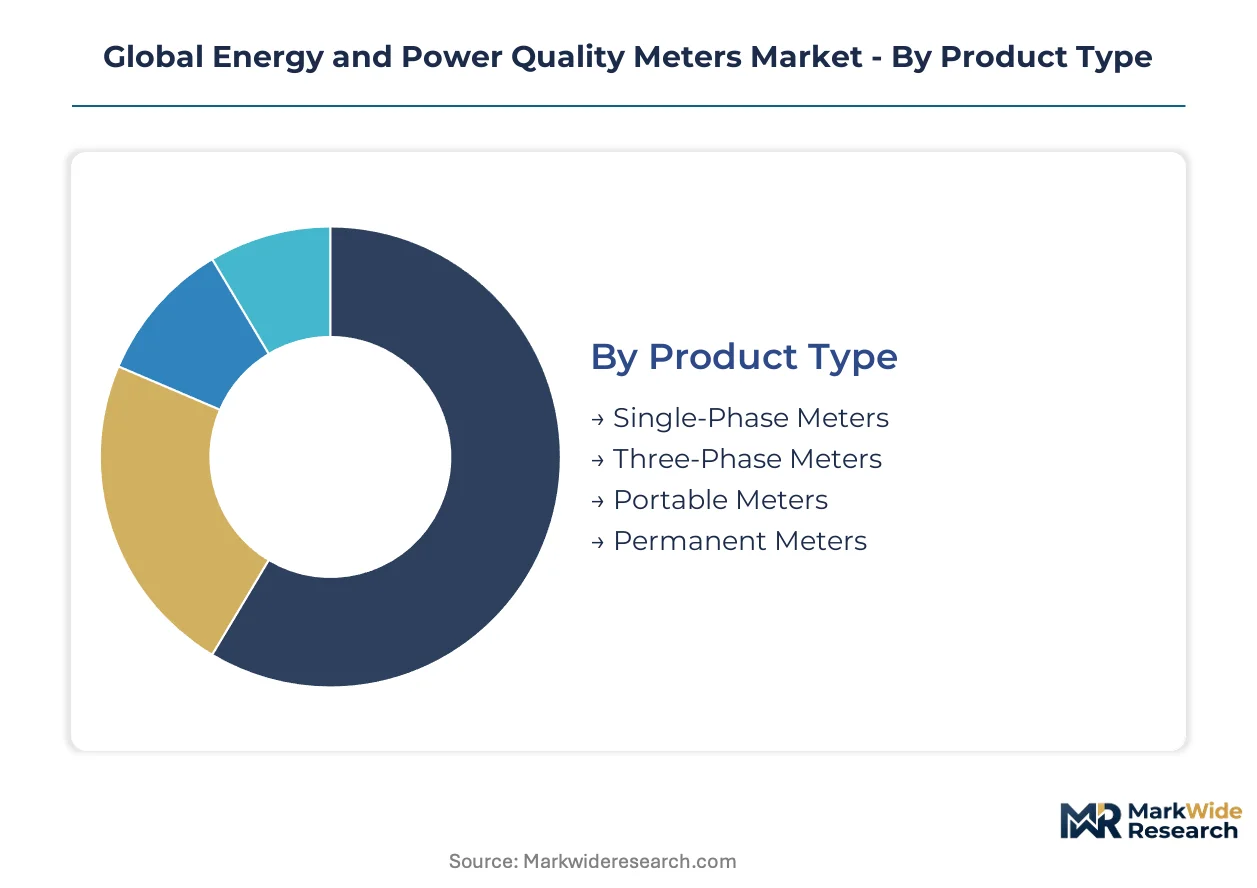
Market segmentation provides a granular understanding of the diverse demands driving the global energy and power quality meters market. Distinct customer needs, technological advancements, and regulatory environments shape the adoption patterns across various product types, technologies, applications, and end-user sectors. This analysis helps identify specific growth pockets and evolving requirements for advanced metering solutions.
Product Type:
Product type segmentation reflects the varying certification burdens required for deployment, from basic safety standards to complex grid interconnection protocols.
- Three-Phase Meters:These devices monitor alternating current in industrial and utility environments, crucial for balancing loads and detecting anomalies across three conductors. Demand concentrates in large manufacturing facilities in Germany and utility substations across the United States, driven by grid stability mandates.
- Portable Meters:Designed for temporary diagnostic work and troubleshooting, these handheld or mobile units offer flexibility for on-site power quality assessments. Demand is high among field service technicians and energy auditors in commercial facilities in France and industrial zones in India, addressing transient grid issues.
- Single-Phase Meters:These meters measure electricity consumption for residential and small commercial applications, meeting basic billing requirements.
- Permanent Meters:Fixed installations provide continuous monitoring of electrical parameters in critical infrastructure like data centers and hospitals.
Leading the category by volume: Single-Phase Meters. Growing fastest: Portable Meters.
Technology:
Technology segmentation illustrates the diverse cost tiers and performance capabilities available, from foundational measurement to advanced real-time analytics.
- Smart:These advanced meters integrate communication modules for remote data transmission and often include edge computing capabilities for local data processing. Demand accelerates in smart grid modernization projects across Japan and for distributed energy resource integration in Australia.
- Electronic:Utilizing solid-state components, electronic meters offer improved accuracy and reliability over older designs for energy measurement. Utilities in the United Kingdom and commercial buildings in Canada increasingly adopt these for billing and sub-metering.
- Digital:Digital meters provide precise readings and often feature LCD displays for local data visualization.
- Solid State:Solid-state meters lack moving parts, ensuring long-term stability and reduced maintenance needs.
- Electromechanical:These traditional meters use rotating discs to measure energy, offering a cost-effective solution for basic monitoring.
The market sees Electromechanical solutions maintaining a foundational presence, while Smart technology drives innovation in grid intelligence.
Application:
Application segmentation highlights the specific operational challenges that energy and power quality meters address across various electrical systems.
- Power Quality Analysis:This application involves diagnosing disturbances like voltage sags, harmonics, and flicker, critical for protecting sensitive equipment. Data centers in the United States and high-tech manufacturing in South Korea prioritize this for uptime assurance.
- Energy Monitoring:Basic energy monitoring tracks electricity consumption for billing and efficiency management across diverse facilities. Commercial real estate in Germany and industrial complexes in China utilize this for compliance with energy efficiency directives.
- Load Management:Load management applications optimize energy consumption by balancing demand across different circuits.
- Demand Response:Demand response uses metering data to adjust energy usage in response to grid conditions or price signals.
- Power Factor Correction:This application measures and improves power factor, reducing energy losses in industrial settings.
While Energy Monitoring remains a core function, Power Quality Analysis is gaining share due to increasing grid complexity.
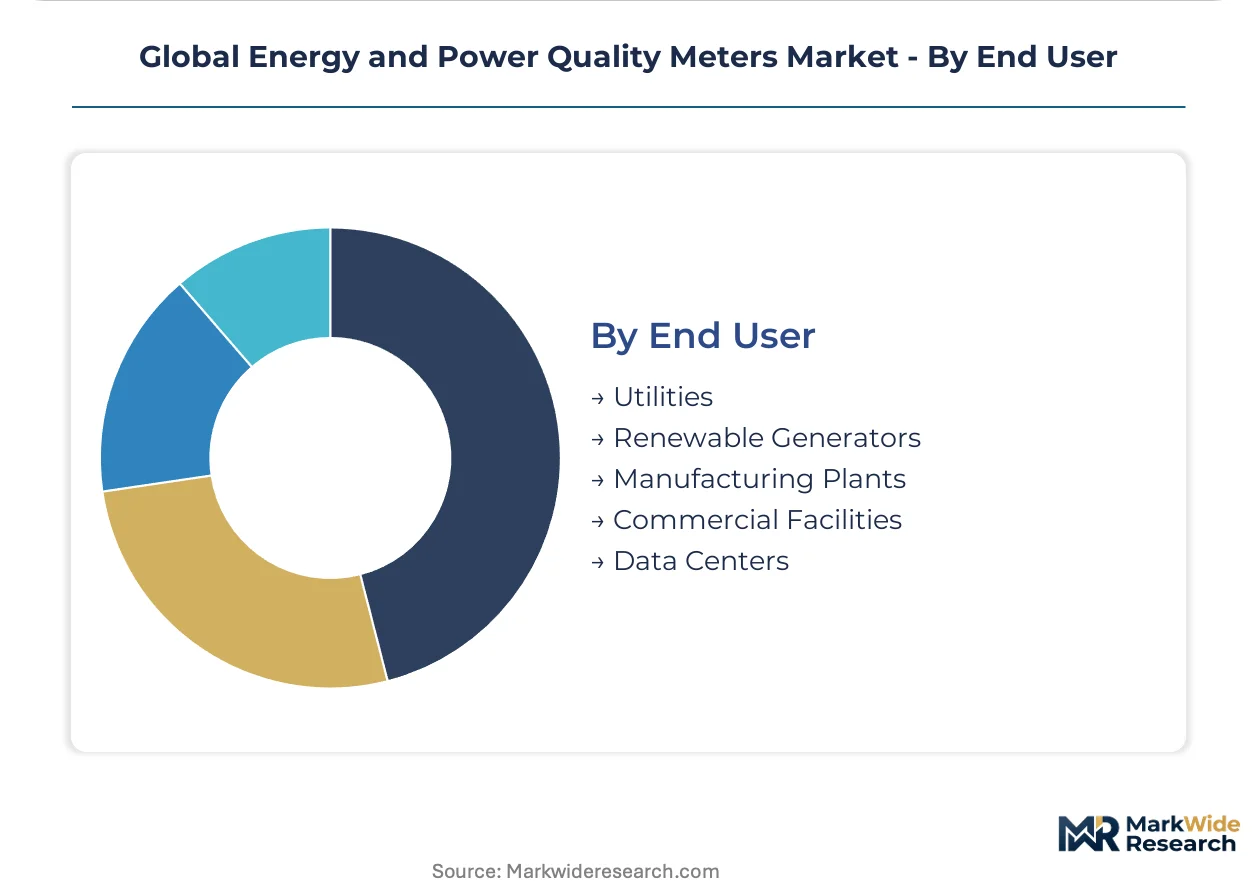
End User:
End user segmentation delineates the distinct operational environments and regulatory compliance needs driving meter adoption across industries.
- Utilities:Utility companies deploy meters for revenue metering, grid management, and compliance with interconnection standards like IEEE 1547. National grids in the United States and state utilities in India represent significant procurement entities.
- Data Centers:These mission-critical facilities demand continuous power quality monitoring to prevent downtime and protect sensitive IT infrastructure. Major data center operators in Ireland and Singapore invest heavily in high-sampling-rate meters.
- Manufacturing Plants:Manufacturing plants use meters for energy efficiency monitoring and managing electrical loads to optimize production.
- Commercial Facilities:Commercial buildings utilize meters for sub-metering, tenant billing, and ESG reporting requirements.
- Renewable Generators:Renewable energy sites deploy meters for monitoring output, grid compliance, and managing bidirectional power flows.
Utilities represent the largest end-user segment by scale, while Data Centers exhibit the most specialized requirements for power quality assurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for energy and power quality meters is particularly pronounced in Germany, driven by its ambitious Energiewende policy and robust industrial sector. This regional focus underscores the influence of national energy policies on advanced metering solutions. Diverse regulatory frameworks across key economies accelerate the deployment of these critical devices.
Germany
Germany's robust industrial sector drives significant demand for advanced energy monitoring to meet decarbonization targets. The nation's Energiewende policy mandates stringent energy efficiency measures across large manufacturing facilities. Industrial complexes in Bavaria actively implement sub-metering solutions for operational optimization and regulatory compliance.
United States
The United States market sees demand from mission-critical data centers for continuous power quality monitoring. Grid interconnection standards like IEEE 1547 necessitate advanced metering for distributed energy resources. Data center clusters in Virginia and utility substations across Texas upgrade systems for enhanced grid stability.
China
China's heavy industry and commercial facilities require stringent energy efficiency monitoring. The nation's dual carbon goals stimulate investment in sub-metering and power quality analyzers. Industrial zones in Jiangsu and Guangdong are seeing significant uptake to meet these directives.
Japan
Japan's smart grid modernization projects accelerate the demand for advanced metering technology. METI directives support the integration of distributed energy resources into the national grid. Utilities like Tokyo Electric Power Company (TEPCO) implement smart meter deployments across urban centers.
India
India's rapidly expanding industrial base and utility infrastructure require enhanced energy monitoring. The Central Electricity Authority (CEA) issues regulations for grid stability and power quality. Industrial zones in Maharashtra and state utilities across Uttar Pradesh procure new metering solutions.
Global Energy and Power Quality Meters Market Key Industry Players
Strategic partnerships and portfolio diversification dominate the current landscape for energy and power quality meters. The market exhibits a tiered structure, encompassing global industrial conglomerates and specialized technology providers. Integrated automation providers, high-precision specialists, and broad distribution network players represent key strategic archetypes. Geographic expansion and technology integration are dominant competitive moves among market participants.
Within the integrated automation provider tier, Siemens AG exemplifies a strategy of combining power quality meters with comprehensive industrial automation and digitalization platforms. Schneider Electric SE, a French multinational corporation, represents broad distribution network capabilities and extensive product portfolios. ABB Ltd., a Swiss-Swedish multinational, occupies a position as a high-precision specialist, tailoring meters for demanding sectors like renewable energy integration and data centers.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| Eaton |
| GE Vernova |
| Emerson Electric |
| Fluke Corporation |
| Honeywell International |
| Accuenergy |
Cost & Logistics Intelligence
Integration of edge computing capabilities directly into advanced meters simultaneously reshapes cost economics and supply concentration for real-time processing components. This shift places a premium on specialized semiconductor firms and their manufacturing ecosystems.
Pricing Analysis
Warranty and service bundling increasingly differentiate offerings, moving beyond basic per-unit transactional pricing models. The dominant pricing structure transitions towards subscription-based Metering-as-a-Service, especially in competitive electricity markets. Price differentiation stems from certification levels, such as IEEE 1547 compliance, and the sophistication of integrated software analytics platforms. Pricing pressure stems from the high initial capital expenditure for advanced three-phase meters, particularly affecting smaller industrial facilities. Data centers, however, exhibit lower price sensitivity due to non-negotiable uptime requirements.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming standard practice among large utilities and industrial consumers. Supply concentration for high-precision analog-to-digital converters primarily sits in Taiwan and South Korea. Raw material dependencies center on specialized silicon and rare earth elements for advanced sensors. A structural risk is vulnerability to supply chain disruptions and price volatility for these specialized components. Distribution runs through extensive global networks maintained by industrial conglomerates and specialized technology providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, with regulations like the EU Green Deal creating a significant barrier-to-entry moat for compliant players.
For Market Incumbents: Anchor product development in comprehensive software and analytics platforms that translate raw meter data into actionable grid management insights. Pursue strategic partnerships to expand geographic distribution, particularly in industrializing nations like Vietnam. Invest in R&D for advanced cybersecurity features to protect networked devices, addressing a critical operational challenge for utilities. Consolidate market share by offering integrated solutions that simplify deployment for large industrial consumers.
For New Entrants and Emerging Players: Begin with a focus on niche opportunities like sub-metering for ESG reporting in commercial real estate, driven by regulations like the EU's CSRD. Target grid modernization initiatives in Southeast Asia, offering scalable and cost-effective metering solutions for underpenetrated markets. Develop cloud-based Analytics-as-a-Service models to provide an opex-friendly alternative to large upfront capital investments. Penetrate the market by offering interoperable solutions that ease integration with legacy utility SCADA systems.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized software and analytics firms that enhance the value proposition of hardware. The long-term viability of the market is anchored in the imperative for grid stability and decarbonization goals over the next decade. Acquisition targets should include companies with strong intellectual property in edge computing capabilities for real-time power quality analysis. A signal to watch for inflection is a widespread shift towards Metering-as-a-Service models across developed economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Analytics-as-a-Service platforms | Translates raw meter data into actionable grid management insights for utilities. |
| Expand sub-metering solutions for ESG reporting | Addresses granular energy data requirements for commercial real estate under EU's CSRD. |
| Invest in edge computing for real-time analysis | Reduces network latency for data centers, enabling real-time grid control. |
| Form strategic partnerships for smart grid deployments | Accelerates market penetration in regions like Japan with smart grid modernization projects. |
| Secure long-term supply agreements for critical components | Mitigates vulnerability to supply chain disruptions for high-precision analog-to-digital converters. |
Research Approach
Multi-period observation of smart grid investment trends and decarbonization policy impacts anchored the trend analysis, supplemented by interviews with utility planning officers, data center facility managers, and industrial plant engineers. Primary insights were triangulated against secondary data from IEEE standards documents, national energy policy reports like the EU Green Deal, and semiconductor industry reports. This approach combined bottom-up market sizing with top-down validation.
The segment-weighting approach calibrated the quantitative model across the analysis window, integrating various data points for product type, technology, application, end-user, and regional policy impact. Compound Annual Growth Rates (CAGRs) were derived by projecting demand drivers such as smart grid investment budgets and data center expansion plans. The analytical framework also incorporated anticipated timelines for decarbonization policies.
Underlying measurement precision varies by segment; three-phase meters and smart technology carry tighter precision than electromechanical solutions. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Deviation in specialized component supply or grid modernization project delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Power Monitoring System Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
Digital Gas Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Solar Meter Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Power Quality Meter Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Smart Water Metering Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
North America Gas Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market