
 Middle East and Africa Energy Management Systems Market | 2026-2036
Middle East and Africa Energy Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Energy Management Systems Market Foresight
Commercial building portfolios across the Middle East and Africa Energy Management Systems landscape are pivoting toward integrated digital platforms as landlords face escalating utility costs and tenant sustainability requirements. Schneider Electric SE leverages its regional service network to anchor long-term facility management contracts in Gulf commercial towers. Honeywell International Inc. competes through building automation convergence, bundling HVAC control with energy analytics for mixed-use developments. Siemens AG differentiates via grid-edge software that connects district cooling systems to utility demand-response programs.
Energy management systems encompass software, hardware, and services that monitor, control, and optimize energy consumption across industrial, commercial, and utility infrastructure through real-time data acquisition and automated load scheduling. These platforms typically integrate meter-level granularity with enterprise resource planning systems to curtail peak demand charges and synchronize distributed generation assets. Software segments lead margin capture as recurring SaaS subscriptions replace perpetual licensing in utility and manufacturing deployments. IoT-enabled sensor networks represent the fastest-expanding technology layer, though cloud computing infrastructure underpins scalable analytics for multi-site commercial operators. Demand response applications mature in Gulf Cooperation Council utilities while renewable integration modules gain traction where solar photovoltaic penetration rises.
Saudi Arabia's SFDA coordinates with national energy regulators to enforce industrial efficiency benchmarks, compelling manufacturing facilities to deploy certified monitoring systems. The UAE's MOHAP and Emirates Authority for Standardization and Metrology shape product certification pathways for building energy controls imported into Dubai and Abu Dhabi. South Africa's National Energy Regulator mandates municipal distribution utilities to implement advanced metering infrastructure, directly stimulating hardware procurement. Stakeholders must weigh interoperability standards against proprietary platform lock-in as government procurement rules tighten data sovereignty requirements.
Market Dynamics
Utility digitalization mandates across Gulf Cooperation Council states are forcing industrial and commercial facilities to replace siloed metering with unified data platforms. Saudi Arabia's SFDA efficiency benchmarks and UAE smart city procurement rules compress deployment timelines for integrated monitoring infrastructure.
Growth Catalysts
- Industrial Efficiency Mandates:Saudi Arabia's SFDA coordinates with national regulators to enforce certified monitoring system deployment in manufacturing facilities, compelling capital expenditure on compliant EMS hardware and software.
- District Cooling Integration:Dubai and Abu Dhabi smart city programs require building energy controls to synchronize with utility demand-response frameworks, creating procurement pull for grid-edge software platforms.
- Advanced Metering Infrastructure:South Africa's National Energy Regulator mandates municipal distribution utilities to implement AMI systems, directly stimulating hardware procurement across industrial and commercial substations.
Market Restraints
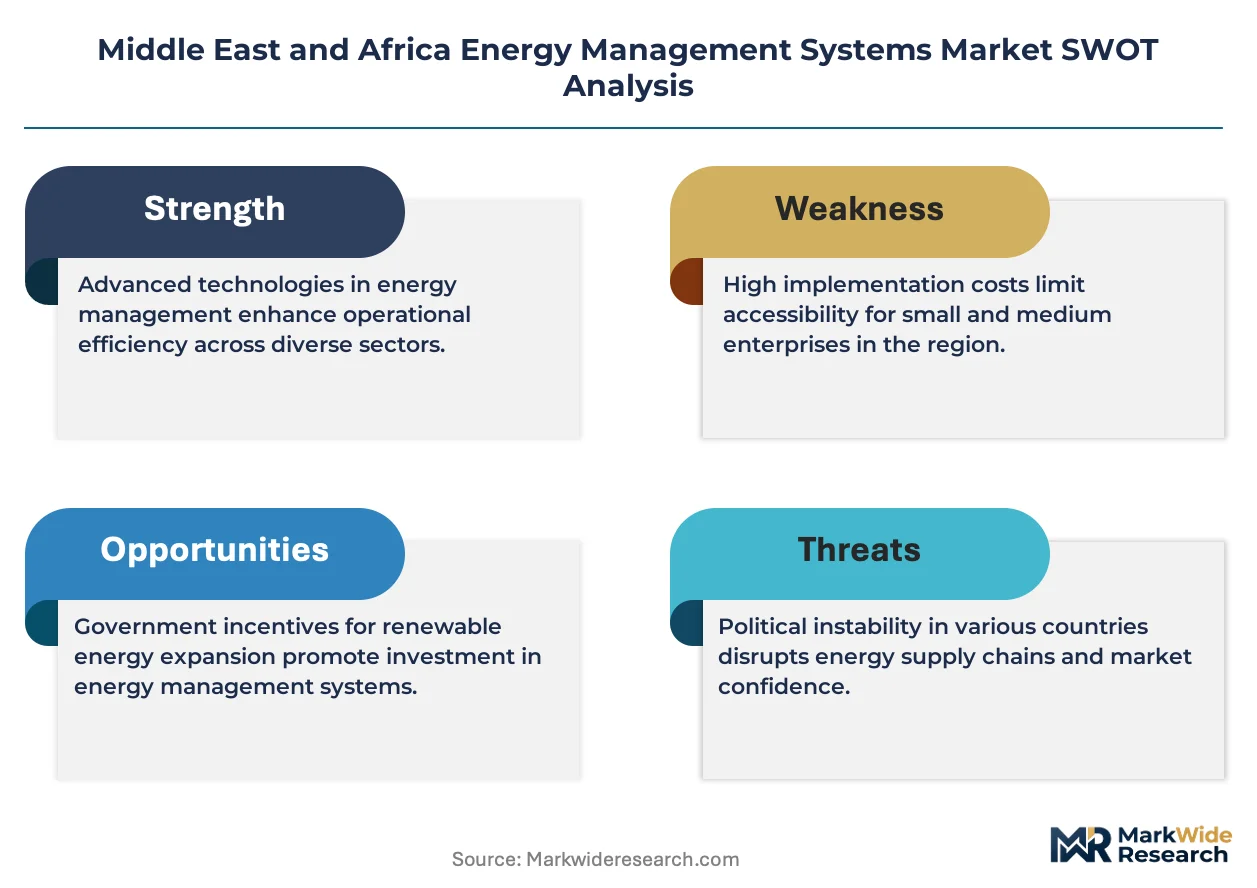
- Semiconductor Supply Concentration:IoT sensor and edge computing component sourcing remains concentrated in East Asian foundries, exposing Middle East and Africa project timelines to shipping volatility and customs delays.
- Proprietary Platform Lock-in:Major automation vendors maintain incompatible data protocols, fragmenting interoperability and forcing buyers into single-source long-term service contracts with limited migration paths.
- Skilled Technician Scarcity:Certified systems integrators capable of deploying IEC-standard industrial IoT networks remain concentrated in UAE and Saudi Arabia, constraining rollout velocity in North and East African markets.
Strategic Opportunities
- Rural Electrification Microgrids:Kenya and Nigeria off-grid solar deployments lack centralized monitoring, creating white space for cloud-native EMS platforms serving distributed generation clusters.
- Data Sovereignty Requirements:UAE and Saudi government procurement rules increasingly mandate local data residency, favoring regional cloud infrastructure providers over hyperscale foreign platforms.
- AI-Driven Predictive Maintenance:Convergence of machine learning analytics with existing SCADA installations enables utilities to defer capital-intensive infrastructure replacement through algorithmic load forecasting.
Industry Challenges
- Legacy System Integration Complexity:Industrial facilities operate decades-old DCS and PLC architectures with proprietary communication stacks, requiring costly middleware development for EMS connectivity.
- Certification Timeline Compression:Emirates Authority for Standardization and Metrology product approval cycles lag behind procurement deadlines for Dubai Expo legacy building retrofits, delaying vendor revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Energy Management Systems Market |
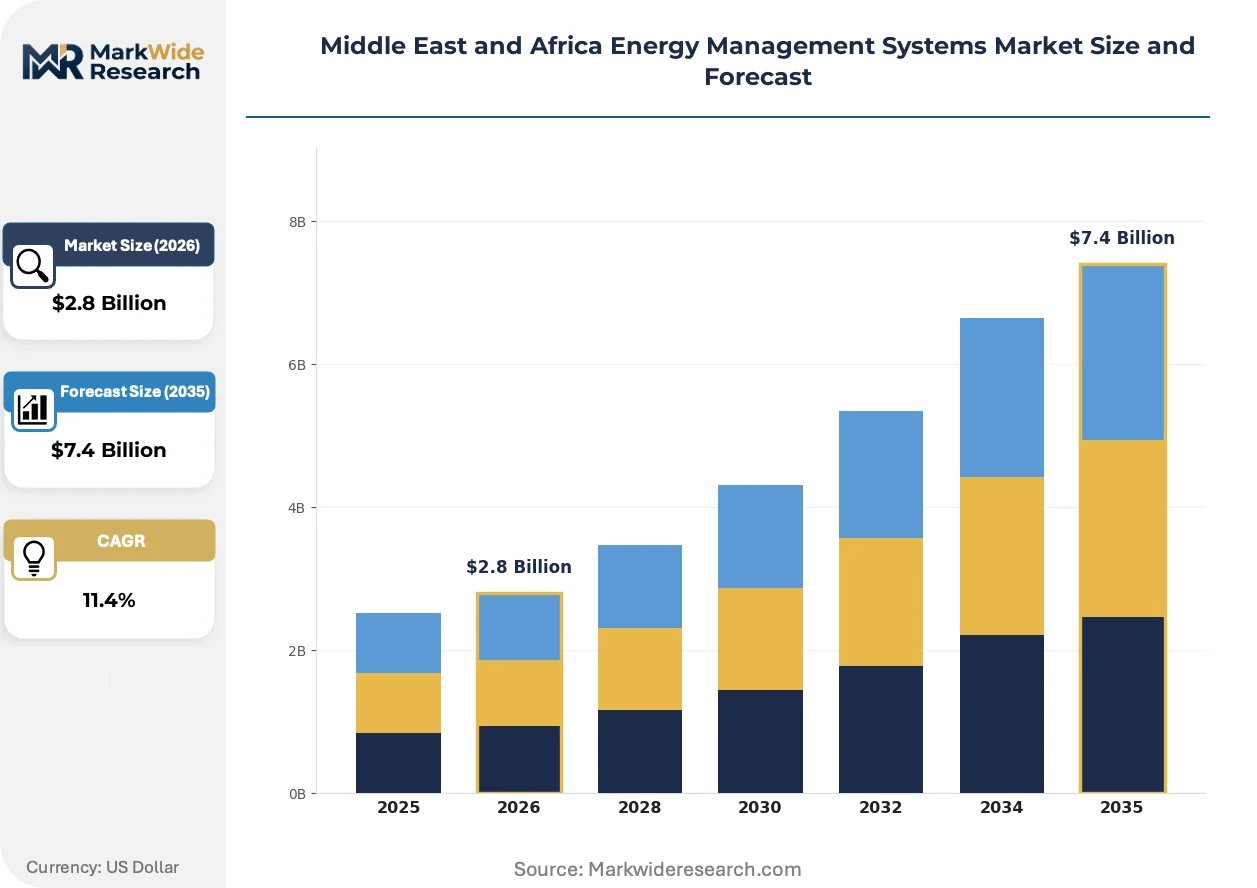
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions End User: Utilities, Manufacturing, Commercial, Residential Technology: IoT, Cloud Computing, Big Data, AI Application: Demand Response, Energy Monitoring, Renewable Integration, Sustainability |
| Companies Covered | Schneider Electric SE, Honeywell International Inc., ABB Ltd., Siemens AG, General Electric Company, Rockwell Automation Inc., Cisco Systems Inc., Johnson Controls International PLC, IBM Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Energy Management Systems Market Shifts & Advancements
Edge computing architectures are displacing centralized SCADA hierarchies across Middle East and Africa utility networks. This shift enables real-time anomaly detection at substation level while reducing bandwidth costs for geographically dispersed infrastructure.
Containerized software deployment is modularizing EMS platform delivery for multi-site commercial operators. Retail and hospitality chains in UAE and Saudi Arabia adopt microservice-based energy analytics that deploy across property portfolios without on-premise server installation. This architecture compresses vendor implementation timelines from quarters to weeks.
Saudi Arabia's SFDA industrial efficiency framework tightens monitoring granularity requirements annually. Manufacturing facilities must now report sub-process energy intensity rather than facility-level aggregates, forcing EMS vendors to retrofit additional sensor layers. Chemical and cement sectors face the steepest compliance ramps.
Facility managers increasingly specify subscription-based SaaS energy analytics over perpetual software licenses. Procurement teams in Gulf commercial real estate favor operational expenditure models that align vendor incentives with sustained efficiency outcomes. This preference shift pressures traditional automation vendors to restructure pricing and service delivery.
Middle East and Africa Energy Management Systems Market Segmentation
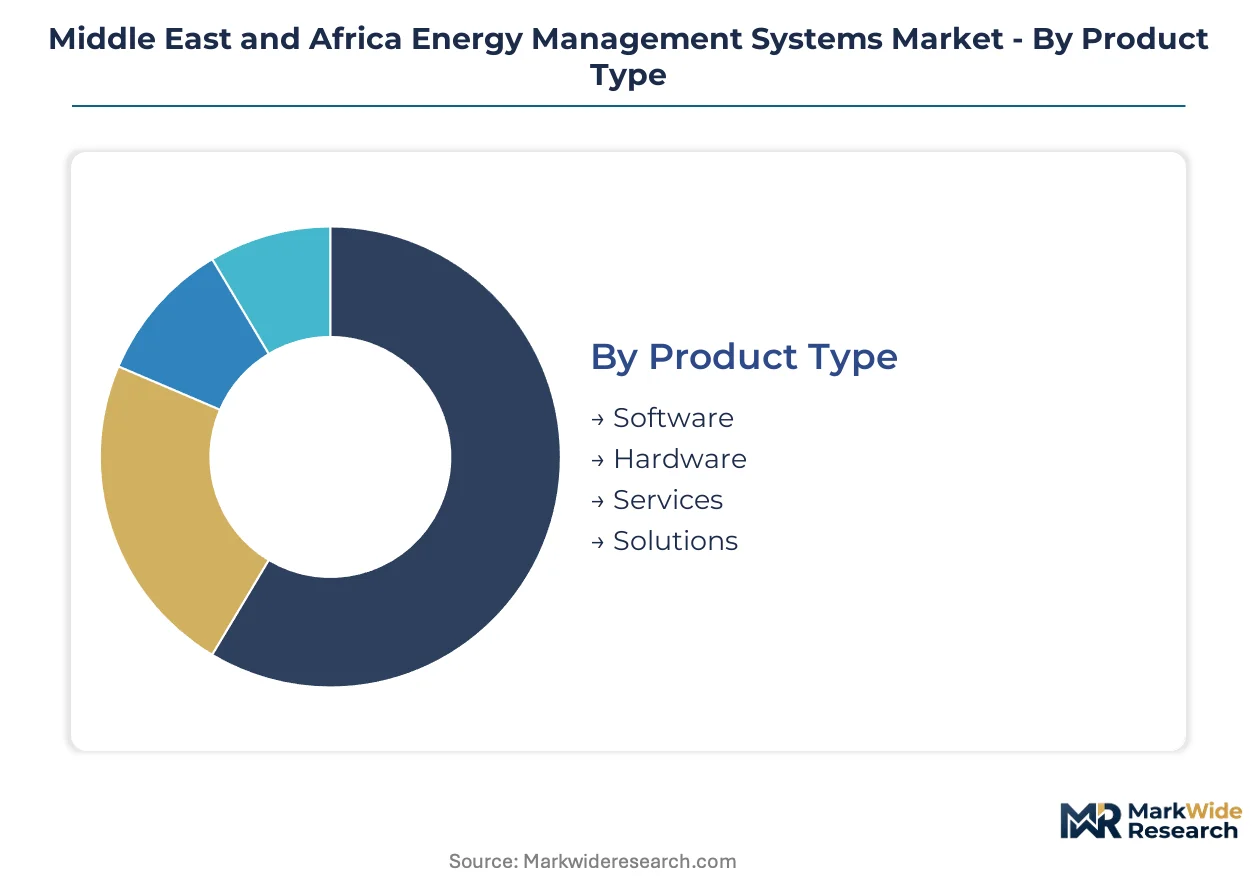
Energy Management Systems vendors in the Middle East and Africa must align product architecture with divergent buyer sophistication. Procurement patterns split between standardized utility-scale deployments and heavily customized industrial integrations.
Product Type:
Customization intensity varies sharply across this category, from configurable SaaS modules to bespoke hardware-software bundles.
- Software:Cloud-native platforms with meter-level data aggregation and automated load scheduling dominate procurement in UAE commercial real estate. Dubai smart city mandates compress implementation timelines, favoring subscription models over perpetual licenses.
- Hardware:Edge computing nodes and industrial IoT sensor networks require field calibration for Saudi Arabia's SFDA-certified monitoring systems. Manufacturing facilities retrofit additional sensing layers to meet sub-process energy intensity reporting requirements.
- Services:Systems integration and ongoing facility management contracts anchor long-term vendor relationships in Gulf commercial towers.
- Solutions:Bundled hardware-software-service packages address district cooling synchronization requirements in Abu Dhabi.
Leading the category by volume: Software. Growing fastest: Hardware.
End User:
Buyer sophistication tiers separate regulated utilities from price-sensitive residential adopters.
- Utilities:Gulf Cooperation Council distribution operators deploy grid-edge software for demand-response program orchestration. South Africa's National Energy Regulator mandates AMI infrastructure, directly stimulating procurement.
- Manufacturing:Saudi Arabia's SFDA efficiency benchmarks compel certified monitoring system deployment in chemical and cement sectors. Sub-process granularity requirements force annual sensor layer retrofits.
- Commercial:Dubai and Abu Dhabi mixed-use developments specify building automation convergence with energy analytics.
- Residential:Kenya and Nigeria off-grid solar clusters lack centralized monitoring, creating white space for cloud-native platforms.
Volume concentrates in Utilities. Steepest expansion trajectory: Manufacturing.
Technology:
Deployment maturity separates established connectivity layers from emerging analytics stacks.
- IoT:Wireless sensor networks with IEC-standard industrial protocols enable real-time anomaly detection at substation level. IoT-enabled deployments expand fastest across geographically dispersed infrastructure.
- Cloud Computing:Regional cloud infrastructure providers gain preference as UAE and Saudi procurement rules tighten data sovereignty requirements. Microservice architectures compress multi-site commercial implementations from quarters to weeks.
- Big Data:Enterprise resource planning integration curtail peak demand charges through historical consumption pattern analysis.
- AI:Machine learning analytics layered onto existing SCADA installations enable algorithmic load forecasting for capital deferral.
Deployment scale favors Cloud Computing. Adoption velocity peaks with AI.
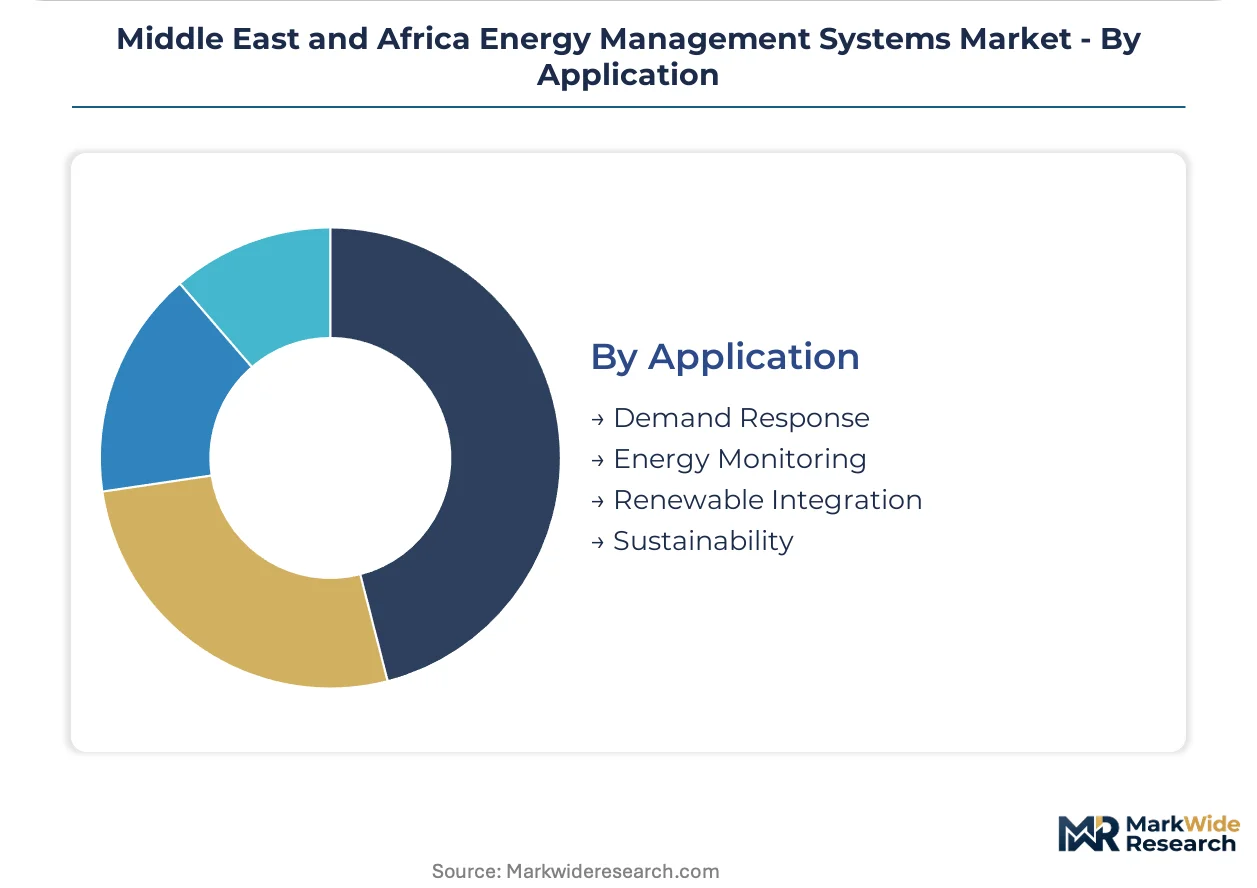
Application:
Use case maturity spans regulatory compliance through voluntary sustainability positioning.
- Demand Response:Dubai and Abu Dhabi building energy controls synchronize with utility frameworks through grid-edge software procurement mandates.
- Energy Monitoring:Saudi Arabia's SFDA sub-process reporting requirements drive manufacturing facility retrofit cycles.
- Renewable Integration:Solar photovoltaic penetration rises across UAE and Saudi Arabia, stimulating module procurement for distributed generation asset synchronization.
- Sustainability:Tenant requirements and landlord cost pressures pivot commercial building portfolios toward integrated digital platforms.
Procurement volume centers on Energy Monitoring. Share gains concentrate in Renewable Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and Saudi Arabia's industrial zones concentrate EMS deployment through SFDA-mandated efficiency programs. The UAE's free trade corridors accelerate procurement timelines for smart building retrofits.
United Arab Emirates
Dubai's smart city mandates and Abu Dhabi's district cooling requirements drive integrated platform procurement. MOHAP and the Emirates Authority for Standardization and Metrology enforce certification pathways for imported building controls. Dubai Expo legacy developments compress vendor implementation schedules for mixed-use towers.
Saudi Arabia
SFDA industrial efficiency benchmarks compel manufacturing facilities to deploy certified monitoring systems with sub-process granularity. National energy regulators tighten reporting requirements annually for chemical and cement sectors. Riyadh and the Eastern Province host the steepest sensor retrofit cycles in heavy industry.
South Africa
The National Energy Regulator mandates advanced metering infrastructure across municipal distribution utilities. Cape Town and Johannesburg industrial zones face procurement deadlines for AMI-compliant substation hardware. Eskom's grid stabilization programs stimulate demand-response software deployment.
Israel
Water-energy nexus management drives precision monitoring in agricultural and desalination facilities. The Ministry of Environmental Protection enforces efficiency standards for industrial cooling systems. Tel Aviv's high-tech corridor incubates edge-computing startups serving utility digitalization projects.
Nigeria
Off-grid solar microgrids in Lagos and Kano lack centralized monitoring infrastructure. Rural electrification agencies prioritize cloud-native platforms for distributed generation clusters. The Niger Delta industrial belt experiments with captive power EMS for oil and gas facilities.
Middle East and Africa Energy Management Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack automation vendors anchoring utility-scale deployments while regional systems integrators capture commercial retrofit work. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with building automation portfolios, pure-play energy software developers, and electrical equipment manufacturers extending into digital services. Competitive positioning hardens through long-term facility management contracts and proprietary protocol ecosystems that complicate customer migration. M&A activity targets regional cloud infrastructure capabilities, while technology licensing agreements accelerate time-to-market for AI-driven analytics modules.
Within the diversified industrial tier, Schneider Electric SE and Siemens AG exemplify full-stack positioning through converged hardware-software-service offerings. Honeywell International Inc. occupies a distinct position bundling HVAC control with energy analytics for mixed-use developments. These three anchors represent contrasting geographic emphases—French and German industrial heritage against American building automation lineage—while each reinforces customer stickiness through incompatible data protocols and multi-year service contracts.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc. |
| ABB Ltd. |
| Siemens AG |
| General Electric Company |
| Rockwell Automation Inc. |
| Cisco Systems Inc. |
| Johnson Controls International PLC |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between SFDA-compliant industrial systems and uncertified commercial platforms manifests in both pricing premiums and supply chain sourcing strategies. Tier-one deployments in Saudi Arabia's chemical sector command substantial markups for sub-process granularity hardware, while standard building automation bundles in UAE commercial towers compete on implementation speed and SaaS conversion rates.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent Gulf Cooperation Council utility procurements from planned manufacturing retrofits. Three-tier pricing structure across premium certified, standard integrated, and economy sensor-only levels reflects SFDA compliance depth and after-sales service bundling. Cost compression in the standard tier intensifies because regional systems integrators compete aggressively for Dubai smart city contracts. Manufacturing facilities face the steepest price sensitivity due to annual sensor layer retrofit mandates, while utilities accept premium pricing to compress AMI deployment timelines.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries supplying industrial IoT sensors and edge computing modules. Component sourcing draws from Taiwan, South Korea, and mainland China for semiconductor-dependent hardware tiers. Raw material dependencies span rare earth magnets for sensor assemblies, lithium-ion cells for backup power systems, and copper for industrial networking infrastructure. Tariff exposure through Red Sea shipping corridors elevates landed cost volatility for UAE and Saudi project sites. Distribution runs through Dubai's Jebel Ali free zone for regional warehousing and forward staging to North and East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics in certified industrial sensor production prop pricing power for vendors with established SFDA approval pathways. Capacity bottlenecks in IEC-standard systems integrator certification constrain rollout velocity and sustain margin premiums.
For Market Incumbents: Acquire regional cloud infrastructure capabilities to satisfy UAE and Saudi data sovereignty procurement rules. Consolidate position through long-term facility management contracts in Gulf commercial towers that complicate customer migration. Defensive priority rests on backward integration into edge computing hardware production to offset East Asian supply volatility. For New Entrants and Emerging Players: Rural electrification agencies in Kenya and Nigeria represent the most penetrable buyer archetype given absence of incumbent service networks. Kenya's off-grid solar microgrids lack centralized monitoring infrastructure and procurement sophistication. White space concentrates in cloud-native SaaS platforms serving distributed generation clusters without on-premise server requirements. Go-to-market leverage hinges on mobile-first deployment models that bypass scarce certified technician constraints. For Investors and Strategic Acquirers: Re-rating potential sits with regional systems integrators achieving SFDA certification given tightening industrial efficiency mandates. Multiple expansion catalyst centers on demonstrated sub-process granularity deployment track records in Saudi chemical and cement sectors. Long-term viability across the analysis window favors acquisition targets with established UAE free zone logistics infrastructure. Signal to monitor: Emirates Authority for Standardization and Metrology approval timeline compression for Dubai Expo legacy building retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Unlocks premium pricing in Saudi chemical and cement sector procurements. |
| Regional Cloud Infrastructure Buildout | Satisfies UAE and Saudi government data residency procurement mandates. |
| Edge Computing Hardware Integration | Reduces bandwidth costs for geographically dispersed utility substations. |
| AI-Driven Predictive Maintenance Module | Enables algorithmic load forecasting for utility capital deferral decisions. |
| Microservice Architecture Deployment | Compresses multi-site commercial implementations from quarters to weeks. |
Research Methodology
Independent corroboration across utility planning officers, EPC contractors, and industrial facility managers underwrites the qualitative findings in this study. Primary fieldwork engaged grid operators, IPP project developers, and fuel supply specialists across Gulf Cooperation Council states and South Africa. Secondary validation drew from EIA data, IEA reports, FERC filings, and project development databases tracking AMI and smart grid investments. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to anchor volume and value estimates.
Rate-of-change decomposition structured the analytical framework across deployment model, organization size, vertical integration depth, and regional regulatory cluster dimensions. CAGRs derived from segmented growth trajectory analysis incorporating technology adoption curves and procurement mandate compliance schedules. Forecast inputs included utility digitalization budget disclosures, SFDA efficiency benchmark tightening schedules, and district cooling integration requirements from Dubai and Abu Dhabi smart city programs.
Revisions become necessary when semiconductor supply disruptions, shipping corridor instability, or regulatory approval timeline extensions materialize beyond modeled assumptions. Forecasts reflect documented assumptions regarding procurement mandate enforcement consistency and systems integrator certification velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Global Energy Consumption Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Heat Meter Market
Energy Management
Microgrid Control System Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Energy Security Market
Energy Management
Energy ESO Market
Energy Management
Industrial Energy Management System Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Smart Power Technologies Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
South Korea Residential Heat Pump Market