

Residential RF Smart Electric Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Residential RF Smart Electric Meter Market Insights
China is fragmenting as domestic meter manufacturers expand production capacity to serve state-backed smart grid rollouts. Itron leverages its vertically integrated RF module production to sustain cost advantages across North American deployments. Landis+Gyr anchors European demand through deep relationships with municipal suppliers requiring ZigBee-enabled meters. Kamstrup competes on precision metrology, differentiating its offerings with ultrasonic measurement cores that extend accuracy lifespans beyond electromechanical alternatives.
A residential RF smart electric meter is a solid-state electricity measurement device that transmits consumption data via radio frequency protocols in unlicensed spectrum bands, typically operating at 900 MHz or 2.4 GHz with transmit power levels below one watt to comply with unlicensed device regulations. Its primary commercial purpose is to eliminate manual meter reading while enabling real-time load monitoring and remote disconnect capability for utility providers. Single-phase meters dominate unit volumes in residential settings where power delivery remains split-phase at standard voltages, while prepaid configurations are gaining traction among electric cooperatives seeking to reduce collection risk and bad debt exposure. Wi-SUN technology leads in new RF deployments due to its mesh networking resilience and sub-GHz propagation advantages through building materials, though cellular backhaul modules command premium pricing in rural territories lacking concentrator density.
FCC Part 15 governs unlicensed RF emissions in the United States, restricting field strength and spurious outputs to prevent interference with licensed services, while CE marking under the EU Radio Equipment Directive mandates harmonized spectrum use across member states. ECHA REACH compliance affects meter housing materials and solder compositions, forcing manufacturers to reformulate assemblies or source alternative substances to maintain European market access. Utility procurement teams must monitor evolving cybersecurity mandates from national regulators as grid-edge device hardening becomes inseparable from network resilience planning.
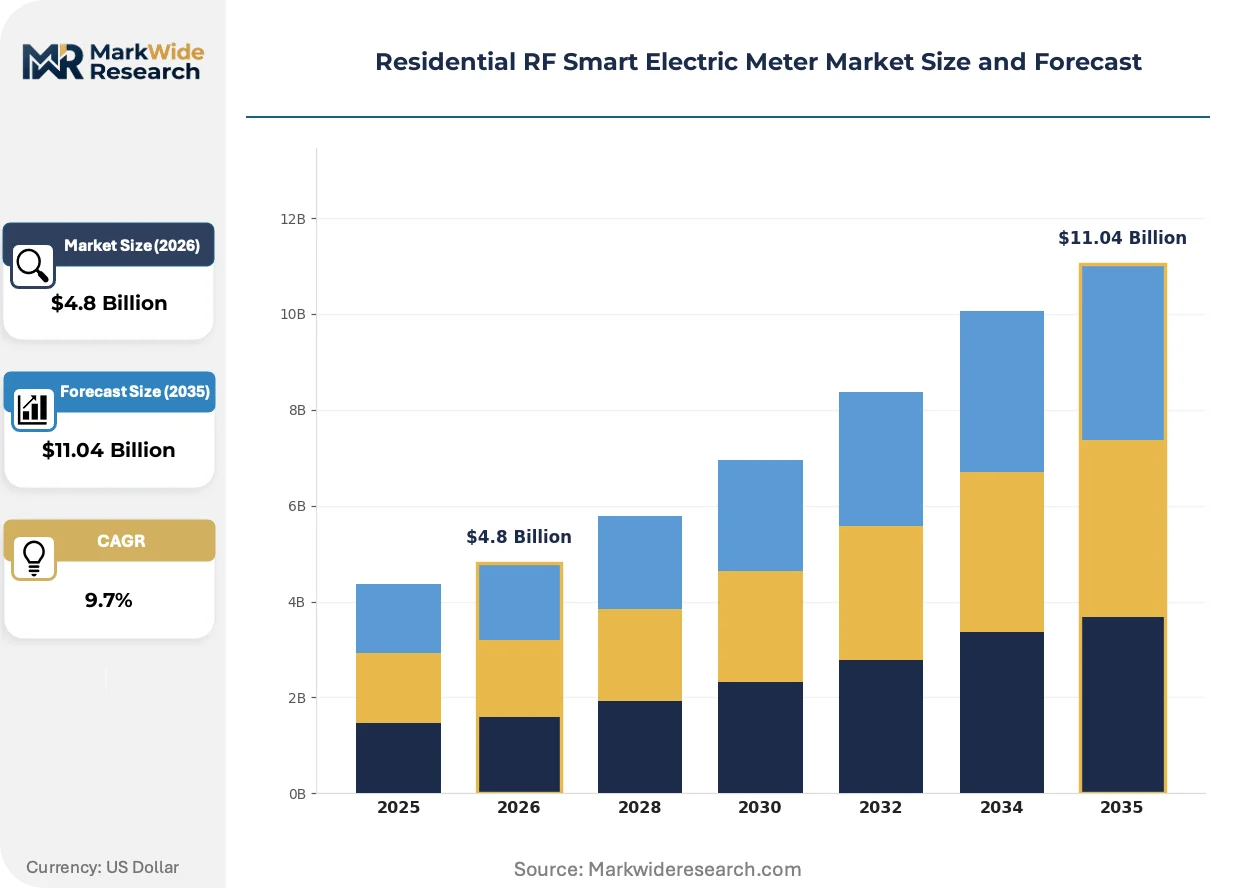
Market Dynamics
Utility procurement teams are compressing RF meter replacement cycles as state grid modernization mandates harden, forcing manufacturers to retool production lines for Wi-SUN mesh compatibility while managing component lead times for sub-GHz transceivers.
Growth Catalysts
- FCC Part 15 compliance frameworks:Unlicensed spectrum rules in the United States reduce certification barriers for RF module suppliers, accelerating product launch timelines for meter OEMs targeting North American utilities.
- China State Grid Corporation:Centralized procurement at provincial levels drives volume consolidation, creating captive demand for domestic manufacturers with localized RF calibration facilities.
- Wi-SUN field area network protocols:Mesh topology resilience through concrete and underground vaults eliminates concentrator density requirements, lowering infrastructure capex for municipal electric cooperatives.
Market Restraints
- Sub-GHz RF component concentration:Silicon foundry capacity for 900 MHz transceivers concentrates among Taiwanese semiconductor fabricators, exposing meter OEMs to geopolitical supply disruptions.
- ECHA REACH substance restrictions:Phased limitations on lead-based solder and flame-retardant housing materials force European manufacturers into costly formulation changes or supplier switches.
- Cellular LPWAN substitution:NB-IoT and LTE-M modules from telecom equipment vendors compete for rural deployments where concentrator infrastructure remains uneconomical.
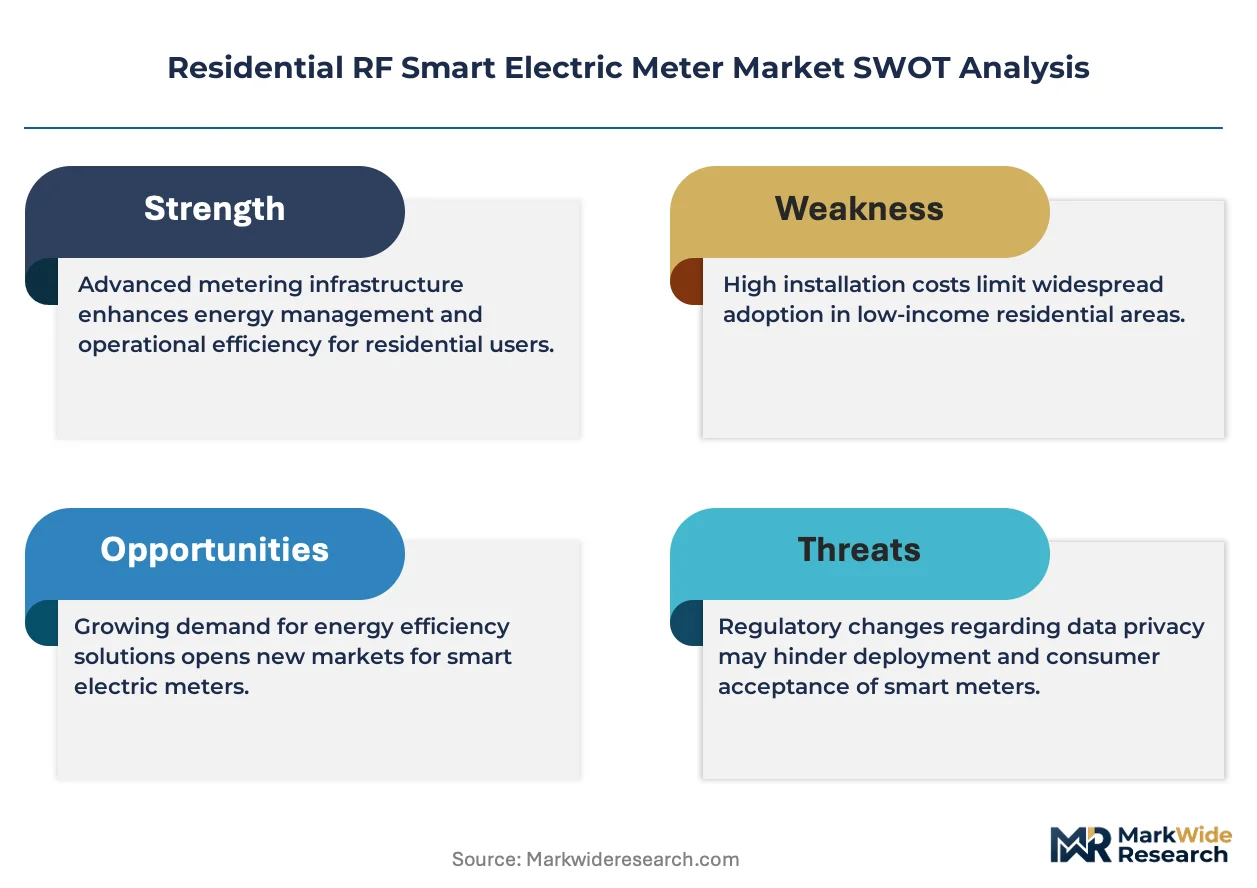
Strategic Opportunities
- Prepaid meter configurations:Electric cooperatives in sub-Saharan Africa and Southeast Asia seek credit-risk mitigation through token-based purchasing systems, opening RF meter demand outside traditional postpaid markets.
- EU Cybersecurity Certification Framework:Incoming horizontal requirements for critical infrastructure devices create first-mover advantages for vendors with pre-certified secure element architectures.
- Edge intelligence convergence:Integration of distribution transformer monitoring with residential meter endpoints enables predictive load balancing for utilities managing distributed solar penetration.
Industry Challenges
- Firmware-over-the-air certification complexity:National regulators require documented security update pathways, extending type-approval timelines by six to twelve months for RF meter platforms with remote upgrade capabilities.
- AMI-MDMS integration friction:Utility IT departments face data schema mismatches between new RF endpoints and legacy meter data management systems, requiring expensive middleware development.
- RF engineer talent scarcity:Specialized expertise in sub-GHz antenna design and mesh network optimization concentrates among semiconductor vendors, not traditional meter manufacturers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential RF Smart Electric Meter Market Trends and Innovations
RF communication architectures are pivoting toward standardized mesh protocols while cybersecurity mandates harden at the grid edge, compressing product development cycles and reshaping vendor qualification criteria.
Wi-SUN FAN 1.1 is migrating from proprietary RF stacks toward interoperable multi-vendor deployments. Large investor-owned utilities in Texas and California are mandating Wi-SUN certification for new AMI tenders, rejecting single-vendor locked ecosystems. This migration is compressing margins for meter OEMs that previously captured recurring revenue from captive RF module supply.
ECHA REACH substance restrictions are tightening compliance burdens for European meter deployments. The phased reduction of lead and certain brominated flame retardants in housing materials forces manufacturers into supply chain requalification. German municipal utilities are responding by consolidating procurement around vendors with pre-validated green material portfolios.
Prepaid service models are displacing traditional billing relationships in emerging utility markets. Token vending systems linked to RF meter disconnect capability are replacing monthly invoicing in South African and Nigerian distribution territories. This behavioral shift is most visible in peri-urban electrification projects where revenue collection infrastructure remains underdeveloped.
Residential RF Smart Electric Meter Market Segmentation
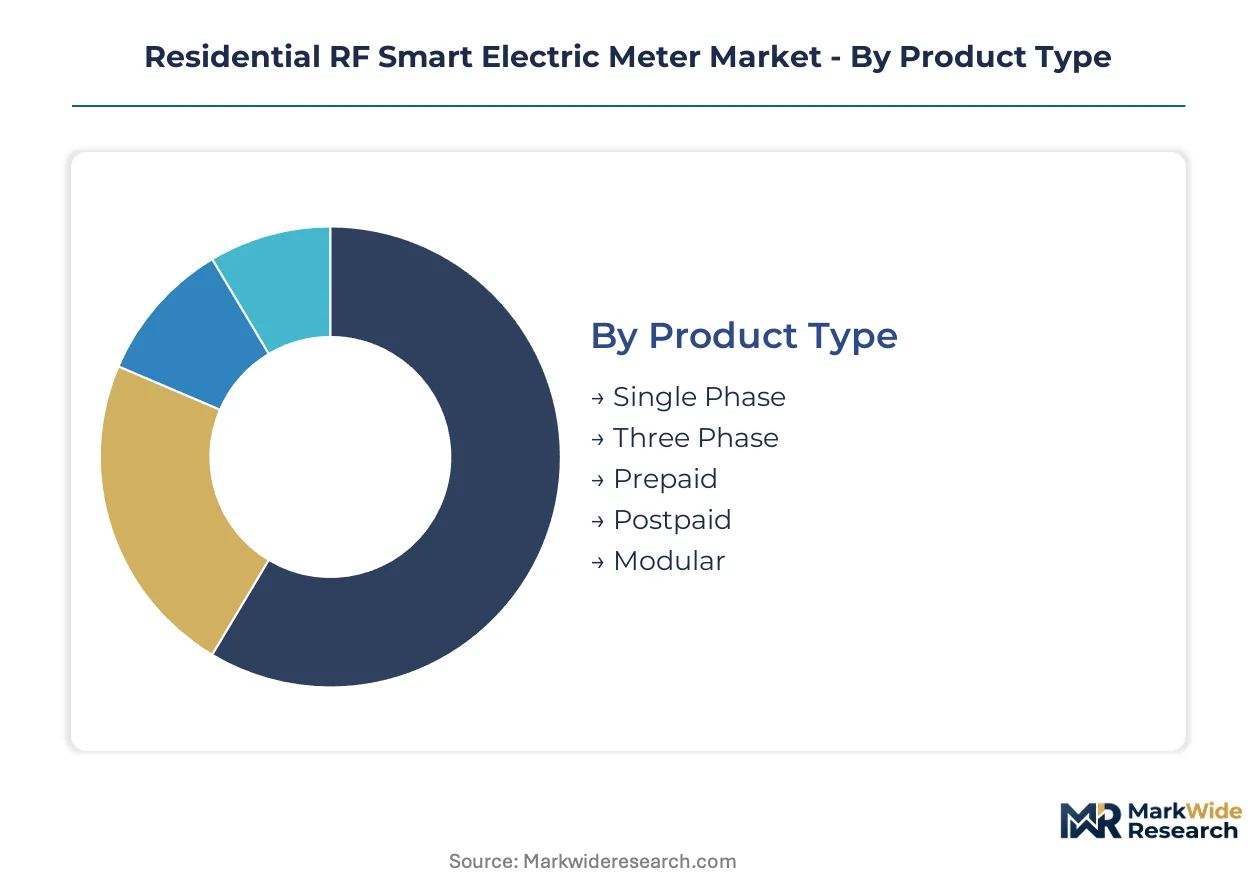
RF smart electric meter segmentation reveals how procurement specifications diverge across grid architectures and regulatory environments. Understanding these divides helps suppliers align R&D investments with the highest-velocity deployment channels.
Product Type:
Residential deployments span a spectrum from basic split-phase measurement to credit-risk-managed service models.
- Single Phase:Dominates unit economics in North American and European residential construction where split-phase 120/240V delivery remains standard. China State Grid procurement concentrates here for urban apartment blocks, compressing margins through volume tenders.
- Three Phase:Serves multi-dwelling units and small commercial premises with 208V or 400V requirements. Demand clusters in German municipal housing associations and Indian urban redevelopment zones where load diversity necessitates phase balancing.
- Prepaid:Token-based purchasing systems with integrated disconnect relays. Nigerian and South African distribution utilities deploy these to eliminate collection infrastructure in peri-urban electrification.
- Postpaid:Traditional monthly billing with accumulated consumption registers. Mature markets in Japan and South Korea maintain this model through established credit verification systems.
- Modular:Field-upgradeable chassis accepting communication or metrology swaps. Texas and California investor-owned utilities specify these for technology migration without full endpoint replacement.
The dominant share belongs to Single Phase, while Prepaid is closing the gap fastest.
Technology:
Communication layer choices trade off spectrum licensing costs against infrastructure density requirements.
- Radio Frequency:Unlicensed sub-GHz and 2.4 GHz transmission with mesh or star topologies. FCC Part 15 compliance in the United States and CE marking under EU Radio Equipment Directive govern certification pathways.
- Power Line Carrier:Data transmission superimposed on distribution conductors. Chinese state grid deployments favor this where RF propagation faces high-rise interference in dense urban cores.
- Cellular:NB-IoT and LTE-M modules from telecom equipment vendors. Rural cooperatives in Australia and Canada specify these where concentrator spacing exceeds economical RF mesh density.
- ZigBee:2.4 GHz mesh protocol with home area network integration. German municipal suppliers require ZigBee-enabled meters for consumer-facing energy display devices.
- Wi-SUN:Sub-GHz mesh with IPv6 addressing and FAN 1.1 interoperability. Texas and California utilities mandate Wi-SUN certification, rejecting single-vendor locked ecosystems.
Wi-SUN commands the steepest expansion trajectory among new deployments, while Power Line Carrier retains entrenched positions in legacy AMI territories.
Application:
Functional modules determine software stack complexity and integration requirements with utility back-office systems.
- Automated Meter Reading:Eliminates manual route-based data collection through scheduled or on-demand RF polling. Remains the baseline procurement specification for municipal suppliers in France and Italy.
- Demand Response:Real-time load curtailment signals to controllable appliances. California investor-owned utilities embed this capability to manage peak air-conditioning loads during grid stress events.
- Energy Management:Consumer-facing consumption analytics and budgeting tools. Japanese utilities bundle these with home energy management system integration for residential solar prosumers.
- Load Forecasting:Aggregated interval data feeding predictive models for transformer sizing and distributed resource dispatch. Grid operators in Germany and the Netherlands prioritize this for solar penetration management.
- Theft Detection:Anomaly algorithms flagging bypass tampering or magnetic interference. Nigerian distribution companies deploy these to address non-technical losses exceeding 30% in some territories.
Automated Meter Reading still accounts for the largest installed base, though Demand Response is expanding most quickly in jurisdictions with capacity market mechanisms.
End User:
Procurement authority structures shape vendor qualification criteria and contract negotiation leverage.
- Utility Providers:Investor-owned and state-owned entities with centralized AMI program offices. China State Grid Corporation drives the largest single procurement volumes through provincial tender consolidation.
- Electric Cooperatives:Member-owned distribution utilities with decentralized governance. Rural cooperatives in Texas and Wisconsin favor prepaid configurations to reduce bad debt exposure.
- Municipal Suppliers:City-owned utilities with localized procurement autonomy. German Stadtwerke specify ZigBee compatibility and REACH-compliant material portfolios.
- Independent Power Producers:Distributed generation developers requiring meter data for PPA settlement. Solar and storage developers in Australia and the United States deploy these at commercial-industrial customer premises.
Utility Providers control the dominant procurement volume, while Electric Cooperatives are gaining share fastest through rural electrification and credit-risk innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 rules govern unlicensed RF device operation in the United States, establishing certification pathways that reduce barriers for meter OEMs targeting North American utilities. This regulatory framework shapes deployment patterns across concentrated demand centers worldwide.
United States
Investor-owned utilities in Texas and California mandate Wi-SUN FAN 1.1 certification for new AMI tenders, rejecting single-vendor locked ecosystems. FCC Part 15 compliance frameworks accelerate product launch timelines for domestic manufacturers. Silicon Valley RF module suppliers concentrate near semiconductor design clusters serving sub-GHz transceiver demand.
China
State Grid Corporation drives the largest single procurement volumes through provincial tender consolidation for urban apartment block electrification. MIIT governs radio transmission equipment type approval under GB standards. Domestic meter manufacturers expand production capacity in Jiangsu and Zhejiang provinces to serve centralized procurement.
Germany
Municipal utilities specify ZigBee-enabled meters for consumer-facing energy display devices under ECHA REACH substance restrictions. The EU Radio Equipment Directive mandates harmonized spectrum use across member states. Stuttgart and Munich industrial clusters host precision metrology specialists serving Stadtwerke procurement.
South Africa
Distribution utilities deploy prepaid token vending systems to eliminate collection infrastructure in peri-urban electrification territories. The national regulator oversees type approval for revenue-grade metering equipment. Johannesburg and Cape Town distribution zones concentrate non-technical loss reduction programs.
Japan
Utilities bundle energy management capabilities with home energy management system integration for residential solar prosumers. METI guides smart grid investment frameworks and interoperability standards. Tokyo and Osaka metropolitan areas concentrate AMI deployment for postpaid billing relationships.
Residential RF Smart Electric Meter Market Competitive Landscape
Vertically integrated multinationals and specialized metrology firms split the market between scale-driven standardization and precision-engineered differentiation. The vendor base concentrates around three strategic archetypes: RF module-integrated OEMs capturing cost advantages through captive semiconductor supply, precision metrology specialists competing on measurement accuracy lifespans, and communication-technology licensors monetizing protocol certification. Dominant competitive moves include backward integration into transceiver silicon and geographic expansion through municipal utility relationships.
Among RF module-integrated OEMs, Itron exemplifies cost-structure optimization through in-house semiconductor production. Landis+Gyr occupies a position within the European municipal supplier tier, anchoring relationships with ZigBee-mandated procurement specifications. Kamstrup represents the precision metrology archetype, differentiating through ultrasonic measurement cores that extend accuracy lifespans.
| Leading Market Players |
|---|
| Itron |
| Landis+Gyr |
| Schneider Electric |
| Siemens |
| Honeywell |
| Kamstrup |
| Aclara Technologies |
| Sensus |
| Apator |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Jiangsu and Zhejiang province meter manufacturing clusters is compressing supplier pricing power while forcing OEMs into aggressive procurement negotiations for sub-GHz RF modules. Taiwanese semiconductor foundry utilization rates directly shape module cost trajectories for North American and European deployments.
Pricing Analysis
Geographic price spreads between Chinese domestic tenders and German municipal contracts exceed three-to-one ratios, driven by volume aggregation effects and REACH compliance certification tiers. Pricing stratifies across Wi-SUN certified, ZigBee-enabled, and basic RF-only configurations, with certification investment separating premium from standard tiers. Cost compression in single-phase residential meters is intensifying because domestic Chinese manufacturers are absorbing margin erosion to maintain State Grid procurement relationships. Electric cooperatives in sub-Saharan Africa exhibit the highest price sensitivity, while Japanese utilities prioritize measurement accuracy over unit cost.
Supply Chain Analysis
Upstream feedstock for sub-GHz transceivers draws from silicon wafer production concentrated in Taiwan, South Korea, and the United States, with backend packaging and testing anchored in Malaysia and Vietnam. Critical dependencies include 900 MHz RF front-end modules, precision current transformers, and flame-retardant housing polymers subject to ECHA substance restrictions. Single-source vulnerability in Taiwanese foundry capacity exposes meter OEMs to geopolitical disruption scenarios. Distribution runs through utility procurement consortiums in North America, direct state-backed tenders in China, and municipal supplier frameworks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory certification entrenchment creates substantial switching costs for utility procurement departments. Network effects in mesh protocol ecosystems further harden incumbent positions.
For Market Incumbents: Harden cybersecurity certification moats by pre-integrating secure element architectures ahead of EU Cybersecurity Certification Framework mandates. Deepen backward integration into RF module semiconductor supply to offset foundry concentration risk in Taiwan. Cellular LPWAN substitution from telecom equipment vendors represents the most credible technology threat to mesh-based RF deployments. For New Entrants and Emerging Players: Build out prepaid meter service capabilities targeting electric cooperatives in Southeast Asia and sub-Saharan Africa where collection infrastructure remains underdeveloped. Peri-urban electrification zones in Nigeria and South Africa offer the most penetrable demand pockets. Partner with token vending system operators to bypass direct utility procurement gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Wi-SUN certified product lines as certification standardization commoditizes RF module differentiation. Target acquisition candidates with ultrasonic metrology IP and established municipal supplier relationships in Germany or Japan. Watch for inflection signals in China State Grid tender consolidation patterns that would compress domestic manufacturer margins further.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-SUN FAN 1.1 Certification Investment | Texas and California utilities now mandate interoperable mesh protocols, rejecting single-vendor lock-in. |
| Backward Integration into RF Module Production | Itron's captive semiconductor supply sustains cost advantages against module-dependent competitors. |
| REACH-Compliant Material Portfolio Validation | German Stadtwerke procurement is consolidating around vendors with pre-validated green material supply chains. |
| Prepaid Configuration Development | South African and Nigerian distribution utilities seek token-based systems to eliminate collection infrastructure. |
| Secure Element Architecture Pre-Certification | EU Cybersecurity Certification Framework creates first-mover advantages for hardened grid-edge devices. |
Research Methodology
Desk research of FCC Part 15 certification databases, ECHA REACH substance restriction filings, and China State Grid procurement bulletins preceded structured interviews with utility AMI program directors, RF module procurement managers, and municipal supplier technical specifications leads. Primary fieldwork with meter OEM engineering teams and semiconductor foundry account managers was cross-validated against customs trade data and utility capital expenditure disclosures. Bottom-up unit deployment tracking and top-down grid modernization budget analysis were triangulated to establish volume estimates.
Assumptions held fixed across the projection horizon include continued Wi-SUN protocol standardization, stable FCC Part 15 regulatory frameworks, and sustained China State Grid centralized procurement consolidation. The analytical framework modeled segmentation across product type, communication technology, application functionality, and end-user procurement authority. CAGRs were derived from deployment pipeline analysis and replacement cycle compression trends, incorporating sub-GHz transceiver supply constraints and cybersecurity mandate implementation timelines as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cellular LPWAN equipment vendors or disruptive prepaid service platform operators would shift outcomes beyond modeled ranges. Cross-checking against national regulatory filing deadlines and utility commission rate case schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.