
 Middle East and Africa Pharmaceutical Plastic Bottles Market | 2026-2036
Middle East and Africa Pharmaceutical Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pharmaceutical Plastic Bottles Market Insights
Project finance tied to pharmaceutical manufacturing zones is fragmenting competitive access across the Middle East and Africa. Amcor Plc leverages its pre-existing film extrusion footprint to anchor bottle supply contracts with multinational drug makers operating in Egypt. Berry Global Inc. sustains volume leadership through backward integration into resin compounding for high-density polyethylene formats. ALPLA Werke Alwin Lehner GmbH & Co KG competes via asset-light toll-manufacturing arrangements with regional distributors in the Gulf.
Pharmaceutical plastic bottles are blow-molded or injection-stretch-blown containers, typically manufactured from polyethylene terephthalate or high-density polyethylene, designed to meet moisture-vapor transmission and child-resistant closure standards for oral solid and liquid dosage forms. Their primary purpose is to preserve drug stability while enabling compliant dispensing across variable temperature and humidity conditions in emerging-market supply chains. Rigid bottles dominate current volume owing to their compatibility with tablet and capsule formats, while dropper bottles capture expanding share in ophthalmic and pediatric liquid segments where precision dosing requirements tighten. Polyethylene maintains cost leadership across high-volume antibiotic packaging, though polypropylene is displacing it in parenteral-compatible formats where autoclave resistance matters.
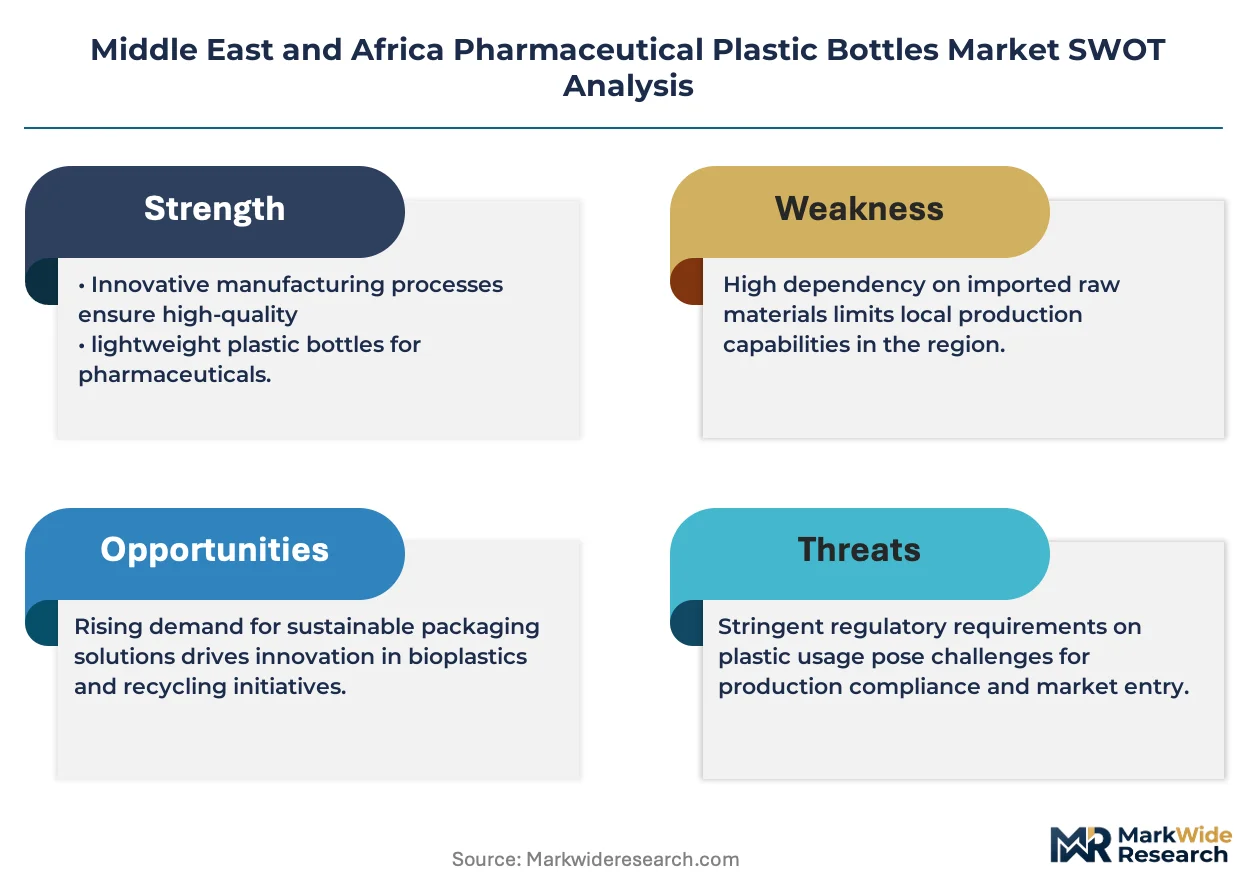
SAHPRA in South Africa enforces pharmacopoeial packaging standards that restrict recycled content in primary drug-contact layers, directly elevating virgin resin demand. Egypt's national drug authority and Saudi Arabia's SFDA both mandate Arabic-English bilingual labeling and child-resistant closure compliance, creating specification complexity that favors technically capable molders. The UAE's MOHAP tracks European MDR alignment for imported devices and packaging, tightening audit requirements on foreign suppliers. Stakeholders must monitor whether Gulf Cooperation Council harmonization on pharmaceutical packaging standards accelerates or fragments national certification pathways.
Market Dynamics
SAHPRA's alignment with ICH Q3D guidelines on elemental impurities is forcing resin-grade upgrades across South Africa's generic pharmaceutical sector, creating a compliance-driven demand surge for virgin-grade polyethylene and polypropylene formats that ripple through regional procurement patterns.
Growth Catalysts
- ICH Q3D Compliance Mandate:South Africa's SAHPRA adoption of elemental impurity standards elevates virgin resin specifications for primary drug-contact layers, expanding addressable volume for compliant molders.
- Contract Packaging Expansion:Egypt's Cairo-Alexandria corridor is aggregating regional export demand as multinational drug makers consolidate packaging operations for North African and Levantine markets.
- HDPE Backward Integration:Regional converters capturing in-house resin compounding capabilities are compressing lead times for high-density polyethylene antibiotic bottles serving Nigeria's public health programs.
Market Restraints
- Virgin Resin Cost Volatility:Crude-linked polyethylene and polypropylene feedstock pricing exposes converters to margin compression when naphtha spreads widen.
- Recycled Content Restrictions:SAHPRA's prohibition on post-consumer resin in primary drug-contact layers eliminates cost-advantaged circular material pathways.
- Import Dependency for Specialized Grades:Pharmaceutical-grade polyethylene terephthalate with specified moisture-vapor transmission properties concentrates supply with Gulf petrochemical complexes.
Strategic Opportunities
- GCC Harmonization Pathway:Potential alignment of Saudi SFDA and UAE MOHAP pharmaceutical packaging standards would streamline multi-market certification for compliant suppliers.
- Ophthalmic Dropper Bottles:Precision-dosing liquid formats for pediatric and eye-care segments remain underpenetrated relative to rigid tablet containers across Egypt and Nigeria.
- Arabic-English Bilingual Labeling Automation:Regulatory mandates from Egypt's national drug authority and Saudi SFDA create specification complexity that rewards technically capable molders with integrated printing capabilities.
Industry Challenges
- Multilingual Mold Configuration:Dual-script embossing and labeling requirements for Saudi and Egyptian markets extend tool-changeover cycles and compress equipment utilization rates.
- ICH Q3D Testing Backlogs:Elemental impurity verification capacity at South African analytical laboratories is creating certification delays for resin-grade changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pharmaceutical Plastic Bottles Market |
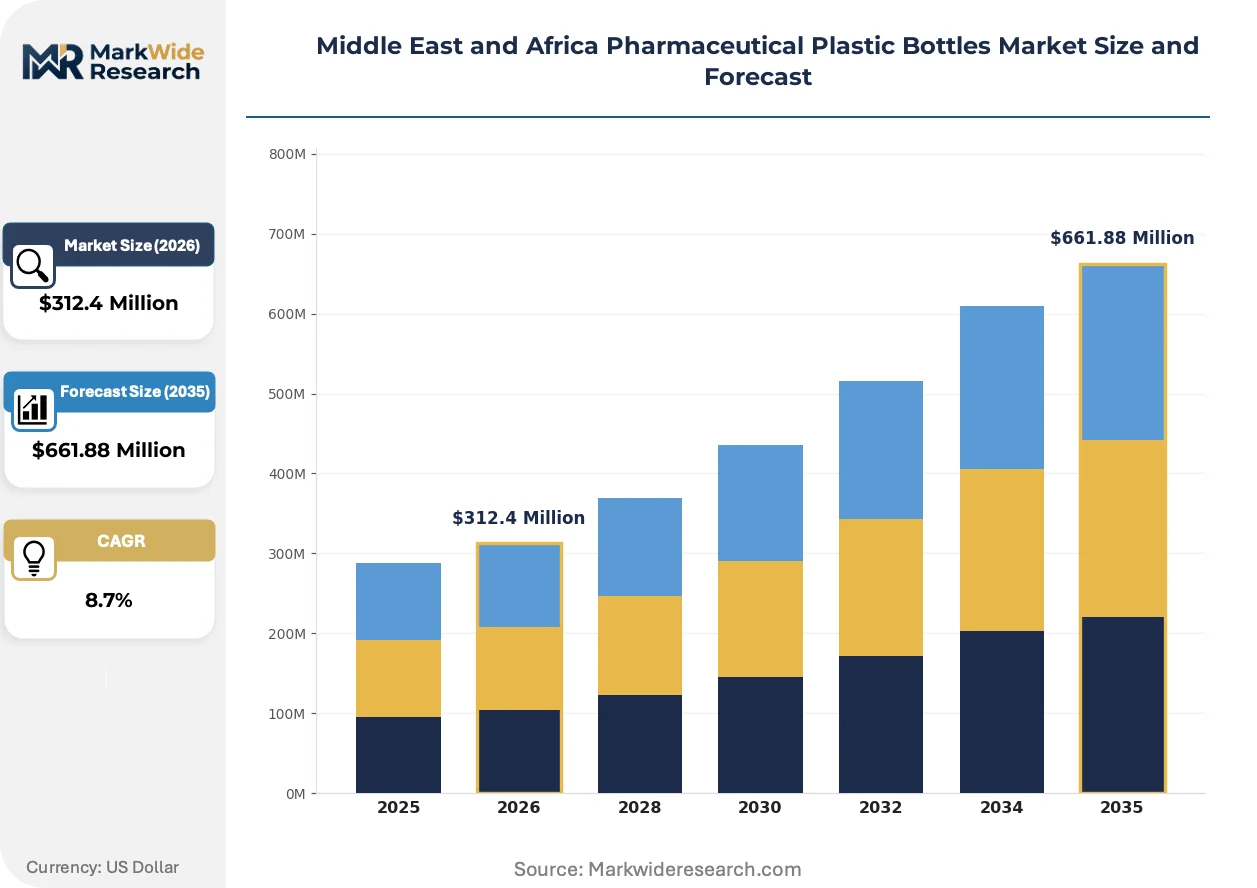
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dropper Bottles, Spray Bottles, Rigid Bottles, Flexible Bottles Capacity: 10ml, 50ml, 100ml, 500ml Material: Polyethylene, Polypropylene, PET, PVC Closure Type: Screw Caps, Tamper Evident Caps, Flip Top Caps, Child Resistant Caps |
| Companies Covered | Berry Global Inc., Amcor Plc, ALPLA Werke Alwin Lehner GmbH & Co KG, Plastipak Holdings Inc., Gil Plastic Products Ltd, Silgan Holdings Inc., Gerresheimer AG, AL AMANA PLASTICS, Drug Plastics Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pharmaceutical Plastic Bottles Market Trends and Innovations
Material science convergence with regulatory stringency is reconfiguring competitive advantage in Middle East and Africa pharmaceutical packaging. Converters are engineering multi-layer structures and specialized barrier formats that satisfy evolving pharmacopoeial standards while accommodating regional supply chain temperature variability.
Co-extruded polyethylene terephthalate with ethylene vinyl alcohol interlayers is hybridizing moisture protection for humidity-sensitive solid oral dosages. Nigerian generic manufacturers are accelerating adoption of these barrier bottles for antibiotic exports to West African markets with limited cold-chain infrastructure. The technology is hybridizing the traditional trade-off between cost-efficient monolayer formats and premium aluminum-laminate alternatives.
SFDA and Egypt's national drug authority are synchronizing child-resistant closure testing protocols with US FDA 16 CFR 1700 standards, eliminating duplicative certification requirements for suppliers serving both Gulf and North American markets. This regulatory convergence reduces time-to-market for compliant bottle-and-cap systems by compressing validation cycles. Multinational drug makers operating in Saudi Arabia are consolidating supplier qualifications around these aligned standards.
Buyer concentration among Egyptian contract packaging organizations is compressing procurement cycles for standardized high-density polyethylene formats. Regional distributors are disintermediating spot-market resin purchases in favor of multi-year toll-manufacturing arrangements with integrated molders. This pattern is most visible in the Cairo-Alexandria corridor, where packaging procurement for regional pharmaceutical exports is consolidating around three vertically integrated suppliers with captive blow-molding and printing capabilities.
Middle East and Africa Pharmaceutical Plastic Bottles Market Segmentation
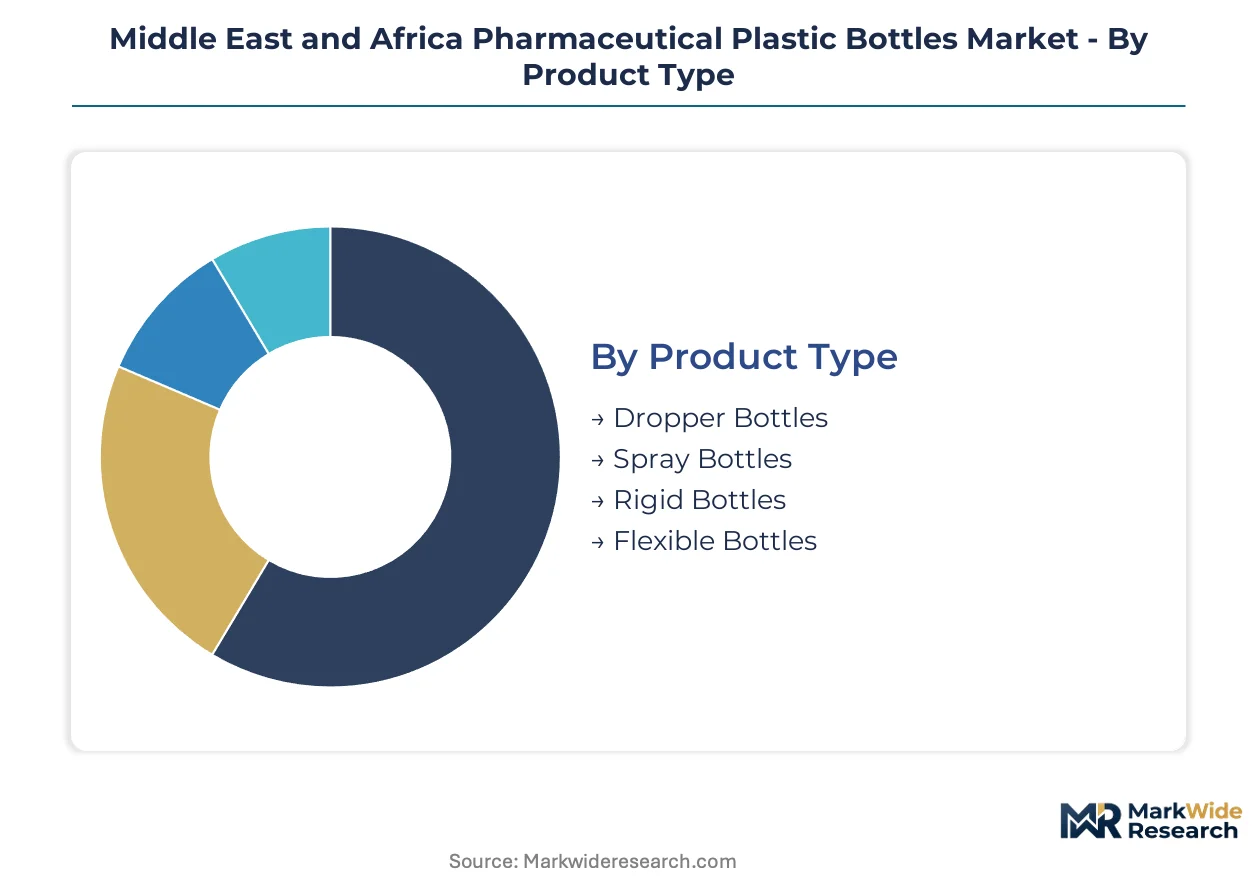
Packaging specifications across Middle East and Africa pharmaceutical markets diverge sharply by dosage form, distribution climate, and regulatory jurisdiction. Segmentation reveals where converters must engineer distinct barrier properties, closure systems, and labeling configurations to capture contract manufacturing volumes.
Product Type:
Application requirements dictate structural design — liquid precision dosing, solid oral protection, and topical dispensing each impose distinct blow-molding constraints and closure integration challenges.
- Rigid Bottles:Blow-molded high-density polyethylene or polyethylene terephthalate containers with cylindrical walls and flat shoulders, engineered for tablet and capsule protection against moisture ingress. Demand concentrates in Egypt's Cairo-Alexandria corridor where contract packagers aggregate regional antibiotic exports; SAHPRA's ICH Q3D compliance mandates are elevating virgin resin specifications for these high-volume formats.
- Dropper Bottles:Low-density polyethylene or polypropylene formats with integrated pipette assemblies and controlled-drop orifices, designed for ophthalmic and pediatric liquid precision. Nigerian generic manufacturers are scaling procurement for these bottles as West African export programs expand eye-care and antimalarial liquid formulations.
- Spray Bottles:Trigger or pump-actuated systems with dip tubes and misting nozzles, typically polypropylene-bodied for topical pharmaceutical applications.
- Flexible Bottles:Collapsible LDPE or multilayer squeeze formats for unit-dose liquid dispensing in resource-limited settings with irregular cold-chain access.
Rigid bottles command the established base. The steepest expansion runs through dropper bottles.
Capacity:
Volume segmentation tracks prescription duration norms, institutional procurement scales, and export packaging economics across North African and Sub-Saharan markets.
- 100ml:Standard prescription-duration format for 30-day solid oral regimens, blow-molded in HDPE with desiccant-cap integration. South Africa's retail pharmacy chains and Egypt's public health programs standardize procurement around this capacity tier.
- 500ml:Institutional and hospital bulk formats for high-volume antibiotic suspensions or chronic disease medications, typically HDPE with wide-mouth screw closures. Nigerian federal drug procurement for primary health centers drives demand concentration.
- 10ml:Unit-dose ophthalmic and pediatric specialty formats, precision-molded in LDPE with integral dropper tips.
- 50ml:Intermediate capacity for 7-14 day antibiotic courses or travel-size pharmaceutical kits.
100ml formats anchor current procurement volumes. The 500ml tier is climbing fastest as institutional purchasing consolidates.
Material:
Resin selection balances moisture-vapor transmission thresholds, autoclave compatibility, and elemental impurity compliance against feedstock cost exposure.
- Polyethylene:HDPE and LDPE grades dominate cost-sensitive antibiotic packaging with adequate moisture barriers for short-distribution-cycle markets. Virgin-grade HDPE is displacing recycled-content alternatives as SAHPRA enforces primary-layer purity standards.
- PET:Polyethylene terephthalate delivers superior moisture-vapor transmission resistance for humidity-sensitive solid dosages, often co-extruded with ethylene vinyl alcohol interlayers. Gulf petrochemical complexes concentrate supply of pharmaceutical-grade resin with specified barrier properties.
- Polypropylene:Autoclave-resistant grades capture parenteral-compatible and high-temperature sterilization applications where thermal stability exceeds polyethylene limits.
- PVC:Limited to specific blister and clamshell secondary packaging applications with declining primary-container relevance due to plasticizer migration concerns.
Polyethylene retains volume leadership. PET is gaining share fastest as barrier requirements tighten for regional export markets.
Closure Type:
Regulatory mandates on child safety, tamper evidence, and bilingual labeling are reconfiguring closure specification complexity and mold-changeover economics.
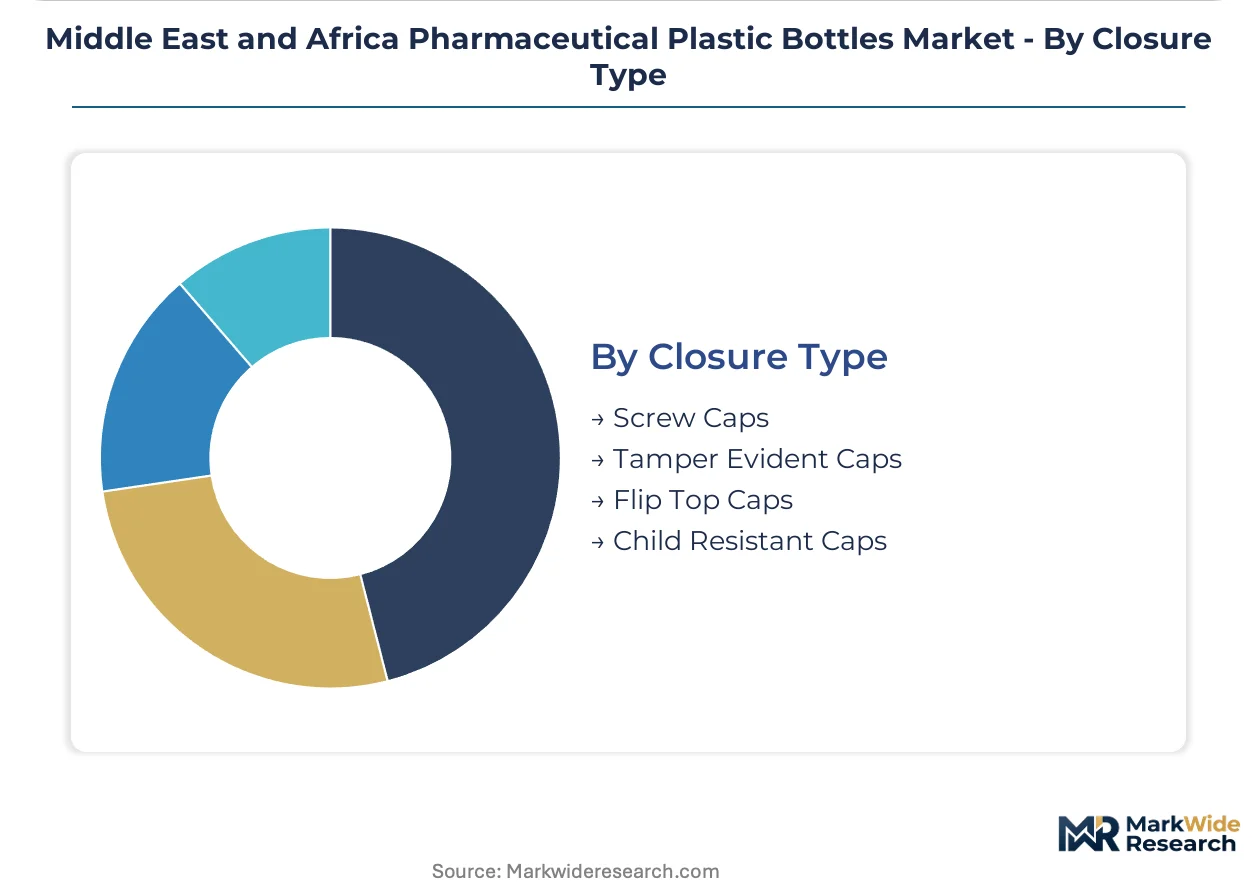
- Child Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms tested to US FDA 16 CFR 1700 protocols, now synchronized with Saudi SFDA and Egyptian drug authority standards. Elimination of duplicative certification cycles is accelerating adoption by multinational drug makers operating across Gulf and North American markets.
- Tamper Evident Caps:Ring-break or shrink-band systems providing visible post-manufacturing intrusion detection, mandatory for over-the-counter pharmaceutical distribution in Saudi Arabia and the UAE.
- Screw Caps:Standard continuous-thread closures for institutional and prescription-controlled pharmaceutical distribution where child resistance is not mandated.
- Flip Top Caps:Hinged dispensing closures for frequent-access liquid medications, common in topical and ophthalmic applications.
Child resistant caps anchor regulatory compliance investments. Tamper evident systems are expanding most quickly as Gulf markets tighten over-the-counter packaging standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Egypt's Cairo-Alexandria corridor where contract packaging aggregators command procurement scale, while Nigerian converters absorb feedstock volatility through shorter-term toll arrangements. This asymmetry fragments margin capture across North African and Sub-Saharan markets.
South Africa
SAHPRA's ICH Q3D alignment is forcing resin-grade upgrades across Johannesburg-Pretoria pharmaceutical manufacturing zones. The regulator's prohibition on recycled content in primary drug-contact layers eliminates cost-advantaged circular pathways. Cape Town's analytical laboratories face elemental impurity verification backlogs that delay compliant bottle certifications.
Egypt
Egypt's national drug authority mandates Arabic-English bilingual labeling and child-resistant closure compliance for all pharmaceutical exports. The Cairo-Alexandria corridor aggregates regional contract packaging demand for North African and Levantine markets. Three vertically integrated suppliers with captive blow-molding and printing capabilities dominate procurement consolidation.
Saudi Arabia
SFDA synchronization of child-resistant closure testing with US FDA 16 CFR 1700 standards eliminates duplicative certification cycles for multinational drug makers. Riyadh-Jeddah manufacturing zones attract packaging suppliers serving both Gulf and North American markets. The regulator's over-the-counter tamper-evident mandates tighten specification complexity for imported bottle systems.
United Arab Emirates
MOHAP tracks European MDR alignment for imported pharmaceutical packaging, tightening audit requirements on foreign suppliers. Dubai's free zone logistics hubs position converters for re-export to African markets with limited domestic molding capacity. The emirate's pharmaceutical trade infrastructure supports regional distribution of compliant primary containers.
Nigeria
Federal drug procurement for primary health centers drives institutional-scale demand for 500ml high-density polyethylene antibiotic bottles. Lagos-Kano distribution corridors face irregular cold-chain access that elevates barrier requirements for solid oral dosage protection. Generic manufacturers are scaling procurement of compliant primary packaging for West African export programs.
Middle East and Africa Pharmaceutical Plastic Bottles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream feeding resin, tooling, and closure subsystems into integrated supply chains. The Middle East and Africa pharmaceutical plastic bottles market structures around three archetypes: multinational converters with captive resin compounding, regional toll-manufacturing networks, and specialized molders with integrated printing capabilities. Consolidation pressure runs through backward integration into polyethylene feedstocks and multi-year toll arrangements that disintermediate spot resin markets. Geographic expansion and certification harmonization represent the dominant competitive vectors as Gulf and North African regulators synchronize standards.
Among multinational converters, Berry Global Inc. and Amcor Plc exemplify scale-driven platform integrators with regional supply footprints. ALPLA Werke Alwin Lehner GmbH & Co KG occupies a position within the toll-manufacturing archetype, leveraging asset-light arrangements with Gulf distributors. These three anchors illustrate how competitive positioning stratifies between integrated resin-to-bottle systems and flexible regional manufacturing partnerships.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor Plc |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Plastipak Holdings Inc. |
| Gil Plastic Products Ltd |
| Silgan Holdings Inc. |
| Gerresheimer AG |
| AL AMANA PLASTICS |
| Drug Plastics Group |
| Others |
Pricing and Supply Chain Analysis
Gulf petrochemical complexes concentrate pharmaceutical-grade polyethylene terephthalate supply, anchoring margin pools with Egyptian contract packaging aggregators who command procurement scale in the Cairo-Alexandria corridor while Nigerian converters absorb feedstock volatility through shorter toll arrangements.
Pricing Analysis
Customization-premium spreads separate ICH Q3D-compliant virgin resin formats from standard recycled-content alternatives. Three-tier pricing structure across premium certification-grade, standard pharmacopoeial-compliant, and economy non-certified levels tracks SAHPRA mandates and SFDA bilingual labeling requirements. Price differentiation hinges on elemental impurity testing documentation and child-resistant closure validation cycles. Cost compression in economy tiers is intensifying because Nigerian federal procurement favors lowest-unit-cost institutional formats. Generic manufacturers in West Africa exhibit highest price sensitivity; multinational drug makers in Saudi Arabia and Egypt demonstrate lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Contract-manufacturing concentration sits with Berry Global Inc., Amcor Plc, and ALPLA Werke Alwin Lehner GmbH & Co KG across Egypt, Saudi Arabia, and South Africa. Raw material dependencies draw from Gulf polyethylene and polypropylene feedstocks, Egyptian resin compounding capacity, and specialized PET moisture-barrier grades from UAE petrochemical operations. Single-source vulnerability concentrates in pharmaceutical-grade PET with specified vapor-transmission properties. Distribution runs through Dubai free-zone logistics hubs for re-export to Sub-Saharan markets with limited domestic molding infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing as SFDA-MOHAP-Egyptian drug authority interoperability on child-resistant closure standards collapses duplicative certification cycles into unified supplier qualification pathways.
For Market Incumbents: Insulate compliant-grade resin supply positions through captive compounding investments in Egypt and Saudi Arabia to offset SAHPRA's virgin resin mandates. Defend against regional toll-manufacturing networks by embedding integrated printing capabilities for Arabic-English bilingual labeling automation. Certification investment in synchronized FDA-SFDA testing protocols represents the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in ophthalmic dropper bottles across Egypt and Nigeria where precision-dosing formats remain underpenetrated relative to rigid tablet containers. Target West African export corridors serving eye-care and antimalarial liquid formulations. Go-to-market execution should anchor on multi-year toll-manufacturing arrangements with Lagos-Kano distributors disintermediating spot resin purchases. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional molders possessing SAHPRA-compliant certifications and Cairo-Alexandria corridor contract packaging relationships. Long-term viability over a multi-year horizon rests on GCC harmonization acceleration and backward integration into resin feedstocks. Watch SAHPRA analytical laboratory capacity expansion as the inflection signal for certification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply compresses lead times for Nigerian antibiotic procurement programs. |
| Arabic-English Bilingual Labeling Automation | Integrated printing capabilities satisfy Egyptian drug authority and Saudi SFDA mandates simultaneously. |
| ICH Q3D Compliance Certification Investment | Elemental impurity testing documentation unlocks SAHPRA-aligned generic manufacturer contracts. |
| Multi-Year Toll-Manufacturing Arrangements | Long-term resin offtake agreements disintermediate spot market volatility for Gulf distributors. |
| Ophthalmic Dropper Bottle Capacity Expansion | Precision-dosing formats capture West African eye-care and pediatric liquid export growth. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical packaging procurement managers, regulatory affairs directors at generic manufacturers, contract packaging operations heads, and resin compounding technical leads and refined through secondary validation across SAHPRA guidance documents, SFDA pharmaceutical packaging standards, Egyptian drug authority export regulations, and customs trade data on polyethylene and polypropylene resin flows. Bottom-up volume modeling triangulated against top-down market sizing anchored the analysis.
Demand-supply-balance framing structured the analytical approach across the analysis window. Segmentation dimensions modeled include product type, capacity tier, material grade, closure system, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trajectories. Forecast inputs incorporated ICH Q3D adoption timelines, GCC harmonization probability assessments, and Nigerian federal drug procurement cycle patterns.
Macroeconomic conditions sit as an overlay; deviation in crude-linked naphtha spreads, Egyptian pound volatility, and South African rand exchange rates would shift the trajectory. Forecasts reflect underlying assumptions on regulatory synchronization pace and resin grade upgrade compliance costs. Quarterly review of SAHPRA certification backlogs, SFDA guidance updates, and Gulf petrochemical operating rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market