
 Pharmaceutical Vial Fillers Market | 2026-2036
Pharmaceutical Vial Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Vial Fillers Market Analytics
Biotech firms is realigning demand toward high-containment robotic fillers for antibody and cell therapy production. Syntegon leverages its isolator-integrated platforms to dominate aseptic filling for complex biologics. IMA Life anchors European supply through modular filler lines that sustain cGMP compliance across multiple drug formats. Vanrx Pharmasystems Inc. specializes in gloveless robotic systems that eliminate human intervention during critical filling operations.
Pharmaceutical vial fillers are precision dosing machines engineered to deliver sterile liquid or lyophilized drug products into glass or polymer vials at rates from 100 to 600 units per minute, with fill accuracy typically within ±0.5% of target volume. These systems incorporate in-process checkweighing, 100% vision inspection, and laminar airflow or isolator containment to maintain sterility assurance levels throughout the filling cycle. Automatic fillers lead installed base volumes due to throughput requirements in large-molecule commercial manufacturing, while robotic fillers represent the fastest-expanding category as gene therapy and personalized medicine batches demand flexible, small-scale aseptic processing with rapid changeover. Aseptic filling technology commands the dominant margin pool because isolator integration and barrier system validation create substantial switching costs for end users.
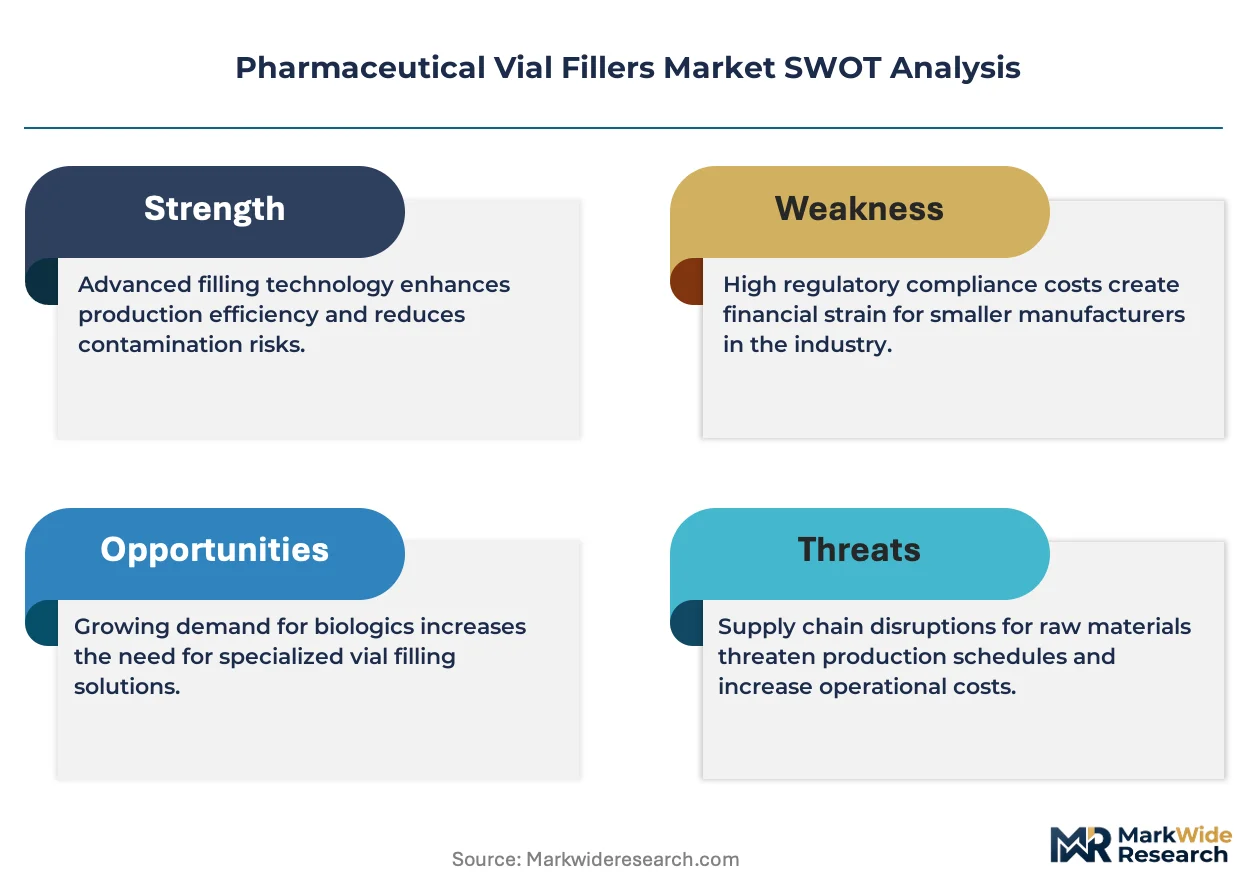
FDA aseptic processing guidelines, EU GMP Annex 1 revisions, and ISO 14644 cleanroom classifications collectively mandate continuous environmental monitoring and closed-system architecture for vial filling operations. The FDA's emphasis on contamination control strategies is accelerating isolator adoption over traditional cleanroom-based filling lines. EMA's tightened sterility assurance expectations for ATMP manufacturing are reshaping equipment qualification protocols across European biotech facilities. Stakeholders must weigh capital intensity against batch failure risk when selecting between isolator-based and conventional aseptic filling architectures for emerging biologic modalities.
Market Dynamics
The transition from open cleanroom filling to isolator-based containment is restructuring capital allocation across pharmaceutical manufacturing, as contamination control strategies become the decisive factor in facility design and equipment selection.
Growth Catalysts
- EMA's ATMP manufacturing guidelines:Tightened sterility assurance requirements for cell and gene therapies are mandating closed-system architectures that only advanced robotic fillers can deliver.
- Precision engineering clusters in Germany:Concentrated supplier ecosystems around Stuttgart and Munich enable rapid prototyping of high-speed filling automation for complex biologics.
- Lyophilization integration:Combined filling-lyophilization lines reduce aseptic transfers, cutting contamination risk for temperature-sensitive monoclonal antibodies.
Market Restraints
- Stainless steel supply concentration:Premium-grade 316L stainless for product-contact surfaces faces sourcing bottlenecks from limited European and Japanese mill capacity.
- Isolator validation timelines:FDA's enhanced expectations for contamination control strategy documentation extend equipment qualification cycles by twelve to eighteen months.
- Skilled aseptic engineering scarcity:The shallow talent pool for isolator-integrated system design inflates implementation costs and delays facility startups.
Strategic Opportunities
- Modular skid-mounted fillers:Pre-validated, containerized filling lines slash deployment time for biotech firms in emerging European markets.
- EU Green Deal alignment:Energy-efficient isolator designs with reduced HVAC loads qualify for sustainability-linked financing instruments.
- Personalized medicine batches:Small-scale robotic fillers enable flexible aseptic processing for patient-specific cell therapies at commercial quality standards.
Industry Challenges
- Legacy cleanroom retrofit complexity:Integrating isolator barriers into existing Grade A suites demands structural reinforcement and airflow rebalancing that disrupts ongoing production.
- Multi-format changeover validation:Demonstrating sterility assurance across vial sizes, closure types, and fill volumes extends regulatory filing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Vial Fillers Market |
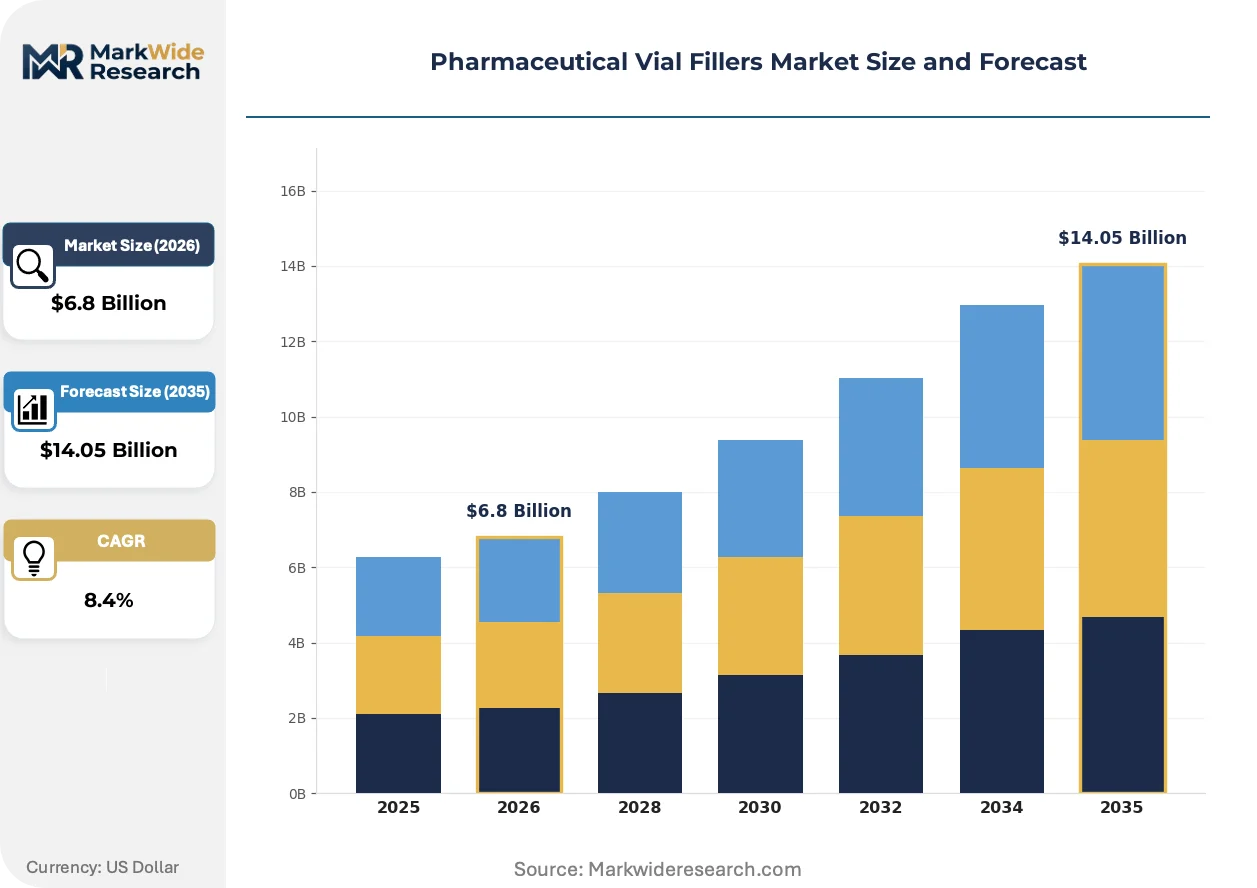
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Fillers, Semi-Automatic Fillers, Manual Fillers, Robotic Fillers Technology: Aseptic Filling, Non-Aseptic Filling, Vacuum Filling, Pressure Filling End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Biotech Firms, Research Laboratories Application: Vaccines, Hormones, Infusions, Antibodies |
| Companies Covered | Syntegon, IMA Life, Groninger, Romaco, Dara Pharma, Harro Höfliger, ACG Worldwide, Bausch+Strobel, Vanrx Pharmasystems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Vial Fillers Market Evolving Landscape
Robotic automation is penetrating aseptic filling at unprecedented depth, compressing batch cycle times while eliminating human intervention as the primary contamination vector. This shift is redrawing competitive boundaries between established cleanroom specialists and precision robotics suppliers.
Gloveless isolator technology is absorbing the most demanding filling applications in cell therapy and viral vector manufacturing. Biotech contract manufacturers in Massachusetts and North Carolina are deploying these systems for commercial-scale gene therapy production. The technology is absorbing market share from conventional restricted access barrier systems by eliminating glove ports as failure points.
EU GMP Annex 1 revisions mandate continuous viable and non-viable particle monitoring throughout filling operations. Pharmaceutical manufacturers must install automated environmental monitoring systems with real-time alert capabilities. Isolator-based lines in Germany and Switzerland are retrofitting rapid microbial detection to meet these expectations ahead of enforcement deadlines.
Biotech procurement teams are consolidating supplier relationships around full-line responsibility rather than component sourcing. Equipment vendors now contract for throughput guarantees and multi-year service commitments. This pattern concentrates most visibly in the Boston-Cambridge biotech corridor, where fill-finish outsourcing decisions increasingly favor turnkey platform providers.
Pharmaceutical Vial Fillers Market Segmentation
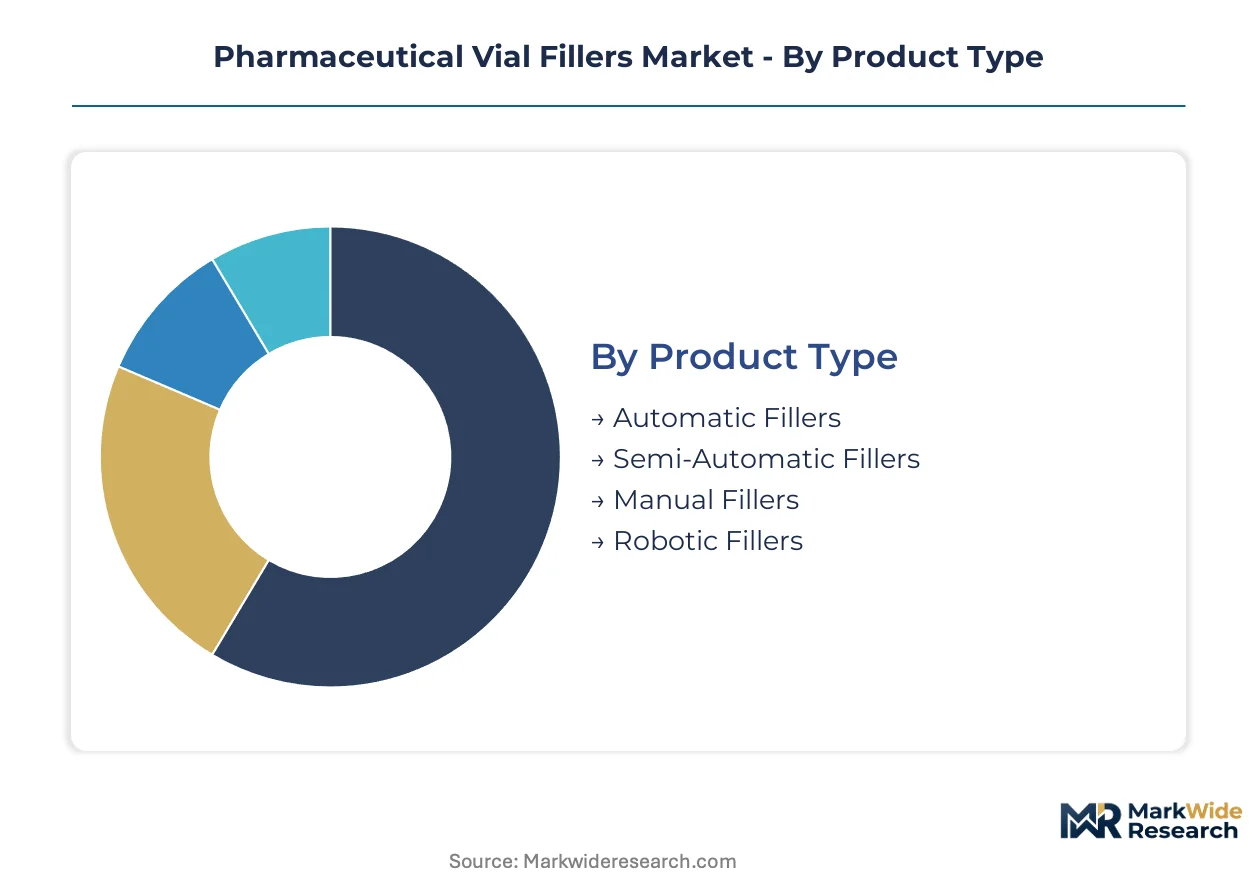
Equipment selection in pharmaceutical vial filling pivots on throughput requirements, sterility assurance levels, and batch flexibility needs. Segmentation reveals where capital concentrates versus where technology shifts fastest.
Product Type:
Automatic fillers dominate installed base volumes while robotic systems capture the premium expansion trajectory.
- Automatic Fillers:High-speed rotary systems deliver 300-600 vials per minute with integrated checkweighing and vision inspection. Demand concentrates in large-molecule commercial manufacturing across Germany and Switzerland, driven by monoclonal antibody output scaling.
- Robotic Fillers:Gloveless isolator-integrated systems eliminate human intervention through SCARA or six-axis arms for complex biologics. Massachusetts and North Carolina biotech corridors are deploying these for commercial gene therapy production, pushed by FDA contamination control guidance.
- Semi-Automatic Fillers:Intermediate systems bridging manual and fully automatic operation for mid-scale batches.
- Manual Fillers:Benchtop units reserved for clinical trial material and early-phase development.
Mature deployment sits with automatic fillers. Newer deployment is concentrated in robotic fillers.
Technology:
Aseptic architectures command margin premiums while non-aseptic systems serve cost-sensitive therapeutic categories.
- Aseptic Filling:Isolator or restricted access barrier systems maintaining ISO 5 environments with continuous particle monitoring. EU GMP Annex 1 revisions are mandating these architectures across European biotech facilities, particularly for cell therapy manufacturing.
- Vacuum Filling:Negative-pressure dosing for viscous or foam-prone formulations with precise volume control. Demand clusters in hormone and biologic infusions where product integrity demands gentle handling.
- Non-Aseptic Filling:Conventional cleanroom-based processing for terminally sterilized products.
- Pressure Filling:Positive-displacement systems for high-speed liquid dosing.
Established infrastructure favors aseptic filling. Fastest capability expansion is occurring in vacuum filling.
End User:
Pharmaceutical companies anchor capital expenditure while biotech firms drive specification innovation.
- Pharmaceutical Companies:In-house fill-finish operations for blockbuster biologics with dedicated high-speed lines. Investment concentrates in German precision engineering clusters where automation integration reaches maximum sophistication.
- Biotech Firms:Flexible aseptic processing for personalized medicine and ATMP manufacturing. The Boston-Cambridge corridor is consolidating procurement around turnkey robotic platforms capable of rapid changeover for patient-specific batches.
- Contract Manufacturing Organizations:Multi-product facilities serving outsourced fill-finish demand.
- Research Laboratories:Small-scale systems for preclinical and clinical material preparation.
Capacity ownership rests with pharmaceutical companies. Specification leadership is shifting toward biotech firms.
Application:
Vaccine production sustains volume demand while antibody manufacturing commands equipment complexity premiums.
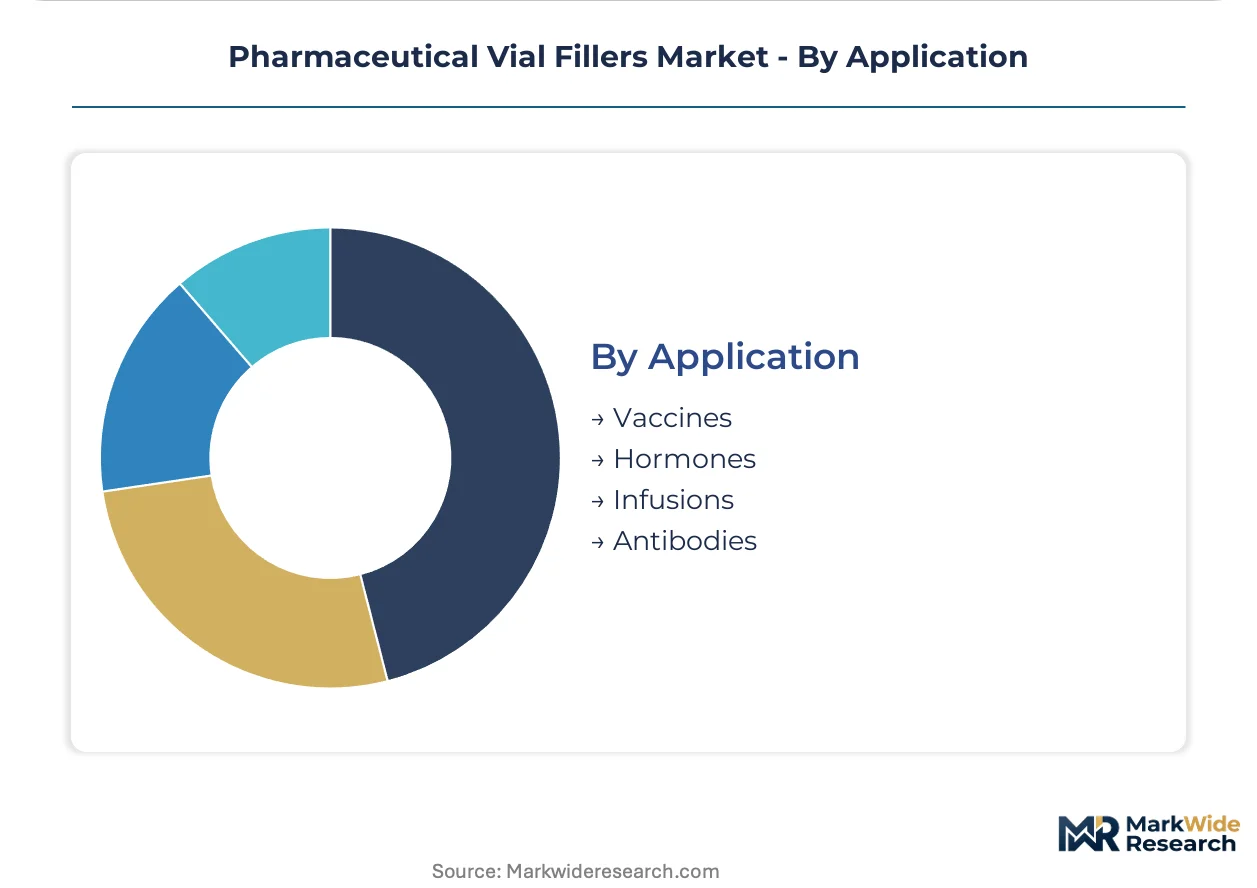
- Vaccines:Large-scale aseptic filling for pandemic preparedness and routine immunization programs. Fill-finish lines in India and Brazil are expanding capacity to meet national immunization targets and export commitments.
- Antibodies:High-containment processing for monoclonal and bispecific antibodies requiring precise dosing and minimal shear. Swiss and German facilities are integrating lyophilization to reduce aseptic transfers for temperature-sensitive molecules.
- Hormones:Specialized handling for potent small-volume parenterals.
- Infusions:Large-volume parenteral filling for hospital supply.
Volume concentration sits with vaccines. Complexity premiums are highest in antibodies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters around Stuttgart and Munich operate within designated high-tech manufacturing zones that attract specialized automation suppliers. These tax-advantaged districts concentrate vial filling equipment development for complex biologics manufacturing.
United States
FDA contamination control guidance drives biotech firms toward isolator-integrated robotic fillers for gene therapy production. The agency's updated aseptic processing expectations mandate continuous environmental monitoring systems. Massachusetts and North Carolina contract manufacturers deploy gloveless filling platforms for commercial-scale cell therapy batches.
Germany
EMA sterility assurance requirements for ATMP manufacturing reshape equipment qualification protocols across Bavarian and Baden-Württemberg facilities. EU GMP Annex 1 revisions accelerate isolator adoption over conventional cleanroom architectures. Stuttgart precision engineering suppliers prototype high-speed automation for monoclonal antibody fill-finish lines.
Switzerland
Swissmedic tightened expectations for biologic manufacturing push Basel and Zurich facilities toward combined filling-lyophilization integration. The regulator's emphasis on reduced aseptic transfers influences barrier system selection for temperature-sensitive molecules. Swiss pharmaceutical clusters anchor European supply for high-containment antibody processing equipment.
India
CDSCO alignment with international PIC/S standards drives contract manufacturers toward modular skid-mounted filler validation. The country's national pharmaceutical regulator accelerates timelines for facilities serving export markets. Gujarat and Maharashtra production hubs expand capacity for vaccine fill-finish operations targeting immunization programs.
Pharmaceutical Vial Fillers Market Competitive Landscape
Top-tier vendors anchor isolator-integrated platform supply, while mid-scale specialists occupy modular and semi-automatic segments. The vendor base stratifies across three capability bands: full-line turnkey providers, precision component fabricators, and regional system integrators. Strategic archetypes include German precision engineering houses, Italian pharmaceutical machinery specialists, and North American robotic automation firms. Competitive moves concentrate on technology licensing partnerships and backward integration into critical component supply.
Within the European precision machinery tier, Syntegon GmbH and IMA Life S.p.A. exemplify full-line responsibility models that contract for throughput guarantees and multi-year service commitments. Vanrx Pharmasystems Inc. occupies a specialized position among North American robotic automation providers serving gloveless isolator applications. These three entities represent distinct competitive positioning vectors: German engineering integration, Italian pharmaceutical machinery heritage, and Canadian-born robotic specialization subsequently absorbed into broader automation portfolios.
| Leading Market Players |
|---|
| Syntegon |
| IMA Life |
| Groninger |
| Romaco |
| Dara Pharma |
| Harro Höfliger |
| ACG Worldwide |
| Bausch+Strobel |
| Vanrx Pharmasystems Inc. |
| Others |
Value Network & Pricing Analysis
Specialized aseptic engineering talent concentrated in Stuttgart and Munich creates labor-cost differentials that widen pricing-tier spreads between German-engineered isolator platforms and modular skid-mounted alternatives sourced from lower-cost manufacturing hubs.
Pricing Analysis
Lead-time premiums command substantial markups for rapid-deployment isolator-integrated fillers, while spot-inventory discounts apply to standardized automatic rotary systems with shorter configuration cycles. Three-tier pricing structure across premium isolator platforms, standard modular lines, and economy semi-automatic units reflects certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because contract manufacturers in India and Brazil prioritize capital efficiency over containment sophistication. Biotech firms in the Boston-Cambridge corridor show least price sensitivity, accepting premium positioning for gloveless robotic systems that eliminate human intervention.
Supply Chain Analysis
Certification and qualification gating from FDA and EMA sterility assurance requirements restricts supplier participation to fabricators with documented barrier system validation histories. Premium-grade 316L stainless steel for product-contact surfaces draws from concentrated European and Japanese mill capacity, creating sourcing bottlenecks for rapid capacity expansion. Supply chain risk centers on single-source vulnerability for precision dosing pumps and isolator glove ports. Distribution runs through direct vendor relationships with full-line responsibility contracts rather than component sourcing through distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical vial fillers market sits in a pronounced technology-transition phase, with gloveless isolator-integrated robotic systems displacing conventional cleanroom-based filling architectures across gene therapy and cell therapy manufacturing.
For Market Incumbents: To counter modular skid-mounted entrants from emerging manufacturing hubs, anchor market position through backward integration into critical component supply for precision dosing pumps and isolator barrier systems. Accelerate capacity addition in Bavarian precision engineering clusters to capture EMA-driven ATMP equipment qualification demand. Certification investment in EU GMP Annex 1 compliance documentation creates switching costs that protect installed base revenues. For New Entrants and Emerging Players: Biotech contract manufacturers in Massachusetts and North Carolina represent the most penetrable channel partner type for establishing commercial reference sites. Target small-scale robotic filler deployments for patient-specific cell therapy batches where rapid changeover capabilities outweigh throughput specifications. White-space opportunity exists in energy-efficient isolator designs that qualify for EU Green Deal sustainability-linked financing instruments. For Investors and Strategic Acquirers: The window for entry favors specialized robotic automation firms with proven gloveless isolator deployments ahead of FDA enforcement timeline acceleration. Long-term viability hinges on acquisition targets possessing validated contamination control strategy documentation rather than equipment-only revenue models. Watch for inflection signals in EMA sterility assurance inspection findings that accelerate replacement demand for legacy cleanroom architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Platform Development | FDA contamination control guidance mandates closed-system architectures for commercial gene therapy production. |
| Precision Component Backward Integration | Captive supply of 316L stainless steel product-contact surfaces mitigates mill capacity bottlenecks. |
| Modular Skid-Mounted Line Expansion | Pre-validated containerized fillers slash deployment time for CDSCO-aligned Indian contract manufacturers. |
| EU Green Deal Alignment Certification | Energy-efficient isolator designs unlock sustainability-linked financing for European biotech facility investments. |
| Multi-Format Changeover Capability Investment | Rapid vial size and closure type flexibility addresses personalized medicine batch fragmentation. |
Research Methodology
Regulatory filings, equipment qualification documentation, and pharmaceutical manufacturing trade data formed the secondary backbone, supplemented by primary interviews with fill-finish engineering directors, aseptic processing consultants, biotech procurement leads, and contract manufacturing executives. Bottom-up triangulation across installed base volumes and top-down validation against capital expenditure patterns anchored market sizing. Cross-referencing FDA 483 observation trends with EMA inspection findings provided demand signal calibration for isolator adoption rates.
Historical trendline analysis of automatic versus robotic filler deployment ratios informed projection modeling across the analysis window. Segmentation dimensions included equipment type, technology architecture, end-user category, and therapeutic application with regional regulatory cluster overlays. CAGRs derived from capacity expansion announcements, facility investment disclosures, and supplier order backlog patterns. Forecast inputs incorporated EU GMP Annex 1 revision implementation timelines and FDA aseptic processing guidance enforcement intensity.
Caveats apply where EMA sterility assurance inspection stringency or FDA contamination control strategy documentation requirements could materially shift the outlook. Forecasts reflect assumptions regarding stainless steel supply availability and specialized aseptic engineering workforce expansion. A model refresh is warranted upon material change in ATMP manufacturing regulatory harmonization across European and North American jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market