
 Injection Bottles Market | 2026-2036
Injection Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Bottles Market Foresight
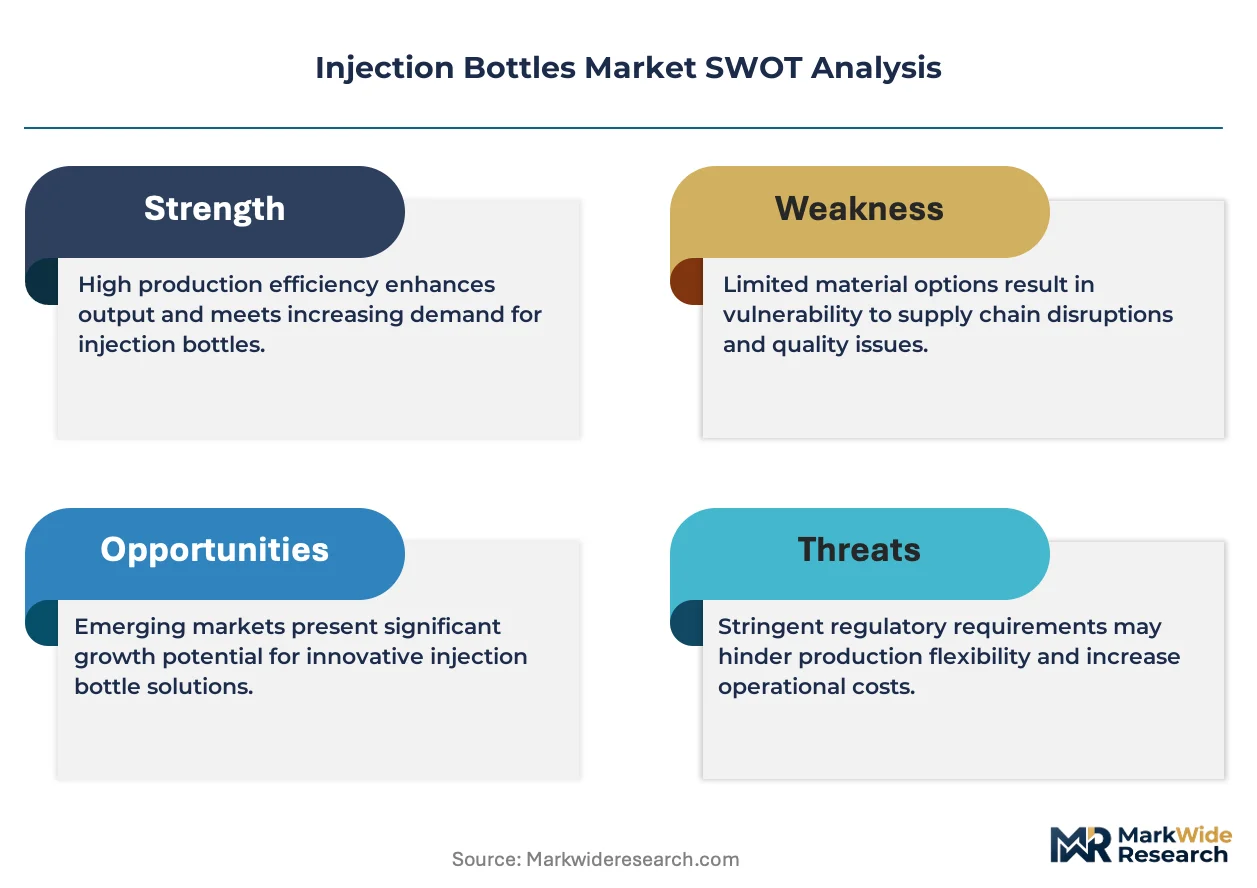
The gap between premium and commodity tiers is broadening as biologic drugs require advanced barrier properties while generic injectables compete on cost. SCHOTT AG leverages its borosilicate expertise to dominate high-value pharma segments. Gerresheimer AG anchors European supply through integrated glass-forming and pharmaceutical finishing capabilities. Bormioli Pharma differentiates via specialized coating technologies for sensitive drug formulations.
Injection bottles are sealed containers manufactured from borosilicate glass or engineered polymers, designed to maintain sterility and chemical stability for parenteral drug storage, typically ranging from 2 mL to 100 mL in fill volume. Pre-filled formats command premium positioning as pharmaceutical companies outsource final assembly steps to packaging specialists. Glass materials sustain dominant share in biologics applications where inertness and extractables control prove critical. Multi-dose configurations face structural pressure from single-use safety regulations while compounding segments expand in hospital settings.
FDA's Container Closure Guidance and EMA's Annex 1 revision on sterile manufacturing both elevate validation requirements for primary packaging materials. USP Chapter 660 and EP 3.2.1 standards govern glass hydrolytic resistance, directly filtering which suppliers qualify for regulated drug markets. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables as novel biologic modalities enter commercial scale-up.
Market Dynamics
Biologics manufacturing is forcing a split in material specifications, with high-barrier borosilicate glass separating from commodity polymer alternatives as drug sponsors outsource final assembly to specialized packaging integrators.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile manufacturing guidelines mandate enhanced container closure integrity validation, pushing pharmaceutical sponsors toward pre-qualified, ready-to-fill formats that reduce in-house qualification burden.
- Cell and Gene Therapy Expansion:Commercial scale-up of personalized medicine modalities requires ultra-low extractable glass and specialized coating technologies that standard vial formats cannot satisfy.
- Germany's Pharmaceutical Manufacturing Corridor:Concentrated biologics production around Frankfurt and Heidelberg generates localized demand for integrated glass-forming and pharmaceutical finishing capabilities.
Market Restraints
- Borosilicate Sand Supply Concentration:High-purity raw material sourcing concentrates in limited geographic deposits, exposing converters to input volatility and qualification delays for alternative suppliers.
- EU F-Gas Regulation Compliance:Tightening restrictions on fluorinated greenhouse gases complicates manufacturing processes for certain polymer barrier coatings and sterilization cycles.
- Glass Breakage Risk in Cold Chain:Ultra-low temperature storage requirements for mRNA and cell therapies expose limitations in conventional glass thermal shock resistance, driving substitution interest.
Strategic Opportunities
- Indian CDMO Expansion:Contract development and manufacturing organizations in India are scaling sterile injectable capacity, creating demand for qualified primary packaging partners under CDSCO oversight.
- Ready-to-Administer Formats:Pre-filled bottles with integrated transfer devices eliminate compounding steps, aligning with hospital pharmacy efficiency mandates and safety protocols.
- Sustainability-Linked Procurement:Pharmaceutical sponsors are embedding carbon footprint criteria into supplier scorecards, rewarding converters with renewable energy glass melting and reduced transport emissions.
Industry Challenges
- Extractables and Leachables Validation:Novel biologic modalities require extended migration studies that extend qualification timelines and strain analytical chemistry capacity at contract laboratories.
- Serialization Integration:Aggregation requirements under the EU Falsified Medicines Directive and similar frameworks demand capital-intensive line upgrades for glass and polymer converters alike.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Bottles Market |
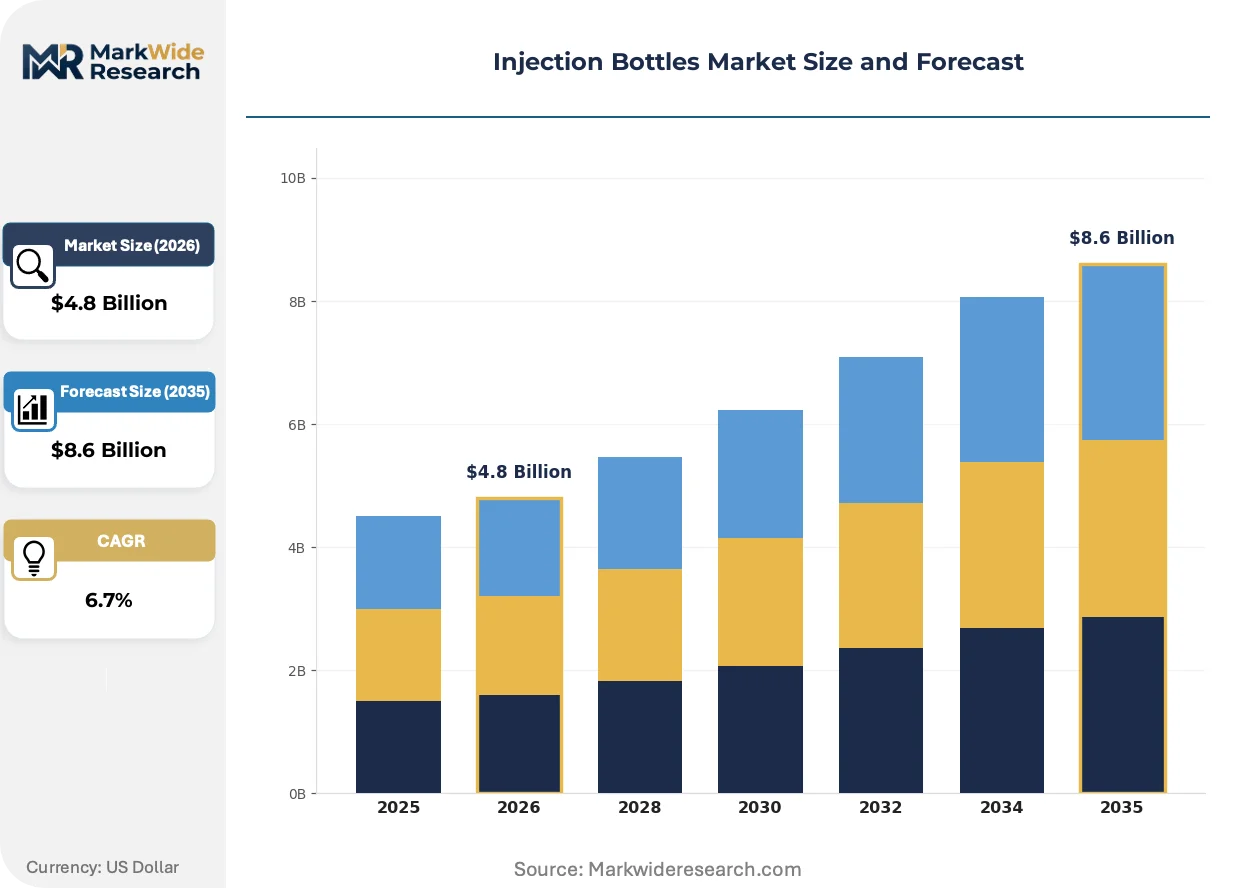
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose, Multi-dose, Pre-filled, Compounding Material: Glass, Plastic, Polymer, Rubber End User: Pharmacies, Clinics, Hospitals, Research Labs Packaging Type: Bulk, Blister, Vial, Carton |
| Companies Covered | Gerresheimer AG, SCHOTT AG, Nipro Corporation, Bormioli Pharma, West Pharmaceutical Services, SGD Pharma, Stevanato Group, Origin Pharma Packaging, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Bottles Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape competitive positioning, with barrier performance and sustainability credentials becoming primary differentiation vectors.
Cyclic olefin polymer (COP) and cyclic olefin copolymer (COC) formulations are rewriting performance expectations for sensitive biologics. These engineered polymers deliver glass-like inertness with superior break resistance and design flexibility. Large-molecule drug sponsors are adopting COP vials for proteins requiring sub-zero storage. This shift is compressing the addressable market for traditional borosilicate in temperature-critical applications.
Europe's MDR and F-Gas Regulation are tightening material compliance requirements for sterile packaging placed on the EU market. Medical device classification of certain drug-container combinations elevates quality management system obligations and post-market surveillance duties. German and French pharmaceutical manufacturers are prioritizing suppliers with established notified body relationships and EU MDR technical documentation.
Hospital pharmacy consolidation is altering procurement patterns for multi-dose and compounding formats. Integrated delivery networks in the United States are centralizing sterile compounding operations, reducing SKU diversity and demanding volume commitments from packaging suppliers. This concentration favors converters with flexible manufacturing platforms and regional distribution hubs over fragmented, specialty-focused competitors.
Injection Bottles Market Segmentation
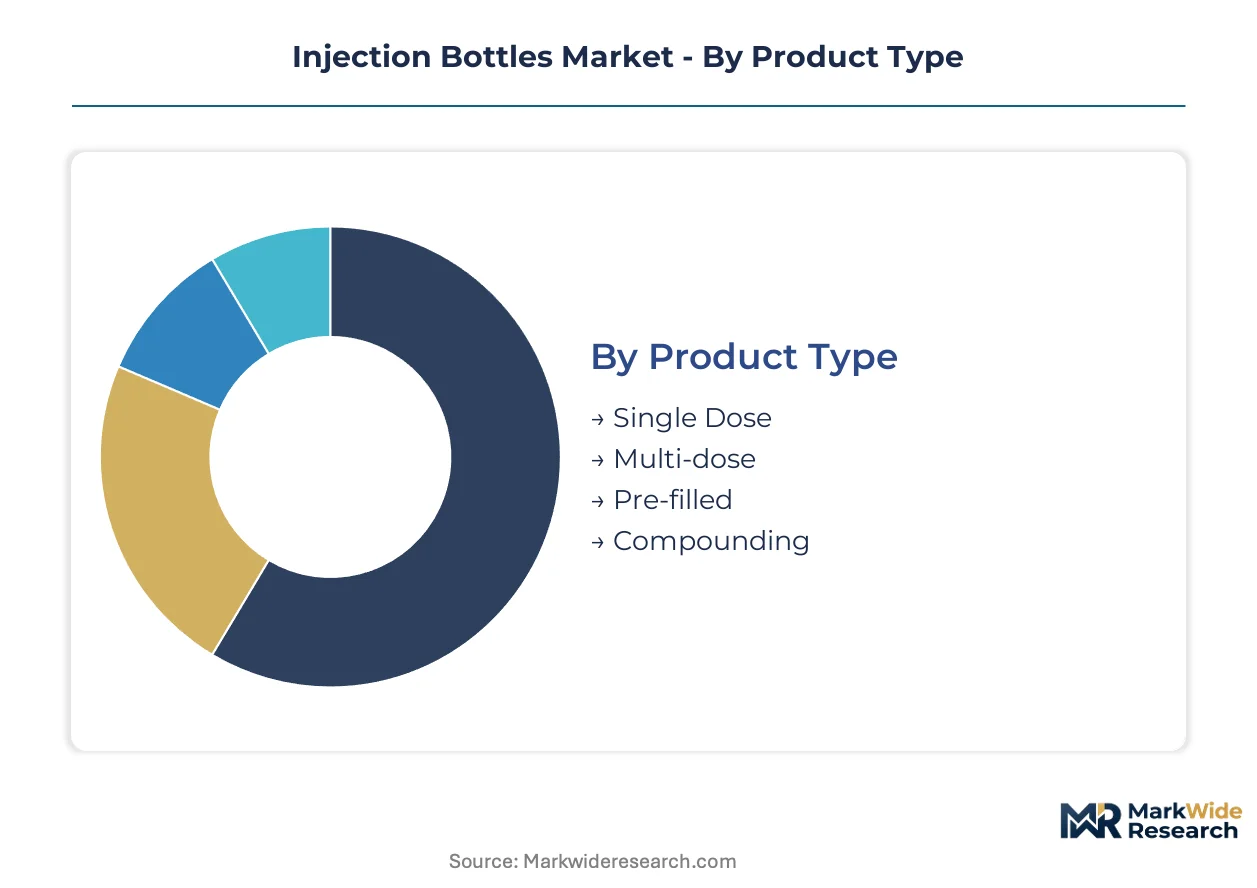
Injection bottles segment across functional, material, and channel dimensions that determine barrier requirements, sterilization protocols, and supply chain configuration. Each axis carries distinct regulatory burdens and margin profiles that shape converter specialization strategies.
Product Type:
Ready-to-fill formats are displacing conventional empty containers as pharmaceutical sponsors outsource final assembly to packaging integrators with validated sterile filling lines.
- Pre-filled:Sealed containers supplied with drug product already loaded, eliminating compounding steps and reducing contamination risk. Demand concentrates in biologics manufacturing corridors around Frankfurt and Heidelberg where integrated glass-forming and pharmaceutical finishing capabilities anchor supply. EMA Annex 1 revision on sterile manufacturing elevates validation requirements that favor pre-qualified formats.
- Single Dose:Unitary containers designed for one-time administration, typically 2-10 mL fill volumes. Safety regulations across Germany, France, and the United States are compressing multi-dose configurations while hospital pharmacy consolidation drives volume procurement of standardized single-use formats.
- Multi-dose:Larger capacity bottles with preservative systems enabling multiple withdrawals. Bacterial contamination protocols and needlestick prevention mandates are restricting applications to specific therapeutic categories with established antimicrobial validation.
- Compounding:Empty containers supplied to hospital and specialty pharmacies for sterile preparation. Centralization of sterile compounding operations within integrated delivery networks is concentrating procurement among converters with flexible manufacturing platforms.
Pre-filled leads on scale; single dose leads on momentum.
Material:
Cost tiers separate premium barrier specifications from commodity alternatives as drug modality requirements diverge.
- Glass:Borosilicate formulations deliver inertness and extractables control critical for protein stability. USP Chapter 660 and EP 3.2.1 hydrolytic resistance standards filter supplier qualification for regulated markets, with high-purity sand sourcing concentrating in limited geographic deposits.
- Polymer:Cyclic olefin polymer (COP) and cyclic olefin copolymer (COC) formulations provide break resistance and design flexibility for sub-zero storage applications. Large-molecule drug sponsors are adopting engineered polymers where thermal shock resistance limitations of conventional glass expose cold chain vulnerabilities.
- Plastic:Commodity thermoplastics for generic injectables competing on cost with reduced barrier requirements. Volume production concentrates in converters serving high-throughput, low-margin therapeutic categories with established extractables profiles.
- Rubber:Elastomeric closures and septa formulations providing resealability for multi-dose configurations. EU F-Gas Regulation compliance complicates manufacturing processes for certain barrier coatings and sterilization cycles.
Glass dominates revenue concentration; polymer is climbing the fastest.
End User:
Customer type determines order pattern, SKU complexity, and technical service intensity across the value chain.
- Hospitals:Centralized procurement through integrated delivery networks demanding volume commitments and regional distribution hubs. Ready-to-administer formats with integrated transfer devices align with pharmacy efficiency mandates and safety protocols.
- Clinics:Outpatient settings requiring standardized formats with simplified handling characteristics. Procurement runs through group purchasing organizations with formulary restrictions on container specifications.
- Pharmacies:Retail and specialty channels with compounding capabilities for personalized medicine. Serialization requirements under the EU Falsified Medicines Directive demand aggregation-capable line infrastructure.
- Research Labs:Preclinical and clinical trial supply with small-batch, high-SKU diversity. Flexible manufacturing platforms and rapid qualification timelines distinguish suppliers serving this segment.
Hospitals anchor volume procurement; research labs show steepest expansion trajectory.
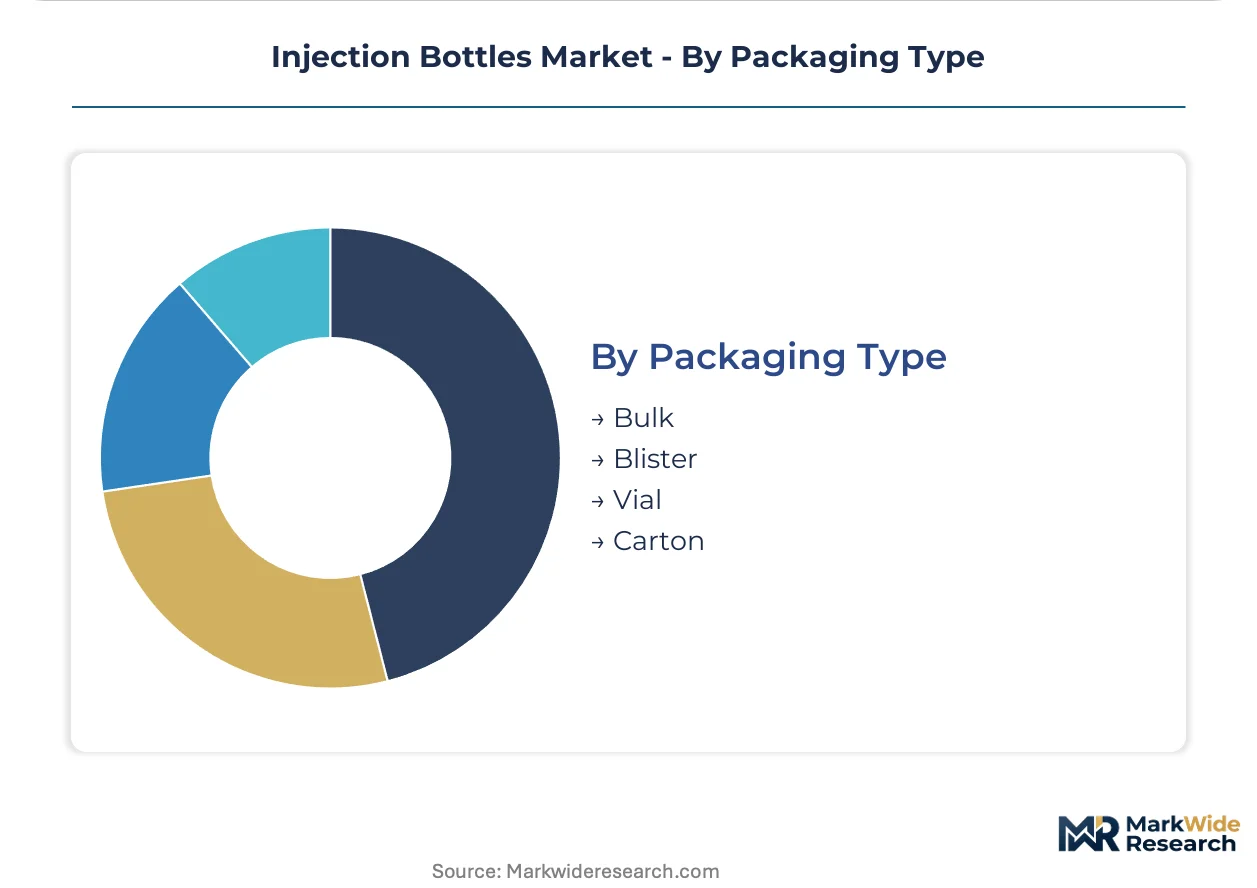
Packaging Type:
Distribution configuration reflects sterilization method, shelf-life requirements, and downstream automation compatibility.
- Vial:Primary container format with established filling line compatibility across pharmaceutical manufacturing. Borosilicate and engineered polymer variants segment by barrier performance tier.
- Blister:Individual unit protection with tamper-evident characteristics. Secondary packaging integration with pre-filled syringes and auto-injector systems drives specification complexity.
- Carton:Tertiary packaging with serialization aggregation and patient information integration. Sustainability-linked procurement embeds carbon footprint criteria into supplier scorecards.
- Bulk:Unpackaged containers for downstream sterilization and filling operations. CDMO expansion in India creates demand for qualified primary packaging partners under national pharmaceutical regulator oversight.
Vial holds installed base dominance; blister is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-tier demand through its pharmaceutical manufacturing corridor, while India scales contract manufacturing capacity under CDSCO oversight. Market maturity diverges sharply between established biologics clusters and emerging sterile injectable hubs.
United States
FDA Container Closure Guidance elevates validation requirements for primary packaging materials, pushing sponsors toward pre-qualified formats. Hospital pharmacy consolidation through integrated delivery networks concentrates procurement among converters with regional distribution infrastructure. The Greater Boston biotech cluster generates specialized demand for ultra-low extractable glass in cell therapy applications.
Germany
EMA Annex 1 revision mandates enhanced container closure integrity validation, favoring ready-to-fill formats that reduce in-house qualification burden. EU F-Gas Regulation compliance tightens material requirements for sterile packaging placed on the EU market. The Frankfurt-Heidelberg pharmaceutical manufacturing corridor anchors European supply through integrated glass-forming and pharmaceutical finishing capabilities.
India
CDSCO oversight of contract development and manufacturing organizations scales sterile injectable capacity for export markets. Pharmaceutical sponsors embed carbon footprint criteria into supplier scorecards, rewarding converters with renewable energy glass melting. Gujarat and Maharashtra host expanding sterile packaging operations serving both domestic and regulated export destinations.
China
NMPA standards for glass hydrolytic resistance filter supplier qualification for domestic regulated markets. Dual carbon goals drive investment in renewable energy glass melting technologies among domestic converters. The Yangtze River Delta concentration of biologics manufacturing generates localized demand for high-barrier primary packaging.
Switzerland
Swissmedic oversight of novel biologic modalities requires extended extractables and leachables validation studies. Medical device classification of certain drug-container combinations elevates quality management system obligations. The Basel pharmaceutical cluster demands specialized coating technologies for sensitive protein formulations.
Injection Bottles Market Competitive Landscape
Top-tier vendors anchor premium barrier specifications, while mid-scale converters serve commodity generic segments. The market structure consolidates around three to four integrated players with captive glass-forming capabilities, alongside specialized coating technology providers. Strategic archetypes separate borosilicate specialists, polymer barrier innovators, and integrated pharmaceutical finishing operators. Dominant competitive moves include backward integration into high-purity sand sourcing and capacity expansion in India's sterile packaging corridor.
Within the integrated glass-forming tier, Gerresheimer AG and SCHOTT AG occupy positions exemplifying European pharmaceutical finishing capabilities. Bormioli Pharma represents the specialized coating technology archetype for sensitive drug formulations. These three anchors demonstrate how geographic concentration around regulatory hubs combines with material science differentiation to structure competitive positioning.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT AG |
| Nipro Corporation |
| Bormioli Pharma |
| West Pharmaceutical Services |
| SGD Pharma |
| Stevanato Group |
| Origin Pharma Packaging |
| Berry Global |
| Others |
Supply & Pricing Matrix
Pharmaceutical sponsor consolidation around ready-to-fill formats forces supply base rationalization, with EMA Annex 1 validation requirements filtering qualified converters and compressing procurement options for high-barrier specifications.
Pricing Analysis
Capacity additions in India are reshaping price floors for commodity-grade polymer containers while premium borosilicate glass maintains structural scarcity. Three-tier pricing structure across premium, standard, and economy levels separates USP Chapter 660-certified borosilicate from EP 3.2.1-compliant alternatives and unqualified commodity formats. Pricing pressure stems from CDSCO-registered Indian CDMOs scaling sterile injectable capacity for export markets. Generic injectable sponsors demonstrate highest price sensitivity, while cell and gene therapy developers prioritize extractables control over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's biologics sector and India's pharmaceutical procurement policies are reshaping sourcing patterns for multinational sponsors. High-purity borosilicate sand concentrates in Germany, the United States, and select Chinese deposits, while engineered polymer resin production centers on Japan, South Korea, and Germany. Converter networks draw from limited qualified glass-forming facilities, creating single-source vulnerability for EMA-notified body-certified suppliers. Distribution runs through regional pharmaceutical manufacturing corridors with validated sterile filling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The injection bottles market functions as a stable compounder anchored by irreversible biologics outsourcing trends and tightening pharmacopeial standards that perpetually renew qualification barriers.
For Market Incumbents: Hedge borosilicate glass exposure by diversifying into COP barrier technologies before cold-chain substitution accelerates. Secure backward integration into high-purity sand deposits to defend input cost position against raw material volatility. Prioritize EMA-notified body relationship maintenance as MDR technical documentation requirements elevate compliance fixed costs for smaller competitors.
For New Entrants and Emerging Players: Compounding pharmacies within integrated delivery networks represent an underserved buyer archetype demanding flexible manufacturing platforms and rapid SKU turnaround. Target research lab supply segments with small-batch, high-diversity requirements that established converters deprioritize. Pursue coating technology specialization for protein-sensitive formulations rather than competing on commodity glass volume.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating technology providers serving novel biologic modalities requiring extended extractables validation. Five-to-ten-year viability favors converters with established EU MDR technical documentation and renewable energy glass melting capabilities. Monitor CDSCO registration timelines for Indian sterile packaging facilities as inflection indicator for supply base geographic diversification.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Notified Body Certification | MDR technical documentation unlocks premium-tier pharmaceutical sponsor procurement. |
| Renewable Energy Glass Melting | Carbon footprint criteria in sponsor scorecards reward low-emission borosilicate production. |
| COP Barrier Technology Investment | Sub-zero storage requirements for mRNA therapies drive polymer substitution in cold chain. |
| Indian CDSCO Registration | Contract manufacturing expansion creates qualified packaging demand under national regulator oversight. |
| Ready-to-Administer Format Development | Integrated transfer devices align with hospital pharmacy efficiency mandates and safety protocols. |
Research Methodology
Multiple input streams — primary interviews, regulatory filing analysis, and trade data reconciliation — were reconciled to construct market estimates. Conversations with pharmaceutical packaging procurement managers, regulatory affairs specialists at drug sponsors, glass-forming plant engineers, and CDMO supply chain directors informed demand-side validation. Secondary sources included FDA Container Closure Guidance documents, EMA Annex 1 revision texts, USP and EP pharmacopeial standards, and national pharmaceutical regulator filings. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level outputs.
Data-stream reconciliation applied across the analysis window linked patient population forecasts to drug launch pipelines, then to primary packaging unit requirements. Segmentation dimensions modeled included product type, material specification tier, end-user channel, and regional regulatory cluster. CAGRs were derived from weighted average of historical trend extrapolation and demand driver elasticity estimates. Industry-specific inputs incorporated biologics capacity expansion timelines and pharmacopeial standard revision schedules.
Underlying measurement precision varies by segment; pre-filled and single-dose formats carry tighter precision than compounding categories due to disclosed contract manufacturing volumes. Forecasts reflect documented assumptions regarding regulatory implementation timing and sponsor outsourcing propensity. Biologic modality failure rates, sand supply disruptions, or MDR enforcement variability could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market