
 Tablets and Capsules Packaging Market | 2026-2036
Tablets and Capsules Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tablets and Capsules Packaging Market Analytics
Smart packaging integration with embedded NFC tags and temperature-sensitive inks is reshaping how pharmaceutical supply chains verify authenticity and monitor cold chain integrity. Amcor leverages its global film extrusion network to supply high-barrier blister foils across multiple continents. WestRock anchors North American demand through its paperboard-based compliance packaging for chronic medication adherence programs. Berry Global competes aggressively in child-resistant closure systems for over-the-counter bottles.
Tablets and capsules packaging encompasses primary and secondary containment systems engineered to protect oral solid dosage forms from moisture, oxygen, and light degradation, typically employing aluminum-polymer laminates with water vapor transmission rates below 0.1 grams per square meter per day to ensure 24-to-36-month shelf stability. Blister packs dominate unit-dose dispensing in regulated markets due to their tamper-evidence and adherence-tracking advantages, while bottles retain cost leadership in high-volume generic markets where manufacturing scale drives per-unit economics. Plastic materials, particularly PVC and PVDC coextrusions, command the largest material share by volume, though aluminum lidding foils capture disproportionate margin pools in specialty barrier applications.
FDA's Drug Supply Chain Security Act and EMA's Falsified Medicines Directive compel packagers to incorporate serialized 2D barcodes and tamper-evident features, directly elevating capital equipment requirements and supplier qualification burdens. India's CDSCO and BIS enforce incremental barrier standards for moisture-sensitive APIs, redirecting domestic procurement toward imported high-performance films. Stakeholders must monitor evolving serialization deadlines and material substitution risks as sustainability mandates from EU Green Deal and state-level extended producer responsibility laws in California and New York reshape acceptable packaging formats.
Market Dynamics
Serialization mandates from FDA and EMA are compressing supplier qualification timelines while blister pack procurement concentrates among high-volume oral solid dosage manufacturers in India and Brazil, creating a bifurcation between compliance-ready and legacy packaging operations.
Growth Catalysts
- Track-and-trace mandates:FDA's Drug Supply Chain Security Act and EMA's Falsified Medicines Directive compel packagers to embed serialized 2D barcodes, expanding equipment upgrade cycles across contract manufacturing organizations.
- Chronic medication adherence programs:Paperboard compliance packaging for multi-dose regimens is gaining traction among Medicare Advantage plans and European pharmacy chains managing polypharmacy populations.
- High-barrier film demand:Maharashtra and São Paulo clusters are redirecting procurement toward aluminum-polymer laminates with sub-0.1 g/m²/day moisture transmission rates to protect moisture-sensitive APIs.
Market Restraints
- Aluminum foil supply concentration:Lidding foil production clusters in China and Russia expose pharmaceutical packagers to raw material allocation risks and tariff volatility.
- Capital equipment intensity:Serialization-ready blister lines require qualification investments that exclude mid-tier generic manufacturers from regulated market supply chains.
- PVC substitution pressure:EU Green Deal extended producer responsibility laws are accelerating material transitions before PVDC coextrusion alternatives achieve cost parity.
Strategic Opportunities
- North Carolina corridor expansion:The Research Triangle's contract manufacturing density supports localized blister pack supply with 24-hour logistics reach to major distribution hubs.
- NFC-integrated authentication:Convergence of near-field communication tags with temperature-sensitive inks enables real-time cold chain verification for biologic oral solids.
- Direct-to-pharmacy distribution:Bypassing wholesale intermediaries allows packagers to capture margin pools previously allocated to distributor markups in consolidated European pharmacy markets.
Industry Challenges
- Serialization engineering talent scarcity:Packagers face recruitment friction for professionals fluent in both pharmaceutical quality systems and industrial automation architecture.
- Legacy line retrofit complexity:Integrating track-and-trace modules with existing thermoforming equipment demands extended validation timelines that compress production windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablets and Capsules Packaging Market |
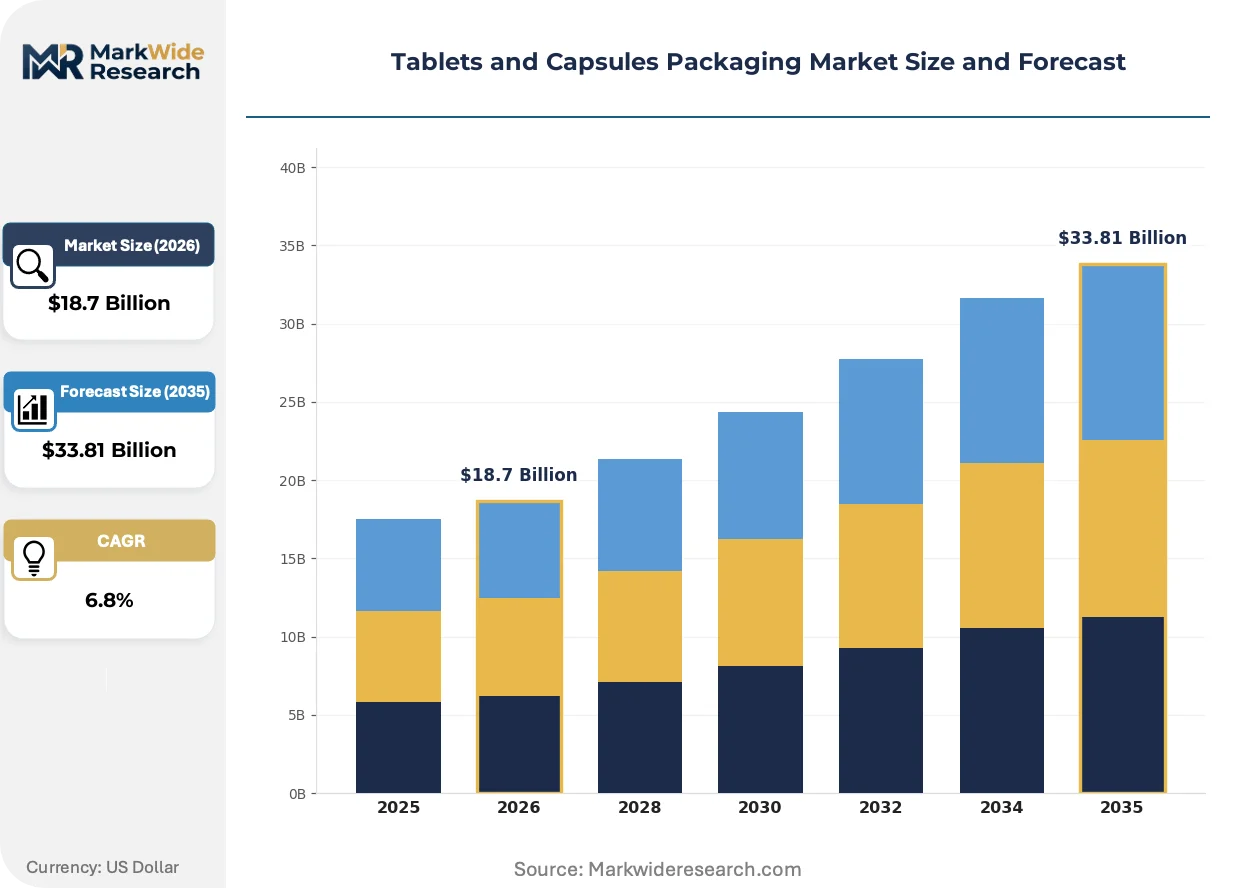
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Bottles, Sachets, Pouches Material: Plastic, Glass, Aluminum, Paper End User: Pharmaceuticals, Nutraceuticals, Over-the-Counter, Veterinary Closure Type: Screw Caps, Flip Tops, Snap Caps, Shrink Bands |
| Companies Covered | Amcor, WestRock, Berry Global, Constantia Flexibles, Huhtamaki, Sonoco, Klöckner Pentaplast, Tekni-Plex, Bilcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablets and Capsules Packaging Market Evolving Landscape
Digital authentication layers and sustainable material transitions are compressing traditional packaging procurement cycles while elevating technical qualification thresholds for supplier selection.
Blockchain-anchored serialization is virtualizing supply chain verification by creating immutable provenance records for each blister cavity. Large pharmaceutical manufacturers are piloting these systems for high-value specialty oral solids. The technology is virtualizing the role of physical tamper-evidence features by shifting trust mechanisms to distributed ledger verification.
EMA's Falsified Medicines Directive enforcement deadlines are accelerating capital deployment toward aggregation-capable packaging lines. The regulation mandates end-to-end traceability from manufacturer to dispenser, forcing contract packagers to requalify equipment stacks. European generic manufacturers with limited serialization experience are outsourcing to specialized contract packaging organizations to meet compliance windows.
Hospital and long-term care facilities are consolidating oral solid dosage procurement through central pharmacy models that favor unit-dose blister packs over traditional bottle dispensing. This channel compression is displacing high-volume bottle contracts with multi-year adherence packaging agreements. The shift is most pronounced in Germany and the Netherlands where pharmacy automation infrastructure supports high-throughput blister dispensing.
Tablets and Capsules Packaging Market Segmentation
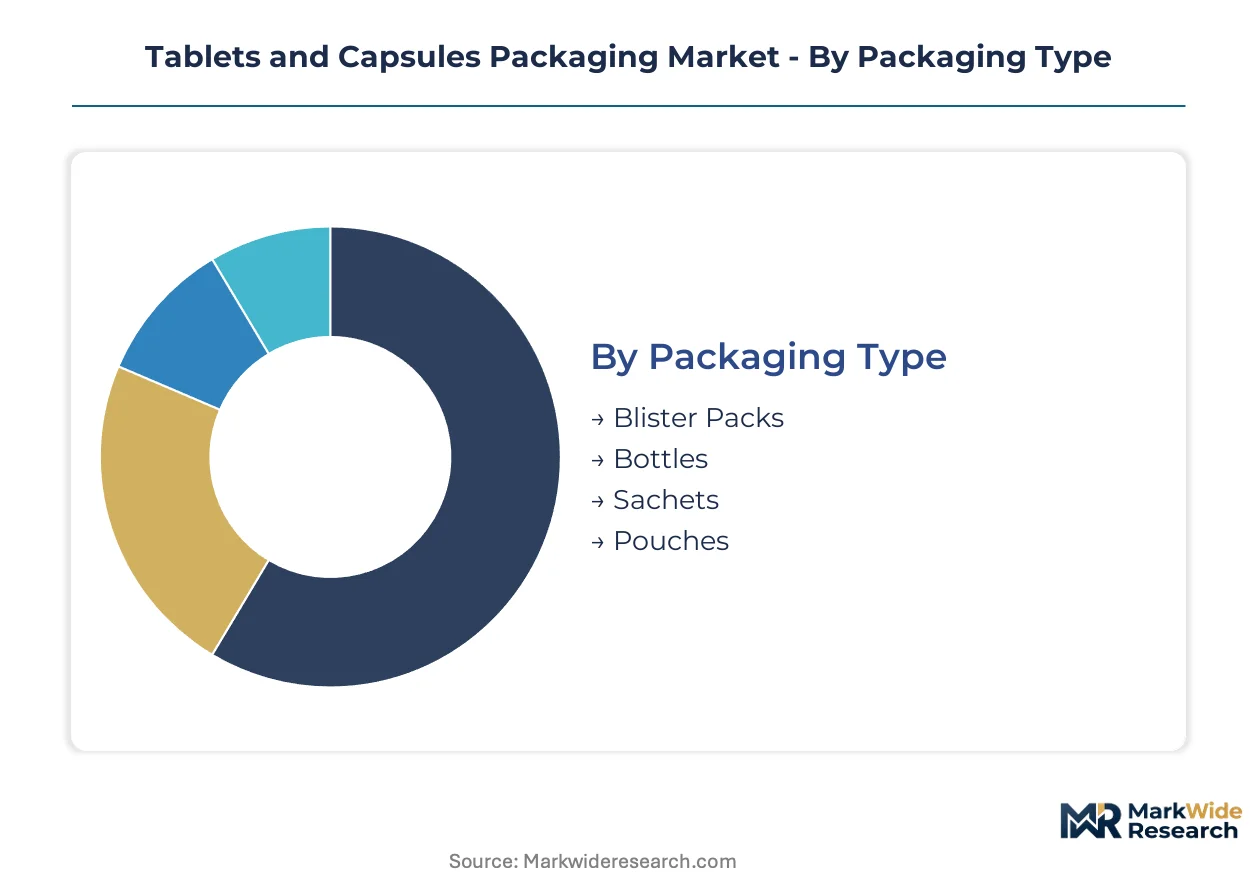
Segmentation in tablets and capsules packaging reveals divergent capital cycles and qualification burdens across containment formats. Material selection and end-use requirements create distinct procurement rhythms that suppliers must synchronize with pharmaceutical manufacturing schedules.
Packaging Type:
Blister packs turn inventory fastest in regulated markets with serialization mandates, while bottles sustain longer production runs in high-volume generic corridors.
- Blister Packs:Aluminum-polymer laminates with thermoformed PVC or PVDC cavities deliver unit-dose tamper evidence and adherence tracking. Demand clusters in Maharashtra and North Carolina contract manufacturing zones where FDA and EMA track-and-trace deadlines compress supplier qualification timelines.
- Bottles:HDPE and PET containers with child-resistant closures dominate high-volume oral solid dosage production in Brazil's São Paulo corridor. Per-unit economics favor bottles for 90-day chronic medication fills where manufacturing scale offsets serialization equipment amortization.
- Sachets:Single-dose foil-laminate strips serve emerging market sample distribution and veterinary applications.
- Pouches:Multi-layer flexible bags accommodate bulk hospital dispensing and long-term care central pharmacy models.
Blister packs dominate installed base in regulated markets. Bottles are where expansion concentrates in cost-sensitive generic manufacturing corridors.
Material:
Cost tier stratification separates premium barrier films from commodity substrates in procurement decision frameworks.
- Plastic:PVC and PVDC coextrusions command volume leadership through thermoformability and moisture barrier tunability. India's CDSCO and BIS incremental standards redirect domestic procurement toward imported high-performance films for moisture-sensitive APIs.
- Aluminum:Cold-form foil and lidding materials capture disproportionate margins in specialty barrier applications requiring sub-0.1 g/m²/day water vapor transmission rates. Supply concentration in China and Russia exposes packagers to raw material allocation risks.
- Glass:Borosilicate and soda-lime containers retain niche positions for light-sensitive and chemically reactive formulations.
- Paper:Paperboard compliance packaging gains traction in Medicare Advantage adherence programs and European pharmacy chain polypharmacy management.
Plastic holds installed base dominance across volume applications. Aluminum is where margin expansion concentrates in high-barrier specialty segments.
End User:
Customer type determines regulatory scrutiny intensity and serialization infrastructure investment thresholds.
- Pharmaceuticals:Prescription oral solid dosages face the most stringent FDA Drug Supply Chain Security Act and EMA Falsified Medicines Directive compliance requirements. Aggregation-capable packaging lines and serialized 2D barcodes elevate capital equipment intensity for contract packagers serving this segment.
- Over-the-Counter:Self-medication products balance child-resistant closure mandates with retail shelf differentiation in competitive pharmacy environments.
- Nutraceuticals:Dietary supplement packaging operates under lighter regulatory frameworks with faster material substitution cycles.
- Veterinary:Animal health oral solids prioritize cost containment and flavor masking over human-pharmaceutical serialization standards.
Pharmaceuticals dominate compliance-driven equipment investment. Over-the-Counter is where volume expansion concentrates in retail channel consolidation.
Closure Type:
Application context and user population demographics drive closure selection across containment formats.
- Screw Caps:Threaded polypropylene closures provide resealability and torque consistency for multi-dose bottle regimens.
- Flip Tops:Hinged polyolefin designs enable single-hand dispensing for arthritis and geriatric patient populations.
- Snap Caps:Press-fit closures serve cost-optimized generic bottles where reseal frequency remains low.
- Shrink Bands:Heat-applied tamper-evident sleeves fulfill regulatory requirements for over-the-counter retail distribution.
Flip tops dominate adherence-focused chronic medication packaging. Screw caps are where generic volume production concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reshape procurement patterns as high-barrier film demand outpaces domestic supply in moisture-sensitive API corridors. India's CDSCO standards redirect procurement toward imported aluminum-polymer laminates. Brazil's ANVISA serialization deadlines compress supplier qualification timelines for contract manufacturers.
United States
FDA's Drug Supply Chain Security Act mandates serialized 2D barcodes and aggregation-capable packaging lines. North Carolina's Research Triangle hosts dense contract manufacturing clusters where 24-hour logistics reach major distribution hubs. Medicare Advantage plans drive paperboard compliance packaging for chronic medication adherence programs.
Germany
EMA's Falsified Medicines Directive enforcement accelerates capital deployment toward end-to-end traceability systems. Hospital central pharmacy models in Germany favor unit-dose blister packs over traditional bottle dispensing. The country's national pharmaceutical regulator maintains stringent qualification burdens for serialization-ready equipment.
India
BIS and CDSCO enforce incremental barrier standards for moisture-sensitive APIs, redirecting domestic procurement toward imported high-performance films. Maharashtra's oral solid dosage manufacturing corridor concentrates blister pack demand. Generic drug manufacturers expand procurement as track-and-trace mandates tighten traceability requirements.
Brazil
ANVISA serialization mandates compress supplier qualification timelines for high-volume generic manufacturers. São Paulo's pharmaceutical manufacturing cluster drives blister pack procurement concentration. The country's national pharmaceutical regulator aligns with FDA and EMA frameworks for cold chain verification standards.
China
Aluminum lidding foil production concentration exposes pharmaceutical packagers to raw material allocation risks and tariff volatility. The country's national pharmaceutical regulator enforces dual carbon goals that reshape acceptable packaging formats. Domestic film extrusion networks supply barrier materials across multiple continents.
Tablets and Capsules Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated film extruders with global aluminum-polymer laminate networks, paperboard-based compliance packaging specialists, and child-resistant closure system manufacturers. Competitive positioning depends on backward integration into high-barrier material production and geographic proximity to FDA-regulated contract manufacturing clusters. M&A activity targets serialization engineering capabilities, while capacity expansion concentrates in Maharashtra and North Carolina corridors.
Within the integrated packaging tier, Amcor exemplifies global film extrusion scale, WestRock occupies a position in North American paperboard compliance packaging, and Berry Global represents child-resistant closure specialization for over-the-counter applications. These three anchors demonstrate how supplier selection increasingly prioritizes serialization-ready infrastructure and 24-hour logistics reach to major pharmaceutical distribution hubs.
| Leading Market Players |
|---|
| Amcor |
| WestRock |
| Berry Global |
| Constantia Flexibles |
| Huhtamaki |
| Sonoco |
| Klöckner Pentaplast |
| Tekni-Plex |
| Bilcare |
| Others |
Value Network & Pricing Analysis
Aluminum foil supply concentration in China and Russia determines both three-tier pricing stratification across premium barrier, standard compliance, and economy generic tiers and the geographic shape of pharmaceutical packaging procurement networks. This raw material chokepoint compresses margins for packagers lacking backward integration into lidding foil production while elevating qualification premiums for FDA- and EMA-ready suppliers.
Pricing Analysis
Equipment-generation pricing gaps separate serialization-ready blister lines from legacy thermoforming systems and emerging NFC-integrated authentication platforms. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance, regulatory certification tier, and geographic delivery cost. Pricing pressure stems from PVC substitution mandates under EU Green Deal extended producer responsibility laws. Generic manufacturers in Brazil's São Paulo corridor exhibit highest price sensitivity; specialty pharmaceutical packagers in North Carolina demonstrate lowest sensitivity due to adherence-program contract premiums.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from aluminum-polymer laminate producers anchor working capital structures for mid-tier contract packagers. Raw material dependencies center on Chinese and Russian lidding foil, Indian and German high-barrier film extrusion, and North American paperboard substrates. Tariff exposure on Chinese aluminum inputs constitutes the dominant structural risk. Distribution runs through direct-to-pharmacy channels in consolidated European markets and wholesale intermediaries in fragmented Latin American corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Medicare Advantage plans and European pharmacy chains, consolidating procurement decisions for chronic medication adherence packaging and compressing supplier margins through multi-year contract aggregation.
For Market Incumbents: Pre-empt serialization engineering talent scarcity by acquiring automation-architecture specialists in the Research Triangle and Maharashtra corridors. Anchor barrier film production through captive supply of aluminum-polymer laminates to defend against Chinese foil allocation risks. Expand paperboard compliance packaging capacity to capture Medicare Advantage plan consolidation. For New Entrants and Emerging Players: Build out NFC-integrated authentication capabilities targeting biologic oral solids with cold chain verification requirements. Veterinary oral solids and nutraceutical sample distribution represent the most penetrable white-space segments. Pursue direct-to-pharmacy distribution partnerships in Germany and the Netherlands to bypass wholesale markups. For Investors and Strategic Acquirers: Contract packaging organizations with serialization-ready infrastructure and 24-hour logistics reach to FDA-regulated hubs represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance moats deepening across the analysis window. Monitor EMA Falsified Medicines Directive enforcement deadlines as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization-Ready Equipment Upgrade | FDA Drug Supply Chain Security Act mandates compress qualification timelines for contract manufacturers. |
| Backward Integration into Aluminum-Polymer Laminates | Captive supply of high-barrier films mitigates Chinese lidding foil tariff exposure. |
| NFC-Integrated Authentication Platform Launch | Near-field communication convergence with temperature-sensitive inks enables cold chain verification. |
| Direct-to-Pharmacy Distribution Expansion | Bypassing wholesale intermediaries captures margin pools in consolidated European pharmacy markets. |
| Sustainability Certification Program | EU Green Deal extended producer responsibility laws accelerate PVC-to-PVDC substitution cycles. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with packaging procurement managers, regulatory affairs leads at generic manufacturers, contract manufacturing executives, and pharmaceutical quality directors; and secondary validation through FDA Drug Supply Chain Security Act filings, EMA Falsified Medicines Directive implementation timelines, CDSCO barrier standard notifications, and customs trade data on aluminum-polymer laminate flows. Bottom-up and top-down triangulation cross-checked equipment installation rates against regional oral solid dosage production volumes.
Forecast inputs considered packaging type segmentation by blister pack, bottle, sachet, and pouch formats; material stratification across plastic, aluminum, glass, and paper substrates; end-user regulatory intensity tiers spanning pharmaceuticals, over-the-counter, nutraceuticals, and veterinary; and closure type adherence requirements. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window, incorporating serialization deadline acceleration curves and moisture-sensitive API formulation trends.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by aluminum foil producers or sudden tariff reconfigurations would shift outcomes. Macroeconomic volatility in emerging market currencies, regulatory deadline extensions, or breakthrough biodegradable barrier materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Injectable Drug Packaging Market