
 Middle East and Africa Plastic Caps and Closures Market | 2026-2036
Middle East and Africa Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plastic Caps and Closures Market Foresight
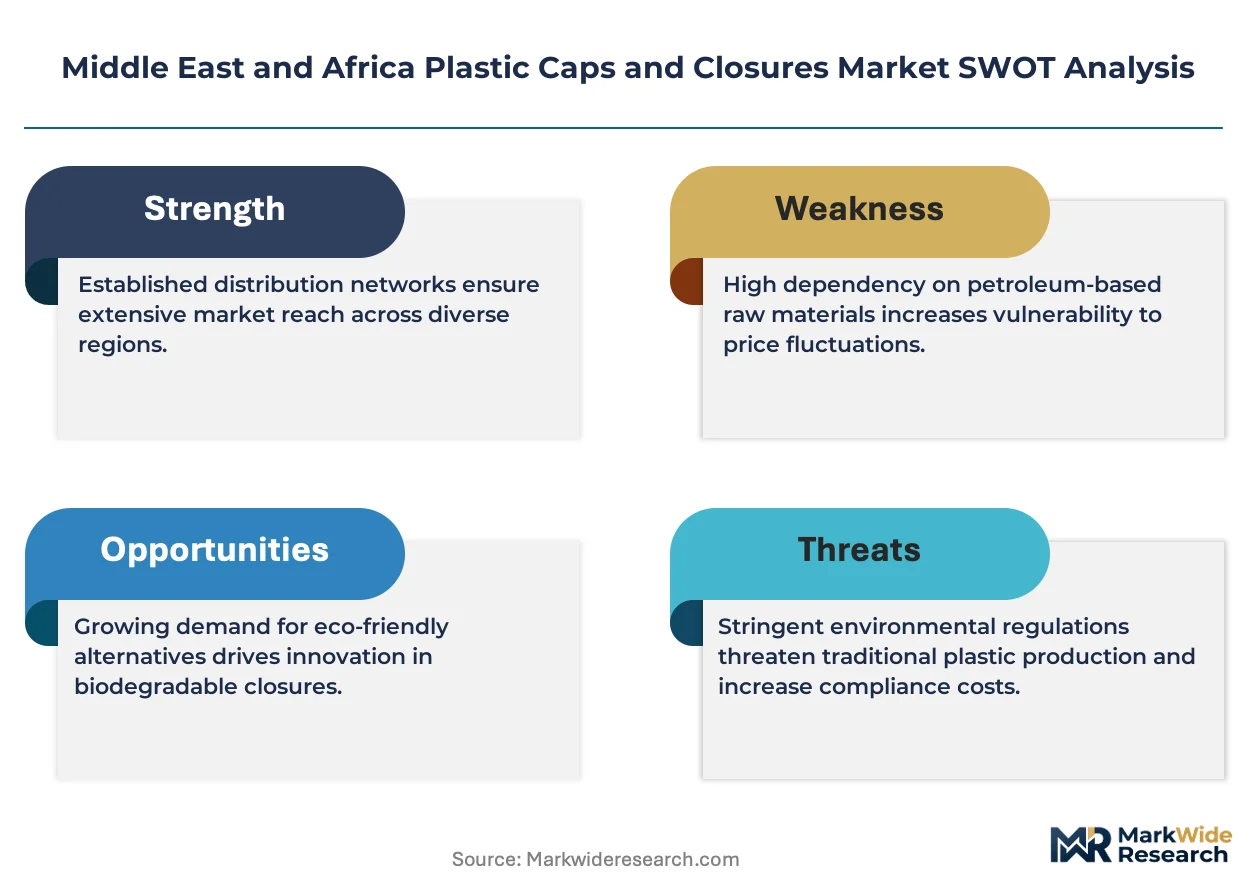
Capital-intensity divergence between integrated resin-to-closure producers and standalone converters is redrawing competitive boundaries across the Middle East and Africa. Berry Global leverages captive polyethylene supply chains to sustain margin resilience in Gulf markets. Zamil Plastic Industries anchors regional share through backward integration into polypropylene compounding in Saudi Arabia. ALPLA competes on high-speed continuous compression molding lines serving beverage bottlers from its UAE hub.
Plastic caps and closures are injection-molded or compression-molded threaded or snap-fit sealing devices, typically manufactured from polyethylene or polypropylene homopolymer with torque-release specifications between 10 and 25 inch-pounds, designed to preserve contents integrity across distribution temperature ranges from 4°C to 38°C. Screw caps occupy the dominant volume position due to universal compatibility with carbonated and still beverage bottles across African retail channels. Polypropylene leads material selection for hot-fill and retort applications in Gulf food processing, while tamper-evident designs command premium positioning in Saudi and Egyptian pharmaceutical packaging.
Saudi Food and Drug Authority pharmaceutical serialization rules and South African Bureau of Standards food-contact migration limits are tightening closure specification requirements across the region. The UAE's Emirates Authority for Standardization and Metrology now enforces Gulf Standard Organization testing protocols for child-resistant closures on household chemical containers. Stakeholders must monitor evolving extended producer responsibility frameworks in Egypt and Morocco that will reshape resin sourcing and post-consumer collection obligations.
Market Dynamics
Captive PET preform integration with in-house cap production is compressing supplier margins across Gulf beverage bottling, forcing standalone converters to defend position through specialty pharmaceutical and chemical closure portfolios.
Growth Catalysts
- Saudi SFDA serialization mandates:Pharmaceutical traceability requirements on closures are pulling tamper-evident and serialized designs into standard procurement specifications across Saudi Arabia's generics packaging sector.
- Hot-fill polypropylene adoption:Gulf food processors are specifying PP homopolymer closures for retort applications above 85°C, displacing polyethylene in sauce and ready-meal segments.
- Nigerian retail formalization:Beverage bottlers in Lagos and Kano are upgrading from loose caps to torque-specified screw closures as modern trade penetration deepens.
Market Restraints
- Propylene feedstock volatility:Gulf polypropylene prices track naphtha and propane differentials, exposing non-integrated converters to margin compression when olefin spreads widen.
- Resin supply concentration:SABIC and Borouge dominate regional polyethylene and polypropylene supply, creating single-source dependency for converters without backward integration into compounding.
- Migration testing bottlenecks:South African Bureau of Standards food-contact certification timelines stretch to 14-18 weeks, delaying new closure launches for regional beverage entrants.
Strategic Opportunities
- Morocco extended producer responsibility:Draft packaging waste regulations will mandate post-consumer collection systems, creating first-mover advantage for closures designed for mechanical recycling streams.
- Child-resistant closure standardization:Emirates Authority for Standardization and Metrology enforcement of GSO testing protocols opens premium positioning for certified suppliers in UAE household chemical packaging.
- Digital printing convergence:Laser marking combined with molded-in QR codes enables unit-level traceability without label adhesives, addressing pharmaceutical serialization at lower total applied cost.
Industry Challenges
- Continuous compression molding skill scarcity:High-speed line operation and preventive maintenance expertise concentrates with Algerian and Egyptian technicians, constraining expansion timelines for new entrants.
- Legacy injection tooling retrofit costs:Converters face capital decisions on whether to upgrade existing screw-cap molds for tamper-evident band integration or invest in greenfield compression capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plastic Caps and Closures Market |
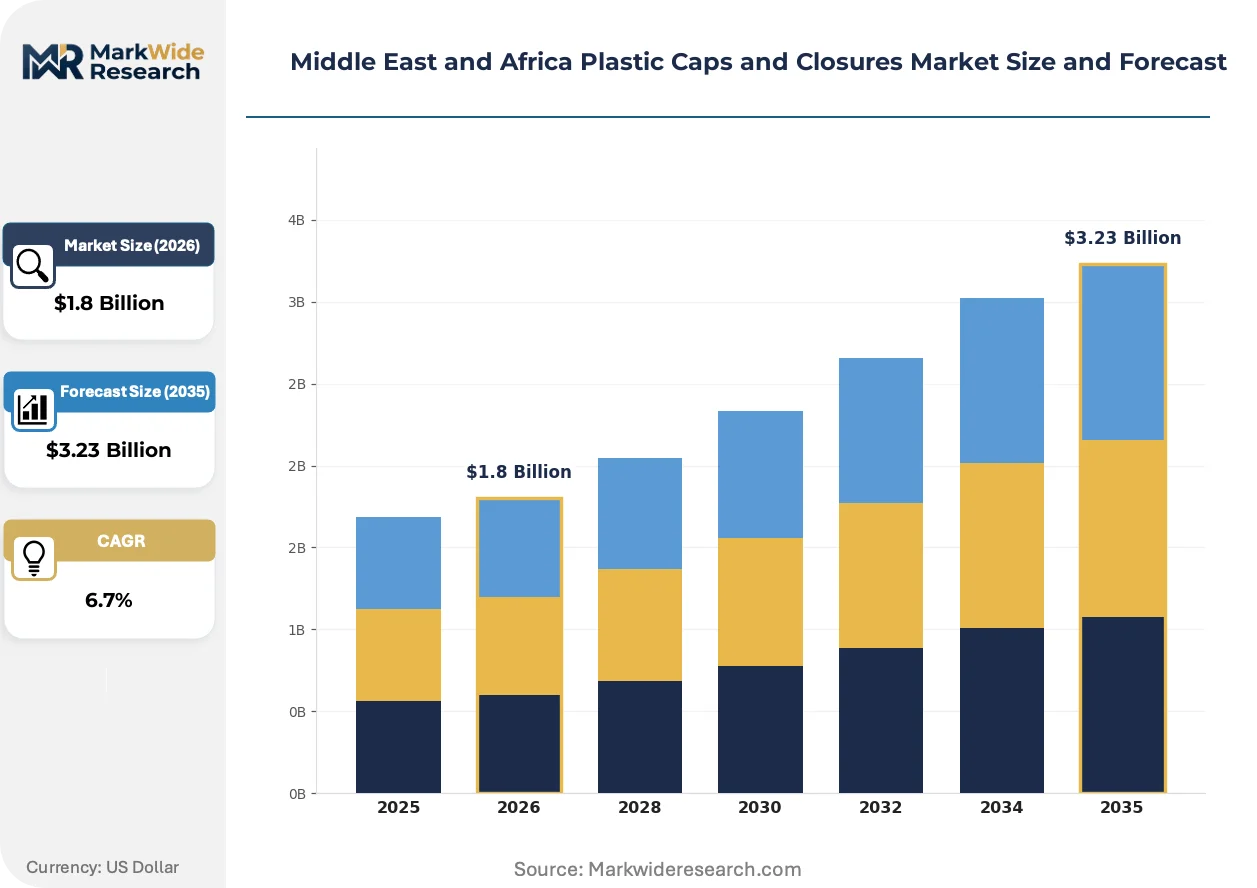
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Dispensing Caps, Sports Caps Material: Polyethylene, Polypropylene, PVC, PET End Use: Food & Beverage, Pharmaceuticals, Cosmetics, Household Design Type: Standard, Child-Resistant, Tamper-Evident, Custom |
| Companies Covered | Bericap, Closure Systems International, Berry Global, Portola Packaging, ALPLA, AptarGroup, Silgan Holdings, Zamil Plastic Industries, Crown Holdings, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plastic Caps and Closures Market Shifts & Advancements
Compression molding technology is displacing legacy injection processes for high-volume beverage closures, while regulatory serialization requirements and sustainability mandates are rewriting material and design specifications across the region.
Continuous compression molding is bifurcating the high-volume beverage segment from specialty pharmaceutical applications. Berry Global and ALPLA have installed twin-screw compression lines at Gulf hubs capable of 72,000 caps per hour per cavity. The technology is bifurcating cost structures: integrated resin producers capture margin through captive supply chains while standalone converters retreat into smaller-lot tamper-evident and child-resistant segments where tooling complexity defends pricing.
Saudi Food and Drug Authority pharmaceutical serialization rules now mandate unique identifiers on individual closure units, not just secondary packaging. This regulatory shift forces converters to integrate laser marking or molded data matrix features into production workflows. Egyptian pharmaceutical exporters face parallel compliance pressure as they supply Saudi-distributed generics, compressing time-to-market for non-compliant suppliers.
Beverage bottlers in Nigeria and South Africa are consolidating supplier relationships from fragmented regional converter networks toward direct partnerships with Gulf-based integrated producers. This procurement concentration eliminates distributor markups but demands logistics coordination across Red Sea and Mediterranean shipping lanes. The shift is most visible in Lagos and Johannesburg, where Coca-Cola and Pepsi bottlers have reduced active closure suppliers from twelve to four over the past three years.
Middle East and Africa Plastic Caps and Closures Market Segmentation
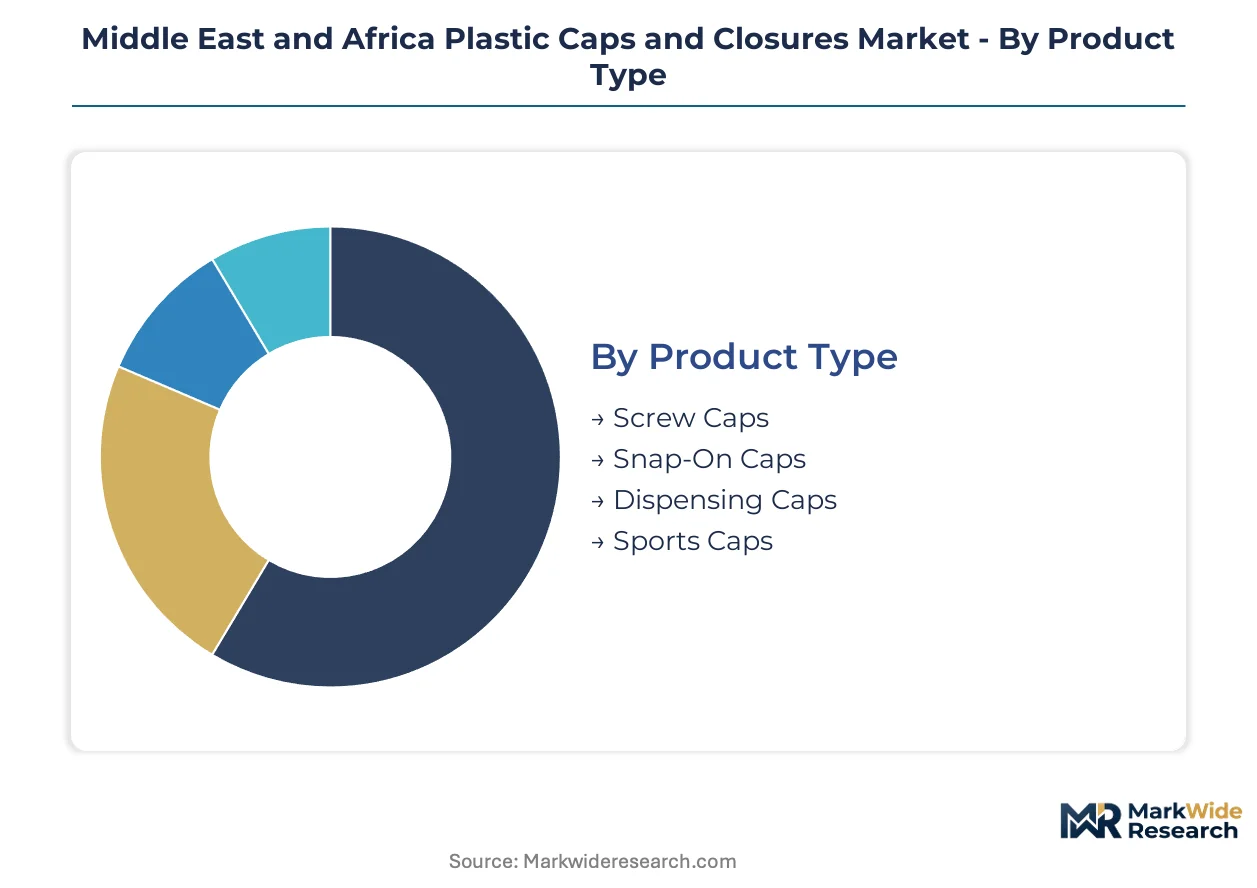
Segmentation in the Middle East and Africa plastic caps and closures market reveals how regulatory divergence and material substitution pressures fragment procurement patterns across beverage, pharmaceutical, and chemical end uses.
Product Type:
Substitution pressure from aluminum and bio-based alternatives concentrates on commodity closure formats, while functional designs with integrated dispensing or tamper-evident features defend polymer positioning.
- Screw Caps:Threaded polyethylene or polypropylene closures with torque-release specifications between 10 and 25 inch-pounds dominate carbonated and still beverage applications across Nigerian and South African retail channels. Demand concentrates with Coca-Cola and Pepsi bottlers in Lagos and Johannesburg as modern trade penetration deepens and loose-cap informal supply chains contract.
- Snap-On Caps:Compression-fit designs manufactured from high-density polyethylene provide cost-efficient sealing for non-carbonated water and dairy containers. Egyptian and Moroccan food processors specify these for UHT milk distribution where resealability requirements are secondary to production speed.
- Dispensing Caps:Integrated valve or flip-top mechanisms serve sauce, condiment, and personal care applications in Gulf food processing and UAE cosmetics manufacturing.
- Sports Caps:Push-pull and twist-lock designs with flow-control features target functional beverage segments in South African fitness and outdoor retail channels.
Screw caps anchor the volume base while dispensing caps gain share at the steepest rate as Gulf food processors automate sauce and condiment packaging lines.
Material:
Cost tier differentiation separates integrated resin producers from converters dependent on spot market procurement, with feedstock volatility reshaping margin structures across polyethylene and polypropylene grades.
- Polyethylene:Low-density and linear-low-density grades dominate cold-fill beverage and dairy applications across African retail channels. Nigerian bottlers specify LDPE screw caps for water and carbonated soft drinks where flexibility and impact resistance outweigh temperature performance.
- Polypropylene:Homopolymer and random copolymer grades withstand hot-fill and retort temperatures above 85°C, displacing polyethylene in Gulf sauce, ready-meal, and pharmaceutical packaging. Saudi Food and Drug Authority serialization mandates accelerate PP adoption for tamper-evident pharmaceutical closures where dimensional stability under thermal stress is critical.
- PVC:Rigid formulations persist in limited chemical and industrial applications despite regulatory pressure from Gulf Standard Organization migration limits.
- PET:Crystallized polyethylene terephthalate closures serve specialty pharmaceutical and high-clarity cosmetic segments where chemical resistance and transparency requirements converge.
Polyethylene retains the largest installed base while polypropylene climbs the fastest as hot-fill processing expands across Saudi and UAE food manufacturing.
End Use:
Application-specific compliance burdens fragment supplier capabilities, with pharmaceutical serialization and food-contact certification creating divergent qualification pathways.
- Food & Beverage:Carbonated soft drinks, bottled water, and dairy applications consume the majority of regional closure volume. South African Bureau of Standards migration testing requirements and extended producer responsibility frameworks in Egypt and Morocco reshape material selection and post-consumer collection design priorities.
- Pharmaceuticals:Tamper-evident and child-resistant closures for generic drug packaging face Saudi SFDA serialization mandates requiring unique identifiers on individual closure units. Egyptian exporters supplying Saudi-distributed generics must parallel-comply, compressing time-to-market for non-certified converters.
- Cosmetics:Premium dispensing and airless pump closures serve UAE and Saudi personal care manufacturing where aesthetic differentiation commands pricing power.
- Household:Chemical-resistant screw and snap-on designs for detergents and cleaning products fall under Emirates Authority for Standardization and Metrology enforcement of Gulf Standard Organization child-resistant testing protocols.
Food and beverage anchors procurement volume while pharmaceuticals expands most quickly on regulatory compliance pull-through.
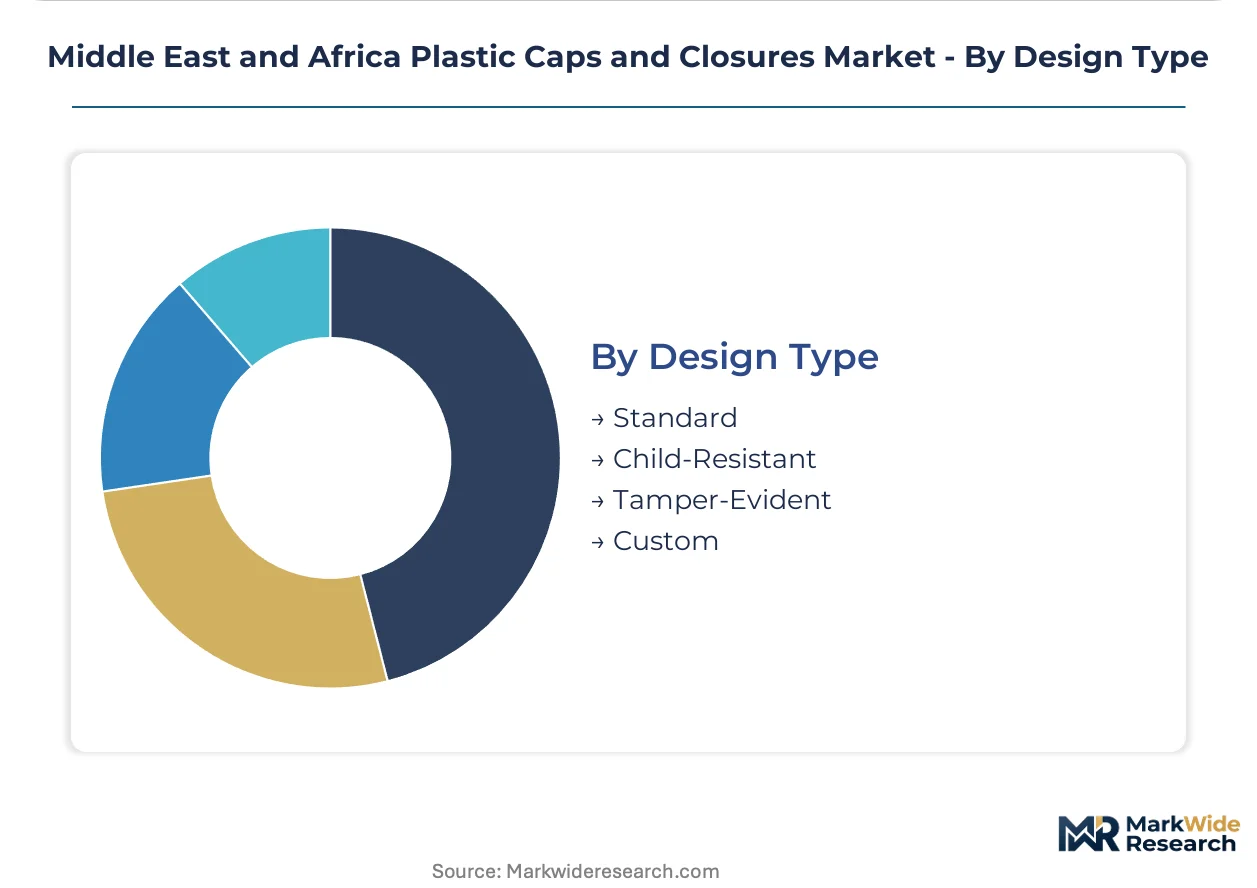
Design Type:
Customer type stratification separates commodity standard designs from certified specialty formats where regulatory compliance creates defendable margin tiers.
- Standard:Basic threaded or snap-fit configurations without additional safety features serve cost-sensitive beverage and food segments across African informal retail channels.
- Child-Resistant:Push-and-turn or squeeze-and-turn mechanisms certified to GSO testing protocols command premium positioning in UAE household chemical packaging and Saudi pharmaceutical applications where Emirates Authority for Standardization and Metrology enforcement is tightening.
- Tamper-Evident:Breakaway bands, shrink sleeves, or molded fracture points provide visible evidence of opening, now mandatory for Saudi pharmaceutical distribution and expanding into Egyptian and South African food safety protocols.
- Custom:Branded colors, embossed logos, and proprietary thread profiles serve Coca-Cola, Pepsi, and regional beverage bottlers consolidating supplier relationships toward direct Gulf-based partnerships.
Standard designs retain the highest unit volume while tamper-evident formats capture the steepest expansion trajectory on pharmaceutical and food safety mandate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Saudi and UAE integrated producers while Nigerian and South African converters absorb feedstock volatility. Gulf resin-to-closure producers command margin premiums through captive polyethylene and polypropylene supply chains. African standalone converters face compressed margins when olefin spreads widen.
Saudi Arabia
Pharmaceutical serialization mandates from the Saudi Food and Drug Authority pull tamper-evident closures into standard procurement specifications. The Eastern Province hosts SABIC's petrochemical complexes feeding backward-integrated converters. Riyadh-based generics packagers now require unit-level traceability features on every closure.
United Arab Emirates
Emirates Authority for Standardization and Metrology enforcement of Gulf Standard Organization child-resistant protocols opens premium positioning for certified suppliers. Dubai and Sharjah beverage bottlers consolidate supplier relationships toward direct Gulf partnerships. ALPLA's UAE hub serves high-volume carbonated soft drink producers with continuous compression molding capacity.
South Africa
Bureau of Standards food-contact migration testing timelines stretch to 14-18 weeks, delaying new closure launches for regional beverage entrants. Johannesburg bottlers upgrade from loose caps to torque-specified screw closures as modern trade penetration deepens. Cape Town pharmaceutical exporters face parallel compliance pressure supplying Saudi-distributed generics.
Nigeria
Lagos and Kano beverage bottlers expand procurement of tamper-evident closures as food safety protocols tighten. Retail formalization drives specification upgrades from informal loose-cap supply chains toward torque-standardized designs. Nigerian distributors reduce active closure suppliers from fragmented networks toward direct Gulf-based partnerships.
Egypt
Draft extended producer responsibility frameworks will reshape resin sourcing and post-consumer collection obligations for closure producers. Cairo-based pharmaceutical exporters must parallel-comply with Saudi SFDA serialization rules, compressing time-to-market for non-certified converters. Alexandria food processors specify snap-on polyethylene caps for UHT milk distribution.
Middle East and Africa Plastic Caps and Closures Market Competitive Landscape
Concentration sits with integrated resin-to-closure producers who capture margin through captive supply chains while standalone converters retreat into specialty segments. Berry Global and Zamil Plastic Industries anchor regional share through backward integration into polypropylene compounding. Three archetypes define competitive positioning: Gulf-based integrated producers with captive resin supply, European multinationals with compression molding technology, and regional standalone converters defending specialty pharmaceutical niches. Dominant competitive moves include capacity expansion in continuous compression molding and strategic partnerships between beverage bottlers and integrated suppliers.
Among European multinationals, Bericap and ALPLA represent the technology-led archetype with high-speed continuous compression molding capabilities. Berry Global exemplifies the integrated producer model through captive polyethylene supply chains sustaining margin resilience. Zamil Plastic Industries anchors the regional specialist tier through in-house polypropylene compounding in Saudi Arabia. Closure Systems International and AptarGroup occupy positions within the premium pharmaceutical and dispensing closure segments where tooling complexity defends pricing power.
| Leading Market Players |
|---|
| Bericap |
| Closure Systems International |
| Berry Global |
| Portola Packaging |
| ALPLA |
| AptarGroup |
| Silgan Holdings |
| Zamil Plastic Industries |
| Crown Holdings |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-week certification timelines at the South African Bureau of Standards concentrate pricing power with Gulf-based integrated producers who bypass third-party resin procurement. This lead-time differential shapes a bifurcated cost structure where Saudi and UAE captives command premium positioning while African standalone converters absorb feedstock volatility.
Pricing Analysis
The customization-premium spread between serialized pharmaceutical closures and commodity beverage screw caps spans three distinct certification tiers. Pricing stratifies across premium, standard, and economy tiers based on SFDA serialization compliance and Gulf Standard Organization child-resistant certification. Cost compression in the standard beverage segment is intensifying because Nigerian bottlers consolidate supplier relationships toward direct Gulf partnerships. Small-lot pharmaceutical converters exhibit the lowest price sensitivity due to regulatory switching costs, while informal African retail channels drive aggressive economy-tier negotiation.
Supply Chain Analysis
Strait of Hormuz transit underwrites resin-to-closure logistics for Saudi, UAE, and Kuwaiti production hubs feeding African markets. Geographic supply concentration centers on Saudi Arabia, the UAE, and Egypt, with polypropylene and polyethylene feedstock drawing from SABIC and Borouge complexes. Single-source vulnerability concentrates in Gulf resin supply, exposing non-integrated converters to margin compression when olefin spreads widen. Distribution runs through Red Sea and Mediterranean shipping lanes to Lagos, Johannesburg, and Alexandria port clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. SFDA serialization mandates and GSO testing protocols create certification switching costs that protect qualified suppliers from price-based displacement.
For Market Incumbents: Consolidate Gulf-based compression molding capacity to capture Nigerian and South African beverage procurement concentration. Deepen backward integration into polypropylene compounding to defend margin resilience against propylene feedstock volatility. Prioritize laser marking and molded data matrix investments to maintain pharmaceutical serialization compliance as Egyptian exporters face parallel certification pressure.
For New Entrants and Emerging Players: Technical service gaps in continuous compression molding preventive maintenance present white-space entry points. Target Moroccan extended producer responsibility preparation as packaging waste regulations mandate post-consumer collection system design. Pursue certified child-resistant closure production for UAE household chemical packaging where Emirates Authority for Standardization and Metrology enforcement tightens.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complay play because pharmaceutical serialization and food-contact certification create enduring qualification barriers. Acquisition targets should display in-house compounding capability or established SFDA/GSO certification pathways. Monitor Egyptian extended producer responsibility finalization as an inflection signal for mechanical recycling-ready closure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Compression Molding Capacity Expansion | ALPLA and Berry Global installations at Gulf hubs capture Nigerian bottler procurement consolidation. |
| Backward Integration into Polypropylene Compounding | Zamil Plastic Industries anchors Saudi market share through captive resin supply chains. |
| Laser Marking and Data Matrix Integration | SFDA pharmaceutical serialization mandates pull unit-level traceability into standard production workflows. |
| Child-Resistant Certification Investment | GSO testing protocol compliance opens premium positioning in UAE household chemical packaging. |
| Mechanical Recycling Stream Design | Morocco draft EPR frameworks create first-mover advantage for post-consumer collection-ready closures. |
Research Methodology
Initial hypotheses were tested against primary input from beverage procurement managers, pharmaceutical packaging engineers, resin supply planners, and regulatory compliance officers, and refined through secondary validation. Primary fieldwork drew from customs and trade flow databases, SABIC and Borouge technical specifications, SFDA regulatory filings, and Gulf Standard Organization testing protocols. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation.
Variance decomposition across product type, material grade, end-use application, and design certification tier shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation across the projection horizon. Forecast inputs incorporated hot-fill polypropylene substitution trajectories, pharmaceutical serialization compliance timelines, and extended producer responsibility implementation schedules.
Forecasts assume regulatory continuity in Saudi SFDA pharmaceutical rules, UAE Emirates Authority for Standardization and Metrology enforcement, and South African Bureau of Standards migration testing regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Egyptian EPR finalization and Moroccan packaging waste regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Disc Top Caps Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Twist Caps Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Mexico Plastic Caps and Closures Market