
 North America Pharmaceutical Plastic Bottles Market | 2026-2036
North America Pharmaceutical Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Plastic Bottles Market Insights
Asset-light leasing models for blow-molding equipment is narrowing the capital barrier for mid-tier contract manufacturers seeking FDA-compliant capacity. Silgan Holdings Inc leverages its captive resin sourcing and in-house mold fabrication to sustain cost advantages across high-volume oral solid lines. AptarGroup Inc differentiates through integrated dispensing closure systems that combine bottle and child-resistant cap in single-source supply. COMAR LLC anchors its position in specialty pharmaceutical packaging with dedicated cleanroom blow-molding for oncology and biologic applications.
North America pharmaceutical plastic bottles are blow-molded or injection-stretch-blown containers, typically manufactured from HDPE, PET, or multilayer coextrusions, designed to meet USP <671> standards for light transmission, moisture vapor transmission, and child-resistant closure compatibility. These containers protect drug stability from manufacturing through patient dispensing while enabling automated filling at pharmaceutical packaging lines. HDPE dominates oral solid dosage volumes due to its chemical inertness and cost position, though PET is gaining share in liquid formulations where clarity and oxygen barrier properties command premium positioning. Child-resistant closure types represent the fastest-growing closure segment, driven by Poison Prevention Packaging Act compliance mandates and generic drug label expansion.
FDA's Current Good Manufacturing Practice regulations and USP packaging standards govern material biocompatibility, extractables testing, and lot traceability across all pharmaceutical plastic bottle production for US distribution. Health Canada's PMRA and US state-level pharmacy boards enforce complementary labeling and dispensing requirements that shape regional bottle specification divergence. The Drug Supply Chain Security Act serialization timeline continues to push pharmaceutical companies toward packaging partners with integrated track-and-trace capabilities. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York, as these frameworks threaten to impose post-consumer recycling cost structures not yet reflected in current contract pricing models.
Market Dynamics
FDA's Drug Supply Chain Security Act serialization mandates are compressing supplier qualification timelines, forcing pharmaceutical manufacturers to consolidate packaging partnerships around blow-molding operations with integrated track-and-trace infrastructure. This regulatory pressure is reshaping procurement patterns across oral solid dosage lines.
Growth Catalysts
- Chronic Disease Prevalence:Rising diabetes and cardiovascular medication volumes in the US Northeast corridor are expanding demand for HDPE bottles with moisture-barrier properties.
- Poison Prevention Packaging Act:Child-resistant closure mandates are accelerating specification upgrades across generic drug portfolios, driving replacement cycles for non-compliant legacy inventory.
- Multilayer Coextrusion Technology:Barrier PET adoption for liquid formulations is penetrating oncology and biologic segments previously served by glass.
Market Restraints
- Resin Price Volatility:HDPE and PET feedstock costs tied to natural gas and crude oil benchmarks create margin compression for contract manufacturers without captive resin sourcing.
- Cleanroom Capacity Concentration:FDA-compliant blow-molding for sterile applications clusters in New Jersey and Massachusetts, creating geographic supply risk for West Coast pharmaceutical operations.
- Extractables Testing Burden:USP <661.1> and <1661> analytical requirements extend qualification timelines for new material formulations beyond 18 months.
Strategic Opportunities
- Extended Producer Responsibility:California and New York state-level recycling frameworks will create first-mover advantage for packaging suppliers with post-consumer content verification systems.
- Integrated Dispensing Systems:Convergence of bottle-body blow-molding with precision closure molding enables single-source supply contracts for specialty pharmaceutical launches.
- Biologic Packaging Migration:Oncology and cell therapy applications in Massachusetts R&D corridors represent underpenetrated demand for barrier-grade multilayer containers.
Industry Challenges
- Blow-Molding Technician Scarcity:FDA cGMP-qualified process engineers are concentrated among incumbent suppliers, constraining capacity expansion for mid-tier contract manufacturers.
- Serialization Integration:DSCSA-compliant track-and-trace hardware requires capital deployment that exceeds the asset-light leasing thresholds favored by emerging packaging operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Plastic Bottles Market |
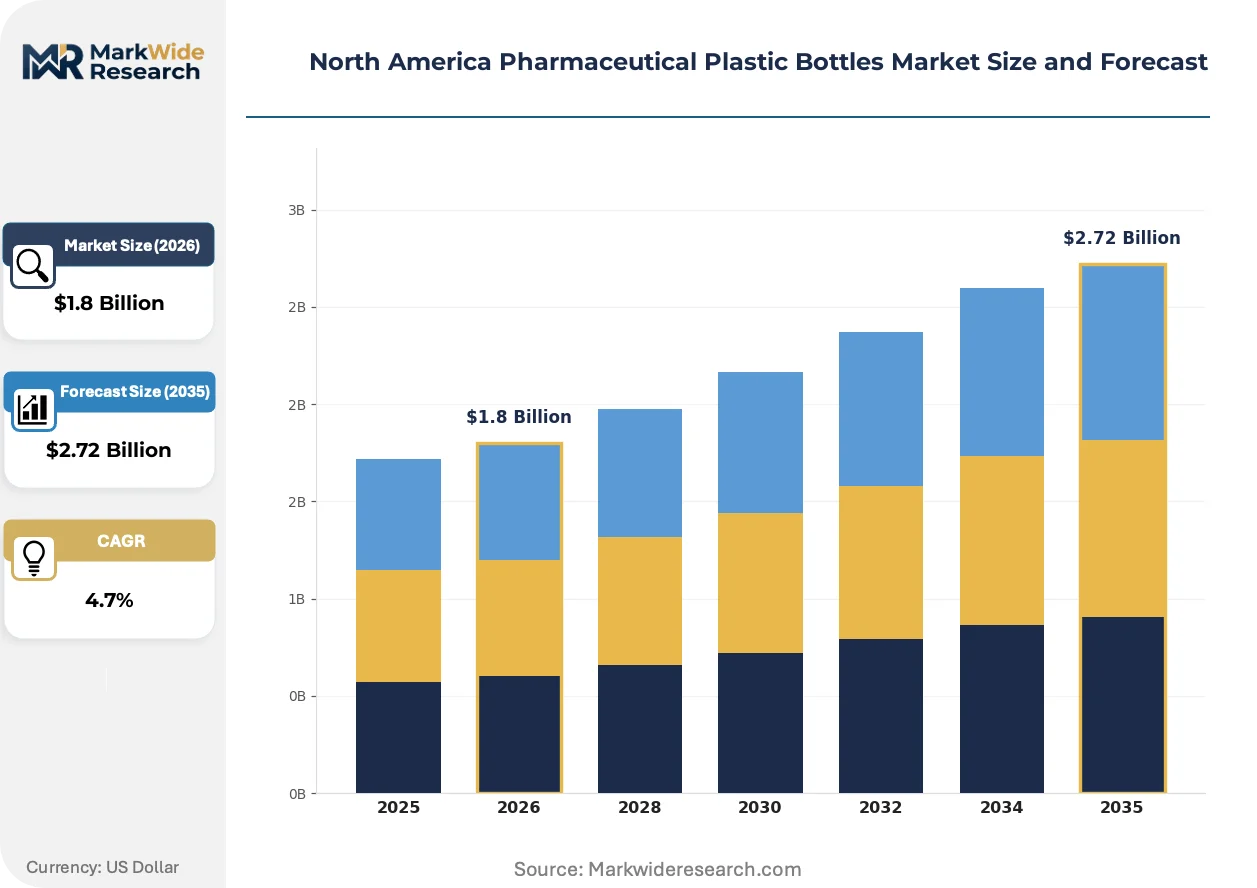
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, PET, PVC, LDPE Closure Type: Screw Caps, Child-Resistant Caps, Dropper Caps, Snap Caps End User: Pharmacies, Hospitals, Clinics, Pharmaceutical Companies Capacity: 30ml, 60ml, 100ml, 500ml |
| Companies Covered | AptarGroup Inc, COMAR LLC, Amcor Group GmbH, Silgan Holdings Inc, Drug Plastics Group, Gerresheimer AG, ALPLA Werke Alwin Lehner GmbH & Co KG, Altium Packaging, Berry Global Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Plastic Bottles Market Trends and Innovations
Material science advances and regulatory compliance automation are converging to redefine competitive positioning in pharmaceutical primary packaging. Suppliers are racing to integrate barrier performance with digital traceability.
Multilayer coextrusion technology is hybridizing HDPE structural layers with EVOH oxygen barriers and tie-layer adhesives to create containers meeting USP <671> Category I light and moisture standards. Oncology drug manufacturers in New Jersey are specifying these constructions for oral solid dosages with 24-month stability requirements. The technology is hybridizing what were previously separate glass and plastic supply chains into unified polymer-based sourcing strategies.
Health Canada's PMRA has aligned its pharmaceutical packaging guidance with FDA serialization timelines, creating synchronized compliance deadlines across the US-Canada trade corridor. Dual-jurisdiction manufacturers must now validate packaging lines against both FDA cGMP and Health Canada ICH Q7 standards simultaneously. Biologic and biosimilar producers are responding by pre-qualifying packaging suppliers with established cross-border regulatory dossiers.
Contract packaging organizations are consolidating procurement around full-service blow-molding partners who assume extractables testing and regulatory filing responsibilities. This vendor consolidation displaces the traditional model where pharmaceutical companies managed material qualification in-house. The shift is most visible in Massachusetts, where biotech startups lack internal packaging expertise and depend entirely on outsourced regulatory support.
North America Pharmaceutical Plastic Bottles Market Segmentation
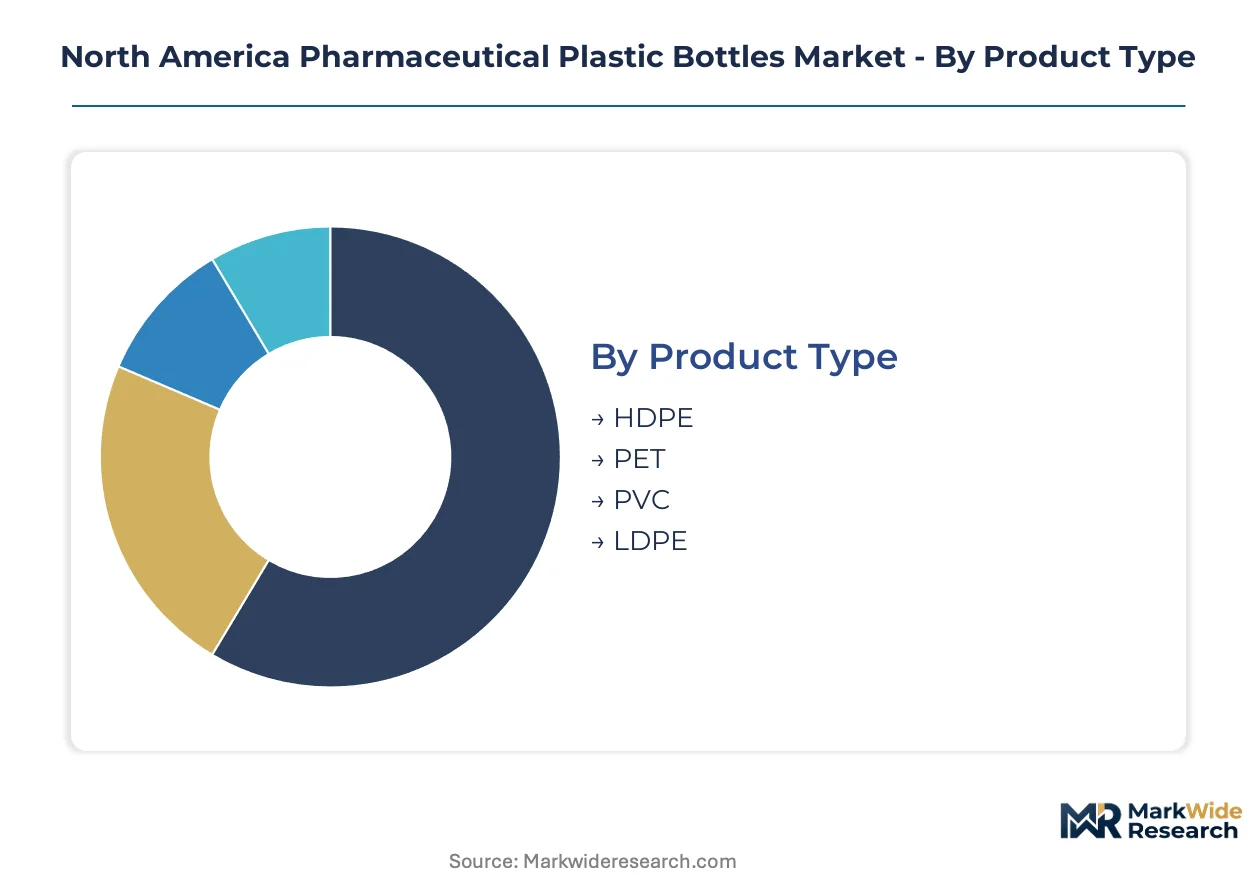
Segmentation in North American pharmaceutical plastic bottles reveals how material chemistry, closure mechanics, and end-use workflow requirements create distinct procurement clusters. Each dimension shapes FDA compliance pathways and resin qualification timelines differently.
Product Type:
Cost tier stratification separates commodity resins from barrier-grade formulations with multilayer coextrusion premiums.
- HDPE:High-density polyethylene dominates oral solid dosage volumes through chemical inertness and moisture barrier performance. Demand concentrates in New Jersey contract packaging corridors serving generic manufacturers with high-throughput lines. FDA USP <671> compliance is routine for HDPE, compressing supplier qualification cycles versus specialty alternatives.
- PET:Polyethylene terephthalate delivers clarity and oxygen barrier properties for liquid formulations. Massachusetts oncology R&D clusters are specifying barrier PET for biologic stability requirements previously met by glass. The material commands resin premiums but enables automated visual inspection systems.
- PVC:Polyvinyl chloride retains niche positioning for specific extractables profiles in legacy parenteral applications.
- LDPE:Low-density polyethylene serves squeeze-dropper formats where flexibility and dosing precision outweigh structural rigidity requirements.
HDPE holds installed capacity. PET is rotating up the share rankings.
Closure Type:
Application-driven mechanical requirements create four distinct specification tiers with divergent tooling investments.
- Screw Caps:Standard threaded closures serve non-restricted medications with straightforward torque specifications. US Northeast pharmaceutical distribution centers specify screw caps for institutional dispensing where child access is controlled through workflow rather than packaging.
- Child-Resistant Caps:Push-and-turn mechanisms complying with Poison Prevention Packaging Act mandates are expanding fastest across retail pharmacy channels. California and New York state pharmacy boards enforce rigorous testing protocols that favor suppliers with in-house mold fabrication and automated torque validation.
- Dropper Caps:Integrated bulb-and-tip assemblies serve ophthalmic and pediatric liquid formulations requiring precise volumetric dosing.
- Snap Caps:Hinged flip-top designs enable single-hand dispensing for arthritis and mobility-impaired patient populations.
Child-resistant caps are climbing the fastest as Poison Prevention Packaging Act compliance deadlines tighten.
End User:
Customer type determines order scale, specification complexity, and regulatory documentation burden.
- Pharmaceutical Companies:Brand and generic drug manufacturers drive primary packaging specifications through FDA NDA and ANDA filings. Massachusetts biotech startups and established New Jersey generics operations represent contrasting demand profiles—early-stage companies require outsourced regulatory support while high-volume manufacturers prioritize line speed and lot traceability integration.
- Pharmacies:Retail and institutional pharmacy chains influence secondary packaging and repackaging demand for unit-dose compliance. US hospital systems are consolidating procurement around DSCSA-compliant suppliers with integrated serialization capabilities.
- Hospitals:Inpatient dispensing workflows favor unit-of-use formats with barcode medication administration compatibility.
- Clinics:Ambulatory care settings generate demand for smaller lot sizes and rapid specification turnaround.
Pharmaceutical companies hold installed capacity. Pharmacies are rotating up the share rankings.
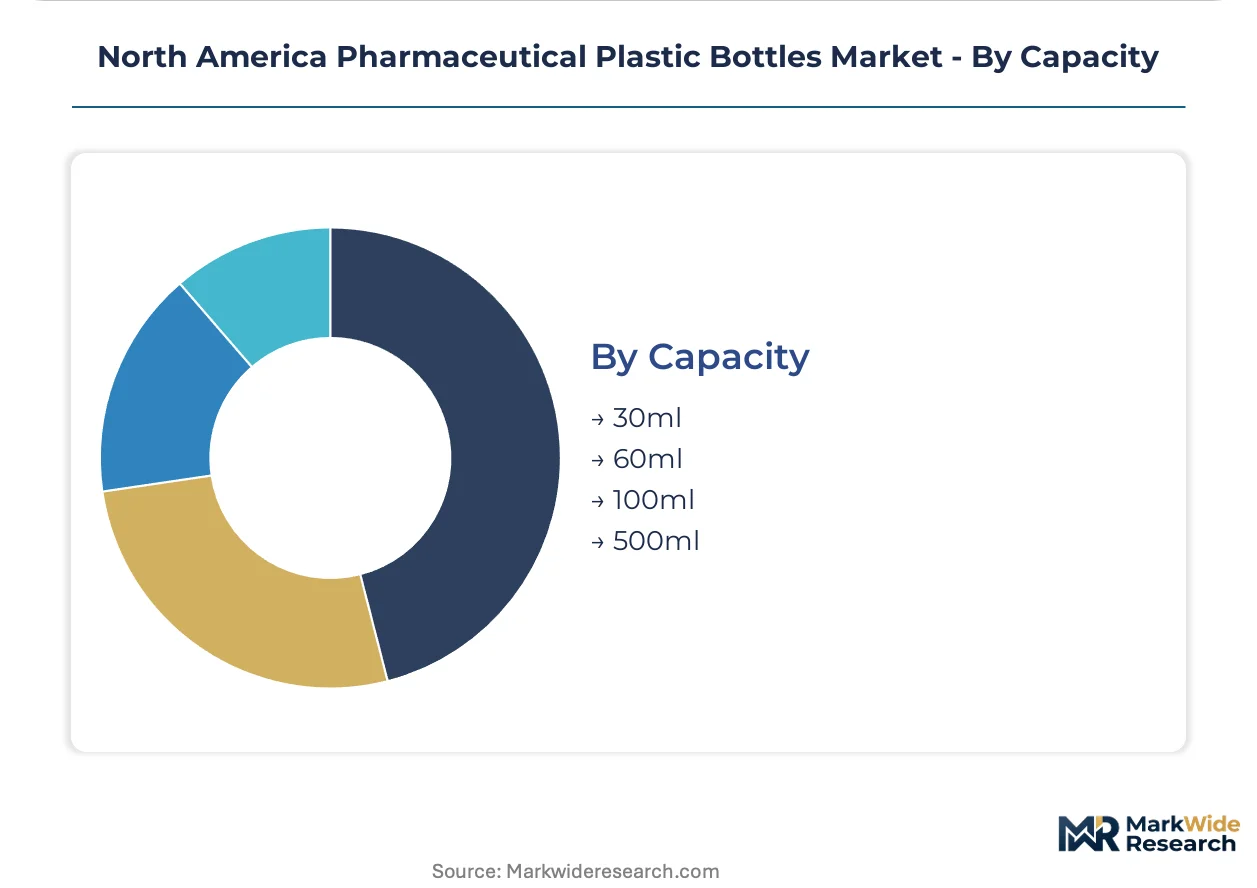
Capacity:
Volume segmentation aligns with dosing regimen duration and patient population scale across therapeutic categories.
- 100ml:Mid-range volumes serve standard 30-day oral solid regimens for chronic disease maintenance. US Northeast generic manufacturers specify 100ml HDPE bottles as the workhorse format for cardiovascular and diabetes medication portfolios, balancing shipping efficiency with patient handling ergonomics.
- 500ml:Large-format containers support institutional dispensing and high-volume liquid formulations. Hospital systems in Massachusetts and New Jersey are specifying 500ml barrier PET for oncology compounding pharmacies with centralized preparation workflows.
- 30ml:Compact volumes serve short-course antibiotics and travel-size compliance packaging.
- 60ml:Intermediate sizing targets pediatric formulations and tapering-dose regimens.
100ml holds installed capacity. 500ml is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Drug Supply Chain Security Act serialization mandates and Health Canada's aligned PMRA guidance are synchronizing compliance requirements across the US-Canada pharmaceutical trade corridor. This regulatory convergence is reshaping packaging supplier qualification patterns and consolidating procurement decisions around track-and-trace capable operations.
United States
Chronic disease medication volumes and generic drug label expansion are driving HDPE bottle demand across the Northeast pharmaceutical corridor. FDA cGMP regulations and USP <671> standards govern material biocompatibility and extractables testing for all domestic distribution. New Jersey and Massachusetts host concentrated contract packaging operations serving biotech startups and established generic manufacturers with integrated serialization infrastructure.
Canada
Biologic and biosimilar production for North American export markets is expanding barrier-grade PET specification requirements. Health Canada's PMRA has synchronized pharmaceutical packaging guidance with FDA serialization timelines, creating dual-jurisdiction compliance obligations. Ontario and Quebec pharmaceutical manufacturing clusters are pre-qualifying suppliers with established cross-border regulatory dossiers and cleanroom blow-molding capabilities.
Mexico
Nearshoring of pharmaceutical packaging operations for US market access is accelerating FDA-compliant capacity investments. COFEPRIS regulatory alignment with international standards supports contract manufacturing growth for export-oriented production. Baja California and Mexico City metro areas are developing blow-molding operations targeting US generic drug manufacturers seeking geographic supply diversification.
North America Pharmaceutical Plastic Bottles Market Competitive Landscape
On the supply side, the industry is consolidating around blow-molding operations with integrated track-and-trace infrastructure and captive resin sourcing capabilities. Mid-tier contract manufacturers face narrowing participation windows as FDA DSCSA deadlines compress supplier qualification timelines. The competitive landscape segments into three strategic archetypes: integrated dispensing system specialists, high-volume commodity resin producers, and cleanroom-certified specialty packaging operators. Dominant competitive moves include backward integration into resin supply chains and strategic partnerships with pharmaceutical companies for co-developed packaging specifications.
Among North American packaging specialists, AptarGroup Inc, Silgan Holdings Inc, and COMAR LLC exemplify distinct competitive positioning archetypes. AptarGroup represents the integrated dispensing system tier, combining bottle-body production with precision closure engineering. Silgan Holdings occupies the scale-driven commodity resin segment, leveraging high-throughput oral solid dosage lines. COMAR anchors the specialty pharmaceutical tier, targeting oncology and biologic applications with dedicated cleanroom manufacturing protocols.
| Leading Market Players |
|---|
| AptarGroup Inc |
| COMAR LLC |
| Amcor Group GmbH |
| Silgan Holdings Inc |
| Drug Plastics Group |
| Gerresheimer AG |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Altium Packaging |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
New Jersey's contract packaging corridor concentrates FDA-compliant blow-molding capacity for oral solid dosage lines, compressing margin negotiation leverage for generic drug manufacturers sourcing HDPE bottles. This geographic clustering of cGMP-certified operations creates asymmetric pricing power that favors incumbent suppliers with integrated track-and-trace infrastructure.
Pricing Analysis
Certification level creates the primary spread between DSCSA-compliant suppliers and standard-grade converters. Three-tier pricing structure across DSCSA-integrated, USP <671>-certified, and commodity HDPE tiers reflects qualification timeline differentials. Cost compression in the commodity tier is intensifying because mid-tier contract manufacturers lack captive resin sourcing. Generic drug manufacturers with high-volume oral solid portfolios exhibit highest price sensitivity, while Massachusetts biotech startups prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Silgan Holdings and AptarGroup anchor North American pharmaceutical packaging capacity, with secondary concentration among Ontario and Quebec contract manufacturers serving cross-border biologic production. HDPE and PET resin supply draws from Gulf Coast petrochemical complexes and Canadian natural gas feedstock. Single-source vulnerability concentrates in EVOH barrier film supply for multilayer coextrusion. Distribution runs through pharmaceutical company direct procurement and contract packaging organization intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical companies consolidating packaging partnerships around full-service blow-molding operations with integrated regulatory support. This procurement consolidation displaces fragmented supplier relationships previously managed through multiple tier-2 converters.
For Market Incumbents: Pre-empt qualification timeline compression by embedding serialization hardware directly into blow-molding lines before DSCSA enforcement deadlines tighten. Defend margin position through backward integration into captive resin supply rather than competing on unit price against asset-light leasing models. Threat substitution from barrier-grade PET penetration into oncology segments demands accelerated multilayer coextrusion R&D investment. For New Entrants and Emerging Players: Mexico's nearshoring corridor offers underpenetrated FDA-compliant capacity for US generic manufacturers seeking geographic supply diversification. West Coast pharmaceutical operations face cleanroom capacity scarcity that creates white-space opportunity for qualified blow-molding investment. Go-to-market positioning should emphasize integrated extractables testing and regulatory filing support to match Massachusetts biotech startup procurement requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA serialization mandates and USP standards continuously raise competitive barriers. Target acquisition archetypes include cleanroom-certified specialty operators with established cross-border Health Canada dossiers. Signal to monitor: California and New York extended producer responsibility legislation implementation timelines as recycling cost structure inflection points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Sourcing | Silgan Holdings' integrated supply chain insulates margin from HDPE feedstock volatility tied to natural gas benchmarks. |
| Cleanroom Blow-Molding Capacity Expansion | COMAR LLC's oncology-focused manufacturing addresses Massachusetts biologic R&D cluster demand for barrier-grade multilayer containers. |
| DSCSA Serialization Infrastructure Deployment | Integrated track-and-trace hardware enables AptarGroup to capture pharmaceutical company consolidation toward single-source supply contracts. |
| Cross-Border Regulatory Dossier Development | Health Canada PMRA alignment with FDA timelines creates dual-jurisdiction qualification advantage for Ontario and Quebec suppliers. |
| Post-Consumer Content Verification Systems | California EPR frameworks will reward first-mover packaging suppliers with verified recycling chain documentation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging procurement directors, FDA regulatory affairs leads, contract manufacturing organization executives, and resin sourcing specialists at generic drug manufacturers. Secondary validation drew from FDA DSCSA guidance documents, USP <661.1> and <1661> standards filings, Health Canada PMRA guidance alignment notices, and SEC 10-K disclosures from listed packaging suppliers. Bottom-up volume modeling triangulated against top-down market sizing across material chemistry, closure mechanism, and end-use workflow dimensions.
Calibration against historical capacity utilization rates and resin price elasticity informed CAGR derivation across the analysis window. Segmentation modeling incorporated product type stratification, closure mechanical requirements, pharmaceutical company versus pharmacy procurement patterns, and capacity tier specifications. Forecast inputs included chronic disease medication volume trajectories, generic drug label expansion timelines, and biologic packaging migration patterns from glass to barrier-grade polymer constructions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private equity-backed contract manufacturing consolidators or resin supplier vertical integration into blow-molding would shift outcomes. Regulatory acceleration of extended producer responsibility frameworks or FDA serialization deadline modifications represent primary revision risks. Quarterly review of Massachusetts and New Jersey cleanroom capacity utilization, HDPE resin spread movements, and DSCSA compliance certification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Tablet Bottle Market